
 Gear Reduction Starter Market | 2026-2036
Gear Reduction Starter Market Size, Share, and Industry Trends Forecast 2026-2036
Gear Reduction Starter Market Insights
Mexico's expanding automotive component corridor is reconfiguring regional supply dynamics for gear reduction starter production. Bosch leverages its integrated manufacturing footprint to sustain cost leadership across North American OEM channels. DENSO anchors technical development through its brushless motor programs serving Japanese transplant factories in the region. BorgWarner competes by specializing in high-torque designs tailored to commercial vehicle cold-start requirements.
Gear reduction starters employ planetary gear sets to multiply torque from compact electric motors, typically achieving cranking outputs exceeding diesel engine compression resistance at ratios between 3:1 and 5:1. These systems replace direct-drive starters in applications where space constraints and high displacement demand superior mechanical advantage during engine ignition. Automotive starters dominate unit volume across the product type landscape, though marine starters command premium positioning due to saltwater corrosion resistance requirements and lower production scale. Brushless technology segments are attracting disproportionate engineering investment as OEMs pursue extended service intervals and reduced electromagnetic interference in electronically dense powertrain architectures.
NHTSA safety standards for starter motor engagement reliability intersect with EPA fuel economy regulations that penalize excessive cranking durations, creating dual compliance pressure on component design. The EU F-Gas Regulation and REACH chemical restrictions additionally constrain insulation and lubricant selections for suppliers serving European aftermarket channels. Stakeholders must monitor evolving electrification roadmaps from commercial vehicle manufacturers, as hybridization strategies may redirect starter motor investment toward integrated starter-generator architectures that blur traditional product category boundaries.
Market Dynamics
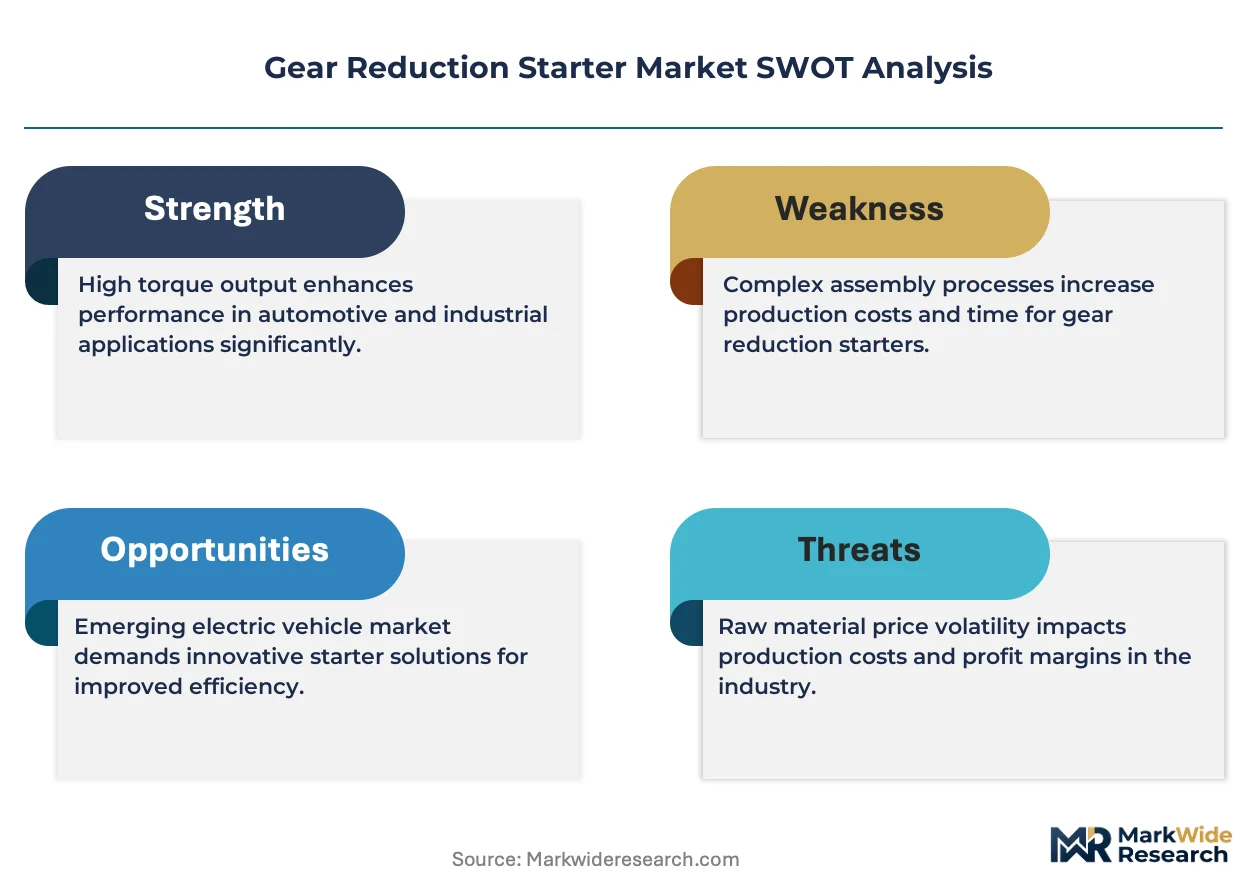
Commercial vehicle electrification timelines and EPA emissions compliance deadlines are compressing product development cycles for gear reduction starter manufacturers, forcing simultaneous investment in brushless architectures and integrated starter-generator platforms.
Growth Catalysts
- EPA Phase 3 Heavy-Duty Emissions Standards:Mandated reductions in idling emissions are accelerating OEM demand for rapid cold-start cranking systems that minimize engine warm-up duration.
- Brushless Motor Architecture:Elimination of brush wear extends service intervals beyond 300,000 miles, aligning with fleet total cost of ownership targets for long-haul trucking operations.
- Mexico Powertrain Manufacturing Corridor:Proximity to major assembly plants in Querétaro and Aguascalientes is concentrating component sourcing decisions within North American supply networks.
Market Restraints
- Neodymium Magnet Supply Concentration:Rare earth processing dominance by Chinese state-controlled entities creates input cost volatility for high-torque permanent magnet designs.
- Integrated Starter-Generator Substitution:Belt-driven and crankshaft-mounted hybrid architectures are absorbing traditional starter motor functions in medium-duty electrification programs.
- EU F-Gas Insulation Restrictions:REACH-compliant alternatives to fluorinated polymer wire coatings impose thermal performance trade-offs in compact motor windings.
Strategic Opportunities
- Marine Commercial Vessels:Saltwater corrosion-resistant starter systems for auxiliary diesel generators represent an underpenetrated premium segment with limited competition.
- 48-Volt Mild Hybrid Convergence:Integration of gear reduction starters with belt alternator starter systems creates new product categories at the boundary of traditional component definitions.
- India BIS Certification Acceleration:Streamlined homologation timelines for commercial vehicle components are opening aftermarket replacement channels for export-oriented suppliers.
Industry Challenges
- Electromagnetic Compatibility Engineering:Dense powertrain electronics require starter motor redesigns that suppress conducted and radiated interference without compromising torque density.
- Dual-Platform Capital Allocation:Simultaneous investment in conventional brushless starters and integrated starter-generator architectures strains R&D budgets across tier-one suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gear Reduction Starter Market |
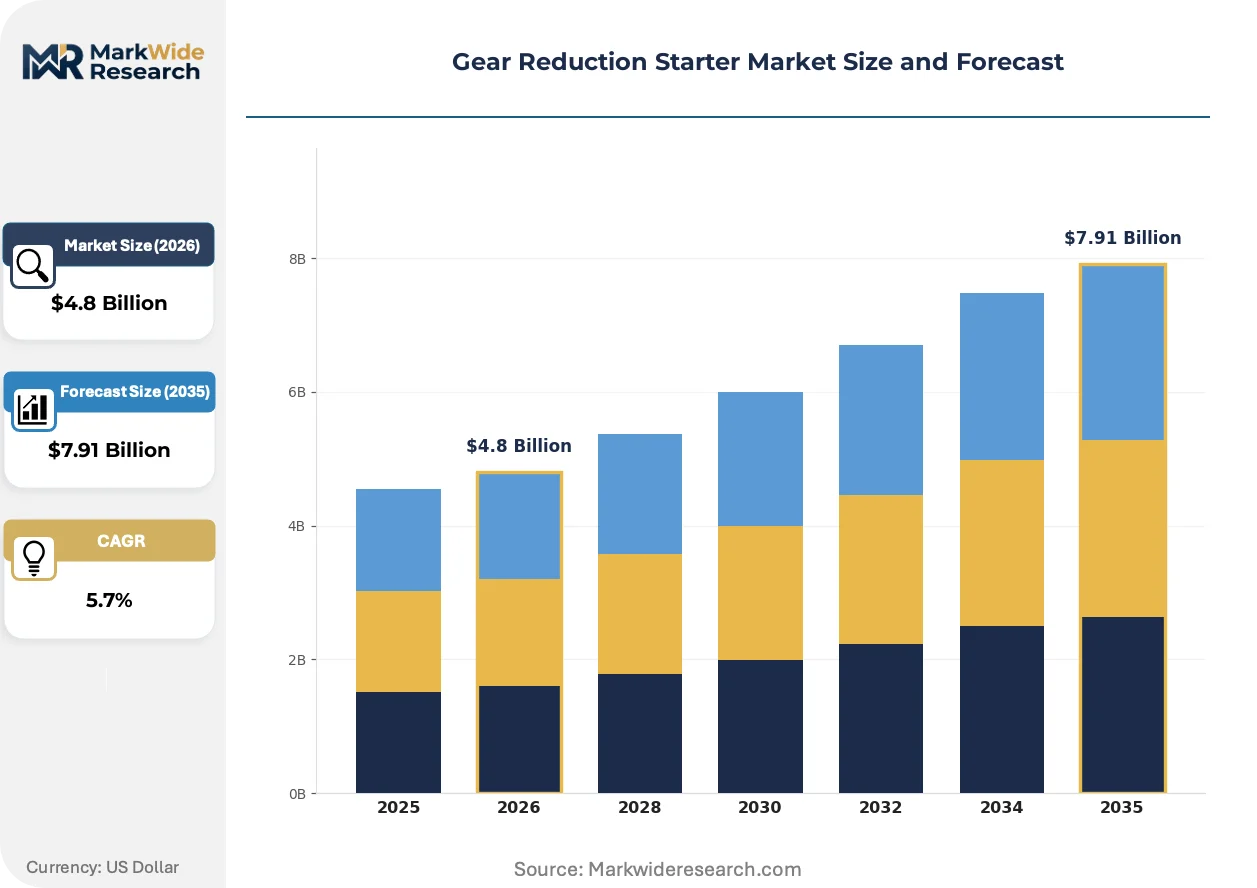
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Starters, Industrial Starters, Marine Starters, Motorcycle Starters Application: Heavy Machinery, Transportation, Power Generation, Recreational Vehicles Technology: Brushless, DC Motors, AC Motors, Solenoid End User: OEMs, Aftermarket Suppliers, Dealerships, Equipment Manufacturers |
| Companies Covered | Bosch, DENSO, BorgWarner, Mitsubishi Electric, Hitachi Automotive Systems, Valeo, Prestolite Electric, Delco Remy, Mitsuba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gear Reduction Starter Market Trends and Innovations
Product architecture decisions in the gear reduction starter market are increasingly dictated by electrification roadmaps that blur boundaries between cranking systems and hybrid assist functions.
Permanent magnet synchronous motor technology with concentrated windings is rendering obsolete conventional wound-field designs in heavy-duty applications. Fleet operators specifying 15-liter diesel engines for line-haul trucking are mandating brushless configurations to eliminate brush dust contamination of electronic control modules. The shift is compressing aftermarket demand for legacy starter rebuild kits.
EPA fuel economy regulations penalizing excessive cranking durations are forcing starter motor torque specification increases without corresponding package size growth. OEMs serving North American commercial vehicle markets are integrating gear reduction ratios above 4.5:1 to achieve sub-one-second start events. Thermal management requirements for repeated start-stop cycling are driving laminated steel rotor adoption.
Aftermarket procurement through consolidated fleet maintenance platforms is displacing traditional jobber distribution for commercial vehicle starters. Large trucking operators with centralized purchasing functions are negotiating direct supply agreements with component manufacturers, bypassing regional warehouse distributors. The pattern is most pronounced in US for-hire trucking segments with standardized equipment specifications.
Gear Reduction Starter Market Segmentation
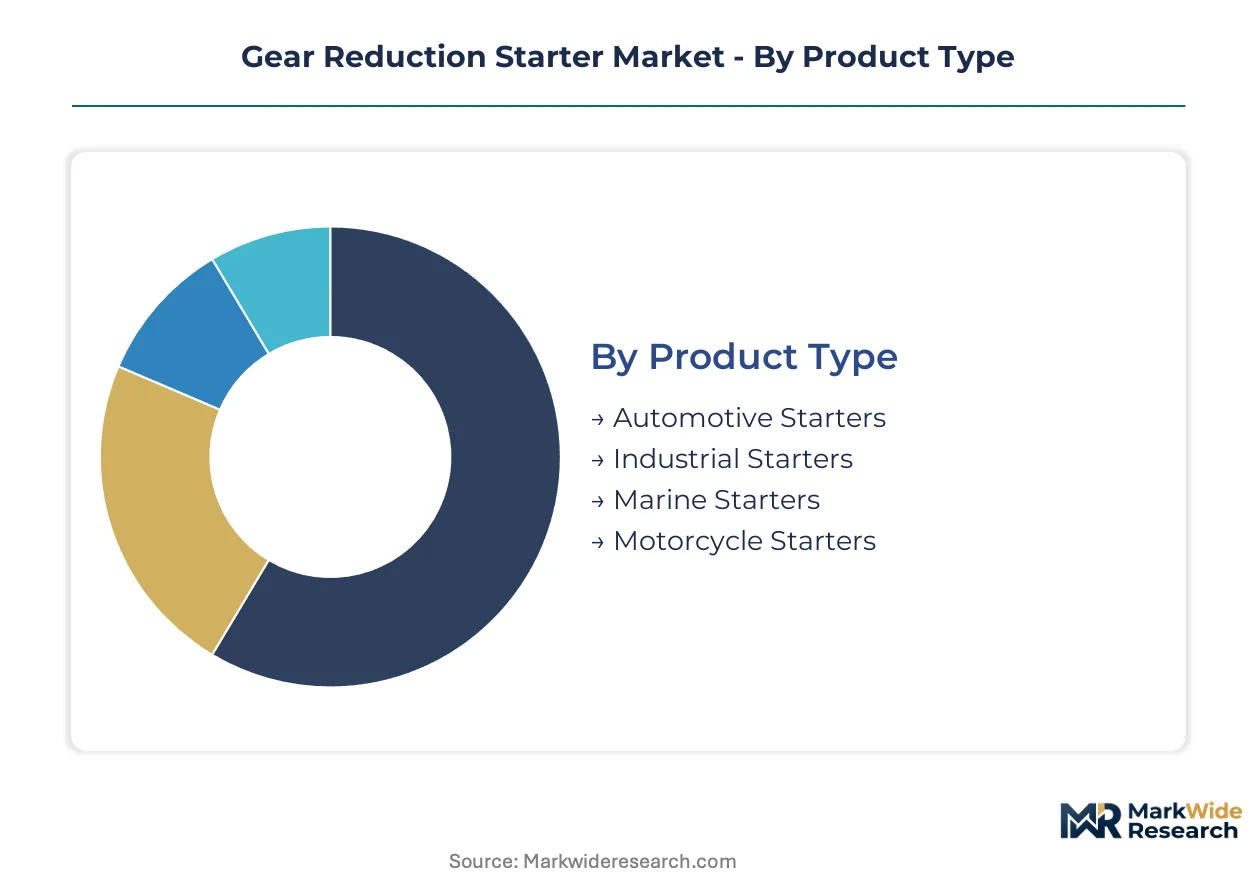
Gear reduction starter procurement cycles vary dramatically across segments, with commercial vehicle fleets replacing units on predictive maintenance schedules while marine operators stretch service intervals across decade-long vessel lifecycles. Understanding these velocity differentials helps suppliers align inventory positioning and technical support resources against actual consumption patterns.
Product Type:
Automotive starters turn inventory fastest due to fleet standardization and high-mileage replacement schedules, while marine starters sit in distribution channels for extended periods awaiting specialized installation windows.
- Automotive Starters:Planetary gear configurations achieving 3:1 to 5:1 reduction ratios dominate passenger car and commercial truck applications. Demand concentrates in Mexico's powertrain corridor serving North American OEM assembly plants, driven by EPA Phase 3 emissions mandates requiring rapid cold-start cranking to minimize idling.
- Marine Starters:Saltwater corrosion-resistant housings with sealed electrical connections protect auxiliary diesel generators on commercial vessels. Salt spray testing to ABYC standards commands premium positioning in shipyards across Louisiana, Florida, and Pacific Northwest fishing fleets.
- Industrial Starters:Heavy-duty wound-field designs persist in mining equipment where brush maintenance access trumps extended service interval targets.
- Motorcycle Starters:Compact permanent magnet units with integrated solenoids serve high-displacement touring bikes and adventure motorcycles.
Automotive starters dominate installed base. Marine starters are where expansion concentrates for suppliers seeking margin protection against commoditization.
Application:
Cost tier stratification separates specification-grade transportation applications from price-sensitive recreational segments, with power generation occupying a technical middle ground.
- Transportation:Line-haul trucking fleets mandate brushless architectures eliminating brush dust contamination of electronic control modules. Large operators with centralized procurement functions negotiate direct supply agreements bypassing traditional warehouse distributors.
- Heavy Machinery:Construction and mining equipment requires high-torque designs with reinforced housings resisting vibration fatigue in extreme duty cycles. Cold-start reliability at sub-zero temperatures drives specification decisions in Canadian oil sands and Alaskan operations.
- Power Generation:Stationary diesel generators for backup and prime power employ gear reduction starters sized for compression-ignition engines up to 30 liters displacement.
- Recreational Vehicles:Cost-optimized direct-drive alternatives compete aggressively in motorhome and towable segments where cranking frequency remains low.
Transportation commands highest specification intensity. Recreational vehicles are climbing the fastest as RV ownership surges in post-pandemic leisure markets.
Technology:
Volume concentration favors mature DC motor architectures while engineering investment migrates toward brushless platforms and emerging AC alternatives.
- Brushless:Permanent magnet synchronous motors with concentrated windings eliminate brush wear and extend service intervals beyond 300,000 miles. Fleet total cost of ownership calculations in long-haul trucking accelerate displacement of wound-field designs.
- DC Motors:Conventional brushed architectures persist in aftermarket replacement channels and cost-constrained developing markets where rebuild economics favor serviceable components.
- AC Motors:Induction motor variants gain traction in integrated starter-generator applications at 48-volt mild hybrid voltage levels.
- Solenoid:Electromechanical engagement mechanisms remain standard across all motor types, with corrosion-resistant plating specifications varying by application severity.
DC motors dominate current production volume. Brushless platforms are where supplier R&D budgets concentrate against electrification timelines.
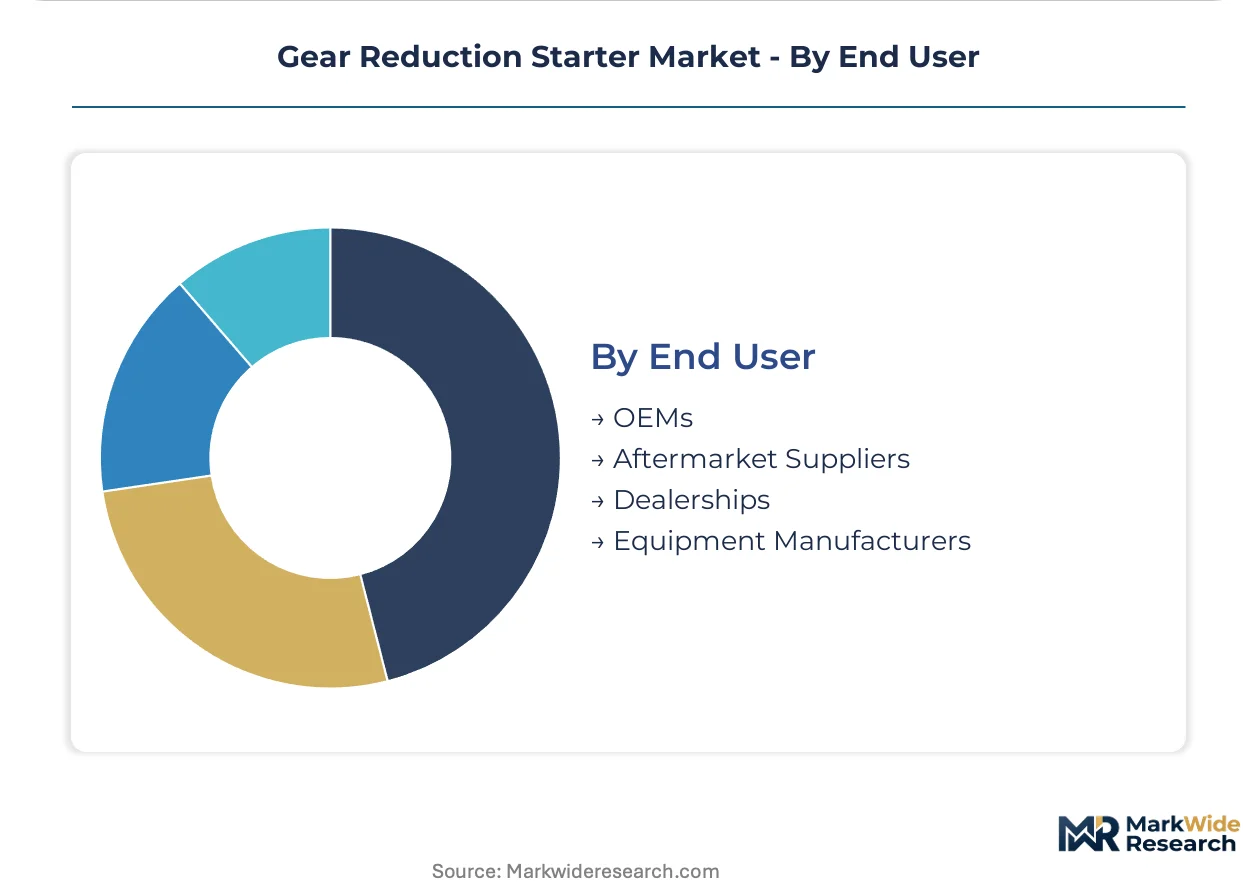
End User:
Customer type determines margin structure and technical support requirements, with OEMs demanding engineering collaboration and aftermarket channels prioritizing availability and price.
- OEMs:Powertrain integration programs require suppliers to synchronize development cycles with engine platform launches, including electromagnetic compatibility validation for dense electronic architectures.
- Aftermarket Suppliers:Consolidated fleet maintenance platforms displace traditional jobber distribution, with large operators standardizing specifications across equipment pools to simplify inventory management.
- Dealerships:Franchise service departments prioritize genuine branded components with warranty alignment over independent alternatives.
- Equipment Manufacturers:Industrial and marine original equipment builders specify starters as subsystems within larger powertrain packages, often delegating sourcing decisions to engine suppliers.
OEMs anchor technical development investment. Aftermarket suppliers are gaining share fastest as fleet consolidation concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 Heavy-Duty Emissions Standards in the United States are compressing product development cycles for gear reduction starter manufacturers, forcing simultaneous investment in brushless architectures and integrated starter-generator platforms across North American supply networks.
United States
Line-haul trucking fleets mandate brushless configurations eliminating brush dust contamination of electronic control modules. NHTSA safety standards for starter motor engagement reliability intersect with EPA fuel economy regulations penalizing excessive cranking durations. Detroit's automotive engineering corridor concentrates powertrain integration programs requiring electromagnetic compatibility validation.
Mexico
Automakers expand powertrain component manufacturing near major assembly plants in Querétaro and Aguascalientes. Proximity to OEM facilities concentrates component sourcing decisions within North American supply networks. The Bajío Region anchors gear reduction starter production serving transplant factories from Japanese and German manufacturers.
Germany
Commercial vehicle electrification timelines compress development cycles for integrated starter-generator architectures. EU F-Gas Regulation and REACH chemical restrictions constrain insulation and lubricant selections for suppliers serving European aftermarket channels. Baden-Württemberg's automotive supplier cluster drives permanent magnet synchronous motor engineering for heavy-duty applications.
China
Rare earth processing dominance by state-controlled entities creates input cost volatility for high-torque permanent magnet designs. MIIT industrial policy prioritizes domestic motor manufacturing capacity for commercial vehicle electrification programs. The Yangtze River Delta concentrates brushless motor production serving both domestic OEMs and export markets.
India
Streamlined BIS certification timelines for commercial vehicle components open aftermarket replacement channels for export-oriented suppliers. Fleet standardization across large trucking operators concentrates procurement authority through centralized purchasing functions. Gujarat's automotive component corridor expands manufacturing capacity for gear reduction starters serving domestic and Middle Eastern markets.
Gear Reduction Starter Market Competitive Landscape
Vertically integrated multinationals and specialized motor fabricators split the market between scale-driven OEM supply contracts and aftermarket service interval optimization. Tier-one suppliers synchronize development cycles with engine platform launches while mid-tier specialists defend margin positions through rebuild kit economics. Two strategic archetypes dominate: integrated powertrain system suppliers and dedicated starter motor manufacturers. Competitive moves concentrate on electromagnetic compatibility engineering partnerships and dual-platform capital allocation between conventional brushless starters and integrated starter-generator architectures.
Within the integrated powertrain tier, Bosch and DENSO exemplify the archetype of suppliers leveraging manufacturing footprint breadth to sustain cost leadership across OEM channels. BorgWarner occupies a position representing specialized high-torque design capability tailored to commercial vehicle cold-start requirements. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning: Bosch represents German engineering integration, DENSO exemplifies Japanese transplant supply relationships, and BorgWarner demonstrates North American commercial vehicle specialization.
| Leading Market Players |
|---|
| Bosch |
| DENSO |
| BorgWarner |
| Mitsubishi Electric |
| Hitachi Automotive Systems |
| Valeo |
| Prestolite Electric |
| Delco Remy |
| Mitsuba Corporation |
| Others |
Pricing and Supply Chain Analysis
Neodymium magnet supply concentration within Chinese state-controlled processing entities creates input cost volatility that compresses margin spreads between premium brushless architectures and standard wound-field alternatives while simultaneously forcing tier-one suppliers toward captive magnet sourcing or alternative motor topologies.
Pricing Analysis
Mexico-manufactured units command price premiums over Asian-sourced equivalents due to proximity savings on North American OEM logistics. Three-tier pricing structure across premium brushless, standard permanent magnet, and economy wound-field levels stratifies procurement decisions. Cost compression in economy tiers intensifies because fleet operators with centralized purchasing negotiate volume discounts bypassing traditional distribution. Aftermarket rebuild channels exhibit highest price sensitivity; OEM direct contracts show lowest.
Supply Chain Analysis
Neodymium oxide feedstock draws from Chinese rare earth separation facilities, with secondary refining capacity concentrated in Japan and limited Western operations. Laminated electrical steel originates from South Korean and German rolling mills; copper magnet wire production centers on Chinese and Mexican fabricators. Single-source vulnerability in rare earth oxide supply creates exposure to export quota fluctuations. Distribution runs through consolidated fleet maintenance platforms displacing regional warehouse distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across electrification roadmaps creates niche opportunities as commercial vehicle OEMs diverge between mild hybrid starter-generator integration and extended-service-interval brushless cranking systems.
For Market Incumbents: Pre-empt integrated starter-generator substitution by accelerating 48-volt platform development partnerships with commercial vehicle powertrain divisions. Secure captive neodymium supply through offtake agreements with Australian or North American rare earth developers. Dual-platform R&D allocation strains capital efficiency; prioritize electromagnetic compatibility engineering to defend OEM specification positions against emerging brushless specialists. For New Entrants and Emerging Players: India's aftermarket replacement channels offer underpenetrated expansion potential as BIS certification streamlines import pathways for export-oriented suppliers. Marine commercial vessel auxiliary generators represent premium white-space with limited incumbent focus and saltwater corrosion resistance requirements that justify technical specialization. Target direct supply relationships with large fleet operators consolidating procurement authority away from traditional jobber networks. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors suppliers with dual-platform capability across conventional brushless starters and integrated starter-generator architectures. Long-term viability hinges on electromagnetic compatibility engineering depth and rare earth supply chain positioning rather than manufacturing scale alone. Monitor commercial vehicle electrification roadmap announcements from major OEMs as the critical inflection signal for platform investment allocation. Cross-checking against vehicle registration data and production schedule disclosures is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor Platform Expansion | EPA Phase 3 compliance requirements accelerate fleet specification shifts toward extended-service-interval architectures. |
| Rare Earth Supply Security Partnership | Captive magnet sourcing insulates production costs against Chinese export quota volatility. |
| 48-Volt Integrated Starter-Generator Development | Mild hybrid electrification roadmaps blur traditional product category boundaries for tier-one suppliers. |
| Electromagnetic Compatibility Engineering Investment | Dense powertrain electronics demand redesigned suppression architectures without torque density compromise. |
| Direct Fleet Supply Agreement Negotiation | Centralized procurement authority among large trucking operators displaces traditional warehouse distribution channels. |
Research Methodology
A standing panel of OEM powertrain procurement directors, Tier 1 supplier engineering leads, fleet maintenance platform operators, and aftermarket distributor category managers provided ongoing calibration against actual order flow and specification shifts. Primary fieldwork combined structured interviews with secondary validation against EPA regulatory filings, NHTSA safety standard documentation, vehicle production databases, and customs trade records. Bottom-up unit demand modeling triangulated against top-down OEM platform production schedules.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product type, application severity, motor technology architecture, and end-user procurement channel. CAGRs derived from regression analysis of historical replacement cycles against electrification adoption curves. Industry-specific forecast inputs included commercial vehicle fleet standardization trends and rare earth oxide price volatility indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed motor manufacturers or accelerated integrated starter-generator adoption by North American commercial vehicle OEMs would shift outcomes beyond modeled ranges. Cross-checking against vehicle registration databases and OEM electrification roadmap disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
North America Precision Gearbox Market
Powertrain
Gas Engine Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Gear Oil Market
Powertrain
Automotive Oil Sump Market
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
Global Automotive Tappet Market
Powertrain
Automotive Conversion Kit Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Dual Clutch Transmission (DCT) Market
Powertrain
Global Automotive Dyno Market
Powertrain
Brazil Automotive Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Canada Automotive Engine Oils Market