
 Global Hydrogen Combustion Engine Market | 2026-2036
Global Hydrogen Combustion Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrogen Combustion Engine Market Outlook
The performance gap between premium hydrogen-direct injection systems and commodity dual-fuel retrofits is broadening. Toyota leverages its decades of hydrogen combustion R&D to sustain technology leadership in passenger and light-commercial segments. Cummins anchors the North American heavy-duty sector with dedicated hydrogen engine platforms for long-haul trucking. Weichai Power dominates China's domestic bus and truck markets through state-backed manufacturing scale and captive fuel-cell supply chain partnerships.
A hydrogen combustion engine ignites hydrogen fuel within a reciprocating piston architecture, typically operating at compression ratios between 12:1 and 15:1 to manage pre-ignition and NOx formation while delivering thermal efficiencies comparable to advanced diesel cycles. Its primary purpose is to decarbonize hard-to-electrify transport and industrial applications where battery weight or refueling infrastructure constraints exclude full electrification. Transportation applications lead current deployment, with marine and power generation segments representing the fastest-growing demand pools as port authorities and grid operators seek dispatchable zero-carbon assets. The OEM end-user channel captures the dominant margin pool through integrated powertrain sales, while aftermarket providers compete on retrofit kits for existing diesel engine blocks.
The EU's F-Gas Regulation and CE marking requirements under the MDR framework shape product standards and market access for hydrogen combustion systems sold in Europe, while the EPA and NHTSA in the United States set parallel emissions and safety compliance thresholds. Japan's METI drives domestic demand through hydrogen society roadmaps that subsidize commercial vehicle fleet conversions. Stakeholders must monitor how divergent national hydrogen purity standards and refueling protocols determine cross-border equipment compatibility and certification costs.
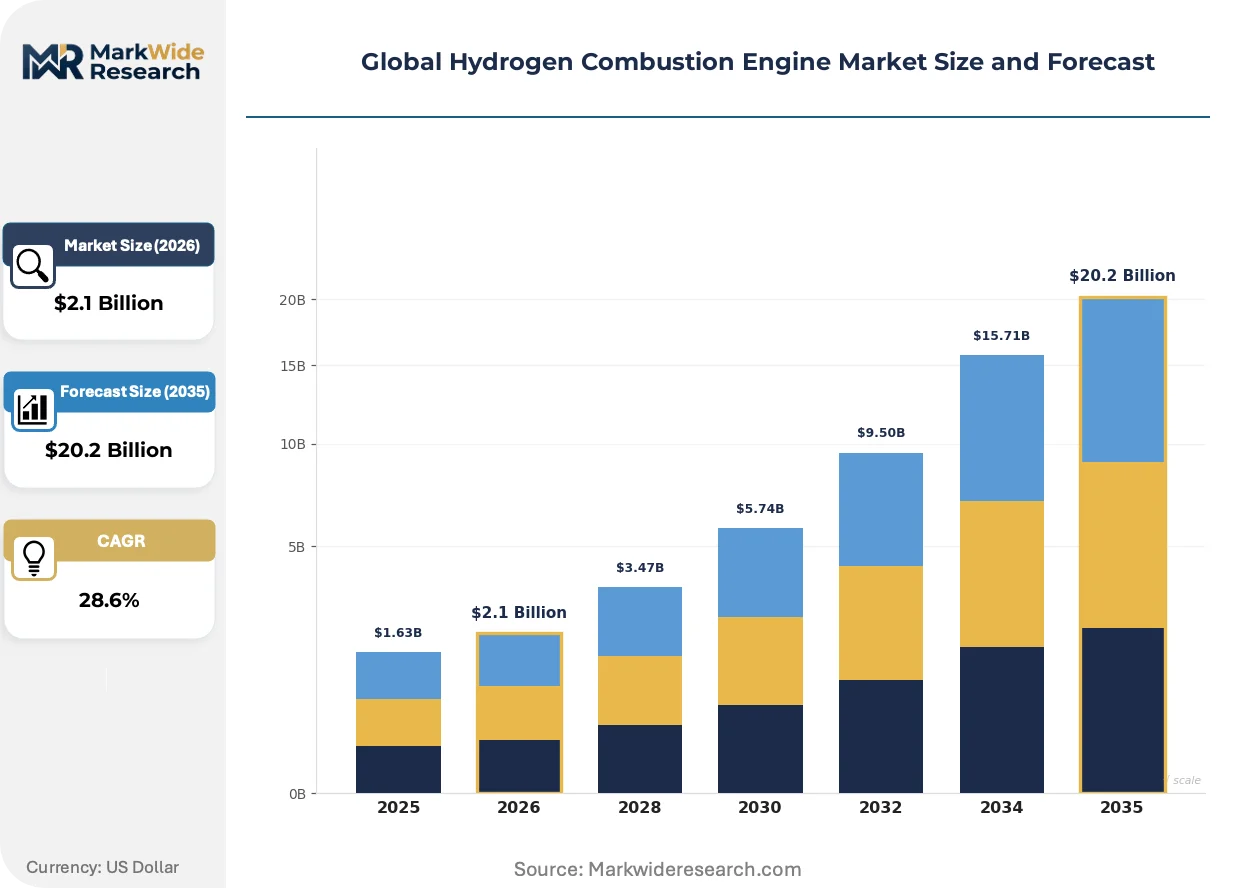
Market Dynamics
The EU's F-Gas Regulation and tightening CO2 standards for commercial vehicles are forcing OEMs to redirect engineering budgets toward hydrogen combustion platforms, compressing development timelines for legacy diesel architectures.
Growth Catalysts
- EU Green Deal mandates:The bloc's commercial vehicle CO2 standards now require 45% emissions reductions by 2030, compelling fleet operators to pilot hydrogen combustion alternatives in Germany's Ruhr industrial corridor.
- Port decarbonization programs:Maritime authorities in Rotterdam, Singapore, and Long Beach are specifying hydrogen combustion for harbor craft and auxiliary power units, creating anchor demand for marine-engine variants.
- Industrial cluster hydrogen hubs:Germany, Japan, and California have operationalized hydrogen refueling corridors that overlap with heavy manufacturing zones, reducing infrastructure risk for early fleet adopters.
Market Restraints
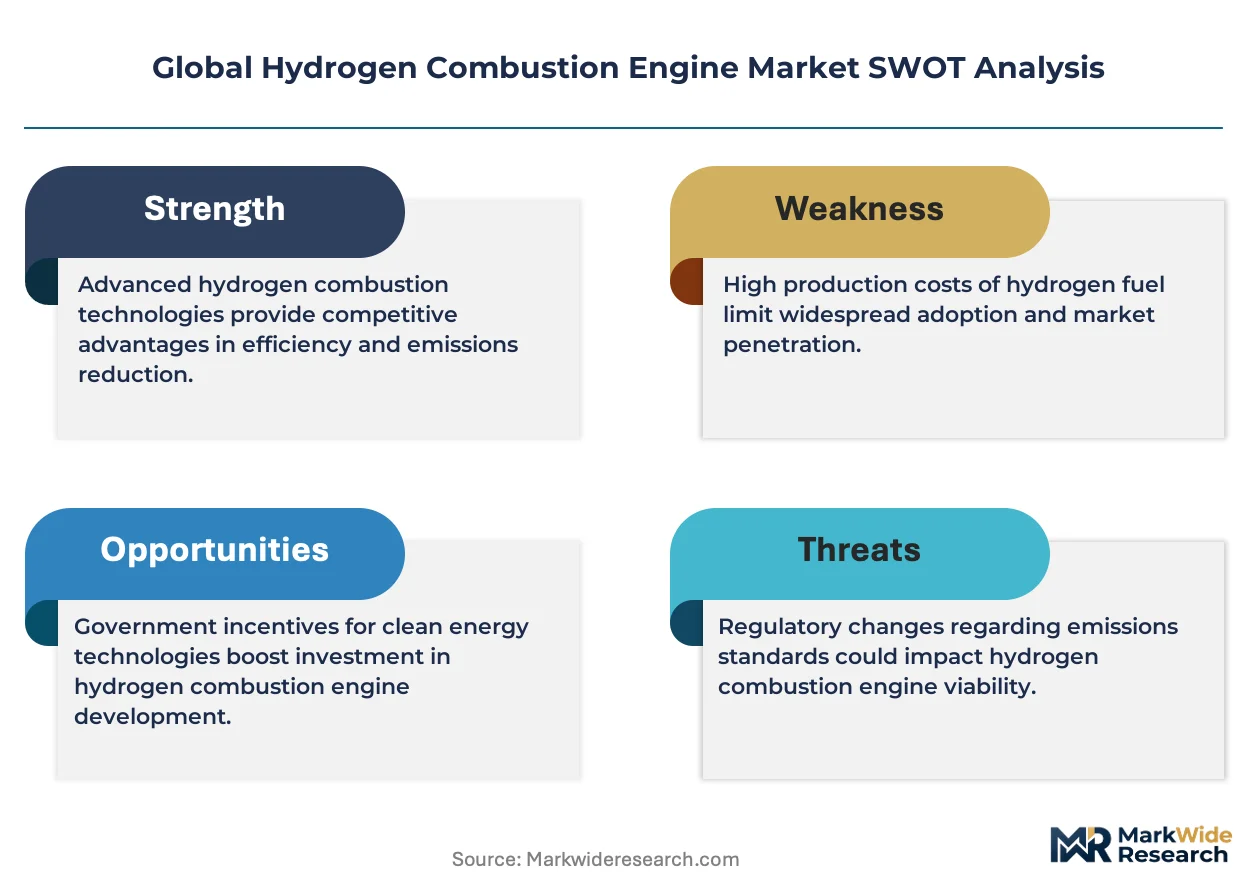
- Platinum-group metal cost volatility:Catalytic aftertreatment systems for NOx control rely on palladium and rhodium, with price swings above 40% annually compressing margin predictability for engine manufacturers.
- Supply concentration in high-pressure injection components:Precision hydrogen direct-injection hardware concentrates among German and Japanese component suppliers, creating single-source vulnerability for non-integrated OEMs.
- Technical limitation in cold-start emissions:Hydrogen combustion exhibits elevated NOx formation during sub-zero starts, requiring thermal management add-ons that add cost and complexity in Nordic markets.
Strategic Opportunities
- Brazil's bio-hydrogen corridor:The country's sugarcane ethanol infrastructure is being repurposed for green hydrogen production, creating a low-cost feedstock opportunity for South American engine deployments.
- Power generation retrofit market:Grid operators in Texas and Australia are seeking dispatchable zero-carbon assets, opening a replacement cycle for diesel backup generators with hydrogen combustion units.
- Japan's METI hydrogen society roadmap:Subsidies for commercial fleet conversions now cover 30% of powertrain costs, accelerating payback periods for urban delivery operators.
Industry Challenges
- Combustion engineer talent scarcity:The shift from diesel to hydrogen flame-speed management requires expertise in high-turbulence injection modeling, a skill pool concentrated among retiring specialists at legacy OEMs.
- Multi-jurisdiction certification timelines:Engine families must secure separate EPA, NHTSA, and KBA approvals for US and German markets, stretching homologation cycles to 18-24 months.
- Integration complexity with telematics platforms:Fleet management systems require recalibration for hydrogen fuel consumption algorithms, demanding software engineering resources most suppliers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrogen Combustion Engine Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $20.2 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Dual-Fuel, Homogeneous Charge, Hydrogen-Direct Injection, Pilot Injection Application: Transportation, Power Generation, Industrial, Marine End User: OEMs, Aftermarket Providers, Utilities, Fleet Operators Fuel Type: Compressed Hydrogen, Liquid Hydrogen, Hydrogen Blends, Biohydrogen |
| Companies Covered | JCB, Toyota, Cummins, Tata Motors, Volvo, Weichai Power, Bosch, Ballard Power Systems, MAN Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrogen Combustion Engine Market Strategic Shifts
Engine architecture is fragmenting into two competing design philosophies: premium direct-injection systems optimized for thermal efficiency versus cost-engineered port-injection retrofits targeting price-sensitive fleet segments.
High-pressure hydrogen direct-injection technology is decentralizing powertrain sourcing decisions. Marine operators in Norway and port authorities in California are adopting this architecture for harbor tugboats and shore-power units. The technology is decentralizing procurement authority from centralized fleet managers to individual vessel captains and terminal operators who specify engine configurations.
The EU's F-Gas Regulation is accelerating refrigerant-phaseout timelines that cascade into auxiliary system redesigns. Hydrogen combustion engines must now integrate with CO2-based cabin cooling systems, adding thermal integration complexity. Heavy-duty truck OEMs in Germany and France are responding by consolidating HVAC and powertrain engineering teams under single platform directors.
Fleet procurement is fragmenting across ownership models. Full-service leasing providers in Germany and the Netherlands are unbundling powertrain maintenance from vehicle financing, creating standalone hydrogen combustion service contracts. This shift is most visible in California's drayage trucking segment, where owner-operators now subscribe to engine-overhaul programs rather than capitalizing powertrain replacements.
Global Hydrogen Combustion Engine Market Segmentation
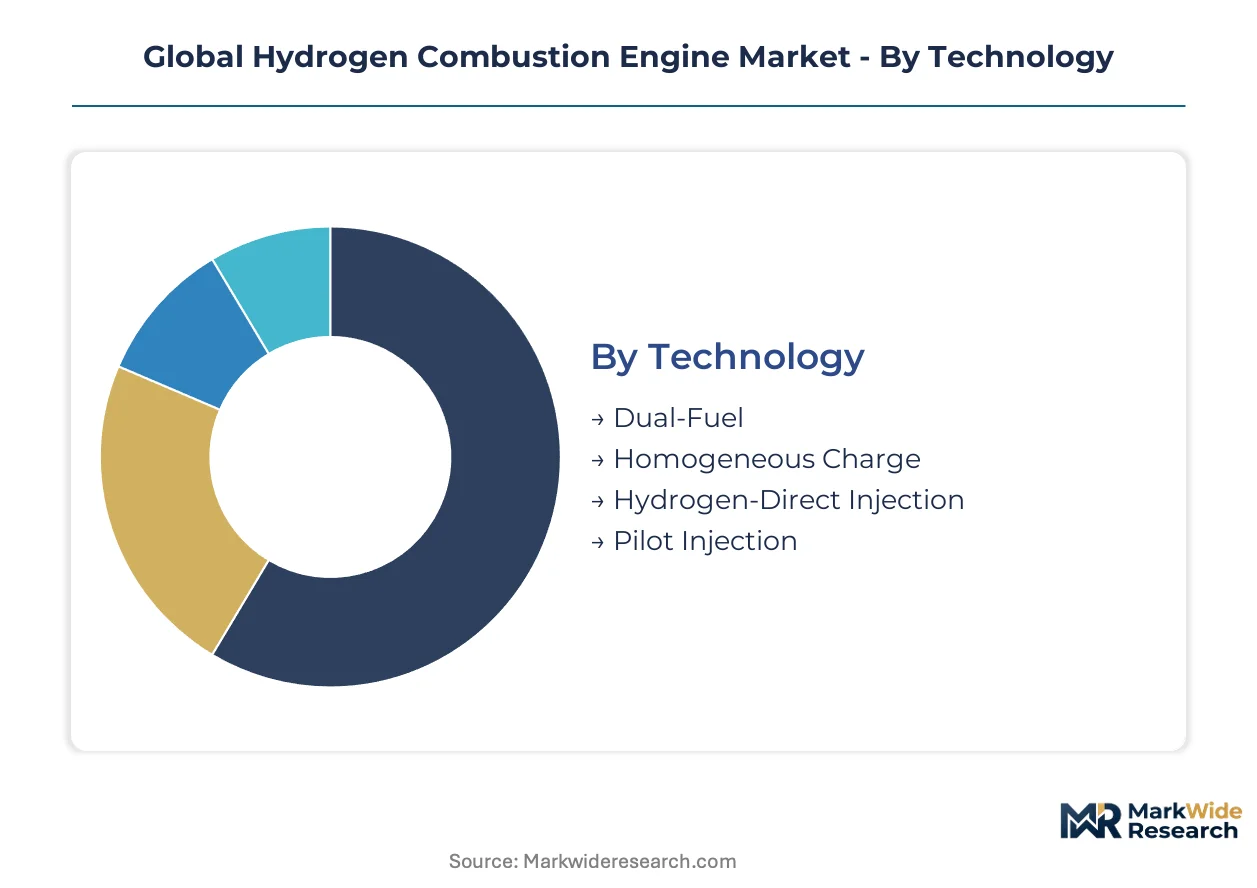
Technology pathways diverge sharply between premium direct-injection architectures and cost-engineered port-injection retrofits. Application demand concentrates in transport and marine segments where battery electrification faces weight or refueling constraints. End-user procurement patterns split between integrated OEM powertrains and aftermarket retrofit kits for existing diesel blocks.
Technology:
Customization intensity spans from standardized dual-fuel conversions to precision-engineered direct-injection systems requiring dedicated cylinder head designs.
- Hydrogen-Direct Injection:High-pressure injectors deliver hydrogen directly into compressed air at 350-700 bar, enabling diesel-comparable thermal efficiency through controlled combustion phasing. Demand concentrates in Germany's heavy-duty trucking corridor where fleet operators prioritize fuel economy over capital cost.
- Dual-Fuel:Retrofit systems inject hydrogen into the intake manifold while retaining diesel pilot ignition, preserving engine block compatibility. Operators in California's drayage segment favor this approach for rapid diesel displacement without vehicle replacement cycles.
- Homogeneous Charge:Premixed hydrogen-air mixtures burn at lower peak temperatures, reducing NOx formation but sacrificing power density. Port authorities in Rotterdam specify this architecture for harbor craft with strict emissions limits.
- Pilot Injection:Micro-diesel sprays ignite lean hydrogen mixtures, bridging combustion stability gaps in cold-start conditions. Japanese bus fleets under METI subsidy programs deploy this variant for urban duty cycles.
Most installed capacity flows through Dual-Fuel retrofits. Expansion is steepest in Hydrogen-Direct Injection.
Application:
Volume distribution tracks the physical constraints of electrification — weight-critical long-haul and refueling-infrastructure-limited maritime lead deployment.
- Transportation:Heavy-duty trucks, buses, and delivery vehicles dominate current order books. Germany's Ruhr industrial corridor hosts the densest concentration of pilot fleets, with hydrogen hub infrastructure overlapping manufacturing zones.
- Marine:Harbor tugs, auxiliary power units, and short-sea shipping represent the steepest demand trajectory. Norwegian operators and California port authorities are specifying hydrogen combustion for vessels operating within emissions control areas.
- Power Generation:Grid operators in Texas and Australia seek dispatchable zero-carbon backup assets, opening replacement cycles for diesel generators. Stationary applications tolerate lower power density in exchange for fuel flexibility.
- Industrial:Forklifts, mining equipment, and stationary machinery in captive fleet settings. Demand clusters where on-site hydrogen production from process off-gas eliminates distribution costs.
Transportation absorbs the dominant share of production capacity. Marine applications are climbing the fastest.
End User:
Margin capture splits between integrated OEM channels capturing powertrain value and aftermarket providers competing on retrofit speed and fleet downtime minimization.
- OEMs:Integrated powertrain manufacturers design dedicated hydrogen architectures from crankcase to aftertreatment. German and Japanese OEMs control the premium segment through captive injection component supply.
- Fleet Operators:Full-service leasing providers in the Netherlands unbundle powertrain maintenance from vehicle financing, creating standalone hydrogen combustion service contracts. California owner-operators subscribe to engine-overhaul programs rather than capitalizing replacements.
- Aftermarket Providers:Conversion kit suppliers target existing diesel engine blocks with port-injection retrofits. Technical limitation in cold-start emissions and NOx aftertreatment integration constrains addressable market scope.
- Utilities:Grid operators procure stationary hydrogen generators for backup power and grid stabilization services. Procurement emphasizes fuel flexibility and dispatchability over transportation-grade power density.
OEM channels capture the dominant margin pool. Aftermarket Providers are gaining share fastest in price-sensitive fleet segments.
Fuel Type:
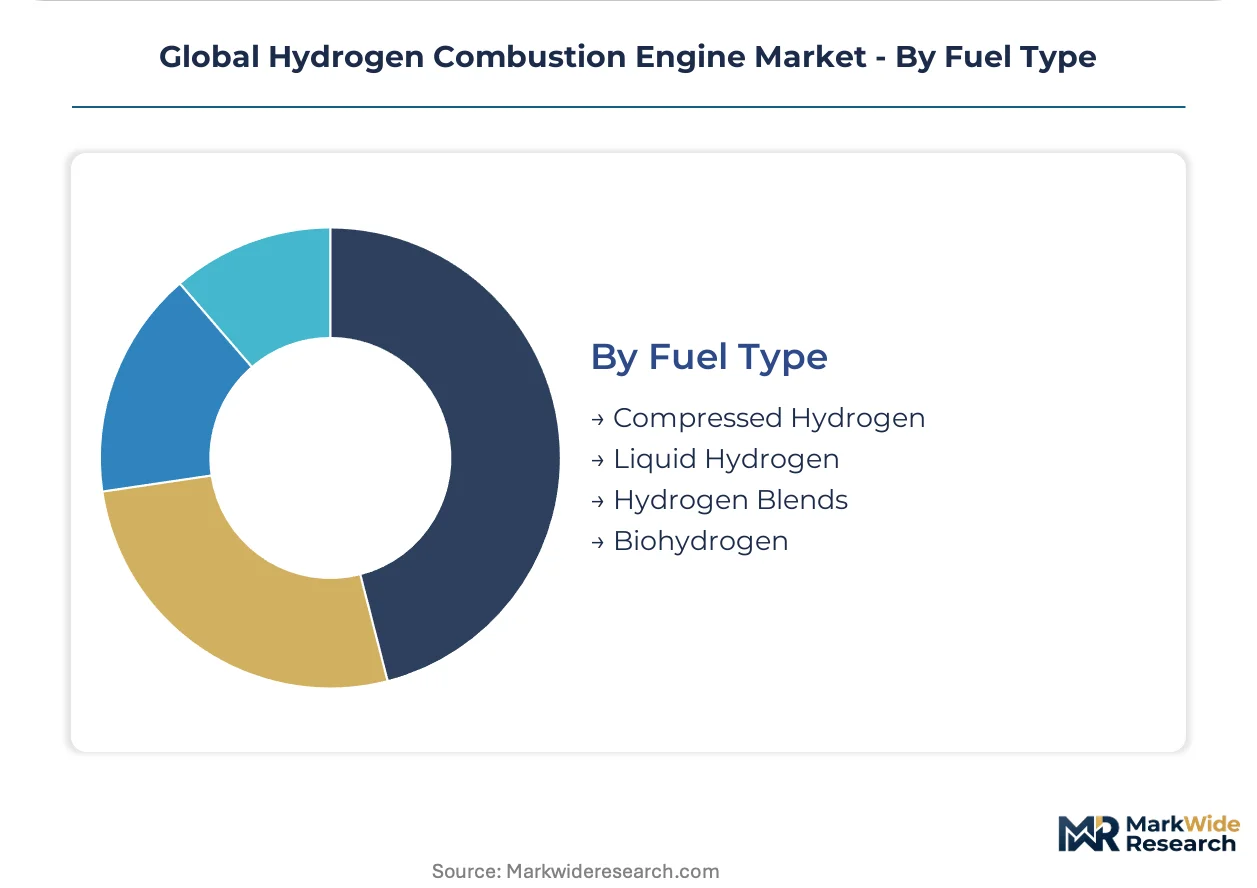
Supply infrastructure maturity determines adoption sequencing — compressed gas leverages existing industrial hydrogen networks while liquid and bio-hydrogen variants await distribution scale.
- Compressed Hydrogen:350-700 bar gaseous storage serves transportation applications with established refueling protocols. Germany's hydrogen hub infrastructure and California's corridor networks anchor demand.
- Liquid Hydrogen:Cryogenic storage at -253°C enables energy density critical for maritime and long-haul segments. Japanese METI roadmaps prioritize liquefaction capacity expansion for commercial fleet conversions.
- Biohydrogen:Production from biomass and waste streams qualifies for renewable fuel credits in EU and North American markets. Brazil's sugarcane ethanol infrastructure repurposing creates a low-cost feedstock corridor for South American deployments.
- Hydrogen Blends:Mixtures with natural gas or synthetic fuels bridge infrastructure gaps during transition periods. Industrial cluster users with captive blending capability pilot this approach for emission reduction without full hydrogen commitment.
Compressed Hydrogen dominates current installed base. Liquid Hydrogen shows the steepest expansion trajectory in marine and heavy-haul segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor generates denser hydrogen combustion pilot activity than California's port networks, though both regions anchor infrastructure buildout with distinct regulatory instruments.
United States
California's drayage trucking segment drives early fleet adoption through CARB mandates requiring zero-emission port equipment by 2035. EPA and NHTSA parallel standards stretch homologation timelines for engine families entering interstate commerce. The Long Beach-Los Angeles port complex hosts the densest concentration of hydrogen harbor craft pilots.
Germany
The Ruhr industrial corridor overlaps hydrogen hub infrastructure with automotive engineering clusters, concentrating heavy-duty trucking pilots. The EU's F-Gas Regulation and KBA certification requirements compress development timelines for legacy diesel architectures. Bavaria's manufacturing zones anchor OEM powertrain engineering centers.
Japan
METI's hydrogen society roadmap subsidizes commercial fleet conversions covering powertrain costs for urban delivery operators. JIS standards and port decarbonization programs in Yokohama and Kobe specify hydrogen combustion for harbor craft. The Kanto region around Tokyo hosts liquefaction capacity expansion for commercial deployments.
China
State-backed manufacturing scale and captive supply chain partnerships dominate domestic bus and truck markets. MIIT dual carbon goals and GB standards shape product certification timelines. Shandong Province's industrial base concentrates Weichai Power's manufacturing footprint for hydrogen powertrains.
Brazil
Sugarcane ethanol infrastructure repurposing creates a low-cost feedstock corridor for green hydrogen production. The country's national environmental regulator and renewable fuel credit frameworks support bio-hydrogen qualification. São Paulo state's industrial corridor pilots engine deployments leveraging existing distribution networks.
Global Hydrogen Combustion Engine Market Competitive Environment
Top-tier vendors anchor integrated powertrain manufacturing, while conversion kit suppliers and component specialists populate lower tiers. The vendor base stratifies across three strategic archetypes: captive OEM engineering divisions controlling premium injection hardware, independent engine builders targeting retrofit markets, and fuel system component suppliers licensing technology across multiple platforms. Competitive moves concentrate on strategic partnerships for hydrogen infrastructure alignment and portfolio diversification into marine and stationary applications.
Within the integrated OEM tier, Toyota and Cummins exemplify divergent geographic anchoring strategies, with the former representing Japanese passenger and light-commercial specialization while the latter occupies North American heavy-duty positioning. Weichai Power sits within the state-backed manufacturing scale archetype. JCB anchors construction equipment applications. These named entities illustrate how competitive positioning fragments across application segments rather than consolidating around unified platform strategies.
| Leading Market Players |
|---|
| JCB |
| Toyota |
| Cummins |
| Tata Motors |
| Volvo |
| Weichai Power |
| Bosch |
| Ballard Power Systems |
| MAN Energy Solutions |
| Others |
Value Chain & Pricing Dynamics
Fleet operator consolidation around hydrogen-direct injection specifications in Germany's Ruhr corridor is forcing component suppliers to qualify precision hardware at scale, compressing margin structures for port-injection retrofit providers unable to meet thermal efficiency benchmarks. This procurement shift toward premium architectures concentrates pricing power among integrated OEMs with captive injection component supply.
Pricing Analysis
Capacity additions in China's Shandong Province are reshaping price floors for dual-fuel conversion kits, intensifying cost competition in the aftermarket tier. Three-tier pricing structure across premium direct-injection, standard dual-fuel, and economy port-injection levels separates OEM-integrated powertrains from retrofit alternatives. Cost compression in the economy tier stems from Chinese manufacturing scale and state-backed supply chain partnerships. Fleet operators in California's drayage segment exhibit highest price sensitivity, while German heavy-duty trucking fleets prioritize fuel economy over capital cost.
Supply Chain Analysis
Precision hydrogen direct-injection hardware rests on German and Japanese specialty component producers, creating single-source vulnerability for non-integrated engine builders. High-pressure injectors, specialized cylinder heads, and platinum-group metal catalysts draw from concentrated supplier bases in Bavaria and Nagoya. Tariff exposure on precision-machined components represents the dominant structural risk. Distribution runs through captive OEM channels for integrated powertrains and independent aftermarket networks for retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Fleet procurement is consolidating around hydrogen-direct injection specifications that demand proven thermal efficiency and KBA certification.
For Market Incumbents: Hedge against platinum-group metal cost volatility through long-term offtake agreements with South African and Russian suppliers. Backward integration into high-pressure injection component manufacturing in Germany or Japan defends margin position against emerging Chinese suppliers. Battery-electric range anxiety in Nordic cold-climate markets preserves hydrogen combustion relevance as a substitute threat. For New Entrants and Emerging Players: Begin with Brazil's bio-hydrogen corridor, where sugarcane ethanol infrastructure repurposing creates a low-cost feedstock advantage absent in European or North American markets. Power generation retrofit demand in Texas and Australia offers the most penetrable white-space target, as grid operators seek dispatchable zero-carbon assets without transportation-grade certification requirements. Partner with established EPC contractors for stationary generator deployments rather than pursuing OEM powertrain integration. For Investors and Strategic Acquirers: Asymmetric upside sits with independent engine builders possessing marine certification and port authority relationships. Long-term viability hinges on hydrogen hub infrastructure maturation across the analysis window, with marine and stationary applications outpacing transportation growth. Watch METI subsidy renewal trajectories and EU F-Gas Regulation enforcement intensity as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Injection Components | Captive supply of 350-700 bar hardware secures margin control against German and Japanese component concentration. |
| Marine Certification Investment | Harbor craft approvals in Rotterdam, Singapore, and Long Beach open the fastest-growing demand pool outside trucking. |
| Bio-Hydrogen Supply Agreement | Brazilian sugarcane ethanol infrastructure repurposing creates cost-advantaged feedstock for South American deployments. |
| Power Generation Retrofit Partnership | Texas and Australian grid operators seek dispatchable zero-carbon assets with lower certification burden than transportation. |
| Platinum-Group Metal Hedging Program | Palladium and rhodium price swings above 40% annually compress margin predictability for NOx aftertreatment systems. |
Study Parameters
Multiple input streams — OEM platform engineering directors, fleet procurement managers at German and California operators, component supplier technical leads, and marine classification society surveyors — were reconciled against secondary validation. Primary interviews with powertrain development executives, aftermarket conversion specialists, and port authority environmental compliance officers informed demand-side assumptions. Secondary sources included EPA certification filings, KBA type-approval databases, METI hydrogen roadmap disclosures, and EU F-Gas Regulation implementation guidance. Bottom-up unit economics and top-down infrastructure deployment scenarios were triangulated to anchor volume estimates.
Data-stream reconciliation across technology pathway adoption curves, regional hydrogen hub buildout timelines, and end-user procurement preference shifts shaped the analytical framework. Segmentation dimensions modeled include injection architecture, application vertical, end-user channel, and fuel storage format across the projection horizon. CAGRs were derived from infrastructure deployment pacing and fleet replacement cycle analysis. Industry-specific forecast inputs incorporated platinum-group metal price trajectory assumptions and regulatory compliance cost evolution under diverging national hydrogen purity standards.
Several conditions sit outside the modeled scope, including breakthrough battery energy density improvements that could displace hydrogen combustion in heavy-duty segments, and geopolitical disruptions to Russian or South African platinum-group metal supply. Forecasts reflect assumptions about hydrogen hub infrastructure buildout pacing and subsidy program continuity. A small set of named triggers — METI roadmap revisions, EU F-Gas Regulation enforcement intensity, and EPA heavy-duty emissions rulemakings — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Brazil Automotive Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Automotive Half Shaft Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Automotive Crankshaft Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Crankshaft Oil Market
Powertrain
Global Automotive Clutch Market