
 Motorcycle Fairings Market | 2026-2036
Motorcycle Fairings Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Fairings Market Analytics
The split between premium carbon fiber fairings and commodity-grade ABS plastic alternatives is realigning procurement patterns across the value chain. Monster Fairings leverages its aftermarket channel control to dominate the replacement segment for sportbike owners. Puig anchors its position through deep specialization in wind tunnel-tested designs for European racing applications. Acerbis competes by sustaining manufacturing scale across thermoformed polypropylene lines for dual-sport and off-road OEM contracts.
Motorcycle fairings are aerodynamic body panels, typically molded from ABS plastic, fiberglass, carbon fiber, or polypropylene composites, designed to reduce drag and protect engine components and riders from wind, debris, and weather exposure. Manufacturing processes include injection molding for ABS variants, vacuum bagging for fiberglass layups, and autoclave curing for pre-preg carbon fiber sheets, with wall thicknesses generally ranging from 2.5mm to 4.5mm depending on material and impact resistance requirements. Full fairings command the largest share of OEM fitment due to their integration with fuel tanks and tail sections on sport-touring platforms, while café racer fairings represent the fastest-growing niche as retro-styled builds attract custom builder investment. Carbon fiber segments concentrate margin pools at the premium tier, whereas polypropylene lines serve volume-driven street motorcycle replacement cycles where cost sensitivity shapes supplier selection.
EPA emissions standards and NHTSA safety regulations in the United States shape fairing design by influencing motorcycle weight targets and crashworthiness testing protocols that manufacturers must satisfy for street-legal certification. ECE R22 helmet and protective equipment standards in Europe extend to fairing-integrated windscreen geometries, while Japan's METI oversees material recycling mandates that affect thermoplastic selection in Pacific Rim supply chains. Stakeholders must monitor how tightening aerodynamic efficiency requirements from transport regulators in multiple jurisdictions will reshape R&D allocation between drag coefficient optimization and sustainable material substitution.
Market Dynamics
The motorcycle fairings market is rebalancing around carbon fiber material standards and aerodynamic testing protocols emerging from Germany's KBA certification requirements, which are compressing development timelines for suppliers serving premium sportbike platforms.
Growth Catalysts
- Carbon Fiber Pre-Preg Adoption:Autoclave-cured carbon fiber sheets are displacing wet layup fiberglass in World Superbike homologation specials, cutting kerb weight by 15-20% for track-day riders.
- EPA Emissions Standards:NHTSA safety regulations in the United States are forcing OEMs to optimize fairing geometries for reduced aerodynamic drag, directly lowering fuel consumption test cycle results.
- Italy's Racing Heritage:The concentration of MotoGP and World Superbike engineering consultancies around Bologna and Modena is accelerating wind tunnel-to-production pipelines for premium OEM supply contracts.
Market Restraints
- Epoxy Resin Cost Volatility:Aerospace-grade pre-preg carbon fiber remains tethered to petrochemical feedstock fluctuations, compressing margin pools for mid-tier aftermarket suppliers.
- Chinese ABS Pellet Concentration:Injection-molding grade ABS for commodity fairings sources 60-70% of virgin resin from Zhejiang and Guangdong petrochemical complexes, exposing volume manufacturers to single-geography supply risk.
- Impact Resistance Trade-offs:Carbon fiber's brittle failure mode under low-speed tip-overs limits its penetration in daily-use street motorcycles where repair cost sensitivity dominates purchasing decisions.
Strategic Opportunities
- India's Premium Motorcycle Surge:The country's 300cc+ displacement segment is expanding at double-digit rates, creating first-mover advantage for fairing suppliers establishing local thermoforming partnerships.
- ECE R22 Windscreen Integration:European helmet visibility standards are mandating larger, optically certified windscreen surfaces, opening design service contracts for aerodynamic engineering boutiques.
- Additive Manufacturing Convergence:Fused filament fabrication of ABS and carbon-reinforced nylon is integrating with traditional injection molding for low-volume custom fairing production, collapsing minimum order quantities for café racer builders.
Industry Challenges
- Autoclave Capacity Scarcity:Certified aerospace-grade curing facilities are concentrated among a handful of European and Japanese contract manufacturers, extending lead times for carbon fiber fairing prototypes beyond 16 weeks.
- Multi-Material Bonding Certification:OEMs require validated adhesive protocols for carbon fiber-to-ABS hybrid constructions, forcing suppliers to maintain parallel R&D streams for dissimilar material joining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Fairings Market |
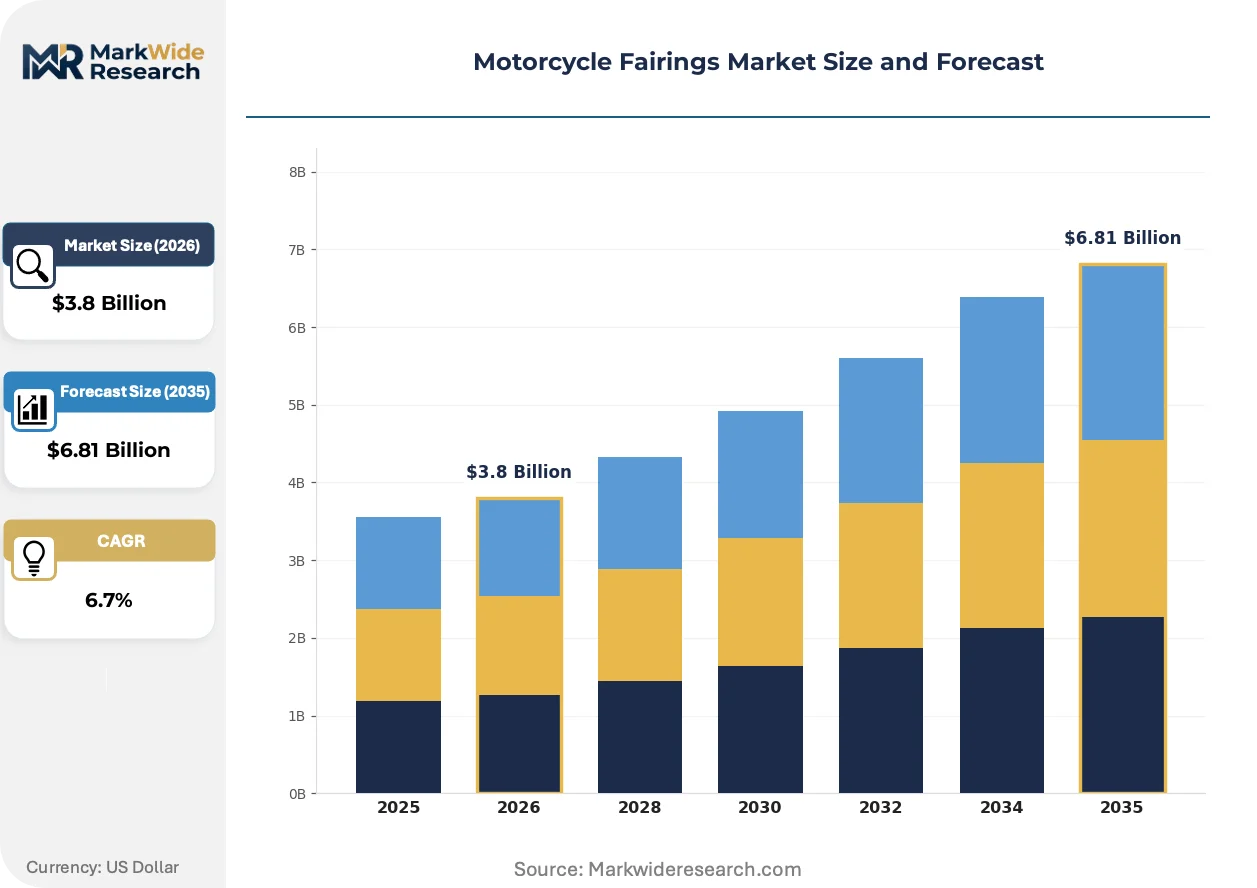
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Fairings, Half Fairings, Quarter Fairings, Café Racer Fairings Material: ABS Plastic, Fiberglass, Carbon Fiber, Polypropylene Application: Street Motorcycles, Racing Bikes, Touring Bikes, Off-Road Bikes End User: OEMs, Aftermarket Providers, Individual Riders, Custom Builders |
| Companies Covered | Monster Fairings, ABS Fairings, Motoforza, AirTech, Sebimoto, Kingsmotorcyclefairings, Summitfairings, Acerbis, Puig, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Fairings Market Evolving Landscape
Computational fluid dynamics and sustainable material substitution are compressing traditional fairing development cycles while opening new procurement channels between racing heritage suppliers and custom motorcycle builders.
Pre-impregnated carbon fiber autoclave curing is integrating with robotic trimming systems to produce repeatable, race-spec fairing geometries at previously unattainable production scales. Track-day enthusiasts and amateur racing teams are adopting these once-prototype-only constructions through direct-to-consumer channels. The technology is integrating quality control standards from aerospace supply chains into motorcycle aftermarket pricing tiers.
REACH substance restrictions in Europe are phasing out specific epoxy hardeners and solvent-based gel coats used in traditional fiberglass fairing production. Manufacturers serving EU type-approval markets are reformulating resin systems to maintain impact resistance while eliminating SVHC-classified chemicals. German KBA documentation requirements for material safety data sheets are extending compliance burdens to aftermarket importers previously exempt from OEM-level scrutiny.
Builder-direct procurement through Instagram-visualized and forum-validated suppliers is displacing traditional distributor networks for custom and replacement fairing segments. Café racer and scrambler enthusiasts are sourcing directly from Vietnamese and Indonesian fiberglass workshops, bypassing established US and European aftermarket distributors. This channel compression is most visible in Australia's import-heavy custom scene, where tariff thresholds favor small-package direct shipping over consolidated container imports.
Motorcycle Fairings Market Segmentation
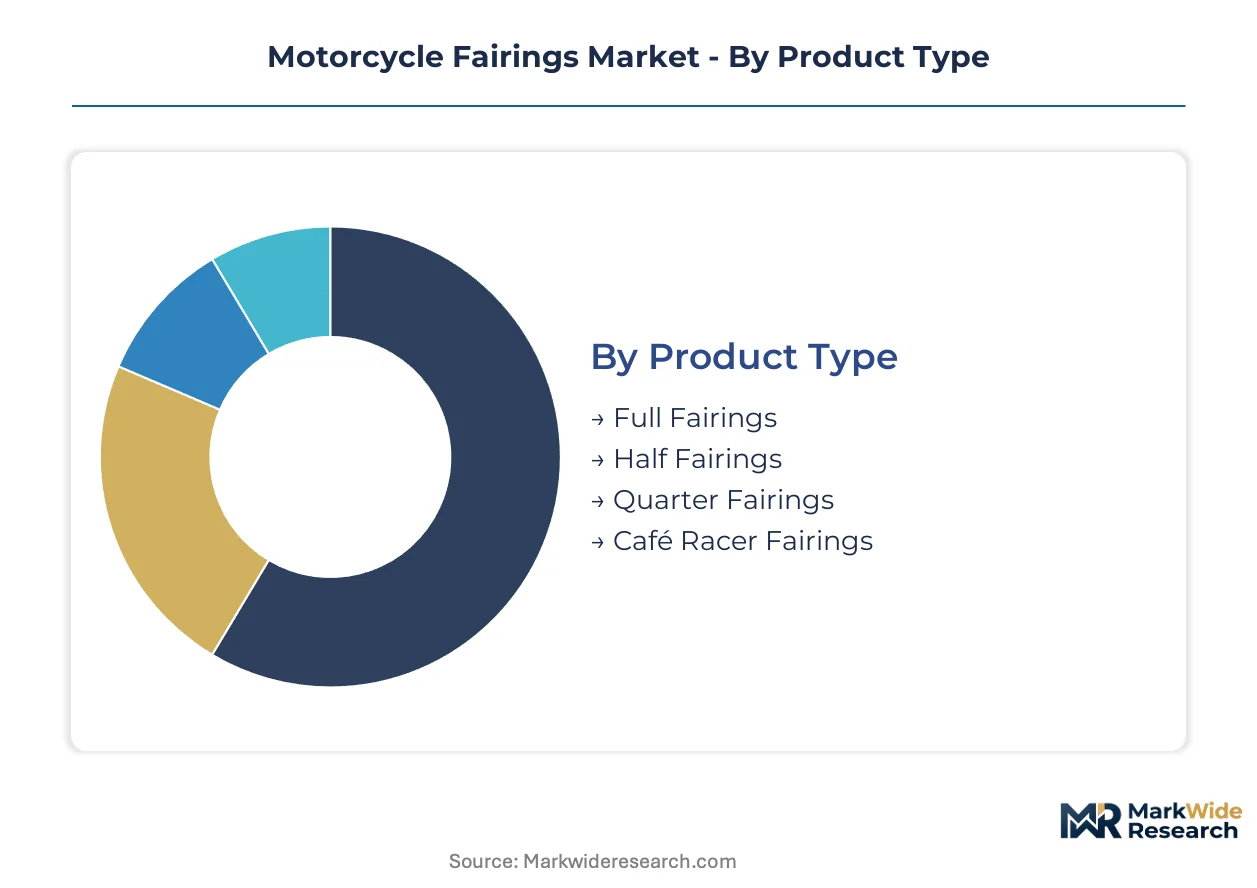
Fairing procurement patterns diverge sharply across material grades and installation contexts. Suppliers must calibrate production assets to serve both high-volume OEM contracts and fragmented custom builder demand.
Product Type:
Supply concentration tilts toward full fairing platforms where tooling amortization justifies dedicated injection molding lines.
- Full Fairings:These integrate fuel tanks, tail sections, and windscreen assemblies into unified aerodynamic envelopes. OEMs in Italy and Japan specify full fairings for sport-touring motorcycles where wind protection and fuel efficiency testing converge. Demand concentrates among 600cc+ displacement platforms where regulatory drag coefficient targets apply.
- Half Fairings:Partial coverage designs shield handlebars and instrument clusters while exposing engines for cooling. German KBA certification protocols treat half fairings as distinct type-approval categories, requiring separate crash testing documentation. Street motorcycle OEMs favor these for naked bike variants where styling flexibility outweighs drag reduction priorities.
- Quarter Fairings:Minimal wind deflectors mount to headlight brackets on retro-styled platforms.
- Café Racer Fairings:Compact bullet-shaped designs attach to vintage frame geometries; Indonesian fiberglass workshops dominate direct-to-builder supply.
Today's leader: Full Fairings. Tomorrow's challenger: Café Racer Fairings.
Material:
Cost tier stratification separates aerospace-grade autoclave curing from commodity thermoforming operations.
- Carbon Fiber:Pre-preg autoclave curing produces 2.5mm wall thicknesses with 15-20% weight reduction over fiberglass. World Superbike homologation specials in Italy and Spain specify these constructions. Supply bottlenecks persist at certified curing facilities in Germany and Japan where lead times exceed sixteen weeks.
- ABS Plastic:Injection-molded acrylonitrile butadiene styrene serves 60-70% of replacement fairing volume through vacuum-formed or injection-molded variants. Zhejiang and Guangdong petrochemical complexes supply virgin resin pellets, exposing volume manufacturers to single-geography concentration risk. Street motorcycle OEMs specify ABS for cost-sensitive 125cc-300cc platforms.
- Fiberglass:Wet layup or vacuum-bagged chopped strand mat constructions dominate custom builder channels.
- Polypropylene:Thermoformed olefin composites withstand off-road impact cycles; Acerbis sustains manufacturing scale for dual-sport OEM contracts.
Carbon Fiber commands margin concentration. ABS Plastic captures volume dominance.
Application:
Volume distribution tracks motorcycle registration patterns across displacement segments and riding disciplines.
- Street Motorcycles:Daily-use platforms from 125cc to 1000cc displacement generate replacement cycle demand every 3-5 years. India's 300cc+ segment expansion is accelerating thermoforming partnership opportunities for fairing suppliers establishing local production.
- Racing Bikes:Track-only and homologation-special platforms require FIM-compliant impact absorption and aerodynamic stability at 300+ kph. Bologna and Modena engineering consultancies compress wind tunnel-to-production timelines for World Superbike and MotoGP derivative supply.
- Touring Bikes:Long-distance platforms prioritize weather protection and luggage integration over drag coefficient optimization.
- Off-Road Bikes:Enduro and motocross applications demand flexible polypropylene constructions that deform without cracking.
Street Motorcycles anchor replacement revenue. Racing Bikes drive technology transfer.
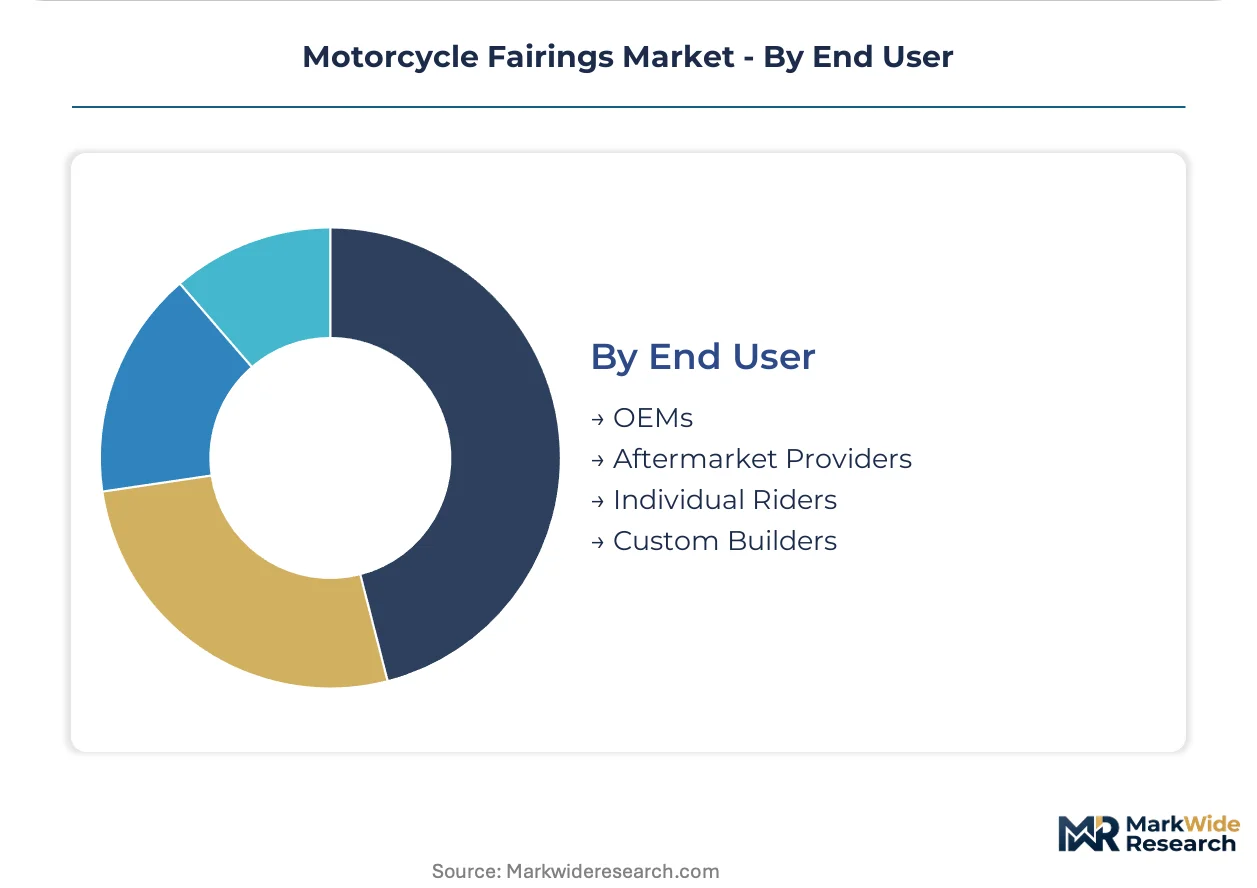
End User:
Customer type determines order quantity economics and design validation requirements.
- OEMs:Original equipment manufacturers in Italy, Japan, and Germany specify fairings during motorcycle development programs, requiring ECE type-approval documentation and material safety data sheet compliance. Contract volumes justify dedicated tooling investments and multi-year supply agreements.
- Aftermarket Providers:Distributors like Monster Fairings and Puig control channel access to sportbike owners seeking crash replacement or styling upgrades. These intermediaries aggregate demand across multiple motorcycle brands, requiring suppliers to maintain broad fitment databases.
- Individual Riders:Direct purchasers through web platforms seek color-matched or custom-painted alternatives to OEM offerings.
- Custom Builders:Café racer and scrambler specialists source small-batch fiberglass through Instagram-visualized Vietnamese workshops, bypassing traditional distributor markups.
OEMs lock in production capacity. Custom Builders are gaining procurement leverage through direct channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian composite engineers and German aerodynamicists anchor the industry's technical workforce concentration, with Bologna-Modena and Stuttgart-Munich clusters supplying specialized talent to premium OEM programs.
Germany
KBA certification protocols demand validated wind tunnel data for street-legal fairing geometries, compressing supplier development timelines. The country's REACH enforcement through ECHA restricts specific epoxy hardeners in fiberglass production. Stuttgart engineering consultancies serve as the primary validation gateway for carbon fiber autoclave curing standards adopted across European premium sportbike platforms.
Italy
MotoGP and World Superbike heritage concentrates engineering talent around Bologna and Modena, accelerating wind tunnel-to-production pipelines. ECE R22 helmet visibility standards extend to fairing-integrated windscreen certification requirements. The Emilia-Romagna manufacturing corridor hosts specialized composite fabrication facilities supplying Ducati and Aprilia homologation programs.
Japan
METI material recycling mandates reshape thermoplastic selection for Pacific Rim supply chains serving domestic OEMs. JIS standards govern impact resistance testing for replacement fairing imports. The Nagoya-Chubu industrial zone maintains concentrated autoclave capacity for carbon fiber motorsport applications with sixteen-week prototype lead times.
United States
EPA emissions standards and NHTSA safety regulations force OEMs to optimize fairing geometries for reduced aerodynamic drag in fuel consumption test cycles. The Southeast and Midwest host distributor consolidation points for aftermarket ABS replacement volume. California Air Resources Board requirements add state-level compliance layers to federal certification pathways.
India
The 300cc+ displacement segment expands at double-digit rates, creating thermoforming partnership opportunities for suppliers establishing local production. BIS certification requirements for automotive plastics govern material specifications for domestic assembly. Maharashtra and Karnataka host emerging motorcycle OEM final assembly plants driving localized fairing procurement demand.
Motorcycle Fairings Market Competitive Landscape
Top-tier vendors anchor premium carbon fiber autoclave curing, while mid-tier injection molders compete on ABS replacement volume and lead time compression. The vendor base stratifies across three functional tiers: aerospace-certified composite specialists, high-volume thermoforming operators, and direct-to-builder fiberglass workshops. Strategic archetypes include racing heritage engineering boutiques, distributor-controlled aftermarket aggregators, and vertically integrated OEM captive suppliers. Competitive moves concentrate on geographic expansion into India's premium motorcycle surge and additive manufacturing convergence for low-volume custom production.
Within the distributor-controlled aftermarket tier, Monster Fairings and Puig exemplify channel-anchored positioning, while Acerbis occupies a scale-driven position in thermoformed polypropylene supply. These three entities represent distinct competitive archetypes: direct-to-consumer sportbike replacement specialists, wind tunnel-validated European racing application providers, and dual-sport OEM contract manufacturers respectively.
| Leading Market Players |
|---|
| Monster Fairings |
| ABS Fairings |
| Motoforza |
| AirTech |
| Sebimoto |
| Kingsmotorcyclefairings |
| Summitfairings |
| Acerbis |
| Puig |
| Others |
Value Network & Pricing Analysis
Pre-impregnated carbon fiber autoclave curing is displacing wet layup fiberglass across premium sportbike platforms, simultaneously elevating unit economics for certified suppliers and compressing margin pools for mid-tier aftermarket operators unable to access German KBA-validated curing facilities. This production-method transition concentrates pricing power among Bologna-Modena engineering consultancies and Stuttgart-based composite specialists while forcing commodity ABS injection molders to compete on volume throughput and lead time compression.
Pricing Analysis
Paint-and-graphics bundling versus raw fairing supply splits procurement economics across OEM and aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade autoclave-cured carbon fiber from vacuum-bagged fiberglass and injection-molded ABS alternatives. Price differentiation rests on KBA certification status and wind tunnel validation documentation. Cost compression in commodity ABS replacement tiers is intensifying because Chinese resin pellet concentration exposes volume manufacturers to single-geography supply risk. Individual riders sourcing through direct-to-builder channels exhibit highest price sensitivity, while racing teams purchasing homologation specials demonstrate lowest elasticity.
Supply Chain Analysis
India's BIS certification requirements for automotive plastics are reshaping sourcing patterns for suppliers establishing Maharashtra and Karnataka thermoforming partnerships to serve domestic OEM final assembly plants. Geographic supply concentration centers on Germany, Italy, and Japan for carbon fiber autoclave curing, China for ABS virgin resin pellets, and Indonesia for direct-to-builder fiberglass workshops. Raw material dependencies draw from Zhejiang petrochemical complexes, aerospace-grade epoxy resin systems, and chopped strand mat reinforcements. Single-source vulnerability persists at certified curing facilities where capacity scarcity extends prototype lead times. Distribution runs through distributor-controlled aftermarket aggregators like Monster Fairings and Puig for sportbike replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where tightening KBA aerodynamic certification requirements and REACH substance restrictions are accelerating demand for validated engineering consultancies capable of navigating multi-jurisdictional compliance pathways.
For Market Incumbents: Hedge against epoxy resin cost volatility by securing long-term offtake agreements with aerospace-grade pre-preg suppliers or backward integration into captive curing capacity. Defend margin position against Vietnamese and Indonesian direct-to-builder fiberglass workshops by investing in ECE R22 windscreen certification capabilities that create regulatory moats around European aftermarket access. Channel control through Instagram-visualized direct platforms offers additional defensive leverage against distributor disintermediation. For New Entrants and Emerging Players: Custom builder aggregators represent the most penetrable channel partner type for establishing initial market presence without competing against entrenched OEM supply relationships. Target India's 300cc+ displacement surge through local thermoforming partnerships in Maharashtra and Karnataka, bypassing autoclave capacity bottlenecks that constrain carbon fiber entrants. Additive manufacturing convergence for café racer fairing production enables low-volume market entry with collapsed minimum order quantities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier ABS injection molders exposed to Chinese resin concentration risk but possessing established fitment databases and distributor relationships. Long-term viability favors aerospace-certified composite specialists with KBA-validated curing capacity and Bologna-Modena engineering consultancy ties. The signal to watch is BIS certification acceleration in India, which would validate thermoforming partnership investments and signal geographic demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| KBA Aerodynamic Certification Investment | Validates wind tunnel data for street-legal geometries, unlocking European premium OEM supply contracts. |
| India Thermoforming Partnership | Establishes local production footprint to capture BIS-certified demand from Maharashtra and Karnataka assembly plants. |
| REACH-Compliant Resin Reformulation | Eliminates SVHC-classified chemicals to maintain EU type-approval access amid ECHA enforcement tightening. |
| Direct-to-Builder Channel Development | Bypasses traditional distributor markups through Instagram-visualized platforms targeting café racer enthusiasts. |
| Carbon Fiber Autoclave Capacity Expansion | Addresses sixteen-week prototype lead time bottlenecks at certified German and Japanese curing facilities. |
Research Methodology
Bottom-up motorcycle displacement segment modeling reconciled against top-down carbon fiber and ABS supply tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, aftermarket distributor procurement heads, custom builder workshop operators, and KBA certification consultants combined with secondary validation against ECE type-approval databases, METI material recycling filings, and BIS automotive plastics standards. Trade data from Zhejiang and Guangdong petrochemical exports, World Superbike homologation documentation, and Instagram-visualized builder-direct transaction patterns provided additional triangulation points.
Input-output matrices mapping autoclave curing capacity, injection molding throughput, and thermoforming partnership investments against displacement segment registration patterns generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include fairing product type, material grade tier, application context, and end-user procurement channel. CAGRs derived from regression analysis of historical premium motorcycle registration trends correlated with fairing replacement cycle assumptions. Industry-specific forecast inputs incorporated KBA certification timeline compression and India's 300cc+ segment expansion trajectories.
Revisions become necessary when epoxy resin feedstock volatility exceeds historical bands, when KBA or ECHA regulatory timelines accelerate beyond modeled assumptions, or when additive manufacturing adoption rates for custom fairing production outpace traditional injection molding cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Motorbike Riding Gear Market