
 Automotive Camera and Camera Module Market | 2026-2036
Automotive Camera and Camera Module Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Camera and Camera Module Market Intelligence
Glass-to-plastic lens substitution is recalibrating module economics across volume segments. Valeo SA leverages captive optical manufacturing to sustain margin control on front-camera assemblies. Continental AG anchors European supply through its Regensburg sensor integration campus. Robert Bosch GmbH competes on software-layer differentiation, bundling perception algorithms with CMOS module hardware.
Automotive cameras and camera modules are electro-optical assemblies comprising image sensors, lens stacks, and signal-processing chipsets, typically operating across visible and near-infrared spectra from 400 to 1000 nanometers for real-time vehicular environment perception. CMOS sensor technology leads unit economics due to lower power draw and on-chip integration capacity versus legacy CCD architectures. ADAS application demand concentrates the fastest growth trajectory, while parking assistance represents a mature volume pool with compressed margins. OEM end-user channels capture the dominant value share, though tier-1 suppliers retain critical design-in influence over module specification.
NHTSA rear-visibility mandates and Euro NCAP pedestrian-detection protocols shape baseline product requirements across export-relevant supply chains. ECE R46 and ECE R79 type approvals govern mirror-replacement and lane-keeping camera performance in European type certification. Stakeholders must monitor divergence between UN R157 automated lane-keeping system requirements and emerging national exemptions that fragment homologation pathways.
Market Dynamics
Glass-to-plastic lens substitution is compressing module costs and redistributing margin pools across tier-1 suppliers, forcing captive optical manufacturing investments to defend assembly economics.
Growth Catalysts
- Euro NCAP pedestrian-detection protocols:Mandates in European type certification are expanding minimum camera specification for new vehicle platforms entering EU markets.
- CMOS sensor on-chip integration:Lower power draw and signal-processing consolidation are enabling multi-camera architectures without alternator upgrades.
- Germany-Japan-US corridor clustering:Tier-1 supplier ecosystems concentrate around vehicle assembly belts, accelerating design-in cycles for ADAS platforms.
Market Restraints
- Automotive-grade glass supply concentration:High-index optical glass for premium lens stacks sources from limited specialty melt capacity in East Asia.
- ECE R79 homologation complexity:Lane-keeping camera performance thresholds vary across member state interpretations, fragmenting certification pathways.
- Silicon wafer input volatility:Image sensor foundry capacity constraints transmit pricing instability through CMOS module supply chains.
Strategic Opportunities
- UN R157 automated lane-keeping divergence:National exemption variations create openings for regulatory arbitrage in system architecture design.
- Mirror-replacement camera systems:ECE R46 type approval expansion permits elimination of exterior mirrors on commercial vehicle platforms.
- Near-infrared spectrum extension:Fusion of 940nm illumination with visible-band sensors enables night-pedestrian detection without thermal imaging cost structures.
Industry Challenges
- Automotive vision algorithm talent scarcity:Perception software engineering competes with consumer electronics for specialized skill pools.
- ADAS calibration equipment capex:Static and dynamic camera alignment systems require six-figure tooling investments per service bay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Camera and Camera Module Market |
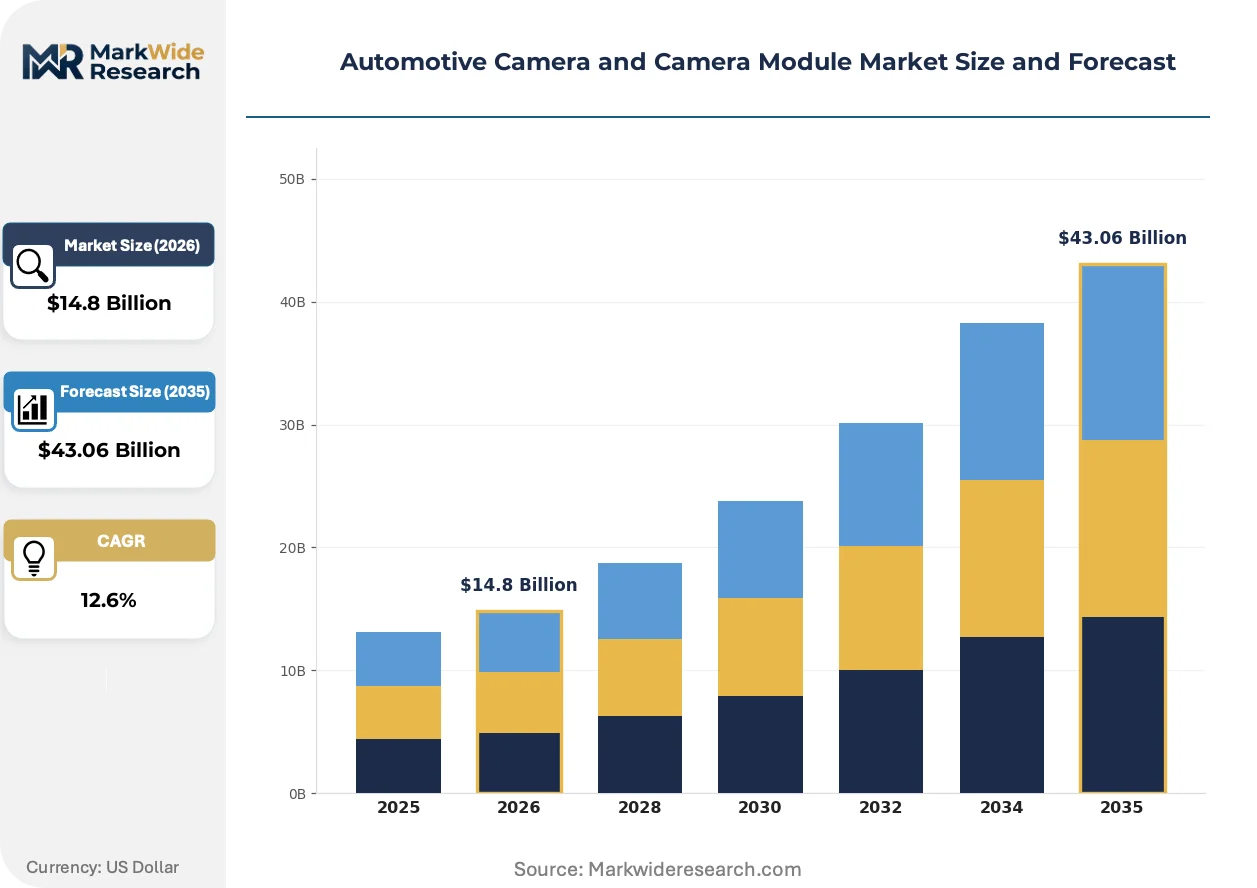
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $43.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Cameras, Rear Cameras, Surround View Cameras, Night Vision Cameras Technology: CCD Sensors, CMOS Sensors, Thermal Imaging, LIDAR Application: ADAS, Parking Assistance, Collision Avoidance, Driver Monitoring End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Manufacturers |
| Companies Covered | Valeo SA, Magna International Inc., Continental AG, Gentex Corporation, Aptiv Plc, Robert Bosch GmbH, Denso Corporation, LG Innotek Co., Ltd., Mobileye, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Camera and Camera Module Market Strategic Shifts & Innovations
Module economics are restructuring around material substitution and software-layer bundling, with perception algorithm integration becoming the primary differentiation axis.
Polymer aspheric lens stacks are absorbing front-camera volume previously captured by ground-glass assemblies. German and Japanese OEMs specify hybrid glass-plastic configurations for L2+ highway assist platforms. Cost compression from this substitution is absorbing margin pressure while preserving optical resolution thresholds.
NHTSA rear-visibility mandates are tightening baseline specification for all light vehicles under 10,000 pounds. The regulation forces backup camera durability upgrades against thermal cycling and vibration exposure. Module suppliers serving US export markets are redesigning housing seals and flex-cable routing to meet the amended FMVSS 111 interpretation.
Fleet operators are consolidating camera module procurement through direct tier-1 contracts rather than OEM captive supply. Commercial vehicle upfitters in North American corridors now specify camera hardware separately from chassis purchase. This disintermediation is compressing aftermarket channel margins while expanding addressable supply base for qualified module vendors.
Automotive Camera and Camera Module Market Segmentation
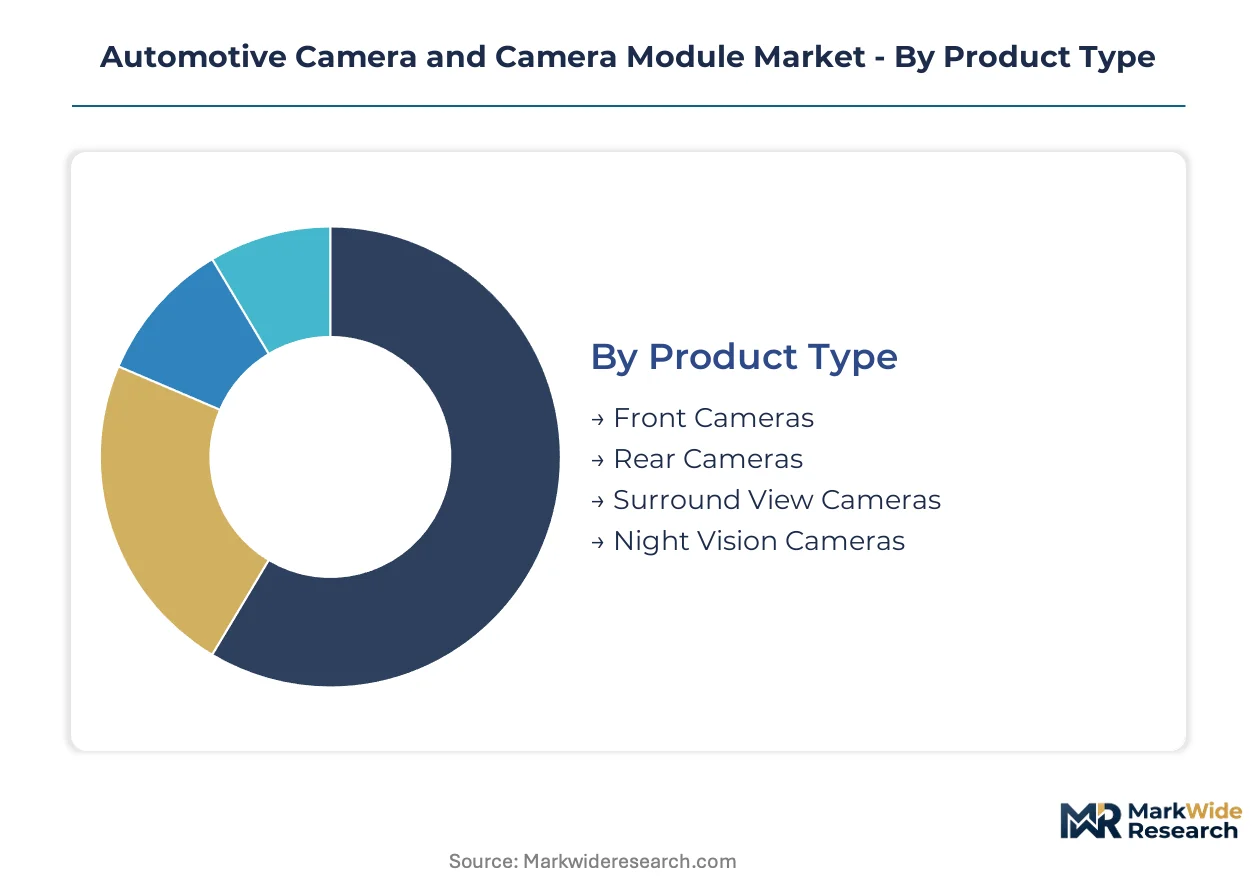
Automotive camera segmentation reflects divergent capital requirements across optical precision tiers and software integration depth. Module suppliers allocate tooling budgets differently across sensor technologies and application specifications, creating distinct margin architectures within each category.
Product Type:
Front camera assemblies demand the heaviest upfront investment due to multi-element lens grinding, active alignment equipment, and ASIL-B functional safety certification requirements.
- Front Cameras:High-resolution CMOS sensors paired with 6-8 element lens stacks process real-time lane and object detection for highway assist platforms. German OEMs specify these modules for L2+ autonomous features on premium sedans, driving specification upgrades in dynamic range and thermal stability.
- Rear Cameras:Wide-angle fixed-focus assemblies with IP69K sealing withstand road spray and pressure washing. NHTSA FMVSS 111 mandates have standardized minimum durability thresholds for US-market light vehicles, compressing supplier differentiation to cost and delivery reliability.
- Surround View Cameras:Four-camera synchronized arrays with fisheye distortion correction.
- Night Vision Cameras:Near-infrared augmented sensors with 940nm illuminator pairing.
Front cameras absorb the bulk of installed capacity; surround view systems are expanding most quickly.
Technology:
Sensor technology segmentation tracks power consumption trade-offs and foundry access economics, with CMOS architectures dominating new platform design-ins due to on-chip integration capacity.
- CMOS Sensors:Lower power draw enables multi-camera architectures without electrical system redesign. On-chip ADC integration reduces companion chip count, shrinking module footprint for mirror-replacement and interior monitoring applications where space constraints dominate.
- CCD Sensors:Legacy architectures persist in specialized night vision and thermal fusion systems requiring superior noise performance at extreme low light. Japanese tier-1 suppliers maintain limited production lines for heritage luxury platforms with long model cycles.
- Thermal Imaging:Uncooled microbolometer arrays for pedestrian detection beyond headlight range.
- LIDAR:Solid-state scanning modules for redundant depth perception in robotaxi platforms.
CMOS sensors command the dominant production volume; LIDAR integration is climbing the fastest as L3 architectures approach series production.
Application:
Application segmentation aligns with OEM platform lifecycle timing, where ADAS content ramps precede parking system refreshes by 18-24 months in typical vehicle development schedules.
- ADAS:Multi-camera fusion with radar and ultrasonic inputs enables adaptive cruise, lane keeping, and traffic jam assist. Euro NCAP rating protocols now weight camera-based vulnerable road user detection heavily, forcing specification upgrades across mass-market segments.
- Collision Avoidance:Forward-facing mono and stereo configurations with sub-100ms latency requirements for automatic emergency braking activation. Regulatory mandates in the United States and European Union have made these systems standard fitment on new passenger vehicles.
- Parking Assistance:Ultrasonic-camera fusion for automated maneuvering in confined spaces.
- Driver Monitoring:Infrared-capable interior cameras for drowsiness and distraction detection.
ADAS applications capture the steepest expansion trajectory; parking assistance represents the most mature volume pool with compressed margins.
End User:
End user segmentation reveals channel power dynamics, where OEM direct procurement concentrates specification authority while tier-1 suppliers retain design-in influence through integrated software offerings.
- OEMs:Direct volume contracts for camera modules specify optical performance, mechanical envelope, and software interface requirements. German and Japanese vehicle manufacturers maintain approved supplier lists with 3-5 qualified sources per module category to ensure supply continuity.
- Tier-1 Suppliers:System integrators bundle camera hardware with perception software and ECU processing. Continental AG and Robert Bosch GmbH leverage this position to capture margin from algorithm licensing and over-the-air update architectures.
- Vehicle Manufacturers:Captive production for vertical integration in specific premium segments.
- Aftermarket Providers:Retrofit camera systems for vehicle parc upgrades and commercial fleet additions.
OEM channels dominate procurement volume; tier-1 suppliers are gaining specification influence fastest through software-layer bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German, Japanese, and US vehicle assembly corridors concentrate tier-1 supplier ecosystems and drive specification authority for camera module procurement. Euro NCAP pedestrian-detection protocols and NHTSA rear-visibility mandates are tightening compliance thresholds across export-relevant supply chains.
United States
NHTSA FMVSS 111 mandates force backup camera durability upgrades for light vehicles under 10,000 pounds. The regulation requires redesigned housing seals and flex-cable routing against thermal cycling and vibration exposure. Michigan and Ohio assembly corridors anchor tier-1 supplier integration campuses serving Detroit-based OEM platform development.
Germany
Euro NCAP safety ratings weight camera-based vulnerable road user detection heavily, forcing specification upgrades across mass-market segments. ECE R46 and ECE R79 type approvals govern mirror-replacement and lane-keeping camera performance in European certification. Bavaria's Regensburg sensor integration campus anchors Continental AG's European supply position for ADAS module assembly.
Japan
Long model-cycle heritage luxury platforms sustain limited CCD sensor production lines for specialized night vision applications. METI industrial policy supports CMOS foundry capacity expansion for automotive-grade image sensors. Nagoya and Tokyo corridor clustering accelerates design-in cycles between tier-1 suppliers and domestic OEMs.
China
Domestic EV platform launches are absorbing multi-camera architectures without alternator upgrades through CMOS on-chip integration. GB standards and MIIT regulations shape baseline product requirements for local homologation. Yangtze River Delta manufacturing clusters concentrate optical component supply for cost-competitive module assembly.
South Korea
Seoul Capital Area electronics manufacturing ecosystems enable captive optical component sourcing for module integrators. MFDS automotive safety regulations align with Euro NCAP protocols for export platform compliance. Busan-Ulsan corridor suppliers serve both domestic OEMs and global tier-1 contract manufacturing demand.
Automotive Camera and Camera Module Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with tier-1 system integrators capturing margin from software-layer bundling while pure-play module vendors compete on cost and delivery reliability. The vendor base clusters around three strategic archetypes: captive optical manufacturers defending assembly economics, algorithm-centric integrators licensing perception software, and scale-driven contract manufacturers serving fleet procurement channels. Consolidation pressure is accelerating through M&A activity among mid-tier optical specialists and strategic partnerships between sensor foundries and module integrators.
Among European tier-1 system integrators, Continental AG and Robert Bosch GmbH exemplify the software-bundling archetype through integrated perception algorithm offerings. Valeo SA occupies a position within the captive manufacturing tier through controlled optical supply chains. These three entities anchor the competitive structure across premium and mass-market ADAS platform specifications.
| Leading Market Players |
|---|
| Valeo SA |
| Magna International Inc. |
| Continental AG |
| Gentex Corporation |
| Aptiv Plc |
| Robert Bosch GmbH |
| Denso Corporation |
| LG Innotek Co., Ltd. |
| Mobileye |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap optical specialists in Germany and Japan maintain pricing discipline through captive lens grinding capacity, insulating front-camera assemblies from commodity margin erosion while forcing tier-1 integrators to absorb cost compression through software-layer bundling.
Pricing Analysis
Front-camera modules command premium positioning against rear-camera volume pools. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-B certified highway-assist configurations from parking-assistance commodities. Cost compression in rear-view segments stems from NHTSA FMVSS 111 standardization. Fleet procurement channels exhibit highest price sensitivity; German OEM direct contracts show lowest.
Supply Chain Analysis
Regional distribution centers in Michigan, Bavaria, and Aichi prefecture anchor hub-and-spoke fulfillment patterns for just-in-time assembly line delivery. Module assembly draws from CMOS foundry output in Taiwan and South Korea, precision glass melts from Japan, and polymer resin from German chemical producers. Single-source vulnerability concentrates in automotive-grade high-index optical glass. Distribution runs through tier-1 supplier campuses co-located with OEM vehicle assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is eliminating sub-scale module vendors unable to fund ASIL-B certification and active alignment equipment, compressing the qualified supplier base to tier-1 integrators with software-layer differentiation.
For Market Incumbents: Anchor specification authority through perception algorithm licensing bundled with CMOS module hardware. Deepen captive optical manufacturing in Regensburg and Nagoya corridors to defend margin against polymer lens substitution. Threat of fleet procurement disintermediation demands direct tier-1 contracting capability. For New Entrants and Emerging Players: Commercial vehicle upfitters in North American corridors represent the most penetrable channel for qualified module vendors without OEM captive supply relationships. Target mirror-replacement camera systems under ECE R46 expansion for commercial platforms. Go-to-market through direct fleet procurement contracts bypassing aftermarket channel compression. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier optical specialists with ASIL-B certification infrastructure in German and Japanese manufacturing clusters over pure-play software ventures lacking hardware integration. Long-term viability hinges on five-to-ten year ADAS content per vehicle trajectories. Watch Euro NCAP protocol evolution as inflection indicator for specification upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Perception algorithm licensing captures recurring revenue from OEM over-the-air update architectures. |
| Backward Integration into Optical Components | Captive lens grinding capacity insulates margin against polymer substitution in front-camera tiers. |
| Geographic Manufacturing Footprint | Co-location with Michigan and Bavaria assembly corridors accelerates design-in cycles for ADAS platforms. |
| Platform Standardization | Multi-camera fusion architectures reduce per-unit engineering overhead across vehicle lineups. |
| Charging Infrastructure Partnership | Camera module integration with EV platform electronics consolidates supplier specification authority. |
Research Approach
Document review covered vehicle production databases, IHS Markit registration data, and SEC filings from tier-1 suppliers, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations personnel. Secondary validation drew from Euro NCAP test protocols, NHTSA FMVSS interpretations, and ECE type approval documentation. Bottom-up module shipment estimates triangulated against top-down ADAS content per vehicle analysis.
Historical penetration curves cross-referenced against expert panel input on L2+ deployment timelines shaped the projection framework. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from installed base growth and replacement cycle dynamics across the analysis window. CMOS sensor foundry capacity expansion and Euro NCAP protocol evolution served as key forecast inputs.
Caveats apply where silicon wafer input volatility, ECE R79 homologation fragmentation, or UN R157 national exemption divergence could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Automotive Micro Switch Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market