
 Canada Automotive Camera Market | 2026-2036
Canada Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Camera Market Outlook
Silicon-based image sensors is consolidating market economics as CMOS arrays displace legacy CCD architectures across Canadian vehicle programs. Bosch Canada leverages in-house semiconductor sourcing to sustain margin structures on advanced driver-assistance bundles. Magna International anchors its camera module production in Ontario, competing on proximity to Detroit-Windsor assembly corridors. Continental AG differentiates through thermal imaging integration for winter-optimized commercial fleets.
Canada automotive cameras are electro-optical sensing devices comprising lens assemblies, solid-state imagers, and signal-processing chipsets sealed to IP69K ingress standards, designed to capture real-time visual data for collision avoidance, lane-keeping, and automated parking functions. The product mix tilts toward surround-view camera configurations as OEMs bundle multi-angle visibility into premium trim packages. CMOS technology leads unit economics through lower power draw and on-chip integration, while thermal imaging commands specialized margin pools in mining and northern logistics fleets where night-vision reliability outperforms conventional sensors.
Transport Canada mandates rear-visibility compliance under the Motor Vehicle Safety Act, while the Canadian Standards Association certifies electromagnetic compatibility and environmental durability for electronic subassemblies. Health Canada coordinates with PMRA on data privacy frameworks governing camera-recorded footage in connected vehicles. Stakeholders must monitor how provincial insurance regulators in Ontario and British Columbia weigh camera-derived evidence in liability determinations, as this shapes aftermarket installation incentives and OEM specification tiers.
Market Dynamics
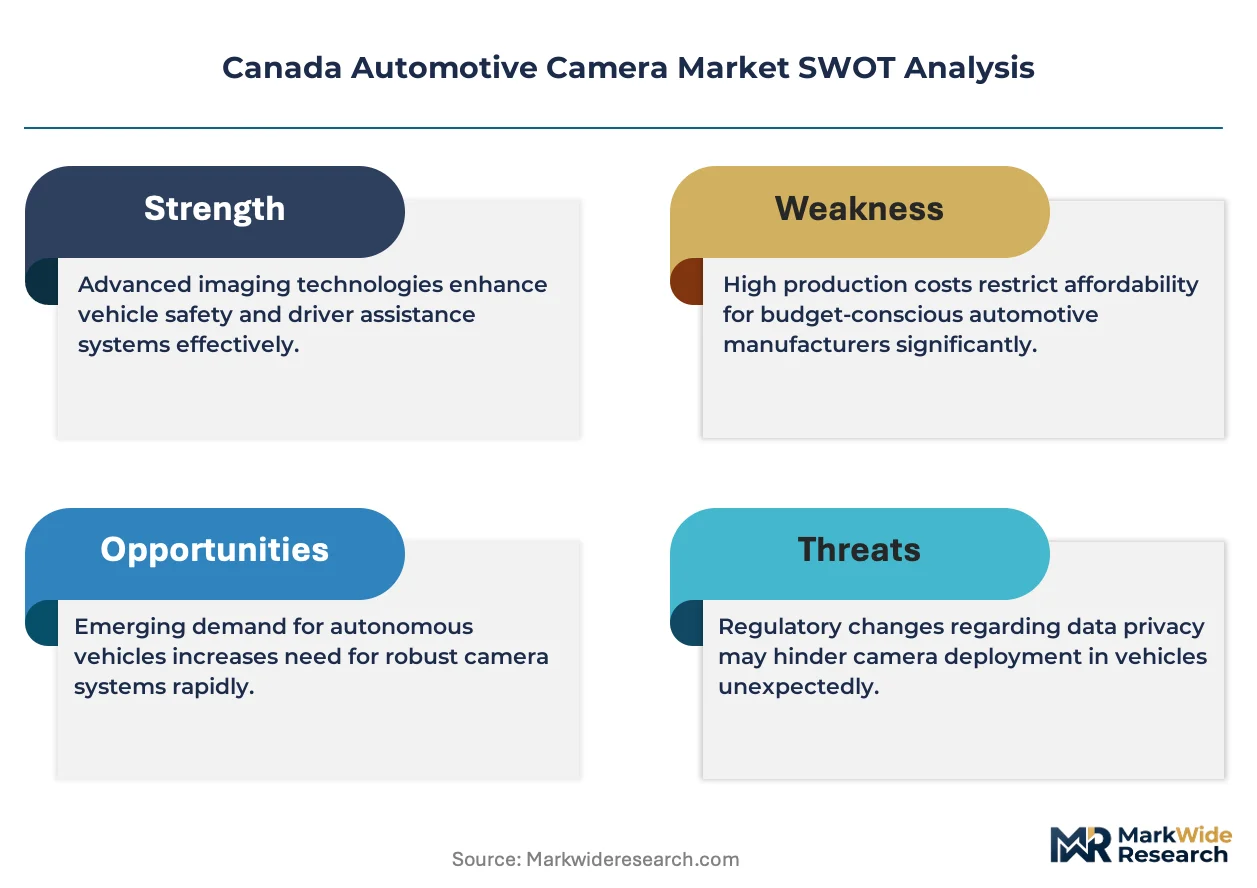
Transport Canada's rear-visibility mandate is compressing supplier compliance timelines while CMOS sensor economics redraw procurement criteria across Ontario and Quebec assembly corridors.
Growth Catalysts
- Regulatory Mandate Compression:Transport Canada's Motor Vehicle Safety Act amendments are accelerating rear-camera installation across all new vehicle classes. Tier-one suppliers in the Greater Toronto Area are scaling module production to meet tightened homologation schedules.
- Silicon Photonics Integration:CMOS image sensor arrays are displacing legacy CCD architectures in Canadian vehicle programs. Lower power draw and on-chip signal processing reduce wiring harness complexity for Windsor-Oshawa assembly lines.
- Winter Fleet Specialization:Mining and northern logistics operators in Alberta and Saskatchewan are specifying thermal imaging overlays. Night-vision reliability in sub-zero conditions commands premium specification tiers for commercial vehicle procurement.
Market Restraints
- Semiconductor Input Volatility:Wafer fabrication capacity constraints in Asia-Pacific create component lead time uncertainty. Canadian camera module assemblers face margin pressure from spot-market memory pricing.
- Supply Concentration Risk:Lens assembly and precision optics sourcing concentrates in East Asian manufacturing clusters. Single-source dependencies for IP69K sealing components expose Ontario production lines to logistics disruption.
- Electromagnetic Compatibility Friction:Canadian Standards Association certification timelines for 5G-V2X coexistence testing extend product validation cycles. Multi-band antenna integration creates interference engineering bottlenecks.
Strategic Opportunities
- Atlantic Canada Aftermarket Penetration:Newfoundland and Nova Scotia commercial fleets show underpenetrated camera retrofit rates. Provincial safety incentive programs in these regions create channel expansion potential for specialized installers.
- Privacy Framework Tailwinds:Health Canada and PMRA coordination on connected vehicle data governance is clarifying liability boundaries. Regulatory certainty accelerates OEM specification of cloud-connected camera systems.
- Thermal-Conventional Sensor Fusion:Multi-spectral imaging stacks combining CMOS visible-light and microbolometer thermal cores enable new ADAS functionality. Quebec winter driving conditions provide ideal validation environments for fused perception algorithms.
Industry Challenges
- Embedded Vision Engineering Talent Scarcity:Signal processing and machine learning optimization for edge inference requires specialized skill sets. Ontario universities produce insufficient graduates to meet Windsor-Toronto corridor demand.
- Legacy Vehicle Integration Complexity:CAN bus architecture variations across 2015-2020 model year vehicles complicate aftermarket camera retrofits. British Columbia and Alberta installers report diagnostic protocol fragmentation.
- Software-Defined Camera Certification:Over-the-air update capabilities for neural network weights challenge traditional type-approval frameworks. Transport Canada and CSA are developing new validation protocols for updatable safety systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Camera Market |
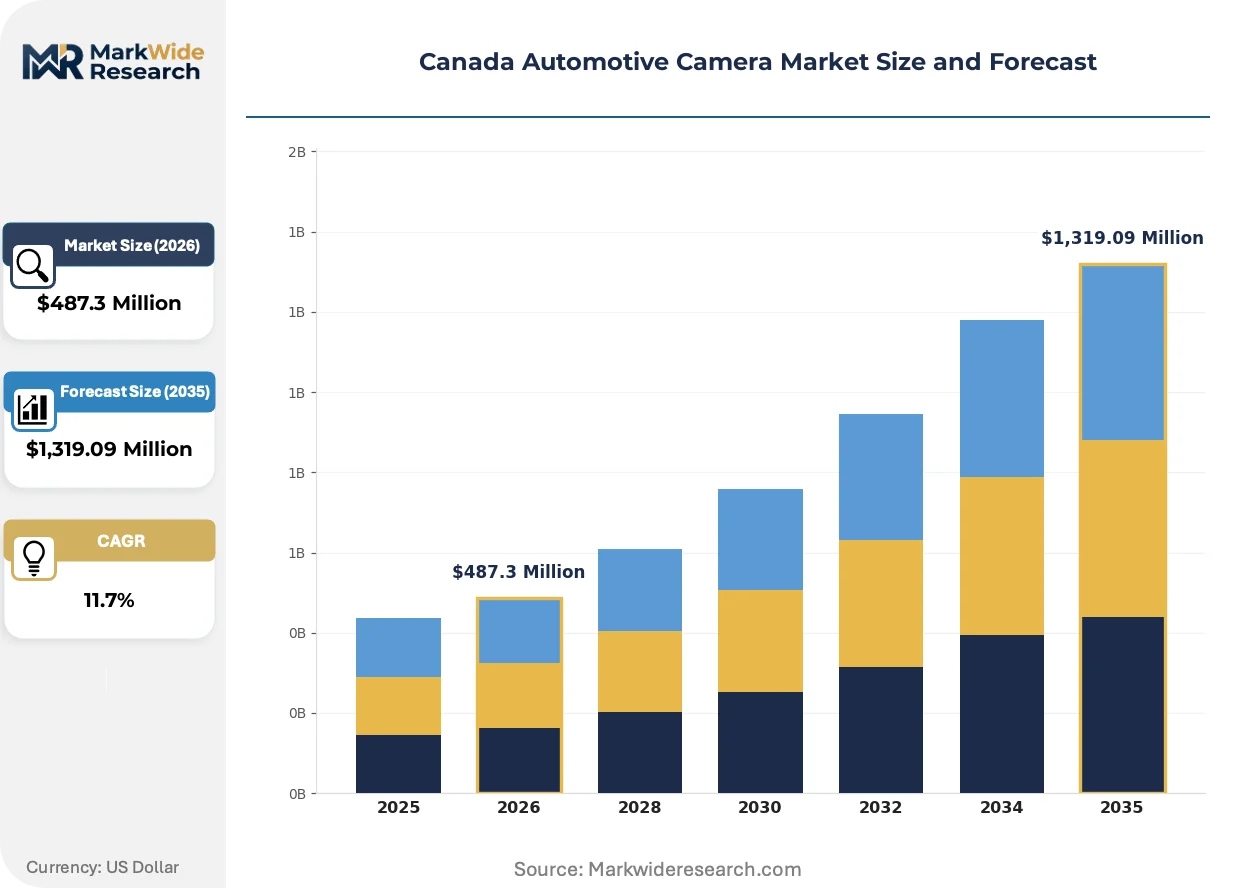
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rear-View Camera, Surround-View Camera, Dash Cameras, Parking Assistance Cameras Technology: CCD, CMOS, Night Vision, Thermal Imaging End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Installation: Integrated, Standalone, Wireless, Wired |
| Companies Covered | Magna International, Bosch Canada, Continental AG, Valeo Canada, Aptiv PLC, Mobileye, Gentex Corporation, Robert Bosch GmbH, Denso Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Camera Market Strategic Shifts
Silicon-based imaging architectures and regulatory mandates are converging to reshape specification criteria across Canadian vehicle assembly and aftermarket channels.
CMOS image sensor technology is consolidating market economics across Canadian automotive camera procurement. Solid-state imagers with on-chip analog-to-digital conversion reduce power dissipation and simplify thermal management for compact module designs. Magna International and tier-one assemblers in the Greater Toronto Area are specifying these arrays for surround-view and rear-visibility configurations.
Transport Canada's Motor Vehicle Safety Act amendments are mandating rear-visibility systems across all new passenger vehicles and light trucks. The compliance timeline compression is forcing suppliers to accelerate electromagnetic compatibility and environmental durability testing. Ontario-based module producers are prioritizing IP69K sealing validation and CSA certification to maintain OEM qualification status.
Fleet procurement patterns in Alberta and Saskatchewan are pivoting toward integrated thermal-visible sensor bundles. Mining operators and northern logistics providers demand night-vision reliability that exceeds conventional CMOS performance in sub-zero, low-illumination conditions. Regional equipment distributors are building specialized installation capacity to capture this specification tier.
Canada Automotive Camera Market Segmentation
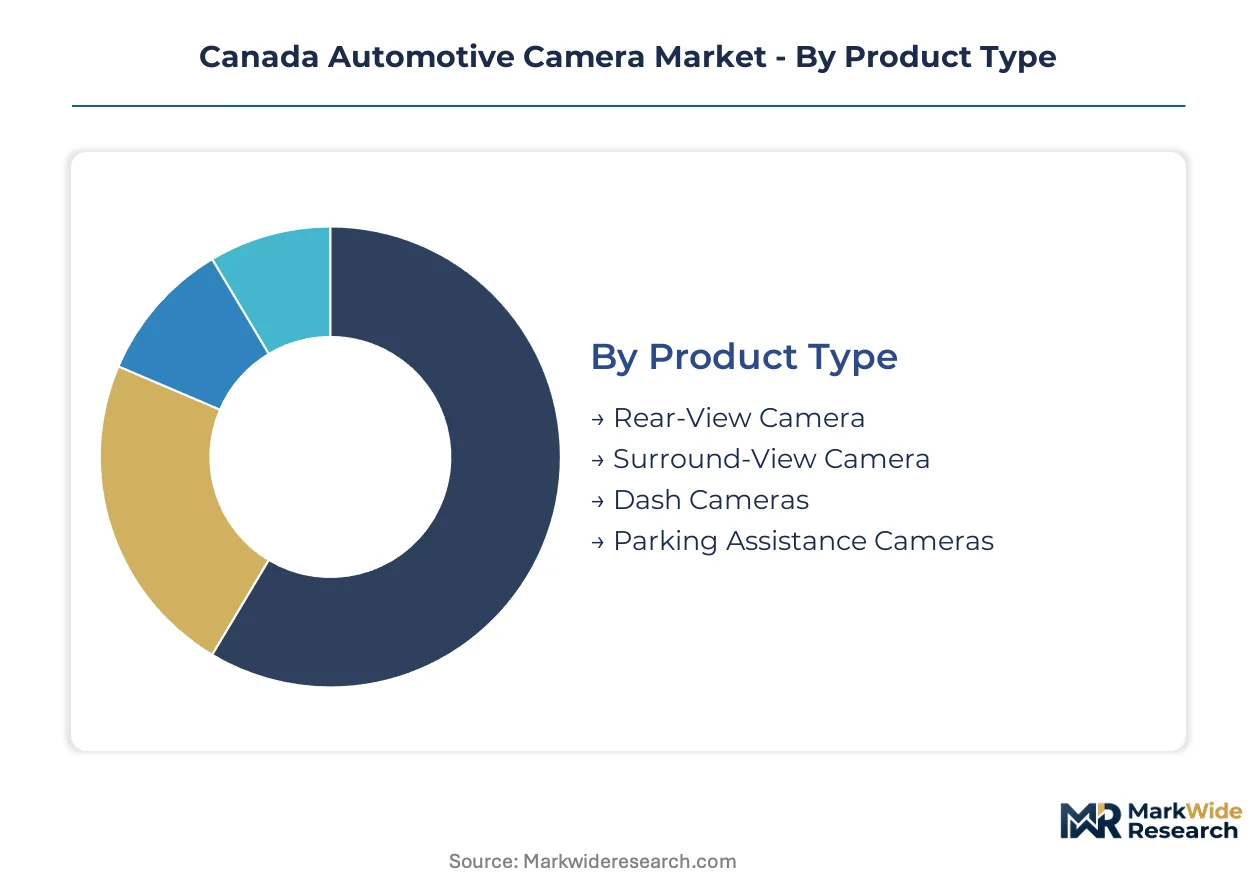
Camera specification tiers in Canada diverge sharply between regulatory-mandated rear-visibility systems and premium surround-view bundles. Procurement patterns across Ontario assembly corridors and Alberta fleet operators create distinct demand clusters that reshape supplier product roadmaps.
Product Type:
Module assembly capacity in the Greater Toronto Area concentrates on configurations serving Transport Canada compliance deadlines and OEM premium packaging strategies.
- Rear-View Camera:Single-lens modules with IP69K sealing and CMOS imagers satisfy Motor Vehicle Safety Act mandates. Windsor-Oshawa assembly lines specify these for light-truck and SUV lineups where compliance timelines compress supplier validation cycles.
- Surround-View Camera:Multi-lens synchronized arrays generate stitched 360-degree visibility for premium trim tiers. Quebec and Ontario OEMs bundle these into luxury packages where proximity to Detroit-Windsor corridors enables just-in-time module delivery.
- Dash Cameras:Forward-facing recording devices with loop storage serve aftermarket channels and fleet liability management.
- Parking Assistance Cameras:Ultrasonic-fusion modules with dynamic overlay graphics target urban commercial vehicle specifications.
Rear-View Camera absorbs the bulk of installed capacity; Surround-View Camera is expanding most quickly.
Technology:
Silicon sourcing economics and winter reliability requirements split procurement between mainstream CMOS adoption and specialized thermal specifications.
- CMOS:Solid-state imagers with on-chip analog-to-digital conversion dominate new vehicle programs. Lower power draw and simplified thermal management reduce wiring harness complexity for Magna International and tier-one assemblers clustering around Toronto.
- Thermal Imaging:Microbolometer arrays detect infrared signatures for night-vision reliability in sub-zero conditions. Alberta mining operators and Saskatchewan logistics fleets specify these for commercial procurement where conventional sensors fail in low-illumination environments.
- CCD:Legacy charge-coupled devices persist in specific aftermarket retrofit applications requiring analog signal compatibility.
- Night Vision:Low-light enhancement algorithms paired with high-sensitivity CMOS variants serve premium passenger vehicle segments.
CMOS captures the dominant production volume; Thermal Imaging commands the steepest expansion trajectory among specialized tiers.
End User:
Customer procurement authority determines specification complexity, with vehicle assemblers driving volume and fleet operators demanding customized durability packages.
- OEMs:Original equipment manufacturers in Ontario and Quebec integrate cameras at trim-level differentiation points. Their procurement teams negotiate multi-year module supply agreements with proximity requirements to Detroit-Windsor assembly corridors.
- Fleet Operators:Mining and northern logistics companies in Alberta and Saskatchewan specify thermal-visible fusion bundles. Their winter reliability requirements exceed standard OEM offerings, creating specialized margin pools for regional equipment distributors.
- Aftermarket Providers:Independent installers serve legacy vehicle retrofit demand across British Columbia and Atlantic Canada.
- Vehicle Assemblers:Contract manufacturers without full OEM status source modules for niche commercial vehicle builds.
OEMs command the largest procurement volume; Fleet Operators are gaining share fastest through specialized winter specifications.
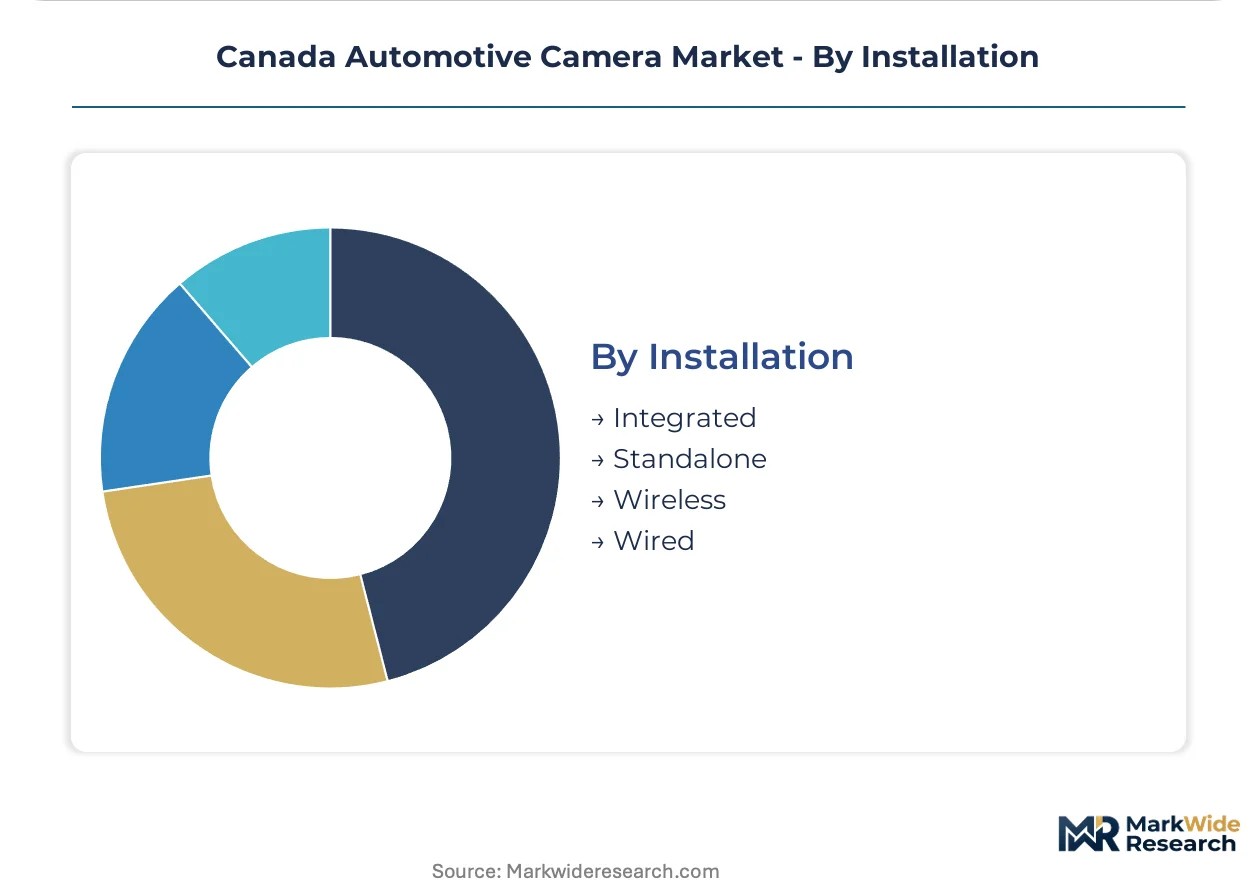
Installation:
Wiring architecture choices reflect vehicle electrical system maturity and aftermarket retrofit complexity across Canadian provincial markets.
- Integrated:Factory-installed modules with CAN bus connectivity and OTA update capability serve new vehicle production. Ontario-based assemblers prioritize these for streamlined homologation and reduced dealer installation liability.
- Wired:Dedicated harness connections with shielded coaxial or Ethernet cabling dominate commercial fleet retrofits. British Columbia installers prefer these for diagnostic reliability in legacy vehicle integrations.
- Standalone:Self-powered recording devices with internal storage target consumer aftermarket channels.
- Wireless:Wi-Fi or Bluetooth-linked modules reduce installation labor for smartphone-connected dash camera deployments.
Integrated installation absorbs the bulk of module production; Wired configurations retain strongest growth in fleet retrofit segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Advanced Manufacturing Investment Strategy and Quebec's green technology tax credits are concentrating camera module assembly capacity along the Windsor-Toronto corridor and Greater Montreal area.
Ontario
OEM procurement teams in Windsor and Oshawa specify surround-view and rear-visibility modules for light-truck lineups. Transport Canada's Motor Vehicle Safety Act amendments compress supplier homologation timelines for these assembly plants. Magna International anchors production in Aurora and Brampton to maintain proximity to Detroit-Windsor cross-border logistics.
Quebec
Winter driving conditions drive demand for thermal-visible sensor fusion in commercial vehicle specifications. The province's green technology investment tax credits support camera module R&D facilities in Longueuil. Continental AG maintains engineering presence in Montreal to validate perception algorithms under sub-zero illumination conditions.
Alberta
Mining operators and northern logistics fleets in Fort McMurray and Edmonton specify night-vision reliability exceeding standard CMOS performance. Provincial commercial vehicle safety regulations incentivize retrofit installations for heavy-duty truck fleets. Regional equipment distributors in Calgary build specialized installation capacity for thermal imaging bundles.
British Columbia
Aftermarket retrofit demand concentrates in Vancouver and Victoria for legacy vehicle camera installations. Insurance regulators in the province weigh camera-derived evidence in liability determinations, shaping installer incentive structures. CAN bus diagnostic protocol fragmentation complicates integration across 2015-2020 model year vehicles in these urban markets.
Atlantic Canada
Newfoundland and Nova Scotia commercial fleets show underpenetrated camera retrofit rates relative to central Canada. Provincial safety incentive programs in Halifax and St. John's create channel expansion potential for specialized installers. Fleet operators in these markets prioritize wired harness configurations for diagnostic reliability in legacy vehicle integrations.
Canada Automotive Camera Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with tier-one module assemblers dominating OEM procurement while regional distributors capture fleet retrofit demand. The vendor base concentrates around proximity to Ontario and Quebec assembly corridors, creating geographic clustering rather than pure scale consolidation. Three archetypes define competitive positioning: integrated multinational electronics suppliers, domestic module assemblers with captive OEM relationships, and specialized thermal imaging distributors serving resource extraction fleets. Capacity expansion and strategic technology licensing represent the dominant competitive moves as suppliers navigate Transport Canada compliance timelines.
Among integrated multinational suppliers, Magna International and Bosch Canada exemplify the tier-one archetype with in-house semiconductor sourcing and proximity to Detroit-Windsor corridors. Continental AG occupies a position within the specialized imaging tier, differentiating through thermal integration capabilities. These three anchors demonstrate how competitive positioning stratifies across regulatory compliance, silicon economics, and winter-optimized functionality.
| Leading Market Players |
|---|
| Magna International |
| Bosch Canada |
| Continental AG |
| Valeo Canada |
| Aptiv PLC |
| Mobileye |
| Gentex Corporation |
| Robert Bosch GmbH |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap lens specialists in Ontario and Quebec anchor tier-two supply tiers, feeding module assemblers with IP69K sealing components while extracting pricing premiums through proximity to Windsor-Toronto assembly corridors. Their geographic clustering reinforces cost discipline for tier-one buyers negotiating multi-year offtake agreements with Transport Canada compliance deadlines compressing validation cycles.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as OEMs accelerate homologation schedules under Motor Vehicle Safety Act amendments. Three-tier pricing structure across premium, standard, and economy levels separates CSA-certified modules with OTA capability from wired retrofit configurations and standalone aftermarket units. Cost compression in economy tiers is intensifying because spot-market memory pricing volatility squeezes margin structures for CMOS imager bundles. Fleet operators in Alberta mining corridors demonstrate lowest price sensitivity due to night-vision reliability requirements, while Atlantic Canada commercial retrofitters face acute budget constraints.
Supply Chain Analysis
Domestic-content mandates under Canada's Advanced Manufacturing Investment Strategy are reshaping sourcing patterns for Windsor-Oshawa assembly lines. Wafer fabrication concentrates in Taiwan, South Korea, and Japan, while precision optics and IP69K sealing components draw from China and Germany. Raw material dependencies span silicon wafers, glass lens substrates, and automotive-grade memory modules. Single-source vulnerability for microbolometer thermal cores exposes Alberta fleet procurement to logistics disruption. Distribution runs through tier-one module assemblers clustering around Aurora and Brampton, with regional equipment distributors capturing specialized thermal imaging retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada automotive camera market functions as a vertical-integration race where in-house semiconductor sourcing and captive lens production determine margin capture. Players are pursuing upstream control over CMOS imager supply to offset spot-market volatility and secure Transport Canada qualification timelines.
For Market Incumbents: Lock in multi-year wafer supply agreements with Taiwan and South Korean foundries before capacity constraints tighten further. Prioritize backward integration into IP69K sealing component production to reduce single-source exposure for Ontario assembly lines. Defensive consolidation around thermal imaging engineering talent in Quebec prevents Continental AG from monopolizing winter-optimized specification tiers.
For New Entrants and Emerging Players: Atlantic Canada commercial fleet operators represent the most penetrable buyer archetype given underpenetrated retrofit rates and provincial safety incentive programs. Specialized installation partnerships with Newfoundland and Nova Scotia distributors bypass incumbent channel control. Direct-to-fleet thermal-visible fusion bundles targeting Saskatchewan logistics operators exploit pricing inelasticity in sub-zero reliability segments.
For Investors and Strategic Acquirers: Health Canada and PMRA coordination on connected vehicle data governance is the leading indicator that cloud-connected camera system specifications will accelerate OEM procurement. Long-term viability hinges on software-defined camera certification capabilities as Transport Canada develops updatable safety system validation protocols. Acquisition targets should demonstrate embedded vision engineering capacity with machine learning optimization for edge inference. Watch for tier-one suppliers announcing in-house semiconductor sourcing initiatives as the inflection signal for vertical-integration momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Sensor Backward Integration | In-house wafer sourcing insulates Magna International and Bosch Canada from Asia-Pacific capacity constraints. |
| Thermal-Visible Sensor Fusion R&D | Continental AG's Montreal engineering presence validates perception algorithms under Quebec winter conditions. |
| Atlantic Canada Distribution Expansion | Specialized installer partnerships capture provincial safety incentive programs in Halifax and St. John's. |
| Software-Defined Camera Certification | OTA update capabilities require new Transport Canada validation protocols for neural network weight updates. |
| IP69K Sealing Component Captive Production | Ontario-based module producers reduce single-source dependencies for lens assembly and precision optics. |
Study Parameters
Multi-period observation of vehicle production volumes, camera content per vehicle, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and fleet operations managers. Secondary validation drew from Transport Canada Motor Vehicle Safety Act filings, Canadian Standards Association certification databases, vehicle registration data, and provincial commercial vehicle safety regulations. Bottom-up module shipment estimates triangulated against top-down OEM procurement budget allocations across Ontario and Quebec assembly corridors.
Input-output matrices structured demand forecasting across vehicle class, propulsion architecture, camera configuration tier, and regional production cluster dimensions throughout the forecast period. CAGRs derived from segment-level shipment trajectories weighted by average selling price evolution. Industry-specific forecast inputs incorporated Transport Canada mandate implementation schedules and CMOS sensor cost curve projections from foundry capacity expansion announcements.
Revisions become necessary when semiconductor fabrication capacity constraints intensify, when Transport Canada accelerates or delays rear-visibility compliance deadlines, or when provincial insurance regulators fundamentally alter camera-derived evidence admissibility standards. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Automotive AR HUD Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market