
 Automotive Haptic Technology Market | 2026-2036
Automotive Haptic Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Haptic Technology Market Analysis
The gap between premium and commodity haptic tiers is hardening as OEMs specify piezoelectric actuators with sub-millisecond response times for flagship vehicles while budget segments retain basic eccentric rotating mass vibration motors. TDK Corporation leverages its magnetics expertise to supply high-definition haptic modules for European luxury brands. Immersion Corporation anchors the software-licensing layer through its touch-feedback patent portfolio.
Automotive haptic technology encompasses electromechanical systems that generate tactile sensations through controlled vibration, pressure, or thermal variation to communicate information to vehicle occupants without visual fixation. These systems typically operate at frequencies between 100 and 300 Hz for optimal human skin perception and serve primarily to reduce cognitive load during driving tasks. Piezoelectric actuators command the highest margin pools due to precision and energy efficiency, while electromagnetic solutions dominate volume shipments in mainstream vehicle segments. Control interfaces are gaining structural importance as touch-surface adoption displaces physical buttons across dashboard architectures.
The National Highway Traffic Safety Administration and the European Union's Vehicle General Safety Regulation shape product requirements by mandating driver-attention systems that incorporate non-visual alerting mechanisms. ISO 26262 functional-safety standards further constrain component qualification timelines for Tier 1 suppliers. Stakeholders must weigh R&D allocation between thermal-feedback differentiation and electromagnetic cost reduction as electrification platforms redefine interior electronics budgets.
Market Dynamics
Touch-surface proliferation across vehicle interiors is compressing actuator development cycles as OEMs eliminate physical buttons. Tier 1 suppliers must now deliver haptic feedback systems that integrate with curved displays and capacitive panels.
Growth Catalysts
- EU Vehicle General Safety Regulation:Mandates for driver-monitoring systems with tactile alerting mechanisms create embedded demand for steering-wheel and seat actuators.
- Piezoelectric precision:Sub-millisecond response times enable texture simulation on flat surfaces, differentiating premium interiors from commodity vibration motors.
- China:Domestic EV manufacturers specify localized haptic module production, accelerating regional supply chain maturation.
Market Restraints
- PZT ceramic supply:Lead zirconate titanate feedstock concentrates among Japanese and Chinese specialty chemical producers, exposing margins to raw material volatility.
- ISO 26262 qualification:Functional-safety certification timelines extend component validation by 18-24 months, freezing design iterations.
- Electromagnetic substitutes:Eccentric rotating mass motors satisfy budget segment requirements at one-fifth the unit cost of piezoelectric alternatives.
Strategic Opportunities
- Thermal-feedback integration:Convergence of temperature-variant materials with vibration actuators opens climate-control and wellness applications in luxury cabins.
- Germany:KBA type-approval processes for novel driver-vehicle interfaces favor early entrants with established safety documentation.
- Subscription software layers:Over-the-air haptic pattern updates create recurring revenue streams independent of hardware replacement cycles.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional engineers capable of bridging firmware, materials science, and human-factors design command premium compensation.
- Legacy CAN bus integration:Real-time haptic feedback demands latency below 50 milliseconds, forcing gateway architecture redesigns in existing vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Haptic Technology Market |
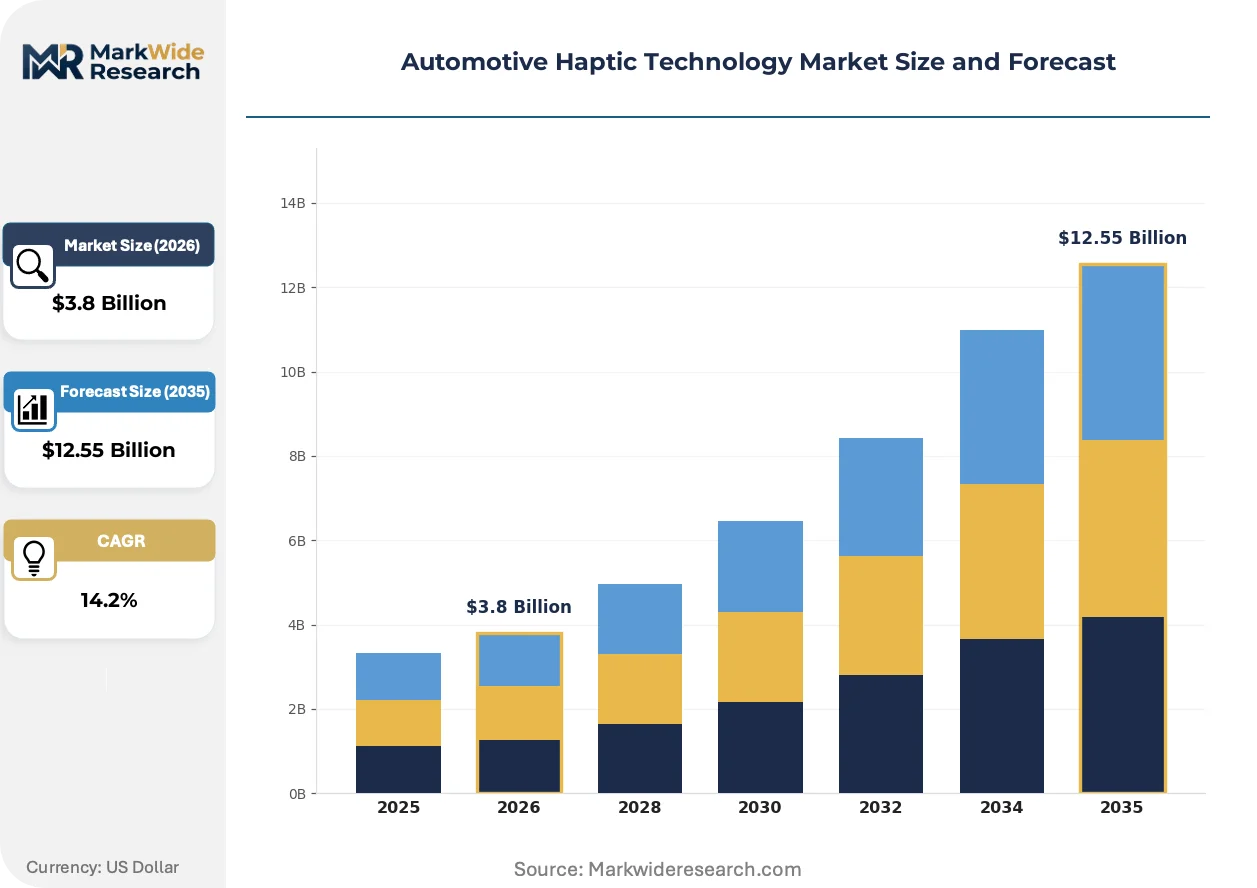
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Actuators, Feedback Devices, Control Interfaces, Sensors End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Application: Dashboard Controls, Infotainment Systems, Safety Features, Navigation Aids Technology: Mechanic Vibration, Piezoelectric, Electromagnetic, Thermal |
| Companies Covered | TDK Corporation, Immersion Corporation, Texas Instruments Incorporated, Apple Inc., Qualcomm Technologies, Johnson Electric Holdings Limited, Semiconductor Components Industries, LLC, Google LLC, AAC Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Haptic Technology Market Emerging Trajectories
Haptic system architectures are fragmenting into discrete, upgradeable subsystems. Component suppliers now compete on integration speed rather than standalone actuator performance.
Surface-integrated piezoelectric arrays is modularizing across curved dashboard substrates. European luxury OEMs embed these layers beneath decorative films during assembly. The technology compresses supplier tiers by enabling direct Tier 2-to-OEM relationships.
NHTSA guidelines on distracted-driving mitigation are tightening tactile-alert specifications for commercial vehicle operators. Fleet procurement departments now require documented haptic-response latency in supplier scorecards. Long-haul trucking segments in the United States are retrofitting steering-wheel modules to meet emerging compliance thresholds.
Buyer preference for configurable feedback intensity is displacing fixed factory settings. Aftermarket calibration tools now reach enthusiast segments through specialty retailers. Japan and South Korea exhibit the strongest consumer willingness to pay for personalized haptic profiles.
Automotive Haptic Technology Market Segmentation
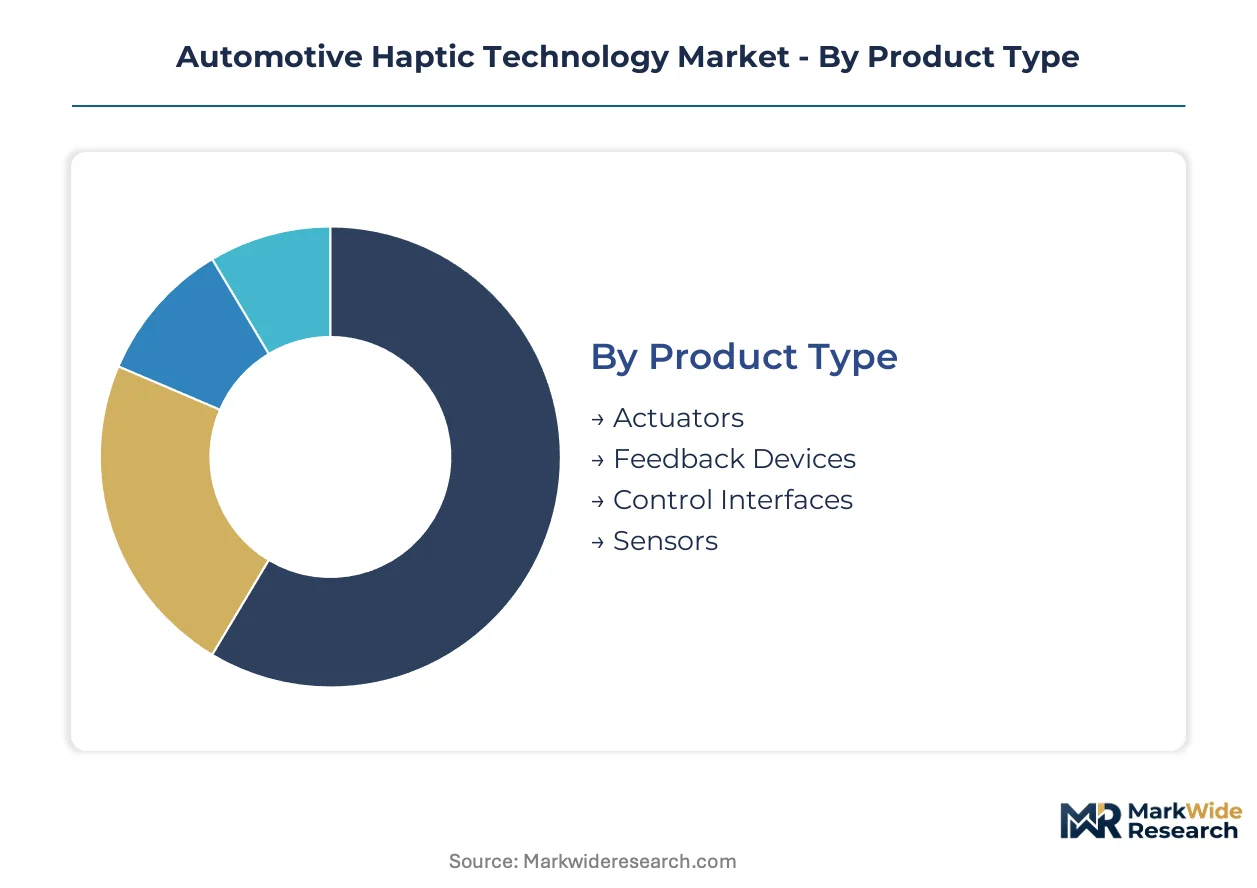
Haptic system architectures fragment across actuator technologies, interface layers, and vehicle integration points. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape supplier positioning.
Product Type:
Component hierarchy reflects precision requirements versus unit economics in electrified vehicle interiors.
- Actuators:Electromechanical transducers convert electrical signals into physical displacement at frequencies optimized for human skin perception. Piezoelectric variants capture premium steering-wheel and seat applications in German and Chinese luxury platforms where EU safety mandates require sub-50-millisecond alert latency.
- Feedback Devices:Integrated modules combine vibration generation with surface mounting hardware for curved dashboard substrates. Demand concentrates in European OEM assembly lines where decorative film integration eliminates secondary supplier tiers.
- Control Interfaces:Capacitive touch surfaces with embedded haptic response replace physical buttons across center console redesigns.
- Sensors:Force and position detection elements enable closed-loop feedback calibration in real-time driving environments.
Mature deployment sits with Actuators. Newer deployment is concentrated in Control Interfaces.
End User:
Procurement authority determines specification stringency and volume predictability across the value chain.
- OEMs:Vehicle manufacturers specify haptic systems during platform development cycles with ISO 26262 functional-safety constraints extending validation timelines. German and US-based OEMs drive piezoelectric adoption through force-feedback steering wheels that satisfy NHTSA distracted-driving guidelines.
- Aftermarket Providers:Specialty retailers and installation shops serve enthusiast segments seeking configurable feedback intensity profiles. Japanese and South Korean consumer willingness to pay for personalized haptic settings sustains this channel's expansion.
- Dealerships:Franchise networks bundle haptic upgrades with premium trim packages during vehicle delivery.
- Fleet Operators:Commercial vehicle procurement departments now mandate documented haptic-response latency in supplier scorecards for long-haul trucking retrofits.
Volume concentration rests with OEMs. Margin expansion is climbing fastest in Aftermarket Providers.
Application:
Functional purpose dictates frequency range, amplitude envelope, and safety-critical classification.
- Safety Features:Lane-departure warnings and collision alerts operate through steering-wheel vibration at amplitudes ensuring perception during high-cognitive-load driving. EU Vehicle General Safety Regulation mandates embed this application with compliance-driven procurement in European and Chinese markets.
- Infotainment Systems:Texture simulation on flat glass surfaces enables eyes-free operation of media and climate controls. Premium cabin architectures in German luxury brands deploy piezoelectric arrays beneath curved displays.
- Dashboard Controls:Center console button replacement drives actuator integration with capacitive panels.
- Navigation Aids:Directional pulse patterns communicate turn-by-turn guidance without visual fixation.
Regulatory pull centers on Safety Features. Experience differentiation is expanding most quickly in Infotainment Systems.
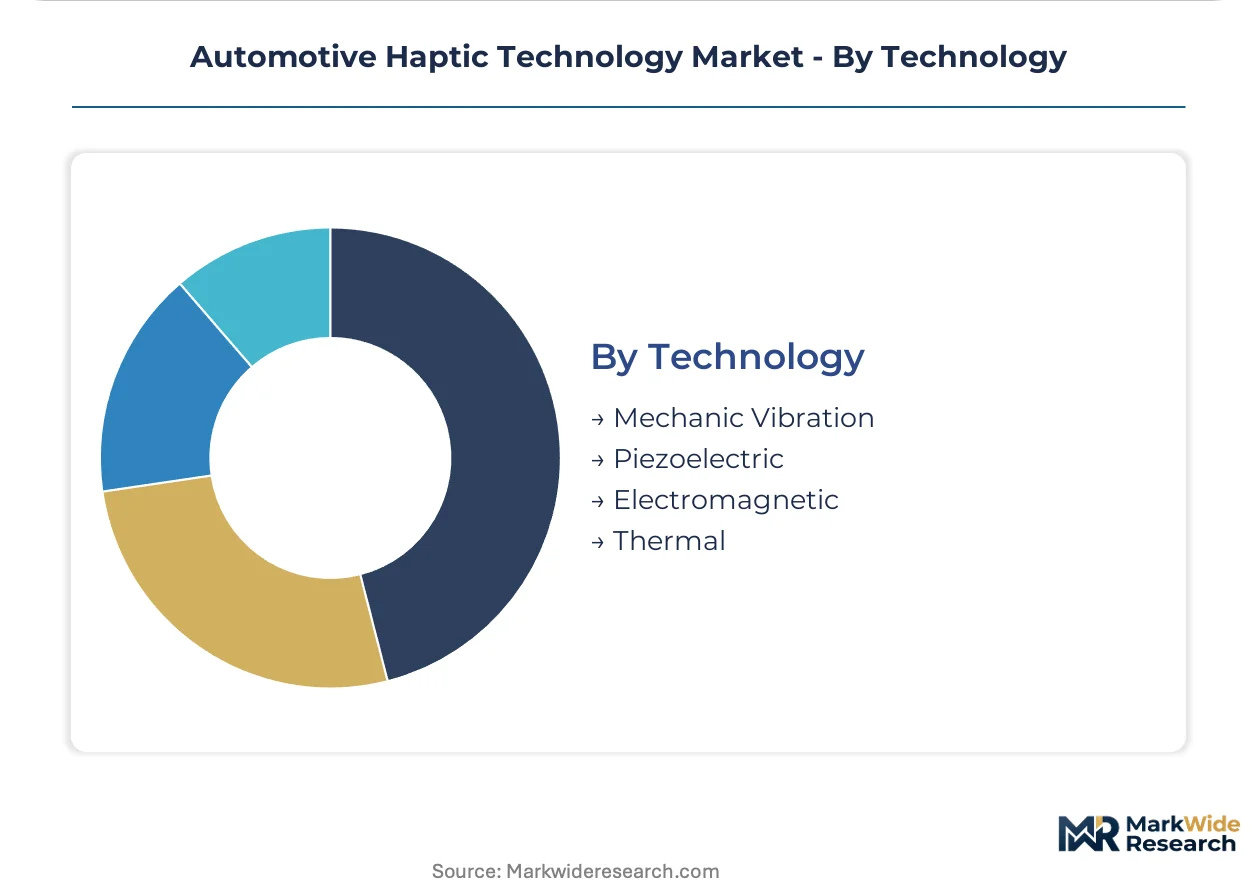
Technology:
Physical operating principle separates precision-tier solutions from commodity vibration generation.
- Piezoelectric:Ceramic-based actuators achieve sub-millisecond response times with minimal energy draw, enabling texture rendering and precise amplitude control. Japanese PZT ceramic supply concentration exposes margins to feedstock volatility while premium OEMs specify these modules for flagship differentiation.
- Electromagnetic:Voice-coil and eccentric rotating mass motors dominate volume shipments through cost structures at one-fifth piezoelectric alternatives. Budget vehicle segments across Chinese domestic EV platforms standardize on these solutions.
- Mechanic Vibration:Eccentric mass rotation provides basic alerting without frequency modulation capability.
- Thermal:Temperature-variant materials converge with vibration actuators for climate-control and wellness applications in luxury cabins.
Cost-driven standardization anchors Electromagnetic. Performance-driven specification is gaining share fastest in Piezoelectric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive haptic development through dense Tier 1 supplier networks serving Mercedes-Benz and Porsche platform teams. This industrial corridor channels EU safety mandates into production-ready force-feedback systems for next-generation vehicle architectures.
United States
NHTSA distracted-driving guidelines tighten tactile-alert specifications for commercial fleet operators. Long-haul trucking segments in Michigan and Ohio retrofit steering-wheel modules to meet emerging compliance thresholds. Detroit-based engineering centers prototype haptic interfaces for autonomous vehicle handoff scenarios.
Germany
KBA type-approval processes for novel driver-vehicle interfaces favor early entrants with established safety documentation. Bavarian automotive clusters integrate piezoelectric arrays beneath curved dashboard substrates for premium cabin differentiation. Munich engineering consultancies bridge ISO 26262 functional-safety requirements with haptic system validation.
China
Domestic EV manufacturers specify localized haptic module production, accelerating regional supply chain maturation. MIIT standards for intelligent vehicle interfaces incorporate tactile feedback performance metrics. Shenzhen and Shanghai hardware ecosystems feed component volumes into BYD and NIO assembly lines.
Japan
METI industrial policy supports advanced actuator development for next-generation mobility platforms. Nagoya automotive suppliers concentrate PZT ceramic feedstock relationships for piezoelectric precision modules. Toyota and Honda procurement teams qualify haptic subsystems through JIS-standard testing protocols.
South Korea
MFDS-equivalent automotive safety frameworks adopt EU-aligned tactile-alert mandates for export vehicle compatibility. Seoul Capital Area electronics conglomerates leverage display panel expertise into integrated haptic feedback layers. Hyundai-Kia platform teams specify configurable feedback intensity for personalized driver profiles.
Automotive Haptic Technology Market Vendor Landscape
Premium-margin players sit above commodity-margin players across actuator technology tiers, with piezoelectric specialists commanding fivefold unit price multiples over electromagnetic alternatives. The vendor base stratifies between magnetics-focused component conglomerates, touch-feedback patent licensors, and precision actuator specialists. Three archetypes dominate: integrated electronics suppliers with captive magnetics capabilities, pure-play haptic software licensors, and automotive Tier 1 system integrators. Competitive moves concentrate on backward integration into ceramic feedstock and strategic patent cross-licensing to secure royalty streams.
Within the integrated electronics tier, TDK Corporation and Texas Instruments Incorporated exemplify magnetics and semiconductor anchor positions respectively. Immersion Corporation occupies the pure-play software licensing archetype, monetizing touch-feedback intellectual property across multiple hardware platforms. These three entities represent divergent margin capture strategies—component manufacturing, chip integration, and royalty extraction—within a market where control-interface standardization remains unresolved.
| Leading Market Players |
|---|
| TDK Corporation |
| Immersion Corporation |
| Texas Instruments Incorporated |
| Apple Inc. |
| Qualcomm Technologies |
| Johnson Electric Holdings Limited |
| Semiconductor Components Industries, LLC |
| Google LLC |
| AAC Technologies |
| Others |
Supply Flow & Price Mechanics
Premium-commodity actuator divergence separates piezoelectric modules commanding fivefold unit multiples from electromagnetic alternatives, with this bifurcation manifesting in tiered procurement strategies and concentrated ceramic feedstock sourcing across Japanese and Chinese specialty chemical producers. OEM specification stringency for sub-50-millisecond response times hardens margin pools at the precision tier while budget vehicle segments absorb cost-engineered vibration motors from regional electromagnetic suppliers.
Pricing Analysis
Value-based pricing anchors on ISO 26262 certification tiers and functional-safety performance metrics rather than component cost alone. Price differentiation separates ASIL-D qualified piezoelectric arrays for steering-wheel applications from basic ERM motors in economy center consoles. Pricing pressure stems from PZT ceramic feedstock volatility as Japanese and Chinese producers concentrate specialty chemical supply. Fleet operators and budget EV manufacturers exhibit highest price sensitivity, while German luxury OEMs prioritize latency specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese PZT ceramic feedstock relationships that concentrate piezoelectric actuator precursor supply. Geographic supply concentration spans Japan, China, and Germany for precision actuator modules and control-interface electronics. Raw material dependencies include lead zirconate titanate ceramics, rare-earth magnets for electromagnetic variants, and force-sensing resistor substrates. Supply chain risk centers on tariff exposure for ceramic imports into European assembly operations. Distribution runs through Tier 1 system integrators with direct OEM platform engineering relationships, compressing supplier tiers for curved display integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive haptic technology is consolidating around functional-safety certification barriers and piezoelectric feedstock control, with ISO 26262 validation timelines freezing out capital-constrained competitors unable to sustain 18-24 month qualification cycles.
For Market Incumbents: Cement platform standardization advantages by embedding haptic subsystems into long-term OEM architecture contracts before next-generation vehicle platforms finalize. Deepen backward integration into PZT ceramic supply through offtake agreements with Japanese specialty chemical producers to defend margin position against feedstock volatility. Prioritize thermal-feedback R&D convergence to extend differentiation beyond vibration-only competitors.
For New Entrants and Emerging Players: The price-point gap between piezoelectric steering-wheel modules and electromagnetic dashboard alternatives creates white-space entry at the mid-tier actuator tier for Chinese domestic EV manufacturers seeking localized supply. Target aftermarket calibration tools for enthusiast segments in Japan and South Korea where consumer willingness to pay for personalized haptic profiles exceeds OEM factory settings. Pursue direct Tier 2-to-OEM relationships for curved display substrate integration to bypass incumbent Tier 1 gatekeepers.
For Investors and Strategic Acquirers: Re-rating potential sits with piezoelectric specialists possessing captive ceramic feedstock relationships given PZT supply concentration and premium OEM specification pull. Long-term viability favors actors with ISO 26262 validation infrastructure and established KBA type-approval documentation in Germany. Watch NHTSA rulemaking on commercial vehicle tactile-alert mandates as inflection indicator for fleet retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| PZT Ceramic Supply Agreement | Captive feedstock access insulates margins against Japanese and Chinese producer pricing volatility. |
| ISO 26262 Certification Investment | ASIL-D qualification opens safety-critical steering-wheel actuator procurement from German luxury OEMs. |
| Curved Display Integration Partnership | Direct Tier 2-to-OEM relationships compress supplier tiers beneath European dashboard substrate architectures. |
| Thermal-Feedback Module Development | Temperature-variant convergence with vibration actuators unlocks climate-control and wellness cabin applications. |
| Aftermarket Calibration Platform Launch | Configurable intensity profiles capture enthusiast willingness to pay in Japanese and South Korean consumer segments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automotive haptic technology assessment. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations specialists combined with bottom-up validation against vehicle production databases and IHS Markit registration data. Top-down triangulation incorporated EU Vehicle General Safety Regulation implementation timelines and NHTSA distracted-driving guideline development.
Segmentation granularity modeled actuator technology, interface layer, vehicle integration point, and regional production cluster across the projection horizon. CAGRs derived from vehicle platform lifecycle analysis and content-per-vehicle trajectories for electrified architectures. Industry-specific forecast inputs included MIIT intelligent vehicle interface standards and KBA type-approval process documentation requirements.
Inputs from OEM engineering centers and Tier 1 supplier networks were available through the study window; gaps in long-haul trucking retrofit installation rates introduce uncertainty bands around fleet aftermarket projections. Forecasts reflect documented assumptions on EV platform haptic content penetration and regulatory mandate implementation pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market