
 In-Vehicle Connectivity Market | 2026-2036
In-Vehicle Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vehicle Connectivity Market Intelligence
Fleet operators is redrawing the In-Vehicle Connectivity landscape as logistics firms and ride-hailing platforms prioritize real-time vehicle monitoring. Qualcomm Technologies dominates modem silicon for 5G-enabled telematics units. Continental AG anchors embedded software stacks across European OEM programs. NXP Semiconductors specializes in secure V2X chipsets that meet automotive-grade functional safety thresholds.
In-vehicle connectivity denotes the integrated ecosystem of hardware, software, and communication protocols that enable data exchange between vehicles, infrastructure, cloud services, and occupant devices, operating across frequency bands from 2.4 GHz Bluetooth to sub-6 GHz 5G with latency requirements below 10 milliseconds for safety-critical V2X applications. 5G technology leads capital deployment as automakers require ultra-reliable low-latency links for autonomous coordination, while over-the-air updates capture expanding margin pools by converting one-time hardware sales into recurring software revenue streams. Infotainment systems remain the most mature product category with saturated penetration in premium segments.
The U.S. NHTSA mandates V2V communication compatibility for new light vehicles, while the EU's Cyber Resilience Act imposes mandatory security update obligations across the vehicle lifecycle. Japan's METI coordinates 5G spectrum allocation specifically for connected mobility corridors on the Tomei Expressway. Stakeholders must monitor regulatory divergence between jurisdictions as compliance architectures designed for one market face costly recertification elsewhere.
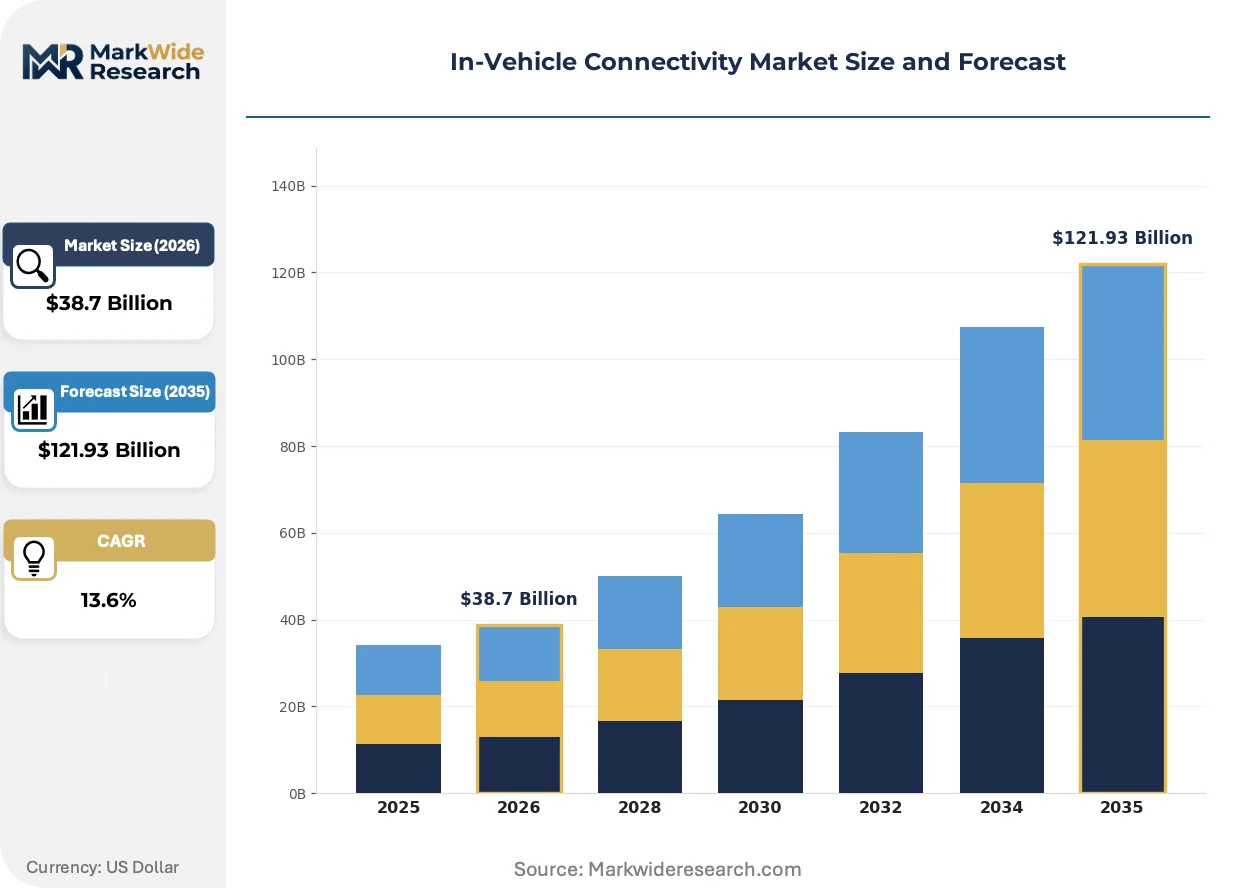
Market Dynamics
Fleet operators are redrawing competitive positioning in In-Vehicle Connectivity as commercial vehicle procurement prioritizes real-time diagnostics over hardware specifications. The EU Cyber Resilience Act is forcing baseline security architecture changes across OEM development cycles.
Growth Catalysts
- 5G spectrum allocation:Japan's METI coordinates dedicated connected mobility corridors on the Tomei Expressway, enabling ultra-reliable low-latency links for truck platooning and autonomous coordination.
- Mandatory V2V compatibility:The US NHTSA mandates vehicle-to-vehicle communication for new light vehicles, creating pull-through demand for compatible modem silicon and antenna systems.
- Logistics digitization:Freight carriers and ride-hailing platforms are embedding connectivity modules as standard equipment to enable predictive maintenance and dynamic route optimization.
Market Restraints
- Semiconductor supply concentration:Automotive-grade modem fabrication concentrates among a limited set of foundry operators, creating vulnerability to capacity constraints and allocation rationing.
- Certification timeline friction:Functional safety validation under ISO 26262 extends development cycles by 18-24 months for V2X chipsets targeting autonomous applications.
- Legacy fleet replacement inertia:Commercial vehicle operators face capital constraints and residual value uncertainty when retrofitting existing assets with connected telematics hardware.
Strategic Opportunities
- Software-defined vehicle architectures:Over-the-air update capabilities are converting one-time hardware sales into recurring revenue streams across infotainment and powertrain management systems.
- German V2X infrastructure:Premium automakers anchor next-generation roadside unit deployment along the A9 digital testbed, creating reference architecture for export markets.
- Edge-cloud convergence:Split computing between vehicle processors and roadside infrastructure is reducing onboard hardware requirements while maintaining sub-10-millisecond latency for safety-critical functions.
Industry Challenges
- Cybersecurity talent scarcity:Embedded systems security engineering expertise remains concentrated among semiconductor vendors and tier-1 suppliers, limiting OEM in-house capability buildout.
- Multi-jurisdiction certification burden:Compliance architectures designed for EU Cyber Resilience Act requirements face costly recertification for US FCC and Japan MIC radio equipment approvals.
- Interoperability standard fragmentation:Competing DSRC and C-V2X protocol camps delay unified roadside infrastructure investment decisions by transportation authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vehicle Connectivity Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $121.93 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth, Wi-Fi, 4G LTE, 5G Product Type: Infotainment Systems, Telematics, V2X Communication, Over-the-Air Updates End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Management Application: Driver Assistance, Entertainment, Navigation, Vehicle Diagnostics |
| Companies Covered | Aptiv PLC, NXP Semiconductors, Robert Bosch GmbH, Qualcomm Technologies, Harman International Industries, Continental AG, ZF Friedrichshafen AG, Intel Corporation, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vehicle Connectivity Market Strategic Shifts & Innovations
Vehicle electronics architecture is decomposing from domain-centralized to zonal compute configurations, redistributing processing loads and connectivity endpoints across the chassis. This structural shift is compressing hardware consolidation timelines and opening new supplier entry points.
Software-defined radio platforms are decomposing traditional fixed-function modem designs into reconfigurable signal processing stacks. Tier-1 suppliers are adopting these platforms to reduce SKU proliferation across regional spectrum allocations. The flexibility is compressing hardware validation cycles while enabling post-deployment protocol updates through firmware revisions.
The EU Cyber Resilience Act imposes mandatory security update obligations across the full vehicle lifecycle, including post-warranty periods. OEMs must now maintain vulnerability response capabilities for 15+ years after initial sale. European premium manufacturers are most affected, restructuring supplier contracts to allocate long-term cybersecurity liability.
Commercial fleet procurement is consolidating vendor relationships around integrated telematics platforms that combine connectivity hardware, cloud analytics, and maintenance scheduling. Logistics operators in Germany and the Netherlands are displacing point-solution providers with multi-year platform contracts. This concentration is visible among long-haul freight carriers prioritizing total cost of ownership over upfront hardware pricing.
In-Vehicle Connectivity Market Segmentation
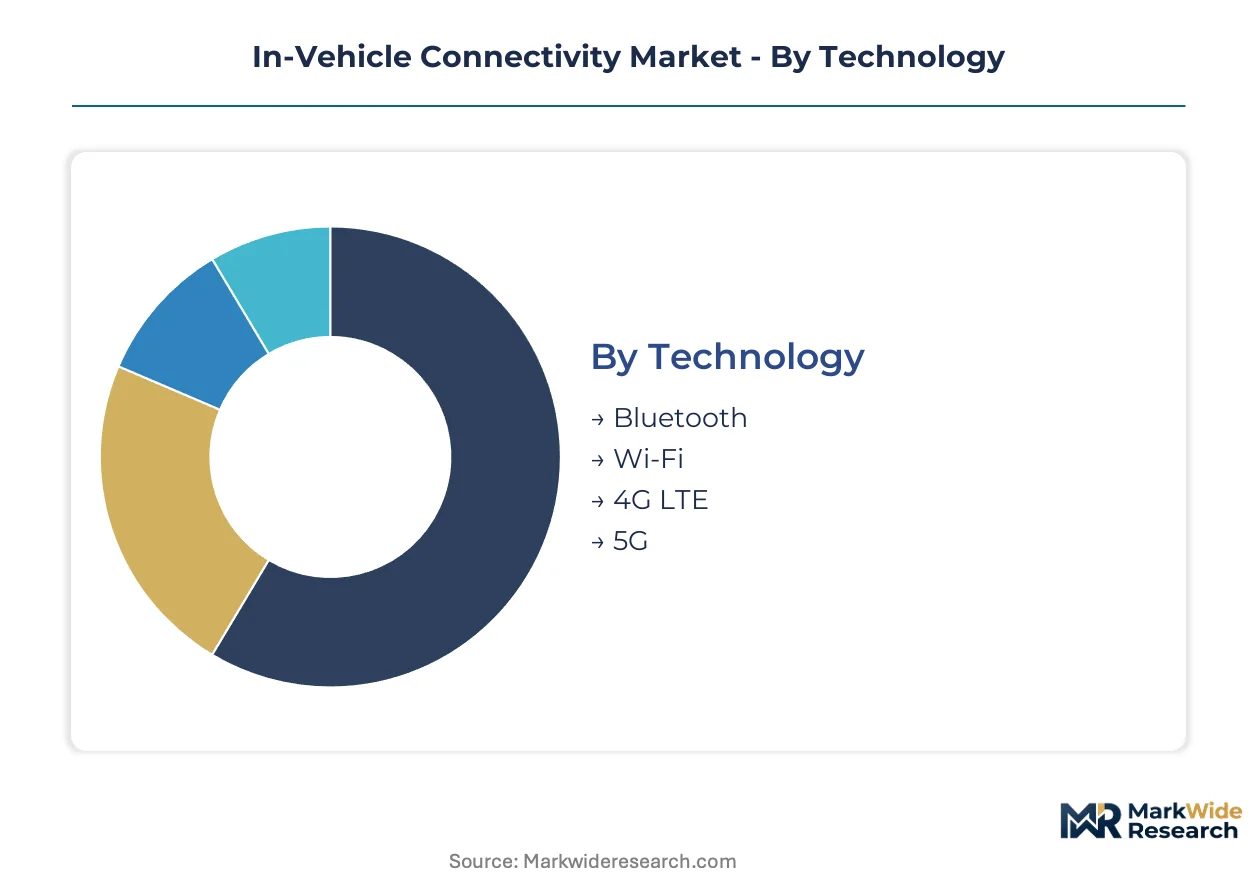
Technology substitution pressures are fragmenting procurement patterns across the In-Vehicle Connectivity landscape as legacy protocols face displacement by next-generation standards. Fleet operators and OEMs now evaluate connectivity investments through total lifecycle cost lenses rather than upfront hardware pricing alone.
Technology:
Bluetooth and Wi-Fi confront the most acute substitution threat as 5G modems absorb short-range connectivity functions into unified cellular platforms.
- Bluetooth:Low-energy protocols enable smartphone pairing and cabin device synchronization at minimal hardware cost. German premium OEMs retain Bluetooth as a fallback layer for occupant device connectivity where cellular handoff creates user friction.
- Wi-Fi:High-throughput local area links support rear-seat entertainment streaming and software update caching. Demand concentrates in North American family vehicle configurations where multiple simultaneous device connections are prioritized.
- 4G LTE:Mature modem silicon dominates current fleet telematics deployments. Commercial vehicle operators in the Netherlands specify LTE as baseline connectivity for route optimization and predictive maintenance.
- 5G:Ultra-reliable low-latency links enable V2X safety messaging and autonomous coordination. Japan's METI-coordinated corridors on the Tomei Expressway anchor early deployment of 5G-enabled truck platooning.
4G LTE retains volume leadership; 5G holds the steepest expansion curve.
Product Type:
Margin structures diverge sharply across this dimension as hardware-centric categories face software-defined displacement.
- Infotainment Systems:Integrated display and audio platforms represent the most mature product category with saturated premium segment penetration. Tier-1 suppliers consolidate around Android Automotive and proprietary OS stacks to reduce fragmentation.
- Telematics:Cellular-enabled data collection modules capture vehicle health and location telemetry. Fleet management platforms in Germany and the Netherlands displace point-solution providers with multi-year integrated contracts.
- V2X Communication:Dedicated short-range and cellular vehicle-to-everything radios enable cooperative safety messaging. The US NHTSA mandate for light vehicle V2V compatibility is accelerating modem silicon procurement.
- Over-the-Air Updates:Software delivery infrastructure converts one-time hardware sales into recurring revenue streams. The EU Cyber Resilience Act mandates update capabilities across the full vehicle lifecycle including post-warranty periods.
Infotainment Systems retain volume leadership; Over-the-Air Updates capture the fastest margin expansion.
End User:
Procurement concentration is shifting toward entities with direct vehicle operating responsibility rather than pure manufacturing players.
- OEMs:Vehicle manufacturers specify connectivity architectures across model lineups. European premium brands anchor zonal compute configurations that redistribute processing loads across the chassis.
- Tier-1 Suppliers:System integrators package modem hardware with embedded software stacks. Continental AG anchors European OEM programs with consolidated telematics platform offerings.
- Aftermarket Providers:Retrofit specialists serve legacy fleet assets with plug-in connectivity hardware. Capital constraints among commercial operators limit addressable volume despite residual value uncertainty.
- Fleet Management:Logistics and ride-hailing platforms procure connectivity as a service layer. Freight carriers prioritize real-time diagnostics and dynamic route optimization over hardware specifications.
OEMs retain volume leadership; Fleet Management is climbing the fastest.
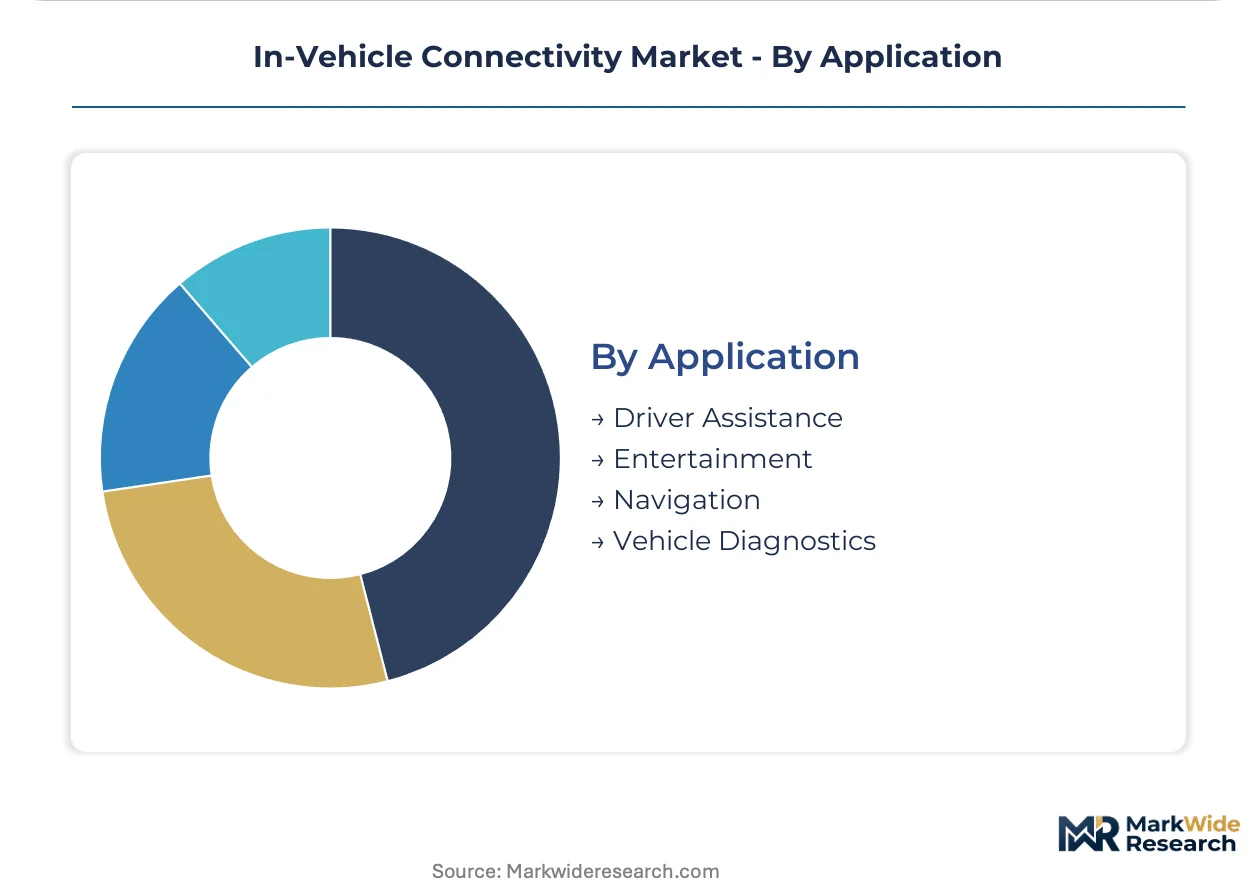
Application:
Functional safety requirements are concentrating investment toward latency-critical use cases while entertainment functions face commoditization pressure.
- Driver Assistance:Sensor fusion and cooperative perception systems demand sub-10-millisecond V2X links. German V2X infrastructure deployment along the A9 digital testbed creates reference architecture for export markets.
- Entertainment:Streaming audio and video delivery represent the most price-sensitive application layer. Saturation in premium segments compresses hardware margins toward mid-economy vehicle tiers.
- Navigation:Cloud-augmented positioning systems reduce onboard map storage requirements. Edge-cloud convergence splits computing between vehicle processors and roadside infrastructure.
- Vehicle Diagnostics:Predictive maintenance algorithms leverage real-time powertrain telemetry. Logistics digitization is embedding diagnostic modules as standard equipment across commercial vehicle procurement.
Entertainment retains volume leadership; Driver Assistance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tomei Expressway's 5G-connected mobility corridors underwrite Japan's central role in validating ultra-reliable low-latency links for commercial vehicle platooning.
United States
NHTSA's V2V mandate for new light vehicles drives modem silicon procurement across Detroit automakers. FCC equipment authorization rules shape radio hardware certification timelines. Michigan's automotive corridor anchors validation programs for connected truck fleets operating on Interstate 75.
Germany
Premium OEMs deploy zonal compute architectures that redistribute connectivity endpoints across vehicle chassis. EU Cyber Resilience Act mandates 15-year security update obligations post-sale. Bavaria's A9 digital testbed serves as reference architecture for V2X roadside unit exports.
Japan
METI coordinates dedicated 5G spectrum allocation for autonomous coordination on freight corridors. National connected mobility programs require sub-10-millisecond latency validation. Nagoya's Chubu region concentrates tier-1 supplier engineering centers for V2X chipset development.
Netherlands
Logistics operators specify LTE-baseline connectivity for predictive maintenance across Rotterdam-European hinterland routes. National freight digitization subsidies accelerate telematics hardware deployment. Eindhoven's high-tech campus anchors embedded software stack development for commercial vehicle platforms.
South Korea
Seoul Capital Area deployment of C-V2X infrastructure enables cooperative perception for urban autonomous shuttles. MFDS radio equipment approvals align with automotive-grade functional safety thresholds. Busan-Ulsan industrial belt concentrates 5G modem foundry capacity for automotive silicon.
In-Vehicle Connectivity Market Key Industry Players
Concentration sits with semiconductor vendors and tier-1 system integrators that control modem silicon supply and embedded software stacks. The vendor base organizes around three archetypes: chip designers with automotive-grade certification, full-stack platform integrators, and specialized V2X radio specialists. Competitive moves center on multi-year fleet management platform contracts and zonal compute architecture partnerships with OEM development programs.
Within the semiconductor tier, Qualcomm Technologies and NXP Semiconductors exemplify divergent specialization vectors—one anchoring 5G modem volume, the other securing V2X functional safety thresholds. Continental AG occupies a position as the reference tier-1 integrator for European OEM telematics programs. These three represent the core competitive anchors around which procurement consolidation is accelerating.
| Leading Market Players |
|---|
| Aptiv PLC |
| NXP Semiconductors |
| Robert Bosch GmbH |
| Qualcomm Technologies |
| Harman International Industries |
| Continental AG |
| ZF Friedrichshafen AG |
| Intel Corporation |
| DENSO Corporation |
| Others |
Cost & Logistics Intelligence
Automotive-grade modem foundry utilization rates above 85 percent in South Korea and Taiwan compress marginal production costs while concentrating pricing power among three dominant silicon vendors. This scale concentration elevates price floors for 5G-enabled telematics modules and creates procurement bottlenecks for fleet operators seeking volume discounts.
Pricing Analysis
Volume-discount tiering structures separate fleet management platforms purchasing 50,000-plus units annually from aftermarket providers ordering sub-thousand quantities. Price differentiation hinges on certification grade—ISO 26262 ASIL-D functional safety thresholds command 40-60 percent premiums over consumer-grade silicon—and geographic delivery cost differentials between Asian foundry output and European final assembly. Cost compression in 4G LTE modem tiers is intensifying because unified 5G platforms absorb legacy connectivity functions, eroding standalone Bluetooth and Wi-Fi module margins. Fleet management platforms exhibit lowest price sensitivity due to total cost of ownership calculations, while aftermarket retrofit specialists face acute margin pressure from hardware commoditization.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose automotive silicon shipments to 14-21 day delivery volatility, forcing tier-1 suppliers to maintain 90-day inventory buffers. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with advanced node capacity for automotive modems resting on TSMC and Samsung Foundry allocations. Raw material dependencies span gallium arsenide substrates, high-purity silicon wafers, and rare-earth elements for antenna ceramics. Single-source vulnerability concentrates in 5G baseband intellectual property held by Qualcomm Technologies and MediaTek. Distribution runs through consolidated tier-1 integrators—Continental AG, Robert Bosch GmbH, Aptiv PLC—who package modem hardware with embedded software stacks for OEM direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-vehicle connectivity is crossing a platform-economics inflection where software-defined radio architectures and over-the-air update infrastructure convert hardware vendors into recurring-revenue service providers. The DSRC-versus-C-V2X protocol fragmentation is forcing ecosystem bets that will determine supplier viability across regulatory jurisdictions.
For Market Incumbents: Compound defensive moats through backward integration into secure element manufacturing and exclusive zonal compute architecture partnerships with German premium OEMs. The EU Cyber Resilience Act's 15-year security update obligations threaten margin structures for vendors lacking long-term cybersecurity liability frameworks. Priority investment in ISO 21434-certified engineering capacity anchors certification tier premiums against commoditization pressure from Chinese modem suppliers. For New Entrants and Emerging Players: Lead with edge-cloud convergence solutions that split computing between vehicle processors and roadside infrastructure, targeting Netherlands-Germany freight corridor deployments where latency requirements below 10 milliseconds remain unmet. The aftermarket retrofit segment for legacy commercial fleets offers most penetrable white space, capitalizing on capital constraints that delay full fleet replacement cycles. Go-to-market positioning as subscription-based "connectivity-as-a-service" bypasses upfront hardware procurement friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor vendors with automotive-grade functional safety certification and established tier-1 supplier relationships over pure-play software entrants. Long-term viability across the 5G transition window hinges on V2X chipset roadmaps aligned with NHTSA and EU regulatory trajectories. Acquisition target archetype: specialized V2X radio specialists with DSRC-C-V2X dual-mode silicon and existing A9 digital testbed validation. Signal to watch: METI spectrum allocation decisions for 6 GHz connected mobility corridors as indicator of Japan's protocol standard commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Over-the-air update capabilities convert Continental AG's hardware sales into recurring revenue streams. |
| Battery Supply Agreement | Electric fleet electrification raises telematics content per vehicle for real-time powertrain monitoring. |
| Platform Standardization | Android Automotive consolidation reduces Harman International's OS fragmentation costs across OEM programs. |
| Charging Infrastructure Partnership | Grid-vehicle integration protocols create data revenue opportunities for NXP Semiconductors' V2X chipsets. |
| Geographic Manufacturing Footprint | Qualcomm Technologies' Nagoya engineering center anchors METI-coordinated 5G corridor validation. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with automotive connectivity stakeholders and systematic secondary validation across regulatory and production databases. Primary fieldwork encompassed OEM platform engineers at German premium manufacturers, tier-1 supplier procurement directors, fleet management operators in Rotterdam-Antwerp logistics corridors, and semiconductor vendor automotive business unit heads. Secondary sources included NHTSA Federal Motor Vehicle Safety Standards filings, EU Cyber Resilience Act implementation guidance, METI connected mobility program disclosures, IHS Markit vehicle production databases, and SEC 10-K automotive segment disclosures. Bottom-up unit shipment estimates triangulated against top-down OEM connectivity content per vehicle projections.
Across the analysis window, forecasts model technology substitution dynamics, regulatory mandate phase-in schedules, and fleet operator procurement cycle timing. Segmentation dimensions span connectivity protocol generation, product type hierarchy, end-user procurement archetype, and application functional safety criticality. CAGRs derive from logistic diffusion curves fitted to 5G modem adoption patterns and V2X infrastructure deployment timelines. Industry-specific inputs incorporate automotive-grade silicon foundry capacity expansion announcements and EU-US-Japan regulatory divergence scenarios.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor capacity investment, coordinated transatlantic V2X standard convergence, or stable commercial vehicle replacement cycles would require recalibration. Forecasts reflect documented assumptions regarding 5G spectrum allocation timing and fleet operator digitization budget trajectories. Specific risk factors include foundry allocation rationing during consumer electronics demand surges and recertification cost inflation from EU-US regulatory divergence. Practitioners should keep alternative scenarios live as DSRC-C-V2X protocol resolution and Cyber Resilience Act enforcement precedents evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
North America Automotive Camera Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Automotive AR HUD Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Digital Tachograph System Market