
 Virtual Reality in Automotive Market | 2026-2036
Virtual Reality in Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality in Automotive Market Intelligence
Photorealistic rendering capability is unwinding the traditional reliance on physical clay models in automotive design studios. Varjo specializes in high-resolution headsets tailored for industrial design and simulation. Unity Technologies provides the foundational software engine for many automotive VR applications. Automakers like BMW leverage these tools to accelerate vehicle development cycles and enhance driver training programs.
Virtual reality in automotive involves using immersive, computer-generated environments to simulate physical presence for design, testing, and marketing. These systems integrate high-fidelity visual simulation with technologies like haptic feedback gloves and sub-millimeter motion tracking to create realistic interactions. The design prototyping application currently commands the largest share, driven by OEM efforts to reduce development timelines. Among end users, direct adoption by OEMs is outpacing that of Tier-1 suppliers, who often use VR for component validation.
Data privacy regulations, such as Europe's GDPR, govern the collection of user data in in-car VR entertainment systems developed by companies like holoride GmbH. Concurrently, bodies like the US NHTSA influence standards for VR-based driver training simulators to ensure they accurately reflect real-world vehicle dynamics. Stakeholder decisions will center on balancing investment in proprietary, high-fidelity platforms against adopting open, interoperable standards for broader ecosystem collaboration.
Market Dynamics
The central force shaping the market is the automotive industry's aggressive push to digitize the entire vehicle development process. This shift from physical to virtual validation is driven by intense pressure on original equipment manufacturers to shorten product cycles and reduce development costs.
Growth Catalysts
- 5G Network Expansion:The rollout of 5G infrastructure enables low-latency, high-bandwidth connectivity, which is critical for supporting complex, cloud-streamed vehicle simulations and collaborative virtual reality design reviews across geographically dispersed teams.
- OEM Cost Reduction Mandates:Automakers are systemically adopting VR for design prototyping to slash the substantial costs and time associated with building and iterating on multiple physical clay models and prototypes.
- Engineering Cluster Concentration:Demand is heavily concentrated in established automotive engineering hubs, particularly within Germany and Japan, where major automakers are making significant capital investments in virtual development centers and talent.
Market Restraints
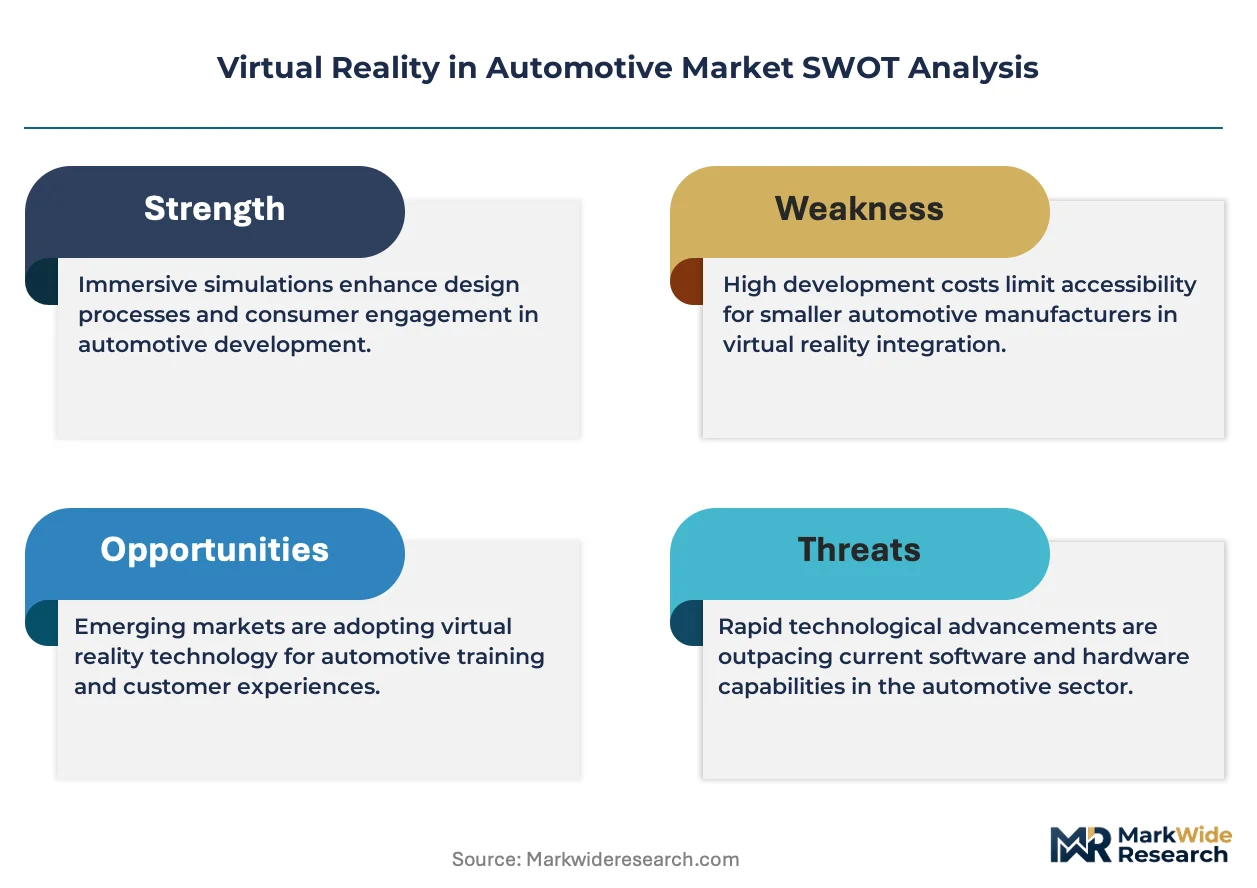
- High Initial Capital Outlay:The acquisition cost for enterprise-grade VR systems, including high-resolution headsets, powerful workstations, and specialized software licenses, presents a significant investment barrier, especially for smaller Tier-1 suppliers.
- Technical Performance Bottlenecks:Achieving fully photorealistic, real-time rendering in multi-user, collaborative environments without perceptible latency remains a significant technical hurdle that can limit the sense of immersion and user comfort.
- Data Security and Privacy:The collection of user interaction and biometric data within VR training or entertainment systems is subject to stringent regulations like Europe's GDPR, complicating system design and data management protocols.
Strategic Opportunities
- Aftermarket Service and Training:There is a significant opportunity to develop VR applications for training automotive technicians on complex repair procedures for electric and autonomous vehicles, reducing the need for physical training hardware. *Haptic Technology Integration: Incorporating advanced haptic feedback gloves and controls can create more realistic tactile sensations for virtual prototyping, allowing designers and engineers to evaluate interior textures, switchgear, and ergonomics with greater fidelity.
- Autonomous Vehicle Simulation:Expanding VR platforms to create vast, realistic virtual worlds for testing and validating autonomous driving algorithms offers a scalable and safe alternative to logging millions of miles in physical test vehicles.
Industry Challenges
- Specialized Talent Shortage:A persistent challenge is the scarcity of professionals who possess a hybrid skillset combining deep automotive engineering knowledge with expertise in real-time 3D development engines and virtual reality systems.
- Interoperability and Standards:The lack of common data formats and interoperability standards between different CAD, PLM, and VR software ecosystems creates data silos and workflow inefficiencies for automotive companies using multi-vendor solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality in Automotive Market |
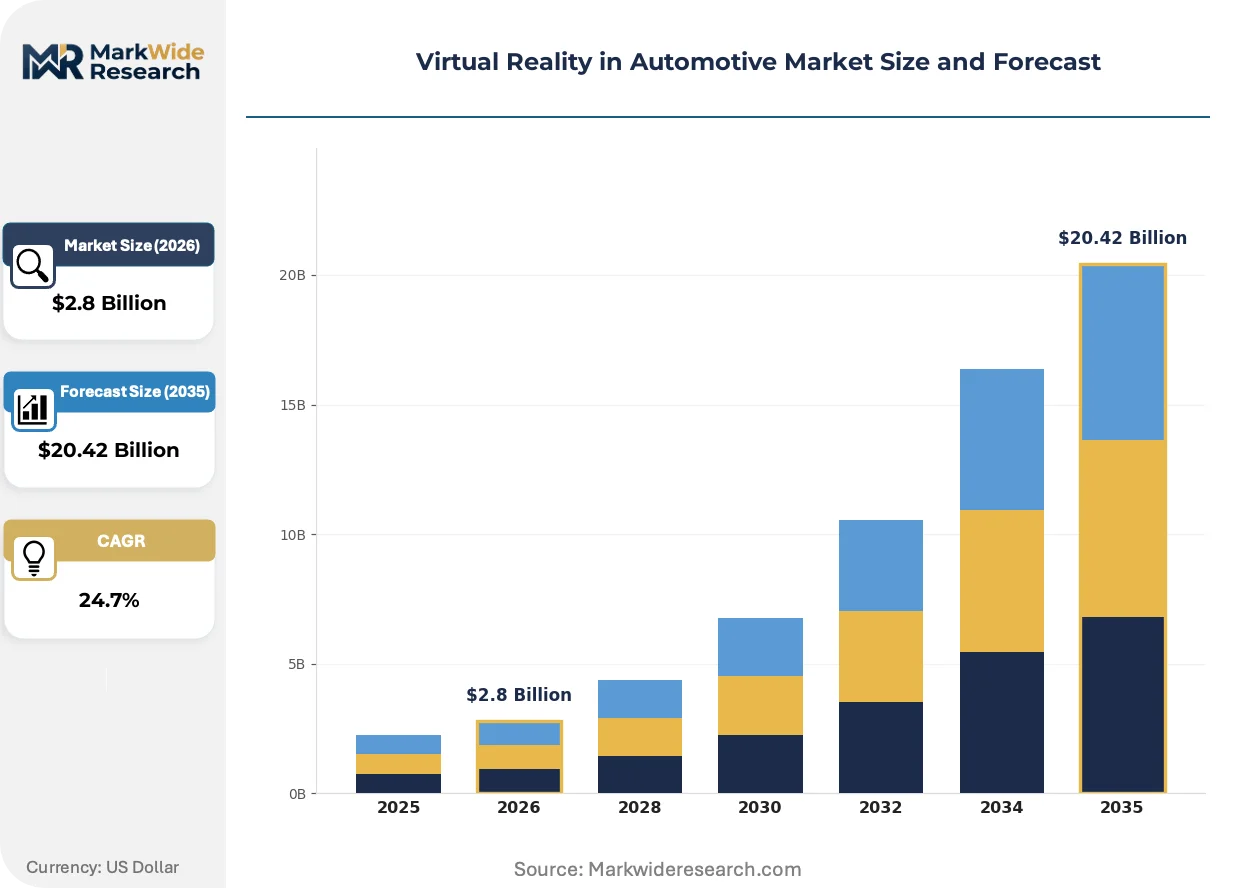
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: VR Headsets, Haptic Feedback, Motion Tracking, Visual Simulation Application: Design Prototyping, Vehicle Simulation, Driver Training, Marketing Demonstrations End User: OEMs, Tier-1 Suppliers, Research Institutions, Marketing Agencies Deployment: On-premise, Cloud-based, Hybrid Solutions, Integrated Systems |
| Companies Covered | holoride GmbH, Varjo, Audi, Meta, AutoVRse, BMW, Takeaway Reality, Unity Technologies, Toyota, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality in Automotive Market Strategic Shifts & Innovations
The convergence of real-time rendering, cloud computing, and haptic feedback is transforming virtual reality from a niche visualization tool into an integrated platform for automotive design, engineering, and training. This evolution is enabling more complex, collaborative, and physically accurate simulations.
Photorealistic, real-time ray tracing technology renders virtual vehicle models with lifelike material finishes, lighting, and reflections. Automotive design studios are rapidly adopting this capability for virtual design reviews, allowing for high-fidelity evaluation of aesthetics and perceived quality. This level of digital accuracy is supplanting the industry's long-standing reliance on physical clay models for early-stage design validation and decision-making.
Regulations governing autonomous vehicle development, such as guidance from the US NHTSA on simulation-based testing, are creating demand for verifiable virtual environments. This pressure requires simulation platforms to accurately model sensor physics and complex traffic scenarios to be considered valid for safety case arguments. Consequently, autonomous systems developers are prioritizing investment in VR platforms that offer certifiable, physics-based simulation engines to validate their software stacks.
A notable behavioral shift is the move away from perpetual software licenses toward flexible, subscription-based models for accessing VR applications. This change disrupts the traditional enterprise software sales cycle, favoring SaaS providers who can offer scalable access to simulation tools. This trend is most pronounced among engineering service firms and Tier-1 suppliers in Europe seeking to align software expenditures with project-based workloads and avoid large upfront capital costs.
Virtual Reality in Automotive Market Segmentation
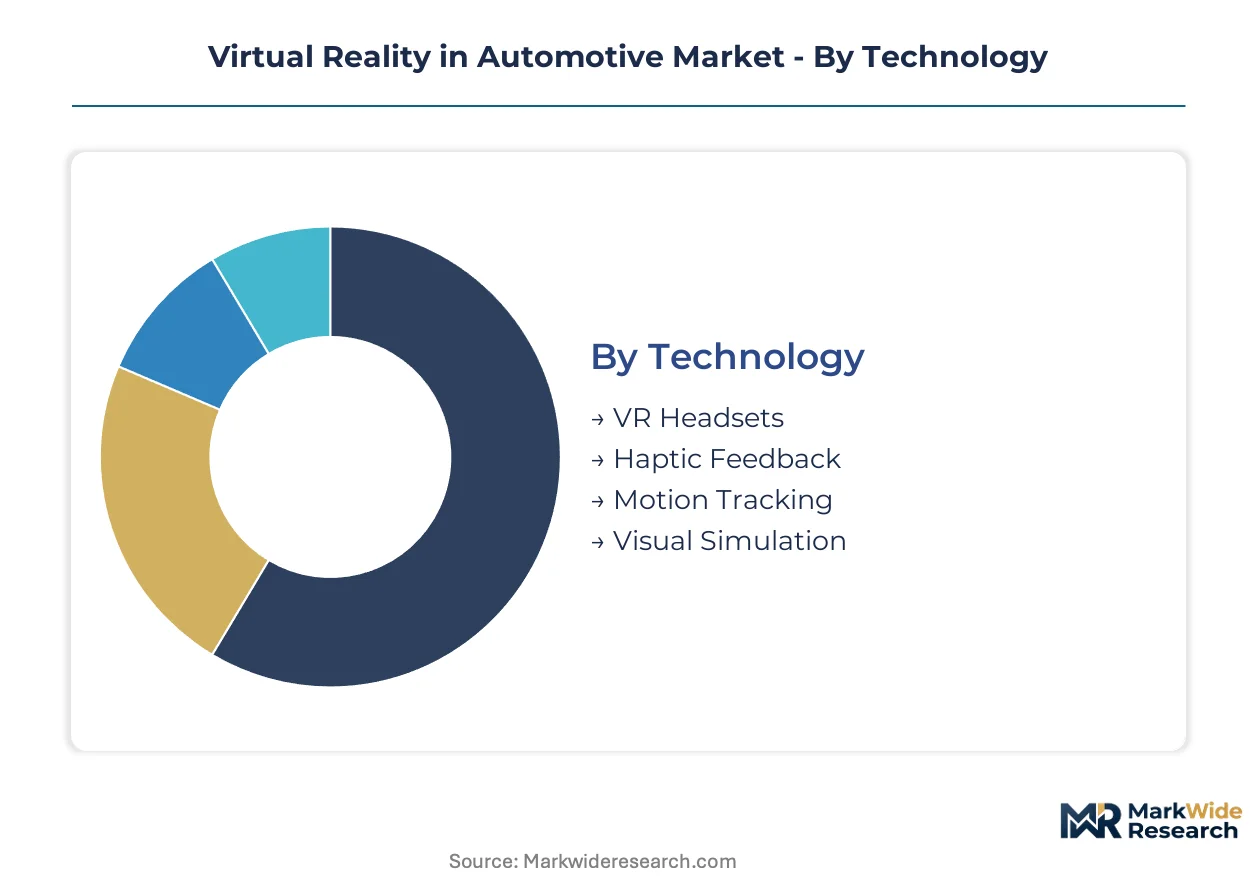
The segmentation of the Virtual Reality in Automotive Market provides a granular view of where technological advancements and user adoption are concentrated. This detailed breakdown helps stakeholders understand the specific components, applications, and customer groups driving market expansion and innovation within the automotive sector.
Technology:
Regulatory bodies influence the adoption of specific VR technologies by setting standards for simulation fidelity and data handling. For example, the US NHTSA's guidance on simulation-based testing impacts the requirements for visual simulation accuracy.
- VR Headsets:These devices provide immersive visual experiences for users, often featuring high-resolution displays and wide fields of view crucial for industrial design and simulation. Demand concentrates in Germany, where major automakers require precise visual fidelity for virtual design reviews and prototyping.
- Visual Simulation:Advanced real-time rendering engines generate photorealistic virtual environments that replicate vehicle aesthetics, material properties, and physical behavior. Automakers in Japan leverage these systems for extensive validation of new ADAS features and complex autonomous driving scenarios.
- Haptic Feedback:Tactile gloves and devices replicate physical sensations, allowing users to interact with virtual objects and perceive textures or resistance.
- Motion Tracking:Sub-millimeter tracking systems capture user movement, enabling natural and intuitive interaction within virtual spaces for design and training.
Established volume favors VR Headsets; emerging adoption favors Visual Simulation.
Application:
Market volume dictates the strategic investment in specific VR applications, with high-volume use cases attracting significant capital. OEMs prioritize applications that directly impact product development timelines and cost efficiency.
- Design Prototyping:Immersive VR environments allow engineers to evaluate vehicle aesthetics, ergonomics, and material finishes with high fidelity before physical models are constructed. OEMs in Germany extensively utilize this application to accelerate design iterations and significantly reduce development costs.
- Vehicle Simulation:Physics-based virtual models enable the testing of vehicle dynamics, safety systems, and autonomous driving algorithms in controlled, repeatable environments. Japanese automakers heavily invest in these simulations for rigorous validation of new ADAS features and autonomous system performance.
- Driver Training:VR systems simulate diverse driving scenarios, providing realistic and safe environments for training new drivers or specialized vehicle operators.
- Marketing Demonstrations:Interactive virtual experiences showcase new vehicle features, interior designs, and customization options to potential customers in a compelling manner.
The largest share of investment goes to Design Prototyping; Vehicle Simulation is expanding most quickly.
End User:
Customer type influences the specific VR solutions procured, with direct OEM adoption outpacing other segments due to their extensive development needs. Each end-user group has distinct requirements for fidelity, scale, and integration.
- OEMs:Automotive manufacturers directly integrate VR tools into their entire product development lifecycle, from conceptual design to virtual assembly and final validation. OEMs in Germany are significant investors in proprietary VR platforms, leveraging them for critical design, engineering, and simulation tasks.
- Tier-1 Suppliers:Component manufacturers utilize VR for validating parts, ensuring precise fit, form, and function within virtual vehicle assemblies and collaborating with OEM partners. Japanese Tier-1 suppliers adopt VR for efficient component design and integration verification.
- Research Institutions:Academic and private research bodies explore new VR applications, develop advanced simulation techniques, and contribute to the technological evolution of the automotive sector.
- Marketing Agencies:These firms employ VR for creating engaging virtual showrooms, interactive product configurators, and immersive promotional content for new vehicle launches.
OEMs represent the largest end-user segment; Tier-1 Suppliers are steadily increasing their VR adoption.
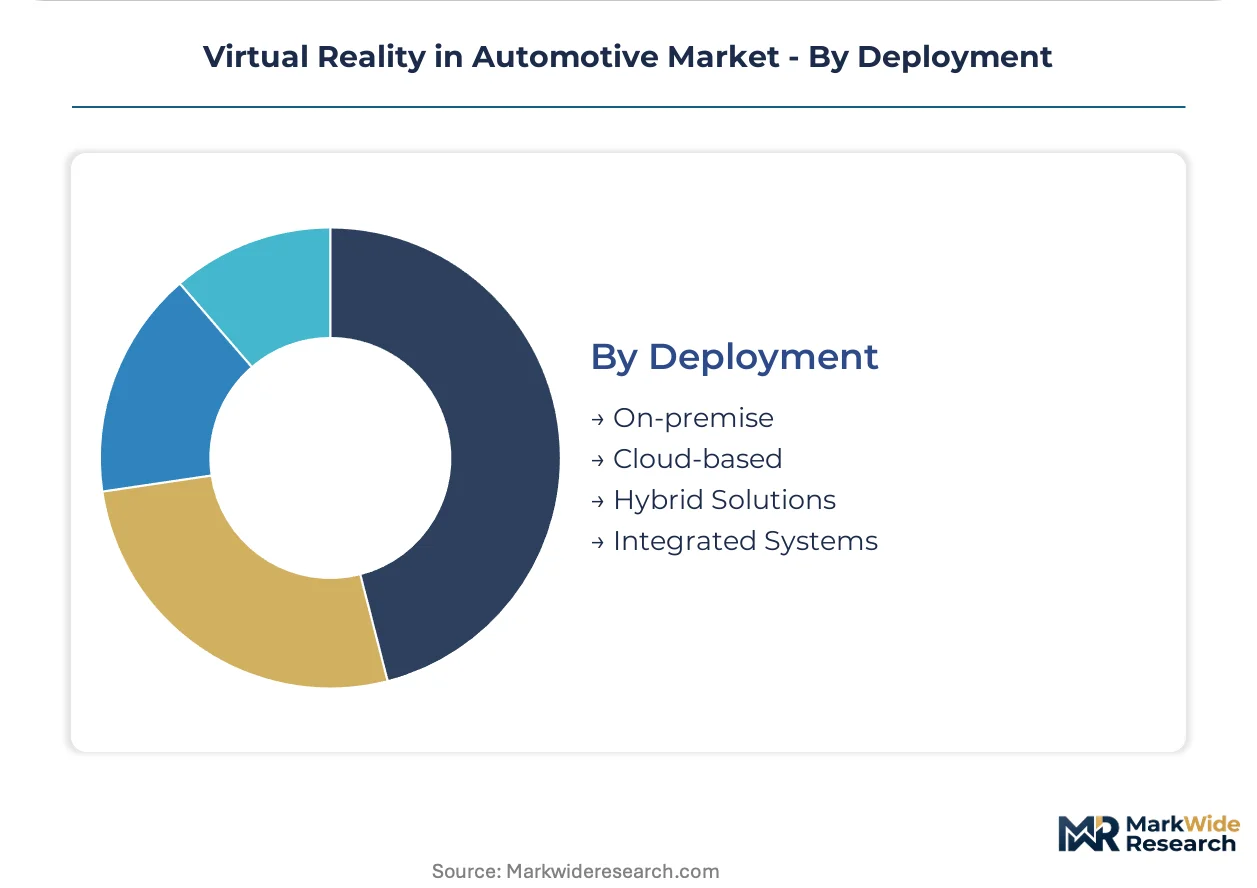
Deployment:
Market maturity influences deployment choices, with newer, more flexible solutions gaining traction over traditional setups. Cloud-based and integrated systems represent different stages of technological evolution and adoption patterns.
- Cloud-based:These solutions stream complex VR applications and simulations from remote servers, enabling collaborative work across geographically dispersed teams with scalable resources. Adoption is expanding among European engineering service firms for flexible access to high-performance VR tools without large upfront capital outlays.
- Integrated Systems:Custom-built VR environments combine specialized hardware and software for specific, high-fidelity automotive applications, often housed within dedicated VR centers. Major OEMs in Germany invest in these comprehensive systems for their most critical design and simulation requirements.
- On-premise:VR hardware and software are installed and managed locally within a company's facilities, offering maximum control over data and performance.
- Hybrid Solutions:These setups combine local processing capabilities with cloud resources, providing a flexible approach to workload management and data storage.
On-premise deployments are well-established; Cloud-based solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan's automotive OEMs drive demand for VR solutions, which often originate from global technology providers. This market concentration reflects significant investments in virtual development environments by major automakers. Specific regulatory frameworks and established engineering clusters further shape regional adoption patterns and technological priorities.
Germany
German automotive manufacturers aggressively deploy VR for design prototyping, significantly reducing reliance on physical clay models. Europe's GDPR influences the design of in-car VR entertainment systems, ensuring robust data privacy protocols. Major automotive hubs like Stuttgart and Munich are central to developing and integrating high-fidelity VR solutions within OEM workflows.
Japan
Japanese automakers heavily invest in visual simulation for validating ADAS features and complex autonomous driving scenarios. METI guidance supports the development of advanced industrial VR applications. Engineering clusters in regions such as Nagoya are focusing on physics-based virtual models for rigorous vehicle dynamics testing.
United States
Demand in the United States stems from the need for realistic VR-based driver training simulators and extensive autonomous vehicle testing. The US NHTSA influences standards for these simulators, ensuring they accurately reflect real-world vehicle dynamics. Detroit's automotive industry and Silicon Valley's technology sector collaborate on developing advanced VR platforms.
China
China's rapidly expanding automotive market, particularly in electric vehicles, fuels the adoption of VR for accelerating design and engineering processes. MIIT policies encourage digital transformation within the automotive sector, including the use of advanced simulation tools. Major automotive production centers like Shanghai are integrating VR into their design and manufacturing pipelines.
Virtual Reality in Automotive Market Key Industry Players
Listed leaders compete with private specialists across the VR hardware and software ecosystem. The market exhibits a tiered structure, with established technology giants offering broad platforms and specialized firms focusing on high-fidelity industrial solutions. Key strategic archetypes include foundational software developers, high-resolution hardware manufacturers, and specialized content providers. Strategic partnerships between hardware and software firms, alongside technology licensing, represent dominant competitive moves.
Specialists in industrial VR hardware, such as Varjo, provide high-resolution headsets tailored for professional design and simulation. Foundational software providers like Unity Technologies offer the underlying engines for numerous automotive VR applications. Meanwhile, holoride GmbH focuses on developing in-car VR entertainment systems, navigating specific data privacy regulations like Europe's GDPR.
| Leading Market Players |
|---|
| holoride GmbH |
| Varjo |
| Audi |
| Meta |
| AutoVRse |
| BMW |
| Takeaway Reality |
| Unity Technologies |
| Toyota |
| Others |
Cost & Logistics Intelligence
The shift from physical clay models to virtual design prototypes reshapes automotive supply chains by centralizing development in software-driven tech hubs, significantly altering traditional manufacturing cost structures. This substitution dynamic drives down overall development costs for original equipment manufacturers.
Pricing Analysis
The pricing gap between current-generation and next-generation VR hardware drives market dynamics, with high-fidelity visual simulation tools commanding premium rates. Subscription-based models dominate software licensing, while project-based pricing applies to custom VR environment development. Price differentiation stems from high-resolution fidelity and customization for OEM-specific workflows. Pricing pressure on enterprise-grade hardware exists, yet specialized software commands premium pricing due to ongoing R&D, with Tier-1 suppliers exhibiting greater price sensitivity than OEMs.
Supply Chain Analysis
Just-in-time inventory strategies are less critical for VR software, which relies on digital distribution, though hardware components require careful management. Geographic supply concentration for advanced VR hardware and software components centers on technology hubs in the United States, alongside automotive clusters in Germany and Japan. The supply chain draws from specialized manufacturers of high-resolution displays, optical components, and powerful GPUs. Single-source vulnerability for these specialized hardware components presents a structural risk, with technology providers distributing solutions directly to OEMs and through engineering service firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Virtual Reality in Automotive Market presents a significant fragmentation opportunity, as the shift toward software-defined vehicles creates specialized niches for VR-based simulation and validation tools. This demand-side shift allows for targeted solutions addressing specific engineering challenges.
For Market Incumbents: Consolidate core VR platform capabilities, focusing on seamless integration with existing CAD and PLM systems. Invest in proprietary high-fidelity platforms to counter technical performance bottlenecks that limit user immersion. Acquire specialized content providers to expand application-specific libraries for design prototyping. Prioritize R&D in real-time rendering to maintain a technological edge against emerging competitors.
For New Entrants and Emerging Players: Specialized aftermarket service training represents a significant service-layer gap where incumbents under-serve the market. Target Tier-1 suppliers seeking cost-effective VR solutions for component validation and integration verification. Develop niche applications for autonomous vehicle simulation, focusing on specific sensor physics or complex traffic scenarios. A go-to-market angle leveraging flexible subscription-based SaaS models can lower initial capital outlay for smaller firms.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized technology providers with strong intellectual property in high-fidelity simulation. Long-term viability remains high, driven by the automotive industry's aggressive digitization push. Target mid-cap specialists with proven expertise in haptic feedback integration or certifiable physics-based simulation engines. Adoption rates of cloud-based VR solutions by engineering service firms serve as a critical signal for broader market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | This initiative streamlines data exchange between CAD, PLM, and VR systems for German OEMs. |
| Software-Defined Vehicle Integration | This move embeds VR tools directly into the development lifecycle for Japanese automakers. |
| Haptic Feedback R&D | Advancements in haptic technology enhance realism for design prototyping applications. |
| Cloud-Based Simulation Expansion | This expands access to high-performance VR tools for European engineering service firms. |
| Autonomous Vehicle Testing Ecosystems | Verifiable virtual environments support US NHTSA guidance for autonomous driving validation. |
Research Approach
A spread of perspectives from OEM platform engineers, Tier-1 R&D directors, VR software developers, and automotive design studio leads converged on the working assumptions. Primary interviews with these stakeholders were validated against extensive secondary research, including automotive industry reports, technology firm SEC filings, and academic papers. This approach ensured robust bottom-up and top-down triangulation of market data.
The forecast framework modeled segmentation dimensions including technology, application, end user, deployment, vehicle class, and OEM tier across the analysis window. Compound annual growth rates were derived from historical data analysis and projected market expansion scenarios. The framework incorporated inputs like OEM investment cycles in virtual development and the global rollout pace of 5G networks.
Underlying assumptions cover established technological trajectories and OEM investment patterns, with deviation risk concentrated in autonomous vehicle regulations and hardware innovation. Forecasts reflect these assumptions; major shifts could alter projections. Revision becomes warranted when these conditions cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Germany Automotive Camera Market