
 Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market | 2026-2036
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market Insights
A shift from single-source to multi-source contracting is restructuring how tier-one suppliers qualify second-tier harness providers. Safran S.A. leverages its vertically integrated aerostructures division to captive-produce engine-zone harnesses for LEAP and CFM56 programs. TE Connectivity sustains broad certification across AS9100 and NADCAP standards, anchoring its position on Boeing and Airbus platforms. GKN Aerospace Services Limited competes through specialized thermoplastic composite conduits that reduce weight in high-temperature nacelle zones.
Aircraft engine electrical wiring harnesses and cable assemblies are bundled conductor systems, typically employing silver-plated copper conductors with PTFE or polyimide insulation rated from minus 65 degrees Celsius to 260 degrees Celsius, organized into looms with integrated connectors and strain relief to distribute power and signals across turbine, accessory, and control modules. Wire harness products dominate current procurement volumes given their ubiquity across thrust control and fuel management channels, while fiber optic cabling segments capture expanding shares in engine monitoring applications requiring immunity from electromagnetic interference. Shielded wiring technology maintains the largest installed base, though Teflon insulation formulations are gaining preference as OEMs push thermal performance thresholds higher.
FAA Part 25 flammability standards, EASA CS-25 certification requirements, and ISO 6722 automotive-derived test protocols collectively govern material selection, fire propagation resistance, and electrical continuity under vibration for engine-mounted harnesses. These frameworks compel manufacturers to maintain dual-certified production lines and traceable lot records, raising barriers for uncertified entrants. Stakeholders must monitor evolving sustainable aviation fuel compatibility requirements that may introduce new chemical exposure conditions for insulation systems.
Market Dynamics
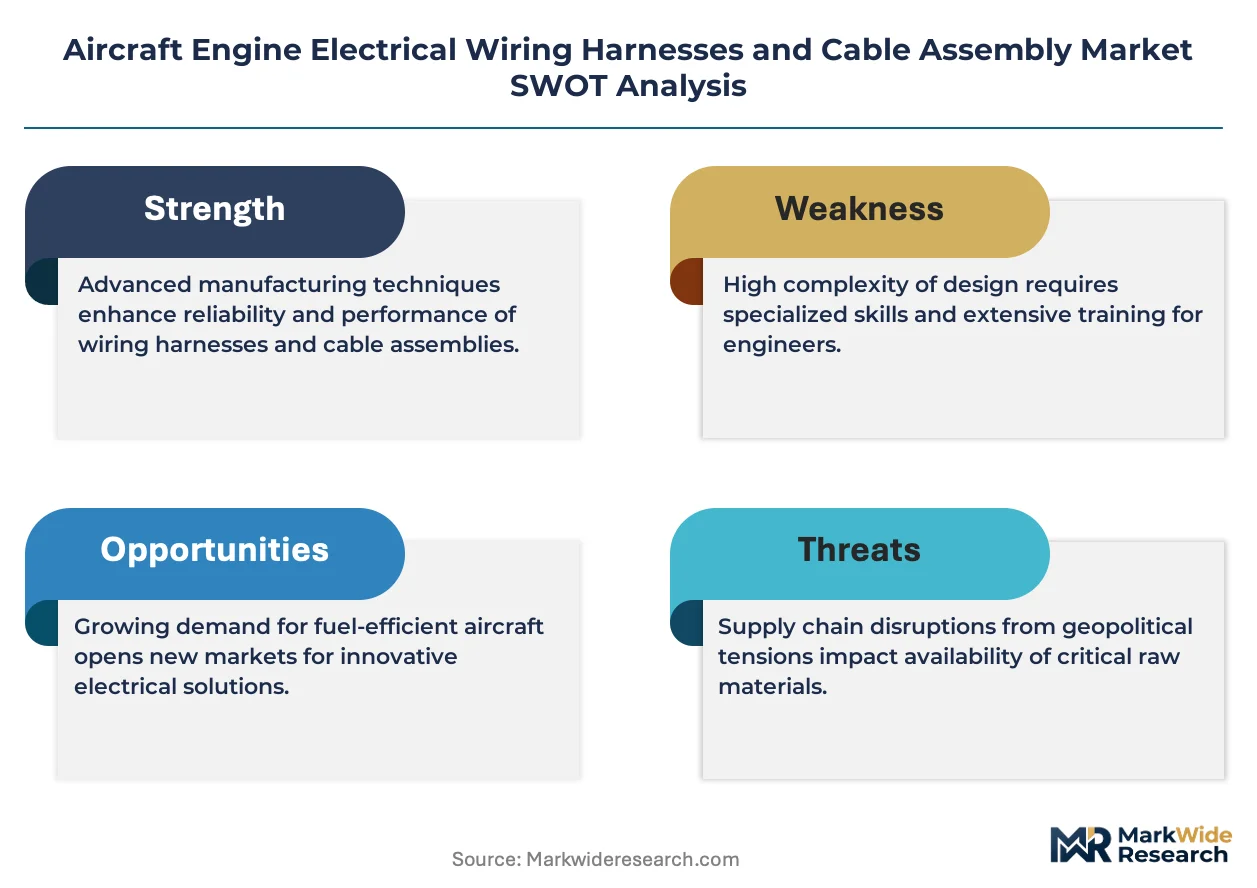
Multi-source contracting mandates from Boeing and Airbus are dismantling single-source harness relationships, forcing tier-one suppliers to requalify second-tier providers under compressed timelines while maintaining FAA and EASA dual certification.
Growth Catalysts
- Next-generation turbofan procurement:Commercial aircraft OEMs are expanding orders for advanced harness systems designed for high-bypass engines, pulling demand through three-tier supplier networks.
- FAA Part 25 flammability enforcement:Tightened fire-resistant wiring standards are accelerating material upgrades across existing engine fleets, creating retrofit pull-through for PTFE and polyimide insulation systems.
- China's domestic final assembly expansion:COMAC C919 and future wide-body programs are localizing harness sourcing requirements, building captive supply chains around Shanghai and Tianjin production clusters.
Market Restraints
- Silver-plated copper input volatility:Precious metal price swings compress margin predictability for harness manufacturers locked into long-term OEM supply agreements.
- Dual-certified production line requirements:FAA and EASA traceability mandates force redundant quality systems, raising fixed costs for uncertified entrants.
- Qualified supplier concentration in France and the United States:Geographic clustering of AS9100-certified harness specialists limits buyer leverage during capacity crunches.
Strategic Opportunities
- India's emerging MRO infrastructure:Maintenance, repair, and overhaul hubs in Bengaluru and Hyderabad are developing engine-zone harness refurbishment capabilities for regional narrow-body fleets.
- Sustainable aviation fuel compatibility testing:New chemical exposure protocols for insulation systems under development by ASTM and SAE committees will favor early-moving material suppliers.
- Fiber optic convergence with sensor networks:Engine health monitoring applications requiring electromagnetic immunity are opening design-in opportunities for hybrid copper-fiber harness architectures.
Industry Challenges
- AS9100 and NADCAP auditor scarcity:Certification backlog delays supplier qualification timelines, constraining OEM multi-sourcing timelines.
- Legacy platform documentation gaps:Aging CFM56 and V2500 harness drawings lack digital thread compatibility, complicating reverse engineering for replacement parts.
- Cross-platform connector standardization deadlock:Proprietary interface designs between engine OEMs prevent modular harness reuse across programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market |
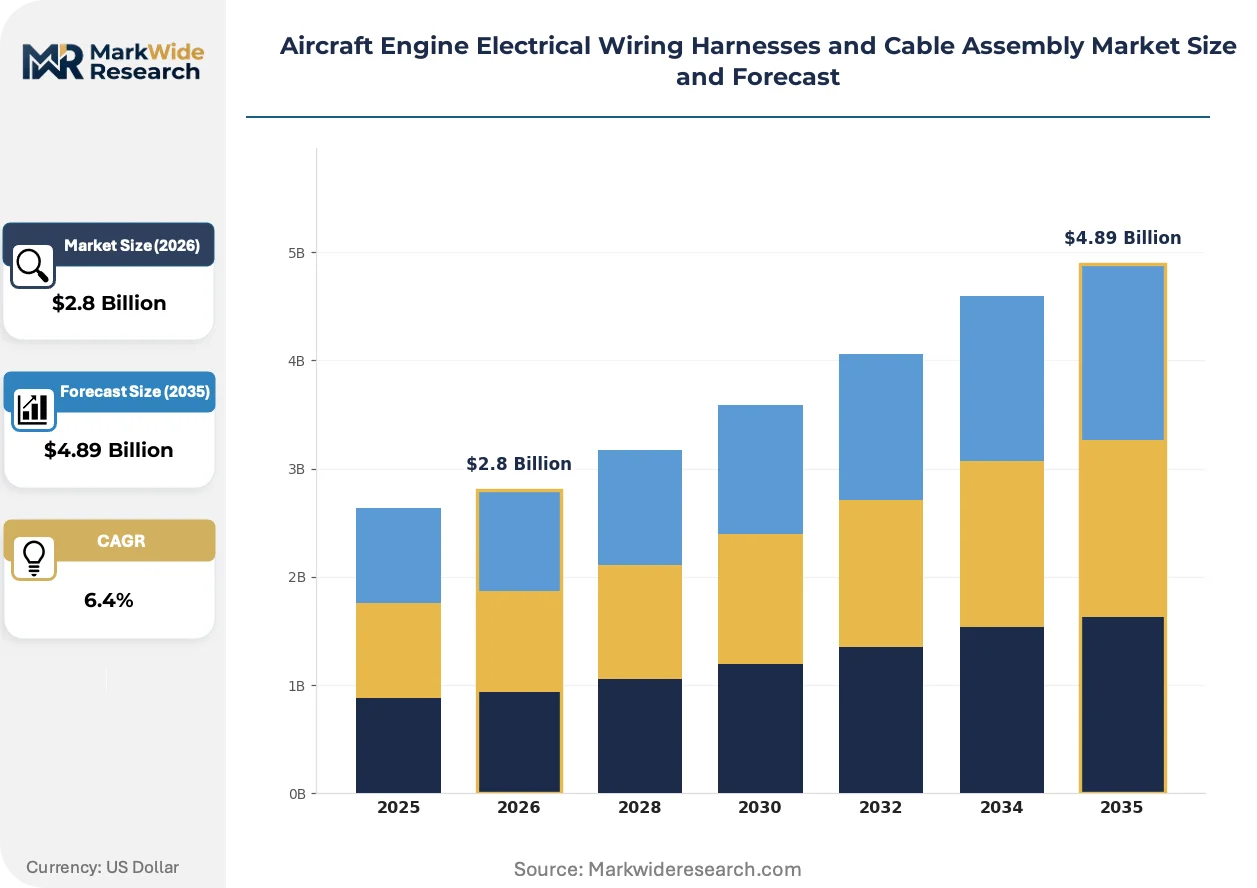
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Harness, Cable Assembly, Circuit Breaker, Connectors, Terminal Blocks Technology: Shielded Wiring, Fiber Optic Cabling, Coaxial Cable, Ribbon Cable, Teflon Insulation Application: Thrust Control Systems, Fuel Management, Flight Control Systems, Avionics Power Supply, Engine Monitoring End User: Commercial Aircraft OEMs, Maintenance, Repair & Overhaul Providers, Defense Sector, Business Jet Manufacturers |
| Companies Covered | Amphenol Corporation, Yazaki Corporation, Safran S.A., Latecoere S.A., AMETEK Inc., Collins Aerospace, GKN Aerospace Services Limited, Glenair Inc., TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market Trends and Innovations
Material science advances and regulatory pressure on thermal performance are compressing development cycles for engine-zone harness architectures, while procurement models favor suppliers with integrated design-to-certification capabilities.
Thermoplastic composite conduits are replacing traditional metal braid shielding in high-temperature nacelle zones, cutting weight while maintaining electromagnetic protection. GKN Aerospace and specialized tier-two suppliers are qualifying these systems for LEAP-1A and PW1100G applications. Fiber-reinforced polymer conduit technology is expanding into wider temperature envelope applications as OEMs push for incremental fuel burn reductions.
EASA CS-25 certification amendments on fire propagation resistance are forcing insulation reformulation across European supply chains, with particular impact on harnesses routed through pylon and core engine compartments. Manufacturers must resubmit qualification data under revised test protocols, compressing product lifecycles for incumbent material specifications. French and German harness specialists are accelerating polyimide-PTFE hybrid development to preempt regulatory obsolescence.
Airline technical procurement teams are unbundling aftermarket harness contracts from engine OEM power-by-the-hour agreements, creating direct sourcing relationships with TE Connectivity and specialized harness houses. This disintermediation is most advanced among low-cost carriers in the United States and Southeast Asia with centralized fleet engineering functions. Direct procurement is compressing channel margins while demanding faster turnaround on custom harness configurations.
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market Segmentation
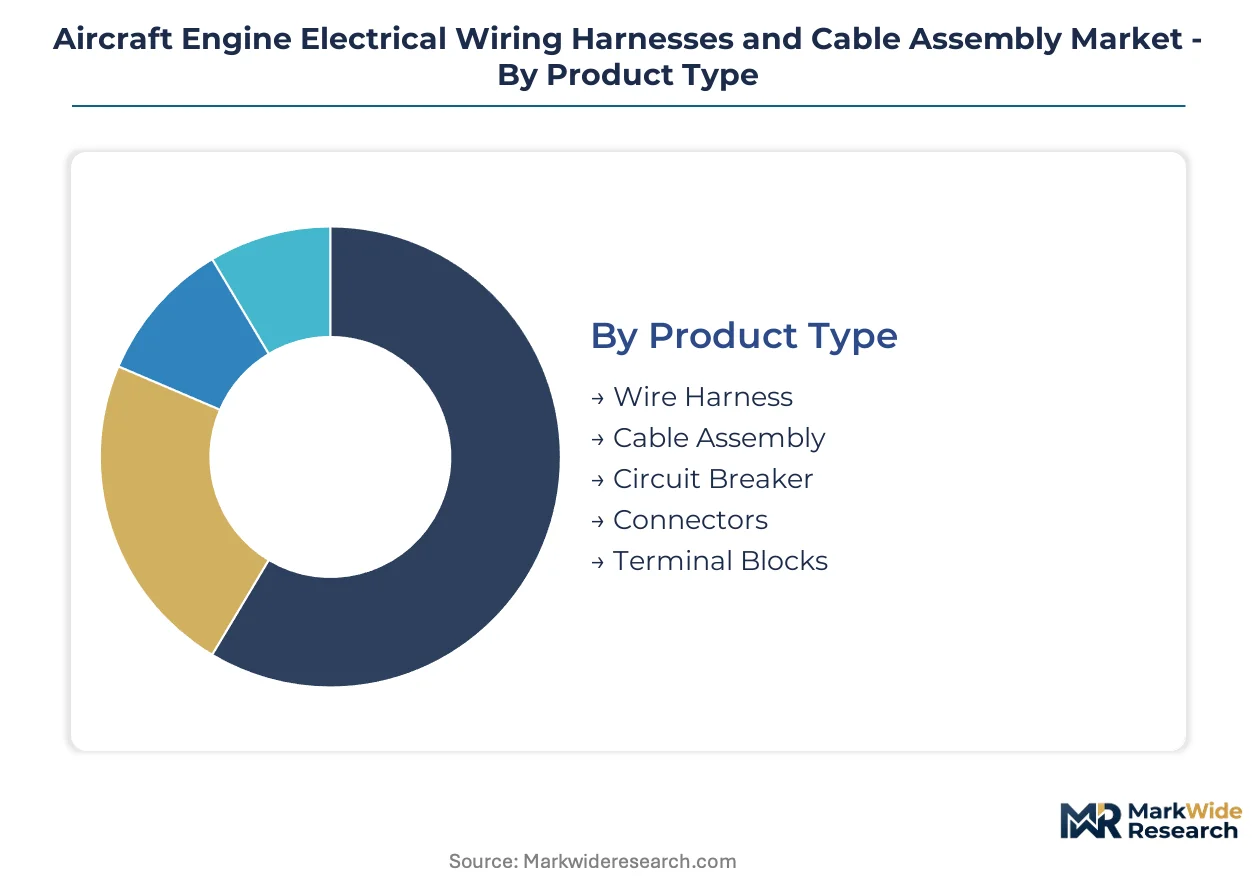
Segmentation in the aircraft engine harness market maps directly to certification pathways and procurement tiers. Each dimension carries distinct qualification burdens that shape supplier positioning and margin structures.
Product Type:
FAA Part 25 and EASA CS-25 certification requirements vary sharply across product types, with fire-resistant wiring standards forcing material traceability down to the conductor plating level.
- Wire Harness:Bundled silver-plated copper conductors with PTFE or polyimide insulation, organized into looms with integrated strain relief for power and signal distribution across turbine modules. Demand concentrates in narrow-body final assembly lines in the United States and France, pulled by next-generation turbofan procurement timelines.
- Cable Assembly:Pre-terminated conductor groups with molded connectors and environmental sealing, specified for high-vibration engine zones. Procurement volumes track LEAP and PW1100G production ramps, with Chinese COMAC programs localizing sourcing requirements.
- Circuit Breaker:Thermal and magnetic protection devices integrated into engine electrical distribution systems.
- Connectors:Circular and rectangular interface components mating harness segments across pylon and nacelle boundaries.
- Terminal Blocks:Junction points for power distribution and grounding within accessory gearbox compartments.
Leading the category by volume: Wire Harness. Growing fastest: Cable Assembly.
Technology:
Technology selection determines thermal envelope and electromagnetic compatibility, with cost tiers separating legacy platforms from next-generation architectures.
- Shielded Wiring:Metal braid or foil-wrapped conductors maintaining electromagnetic protection across high-current engine control channels. Retrofit demand from aging CFM56 and V2500 fleets sustains volumes in the United States and European MRO networks.
- Fiber Optic Cabling:Glass or polymer fiber transmission immune to electromagnetic interference, specified for digital engine monitoring and FADEC data links. Adoption climbs fastest in wide-body programs requiring high-bandwidth sensor networks.
- Coaxial Cable:Concentric conductor geometry for radio frequency and high-speed data transmission.
- Ribbon Cable:Parallel conductor arrays for compact avionics interface applications.
- Teflon Insulation:Fluoropolymer dielectric formulations rated to 260 degrees Celsius, gaining preference as OEMs push thermal performance thresholds.
Shielded Wiring captures the largest installed base. Fiber Optic Cabling climbs the fastest as sensor density increases.
Application:
Application segmentation aligns with engine system criticality, where flight-safety channels demand dual-certified supply chains and documentation traceability.
- Thrust Control Systems:Harness architectures routing FADEC commands to fuel metering valves and variable stator vane actuators, requiring fault-tolerant redundancy. Procurement ties directly to new engine introduction schedules at GE Aerospace and Pratt & Whitney.
- Fuel Management:Wiring for fuel flow sensors, boost pumps, and shutoff valve control across pylon and wing tank boundaries. Demand tracks narrow-body production rates in Toulouse, Mobile, and Tianjin.
- Flight Control Systems:Signal paths connecting engine thrust levers to airframe autopilot and autothrottle functions.
- Avionics Power Supply:Distribution harnesses feeding engine-driven generators to aircraft electrical buses.
- Engine Monitoring:Sensor networks for vibration, temperature, and pressure data acquisition trending toward hybrid copper-fiber architectures.
Thrust Control Systems leads procurement value. Engine Monitoring expands most quickly on health management digitization.
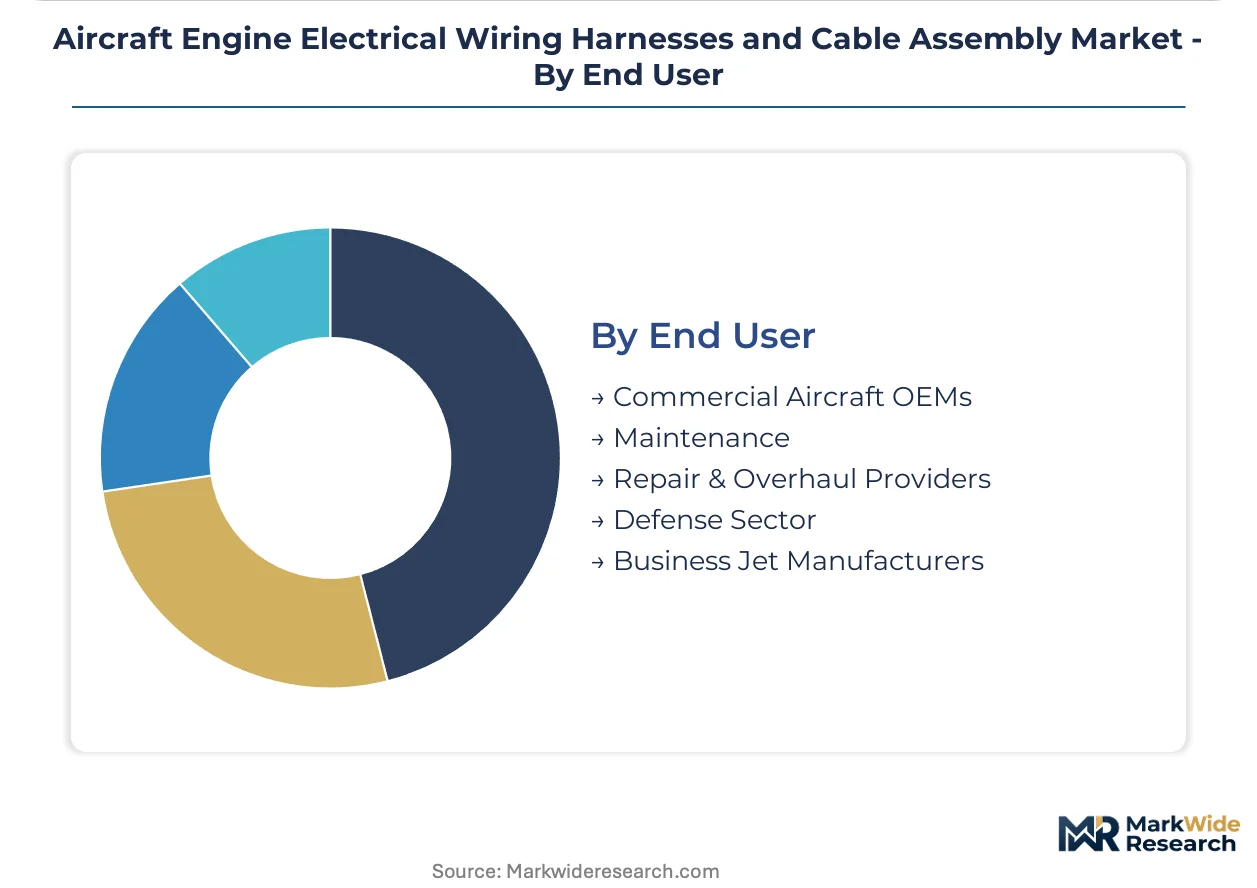
End User:
End user type determines contract structure, with OEMs demanding design-to-certification capabilities and MROs prioritizing turnaround velocity over development depth.
- Commercial Aircraft OEMs:Boeing, Airbus, and COMAC final assembly operations specifying harnesses at the engine-airframe interface. Multi-source contracting mandates are dismantling single-source relationships and compressing supplier qualification timelines.
- Maintenance, Repair & Overhaul Providers:Independent and airline-affiliated overhaul shops in Bengaluru, Hyderabad, and Singapore developing engine-zone harness refurbishment capabilities for regional fleet support.
- Defense Sector:Military engine programs with specialized shielding and hardening requirements.
- Business Jet Manufacturers:Low-volume, high-customization procurement from Gulfstream, Bombardier, and Dassault Aviation.
Commercial Aircraft OEMs dominate segment value. Maintenance, Repair & Overhaul Providers gain share fastest on fleet age accumulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Final assembly lines for narrow-body and wide-body programs concentrate procurement leverage in the United States, France, and China. Each geography maintains distinct certification requirements and supplier qualification timelines that shape harness sourcing patterns.
United States
Boeing's 737 MAX and 777X production ramps in Renton and Everett pull harness demand through multi-source contracting mandates. FAA Part 25 flammability enforcement accelerates material upgrades across existing fleets. Wichita, Kansas hosts specialized AS9100-certified harness houses serving engine OEMs and tier-one aerostructures suppliers.
France
Airbus final assembly in Toulouse and engine integration at Safran anchor European demand for fire-resistant wiring systems. EASA CS-25 certification amendments on fire propagation resistance force insulation reformulation across supply chains. The Toulouse-Blagnac aerospace cluster concentrates qualified harness specialists serving LEAP and PW1100G programs.
China
COMAC C919 production expansion and future wide-body development localize harness sourcing requirements around Shanghai and Tianjin. The country's national aviation regulator aligns certification protocols with FAA and EASA standards to facilitate export market access. Xi'an and Chengdu develop specialized conduit manufacturing for domestic turbofan programs.
United Kingdom
GKN Aerospace's thermoplastic composite conduit development anchors specialized harness innovation for high-temperature nacelle applications. Rolls-Royce engine programs at Derby sustain demand for shielded wiring in thrust control and fuel management channels. The Bristol aerospace corridor hosts tier-two suppliers qualifying under compressed OEM timelines.
India
Maintenance, repair, and overhaul hubs in Bengaluru and Hyderabad build engine-zone harness refurbishment capabilities for regional narrow-body fleets. The country's national aviation regulator expands certification infrastructure to support indigenous aerospace manufacturing targets. Pune and Chennai develop connector assembly operations for export markets.
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market Competitive Landscape
Multi-source contracting mandates dominate the current landscape as Boeing and Airbus dismantle single-source harness relationships. The vendor base concentrates around tier-one aerostructures suppliers with captive harness capabilities and specialized interconnect houses holding broad platform certifications. Three archetypes define positioning: vertically integrated engine OEM affiliates, broad-certification interconnect specialists, and weight-reduction material innovators. Competitive moves center on supplier requalification acceleration and thermoplastic composite conduit development for thermal performance gains.
Within the vertically integrated tier, Safran S.A. exemplifies the aerostructures-to-harness model through captive production for LEAP and CFM56 programs. TE Connectivity occupies a position as the broad-certification archetype, anchoring supply relationships across Boeing and Airbus platforms through AS9100 and NADCAP standards maintenance. GKN Aerospace Services Limited represents the materials innovation vector, specializing in thermoplastic composite conduits that reduce weight in high-temperature nacelle zones.
| Leading Market Players |
|---|
| Amphenol Corporation |
| Yazaki Corporation |
| Safran S.A. |
| Latecoere S.A. |
| AMETEK Inc. |
| Collins Aerospace |
| GKN Aerospace Services Limited |
| Glenair Inc. |
| TE Connectivity |
| Others |
Pricing and Supply Chain Analysis
Captive production within vertically integrated aerostructures divisions anchors both supply security and pricing power for tier-one suppliers serving LEAP and CFM56 programs, while specialized harness houses compete on certification breadth rather than cost scale. This integration choice insulates engine OEM affiliates from silver-plated copper volatility but compresses margins for independent suppliers locked into long-term offtake agreements.
Pricing Analysis
Warranty and service bundling separates power-by-the-hour inclusive contracts from unbundled aftermarket procurement, with low-cost carriers in the United States and Southeast Asia driving the shift toward direct harness sourcing. Three-tier pricing structure across OEM-specified, PMA-certified, and repair-and-overhaul grades reflects certification level and traceability depth. Cost compression in PMA tiers intensifies because airline engineering functions centralize procurement decisions. MRO providers exhibit highest price sensitivity; OEM captive suppliers demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Wichita, Toulouse-Blagnac, and Shanghai-Tianjin clusters operate hub-and-spoke patterns feeding final assembly lines. Manufacturing concentrates in the United States, France, and China. Silver-plated copper conductors, PTFE resin, and polyimide film feed from specialized chemical suppliers. Single-source vulnerability runs through qualified AS9100-certified harness specialists. Distribution runs through tier-one aerostructures suppliers with captive logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as fiber optic cabling displaces shielded copper architectures in engine health monitoring applications. Legacy harness drawings for CFM56 and V2500 platforms lack digital thread compatibility, creating documentation gaps that favor suppliers with reverse-engineering capabilities.
For Market Incumbents: Extend certification coverage across EASA CS-25 amendment protocols before polyimide-PTFE hybrid specifications harden into de facto standards. Invest in thermoplastic composite conduit capacity to defend against GKN Aerospace's weight-reduction advantage. Threat of disintermediation by airline procurement teams demands faster turnaround on custom configurations. For New Entrants and Emerging Players: Launch via direct aftermarket relationships with low-cost carriers unbundling harness contracts from engine OEM agreements. White-space concentrates in India's emerging MRO infrastructure at Bengaluru and Hyderabad, plus sustainable aviation fuel compatibility testing services. Most penetrable segment: regional narrow-body fleet refurbishment. Go-to-market angle: AS9100 certification acceleration through auditor training partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by tier-one aerostructures suppliers seeking captive harness capabilities. Long-term viability favors suppliers with dual FAA-EASA certification and fiber optic design-in relationships. Target archetype: specialized tier-two harness houses with NADCAP accreditation and LEAP program qualification. Signal to watch: ASTM and SAE committee finalization of new chemical exposure protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | FAA-EASA traceability systems unlock Boeing and Airbus multi-source contracting mandates. |
| Thermoplastic Composite Development | Weight reduction in nacelle zones addresses LEAP-1A and PW1100G thermal performance thresholds. |
| Aftermarket Channel Disintermediation | Direct airline procurement relationships bypass engine OEM power-by-the-hour agreements. |
| Fiber Optic Hybrid Architecture | Electromagnetic immunity design-ins capture engine health monitoring digitization. |
| India MRO Infrastructure Buildout | Bengaluru and Hyderabad refurbishment capabilities serve regional narrow-body fleet age accumulation. |
Research Methodology
Multi-period observation of turbofan production ramps, certification amendment timelines, and precious metal input costs anchored the trend analysis, supplemented by interviews with harness procurement managers at tier-one aerostructures suppliers, quality directors overseeing AS9100 compliance, airline fleet engineering heads, and MRO operations leads. Secondary validation drew from FAA airworthiness directive filings, EASA certification bulletins, customs trade data for silver-plated copper and fluoropolymer resins, and OEM supplier conference disclosures. Bottom-up build of harness unit demand by engine program triangulated against top-down aerostructures market sizing.
Segment-weighting applied product type, technology, application, and end-user dimensions across the projection horizon. Wire harness and cable assembly volumes modeled separately from fiber optic growth curves. CAGRs derived from production forecast linkages to 737 MAX, 777X, A320neo family, and COMAC C919 delivery schedules. Thermal performance threshold evolution and sustainable aviation fuel compatibility requirements fed scenario analysis.
Regulatory amendment timing, precious metal price volatility, and qualified supplier capacity constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on certification pathway alignment and OEM multi-sourcing timeline execution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market