
 Autonomous Bike Market | 2026-2036
Autonomous Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Bike Market Analysis
Aftermarket service revenue is reconfiguring how autonomous bike manufacturers capture lifetime value from hardware sales. Yamaha Motor leverages its powersports dealer network to sustain service attachment rates across European markets. Joyride Technologies anchors its business model on fleet-management software subscriptions rather than unit margins alone.
An autonomous bike integrates electric propulsion with self-navigating sensor arrays—typically combining GPS positioning, LiDAR obstacle detection, and machine-learning path planning—to execute trips without continuous human steering input. Electric bikes occupy the dominant product position due to mature battery supply chains and established consumer familiarity, while cargo bikes represent the fastest-expanding segment as logistics operators replace van-based urban delivery. Computer vision technology leads R&D investment intensity, though machine learning platforms command the highest software-margin potential as fleet operators seek predictive maintenance and route-optimization capabilities.
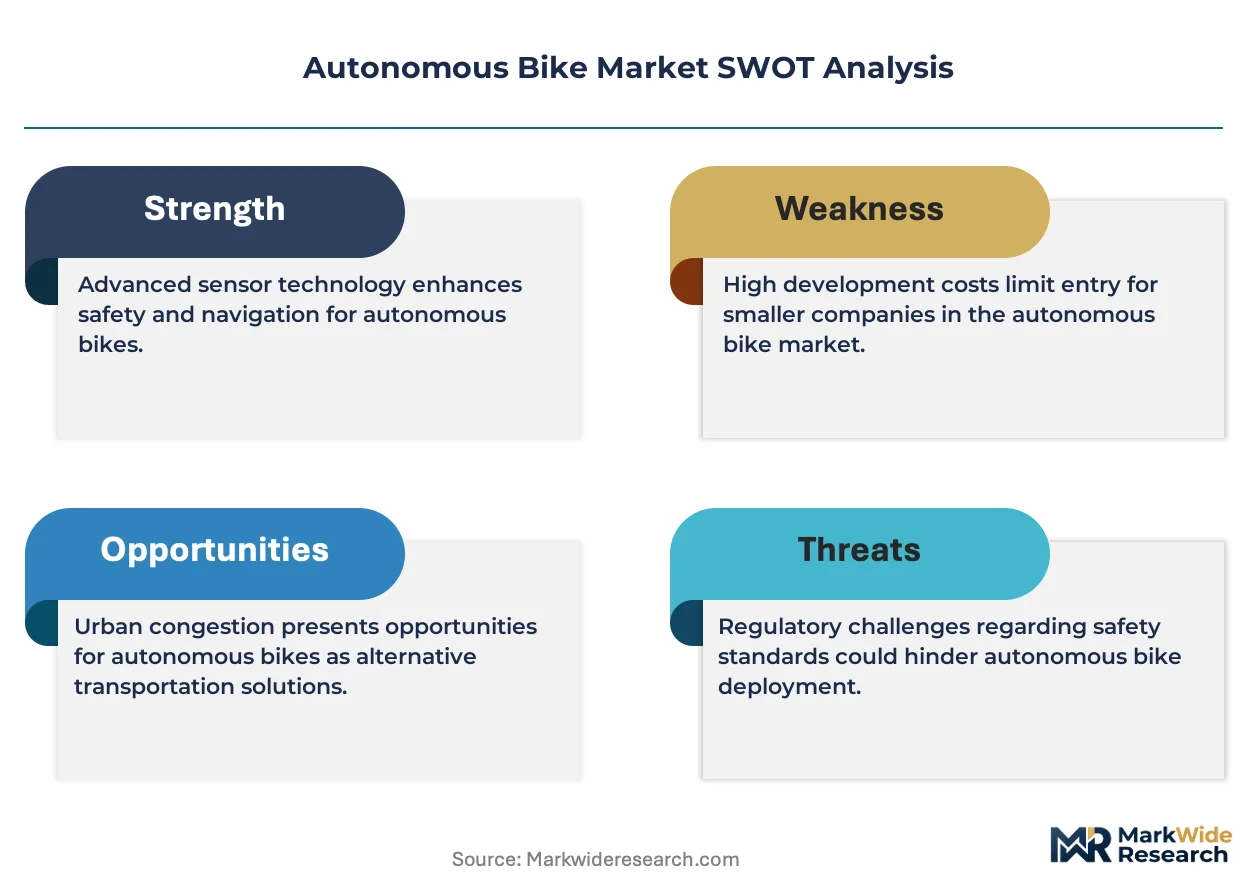
The EU AI Act and CE marking requirements under the Machinery Directive shape product liability and algorithmic transparency obligations for autonomous bikes sold in Europe. The US NHTSA and FAA maintain parallel oversight interest as vehicle autonomy classifications evolve, creating compliance complexity for cross-border suppliers. Stakeholders must monitor how regulatory fragmentation between national transport authorities and emerging micromobility codes affects homologation timelines and market access sequencing.
Market Dynamics
Last-mile logistics operators in Germany, the Netherlands, and Denmark are accelerating autonomous bike procurement as urban congestion charges and diesel bans compress delivery economics for van-based fleets. This demand compression is restructuring supplier priorities around fleet-scale deployment rather than consumer retail channels.
Growth Catalysts
- EU AI Act compliance pathways:The Machinery Directive harmonization with algorithmic transparency requirements is creating a certification moat that favors early-moving manufacturers with established CE marking workflows.
- Li-ion battery cost curves:Mature cell supply chains from automotive sector spillover are reducing powertrain cost barriers for autonomous bike platforms.
- German micromobility infrastructure density:Dedicated lane networks in Berlin, Munich, and Hamburg reduce operational complexity for self-navigating systems.
Market Restraints
- LiDAR sensor supply concentration:Component sourcing depends on a narrow base of automotive-tier suppliers with allocation priority toward passenger vehicle programs.
- EU AI Act liability fragmentation:Algorithmic transparency obligations vary across national transport authorities, extending homologation timelines.
- Human courier wage arbitrage:Platform economy labor pools in Southern and Eastern Europe sustain cost competition against capital-intensive automation.
Strategic Opportunities
- Polish urban logistics corridors:Warsaw and Krakow lack mature micromobility infrastructure but show rising e-commerce delivery density suitable for autonomous bike pilot programs.
- Predictive maintenance software:Machine learning platforms analyzing sensor degradation patterns offer recurring revenue attachment beyond hardware margins.
- Swiss precision manufacturing ecosystem:Geneva and Zurich clusters provide component sourcing for high-reliability navigation modules.
Industry Challenges
- Edge-case training data scarcity:Rare weather conditions and anomalous pedestrian behaviors require extensive simulation investment.
- Retrofitting legacy fleet management systems:Logistics operators demand API compatibility with existing dispatch software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Bike Market |
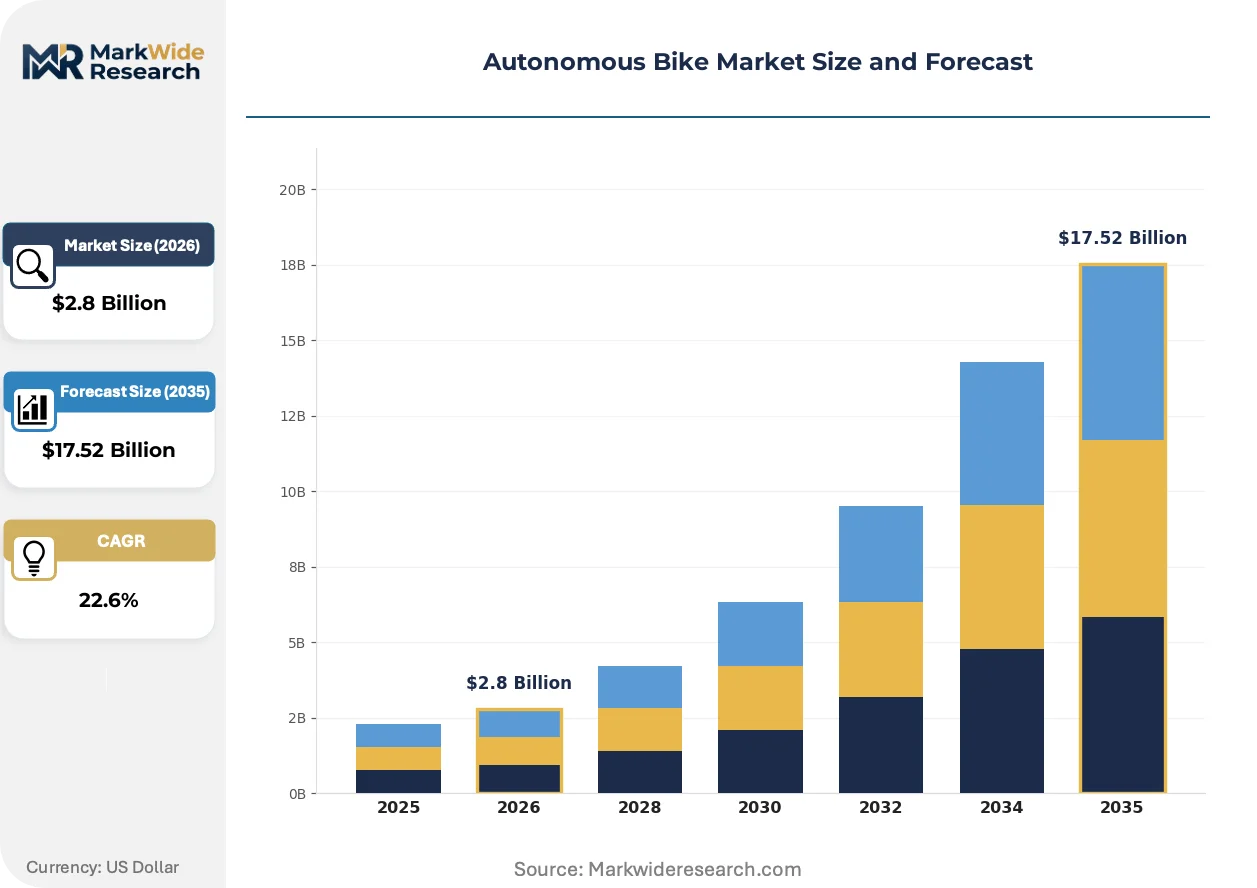
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $17.52 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Bikes, Pedal Assist Bikes, Folding Bikes, Cargo Bikes Technology: GPS Navigation, Computer Vision, LiDAR, Machine Learning End User: Commuters, Delivery Services, Tourists, Recreational Users Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Rental Services |
| Companies Covered | Audi, Tenways, Yamaha Motor, Joyride Technologies, MODMO, Verge Motorcycles, Hello TransTech, Apiir, Acer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Bike Market Emerging Trajectories
Computer vision architectures are compressing hardware requirements while expanding operational envelope capabilities. Sensor fusion approaches and software-defined functionality are displacing fixed-configuration platforms across European deployment scenarios.
Solid-state LiDAR is collapsing the cost-performance threshold for obstacle detection in autonomous bikes. German logistics operators are deploying these units across Berlin and Hamburg delivery fleets within eighteen-month refresh cycles. The technology is collapsing the capital barrier between pilot programs and scaled commercial rollout.
The EU AI Act's algorithmic audit requirements are forcing documentation infrastructure investment across the supplier base. Manufacturers must maintain training data provenance records and decision-log retention systems. Cargo bike platforms with higher kinetic energy profiles face stricter conformity assessment procedures than lighter passenger variants.
Fleet operators are consolidating procurement decisions under centralized sustainability officers rather than distributed depot managers. This shift compresses vendor evaluation timelines but elevates lifecycle carbon accounting requirements. Dutch postal and parcel carriers are the most advanced in implementing total-cost-of-ownership frameworks that internalize battery second-life value.
Autonomous Bike Market Segmentation
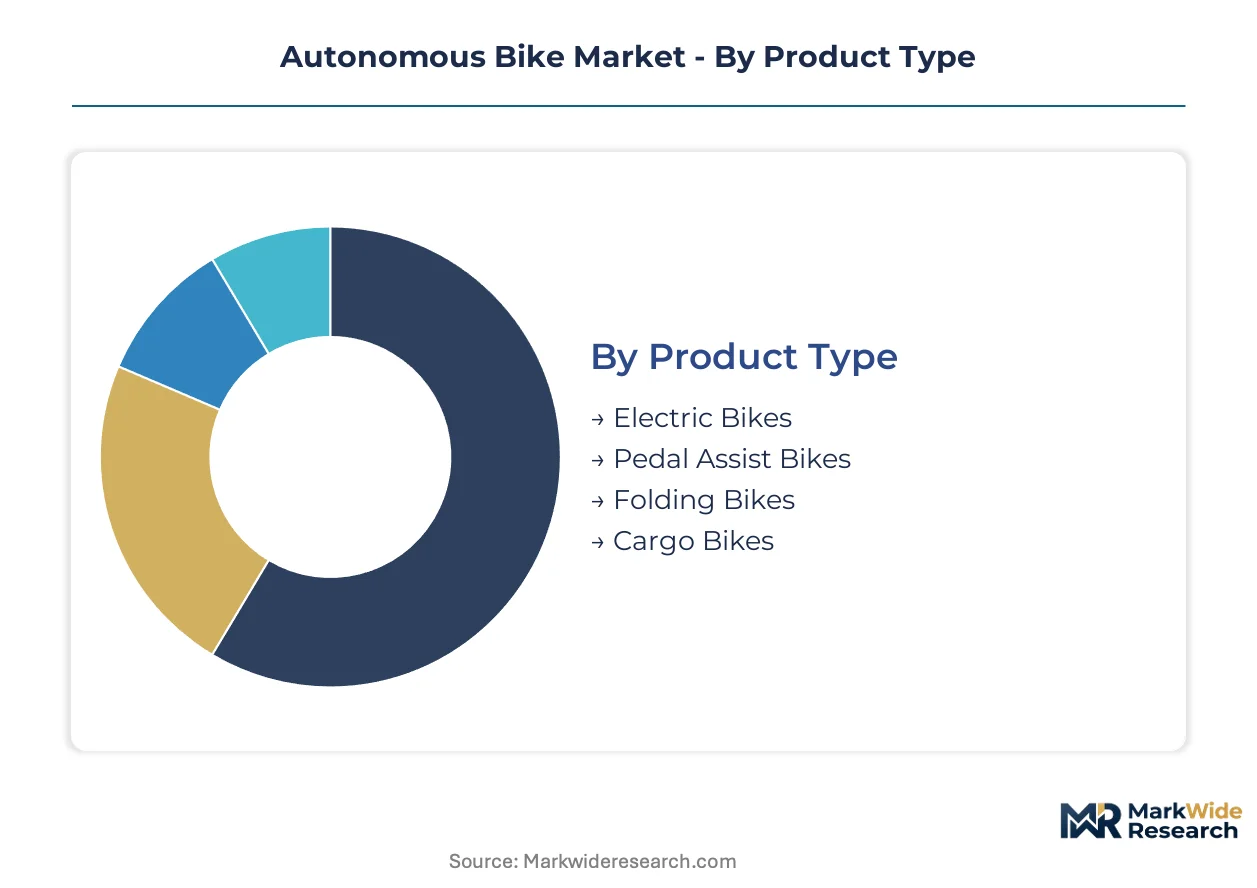
Segmentation in autonomous bikes determines service revenue models and sensor calibration requirements. Fleet operators demand predictive maintenance packages that vary sharply by product type and technology stack. Procurement contracts now bundle hardware with software subscriptions tied to specific end-use intensity profiles.
Product Type:
After-sales-service intensity escalates dramatically with payload capacity and battery duty cycles, reshaping margin capture across hardware categories.
- Electric Bikes:Full-electric propulsion systems with integrated battery management and regenerative braking dominate urban commuter deployments. German last-mile fleets in Berlin and Munich concentrate procurement here, driven by mature charging infrastructure and CE marking harmonization under the Machinery Directive.
- Cargo Bikes:Extended wheelbase platforms with reinforced frames and dual-motor configurations support parcel loads exceeding 150 kilograms. Dutch postal operators and Danish logistics firms drive fastest expansion, compressed by urban diesel bans and congestion charging schemes in Amsterdam and Copenhagen.
- Pedal Assist Bikes:Torque-sensor augmentation preserves rider exercise while reducing physical exertion thresholds.
- Folding Bikes:Hinged frame architectures prioritize multimodal transit integration and storage density in dense European cores.
By volume, Electric Bikes leads. By growth pace, Cargo Bikes is climbing the fastest.
Technology:
Cost tier stratification separates commodity positioning from premium system integration, with software-margin potential concentrated in predictive layers.
- Computer Vision:Camera-based object recognition using convolutional neural networks processes real-time pedestrian and vehicle trajectories. German automotive supplier ecosystems in Stuttgart and Munich anchor R&D investment here, propelled by EU AI Act algorithmic transparency requirements and CE marking liability frameworks.
- Machine Learning:Cloud-trained models deployed at the edge enable route optimization and predictive maintenance across fleet scales. Fleet management platforms in Rotterdam and Hamburg attach recurring revenue here, driven by total-cost-of-ownership frameworks that internalize sensor degradation patterns.
- GPS Navigation:Satellite positioning fused with cellular triangulation provides baseline localization in mapped environments.
- LiDAR:Time-of-flight laser arrays generate high-fidelity point clouds for obstacle detection in unstructured urban terrain.
By deployment scale, GPS Navigation leads. By margin expansion, Machine Learning is gaining share fastest.
End User:
Application intensity varies from sporadic recreational use to continuous commercial duty cycles, dictating durability specifications and warranty structures.
- Delivery Services:Continuous-duty fleet deployment with centralized dispatch integration and API compatibility requirements. Polish logistics corridors in Warsaw and Krakow show rising pilot density, compressed by e-commerce volume growth and courier wage arbitrage constraints in Eastern European labor markets.
- Commuters:Daily personal transportation with weather-dependent utilization patterns and theft-risk exposure. German micromobility infrastructure density in Hamburg and Munich supports concentration here, shaped by dedicated lane networks and municipal subsidy programs.
- Tourists:Short-duration rentals with simplified user interfaces and geofenced operational envelopes.
- Recreational Users:Weekend and leisure deployment with performance-oriented feature preferences and lower utilization duty cycles.
By installed base, Commuters leads. By contract value expansion, Delivery Services shows the steepest trajectory.
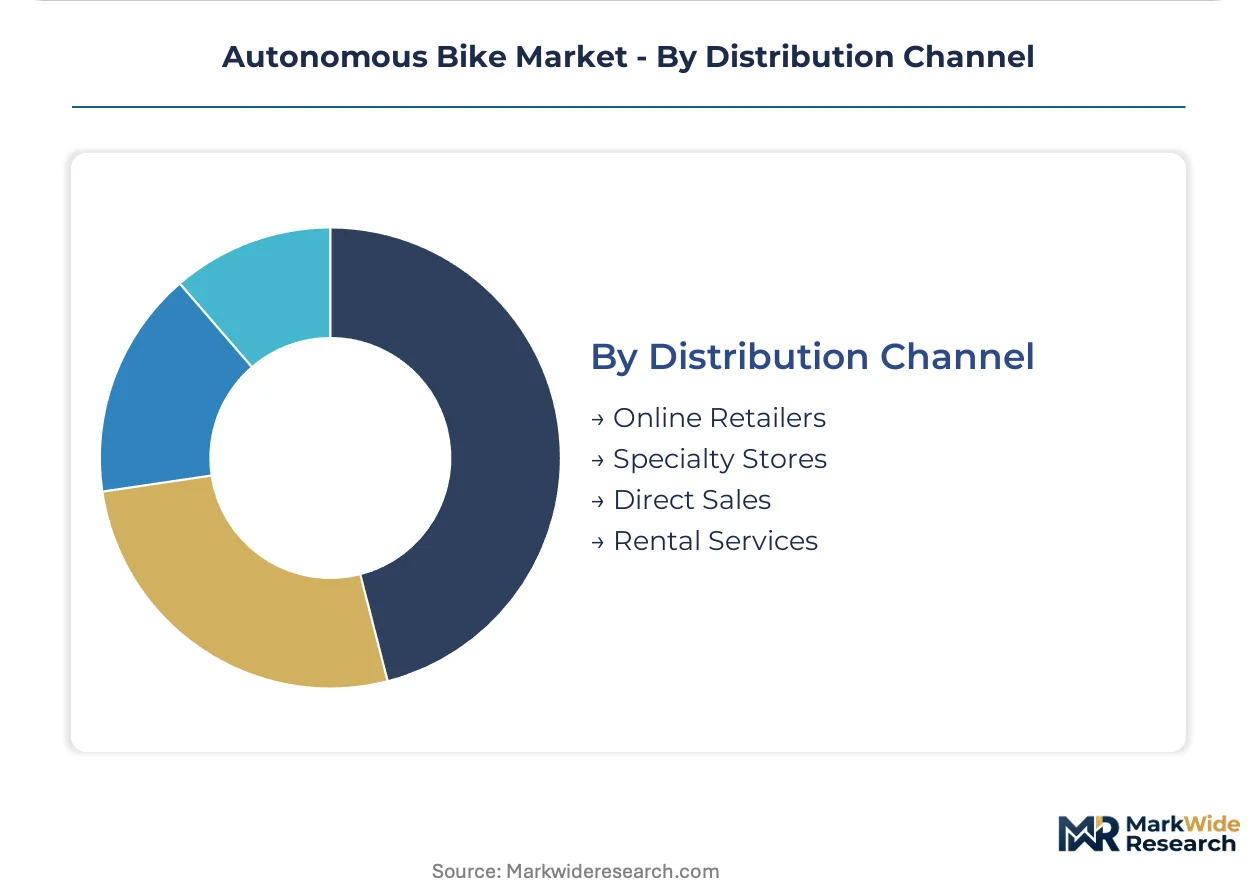
Distribution Channel:
Customer type fragmentation separates individual purchasers from institutional procurement with diverging evaluation timelines and lifecycle cost frameworks.
- Rental Services:Fleet-as-a-service models with centralized maintenance hubs and rapid depreciation schedules. Dutch and Danish municipal operators concentrate procurement here, driven by sustainability officer consolidation and carbon accounting requirements under EU Green Deal implementation.
- Direct Sales:Manufacturer-to-fleet contracts with customized sensor configurations and training data provenance documentation. German logistics operators favor this channel for EU AI Act compliance pathway efficiency.
- Online Retailers:E-commerce platforms with standardized specifications and consumer financing integration.
- Specialty Stores:Physical showrooms with test-ride capabilities and localized service attachment.
By transaction volume, Online Retailers leads. By revenue per unit, Rental Services is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators show the lowest price elasticity as EU AI Act compliance premiums override unit cost considerations. Polish logistics buyers remain most sensitive to upfront capital outlay, compressing vendor margins in Warsaw procurement corridors. Dutch sustainability officers internalize total-cost-of-ownership frameworks that elevate lifecycle value over sticker price.
Germany
Berlin and Hamburg micromobility infrastructure density supports continuous-duty fleet deployment for last-mile delivery operators. The EU AI Act and Machinery Directive CE marking requirements create certification moats favoring established manufacturers with documented algorithmic transparency workflows. Bavaria's automotive supplier ecosystem around Munich and Stuttgart anchors LiDAR sensor integration and machine learning platform development for autonomous navigation systems.
Netherlands
Amsterdam and Rotterdam postal carriers drive cargo bike procurement acceleration under urban diesel bans and congestion charging compression. EU Green Deal carbon accounting requirements and CSRD sustainability disclosure rules elevate lifecycle assessment in procurement decisions. Eindhoven's precision manufacturing cluster supplies high-reliability navigation modules for fleet-scale sensor calibration.
Denmark
Copenhagen's municipal logistics operators consolidate autonomous bike procurement under centralized sustainability officers with total-cost-of-ownership mandates. National transport authority alignment with EU AI Act algorithmic audit requirements streamlines homologation pathways for compliant manufacturers. Odense's robotics research corridor contributes simulation infrastructure for edge-case training data generation in Nordic weather conditions.
Poland
Warsaw and Krakow e-commerce delivery density rises against courier wage arbitrage constraints in Eastern European labor markets. The country's national transport authority maintains parallel compliance interest with EU regulatory frameworks as accession-aligned standards evolve. Silesian industrial zones provide component assembly capacity for cost-optimized autonomous bike platforms targeting price-sensitive fleet segments.
Switzerland
Geneva and Zurich precision manufacturing ecosystems supply navigation module components for high-reliability autonomous systems in Alpine terrain conditions. Swissmedic and national transport authority oversight maintains rigorous conformity assessment procedures exceeding baseline EU requirements. Basel's pharmaceutical logistics corridor pilots autonomous cargo bikes under stringent cold-chain and timing protocols.
Autonomous Bike Market Vendor Landscape
Capability concentration sits with specialized sensor-software integrators; scale advantage sits with diversified mobility conglomerates. The market structure tiering separates premium-tier algorithmic specialists from mid-market hardware assemblers and economy-tier white-label fabricators. Three archetypes dominate: automotive spin-offs leveraging CE marking workflows, fleet-software platforms anchoring subscription revenue, and component suppliers backward-integrating into complete systems. Competitive moves concentrate on strategic partnerships for AI training data access and geographic licensing arrangements for regulatory pathway efficiency.
Within the automotive heritage tier, Audi and Yamaha Motor exemplify manufacturers with established European homologation infrastructure and powersports dealer networks for service attachment. Joyride Technologies occupies the fleet-software platform position, representing the archetype of companies prioritizing recurring subscription revenue over hardware unit margins. Tenways sits within the emerging specialist category, illustrating the pattern of focused manufacturers targeting specific price-performance segments in procurement-consolidated markets.
| Leading Market Players |
|---|
| Audi |
| Tenways |
| Yamaha Motor |
| Joyride Technologies |
| MODMO |
| Verge Motorcycles |
| Hello TransTech |
| Apiir |
| Acer |
| Others |
Supply Flow & Price Mechanics
LiDAR sensor supply concentration in Germany's automotive-tier supplier base anchors margin capture downstream in fleet-management software subscriptions. Yamaha Motor's powersports dealer network and Joyride Technologies' SaaS platforms illustrate how service attachment rates redistribute value away from hardware unit economics.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions drive lifetime value capture beyond initial hardware transactions. Three-tier pricing structure across premium algorithmic-audit-compliant systems, standard CE-marked platforms, and economy-tier white-label units separates procurement decisions by fleet scale and regulatory exposure. Cost compression in economy tiers intensifies because Polish logistics buyers prioritize upfront capital outlay over lifecycle frameworks. Delivery services show lowest price sensitivity as EU AI Act compliance premiums override unit cost considerations, while commuter segments retain higher elasticity.
Supply Chain Analysis
Tariff exposure between Chinese battery cell manufacturers and European assembly operations dominates supply chain risk calculus for autonomous bike platforms. Component sourcing draws from Germany for LiDAR integration, the Netherlands for fleet-management software development, and Poland for cost-optimized frame assembly. Single-source vulnerability in solid-state LiDAR automotive-tier suppliers creates allocation bottlenecks when passenger vehicle programs claim priority. Distribution runs through direct manufacturer-to-fleet contracts with API compatibility requirements and centralized sustainability officer procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from human courier wage arbitrage in Southern and Eastern European labor markets that sustains cost competition against capital-intensive automation platforms.
For Market Incumbents: Pre-empt software-defined functionality displacement by deepening backward integration into machine learning platform development and securing exclusive training data partnerships with German logistics operators. Anchor defensive positioning through CE marking workflow moats that extend homologation timelines for challengers. Prioritize sensor degradation pattern libraries as proprietary assets that elevate switching costs in fleet management contracts.
For New Entrants and Emerging Players: Build out Polish urban logistics corridors in Warsaw and Krakow where micromobility infrastructure underdevelopment creates pilot program white space before German market saturation. Target cargo bike segments with dual-motor configurations for parcel loads exceeding 150 kilograms where Dutch postal carrier procurement accelerates fastest. Deploy fleet-software-first go-to-market positioning that anchors recurring revenue before hardware margin competition intensifies.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fleet-software platforms that have achieved API integration density with logistics dispatch systems but lack sensor-hardware manufacturing scale. Five-to-ten year viability hinges on EU AI Act algorithmic audit infrastructure becoming mandatory compliance cost rather than competitive differentiator. Monitor LiDAR cost-performance threshold collapse as inflection signal for scaled commercial rollout feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Infrastructure | Algorithmic transparency documentation creates certification moats favoring early-moving manufacturers with established CE marking workflows. |
| Predictive Maintenance Platform Development | Machine learning models analyzing sensor degradation patterns attach recurring revenue beyond hardware unit margins. |
| Polish Logistics Corridor Pilot Programs | Warsaw and Krakow e-commerce density offers white-space deployment before German market saturation. |
| Solid-State LiDAR Integration Partnerships | German automotive supplier ecosystems in Stuttgart and Munich anchor obstacle detection cost-performance improvements. |
| Fleet Management API Standardization | Dispatch software compatibility requirements compress vendor evaluation timelines for logistics procurement consolidation. |
Methodological Framework
A standing panel of fleet operations directors, sustainability officers at Dutch postal carriers, Tier 1 automotive supplier procurement leads, and micromobility infrastructure planners provided ongoing calibration across the analysis window. Primary interview findings triangulated against secondary sources including EU AI Act implementation guidance, Machinery Directive CE marking databases, German KBA homologation records, and Li-ion battery customs trade data. Bottom-up unit economics modeling and top-down market sizing converged through iterative validation loops.
Scenario bracketing around regulatory implementation pace and LiDAR cost curve trajectories shaped projection outputs across the modeling period. Segmentation dimensions included product type, navigation technology stack, end-use intensity profile, and distribution channel structure. CAGRs derived from logistic curve adoption modeling calibrated against fleet procurement pipeline visibility. Industry-specific inputs incorporated EU Green Deal carbon accounting requirements and CSRD sustainability disclosure rule implementation timelines.
Sensitivities concentrate around EU AI Act liability fragmentation across national transport authorities and LiDAR supplier allocation priority shifts toward passenger vehicle programs. Forecasts reflect documented assumptions regarding micromobility infrastructure deployment pace and battery second-life value realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market