
 China Automotive Camera Market | 2026-2036
China Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Camera Market Outlook
The capability gap between integrated semiconductor-camera module producers and pure-play lens assemblers is reorganizing competitive tiers in the China Automotive Camera Market. Robert Bosch GmbH leverages its in-house sensor fusion stack to anchor premium OEM contracts across domestic brands. BYD Semiconductor controls captive wafer supply for image signal processors, insulating margins against foundry volatility. Sunny Smartlead specializes in high-resolution optical modules, occupying the mid-tier replacement channel through cost-engineered designs.
China automotive cameras are electro-optical imaging devices typically specified at 1.3 to 8 megapixels with automotive-grade temperature tolerance from negative forty to eighty-five degrees Celsius, engineered to feed real-time visual data into advanced driver assistance and autonomous navigation systems. Front view camera systems lead product type deployment as OEMs integrate adaptive cruise and lane-keeping functions into mass-market nameplates. Digital camera technology is displacing analog architectures fastest among technology tiers, driven by MIIT-connected vehicle data requirements that demand raw image processing at the edge rather than compressed signal transmission.
MIIT mandates camera-based advanced driver assistance system compliance under GB/T standards for new vehicle type approvals, while SAMR enforces quality certification under compulsory product standards that gate aftermarket distribution channels. The national dual carbon goals from MEE indirectly shape demand by accelerating electric vehicle platform launches, which bundle higher camera counts per vehicle for energy-efficient automated driving. Stakeholders must monitor whether GB standard revisions will mandate higher pixel specifications that obsolete current analog inventories before replacement cycles complete.
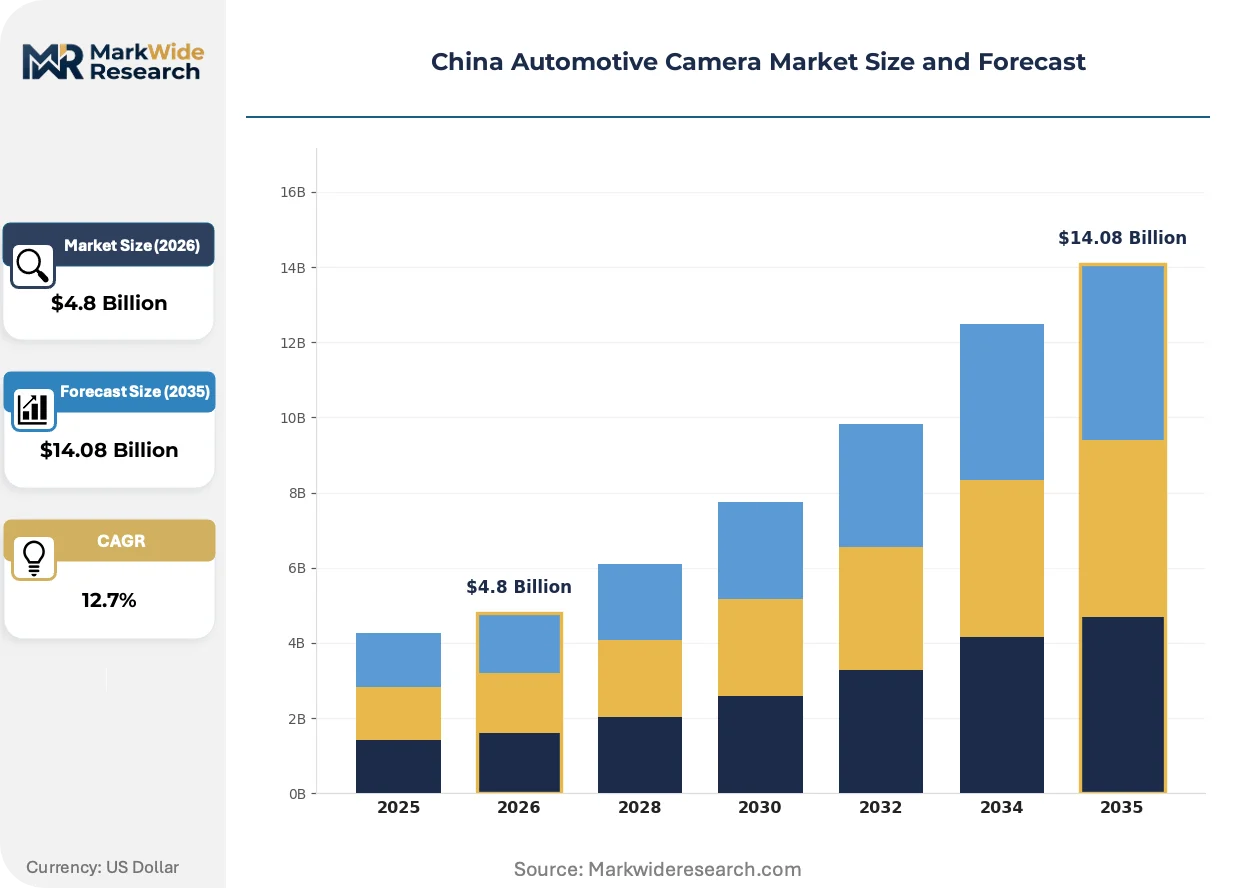
Market Dynamics
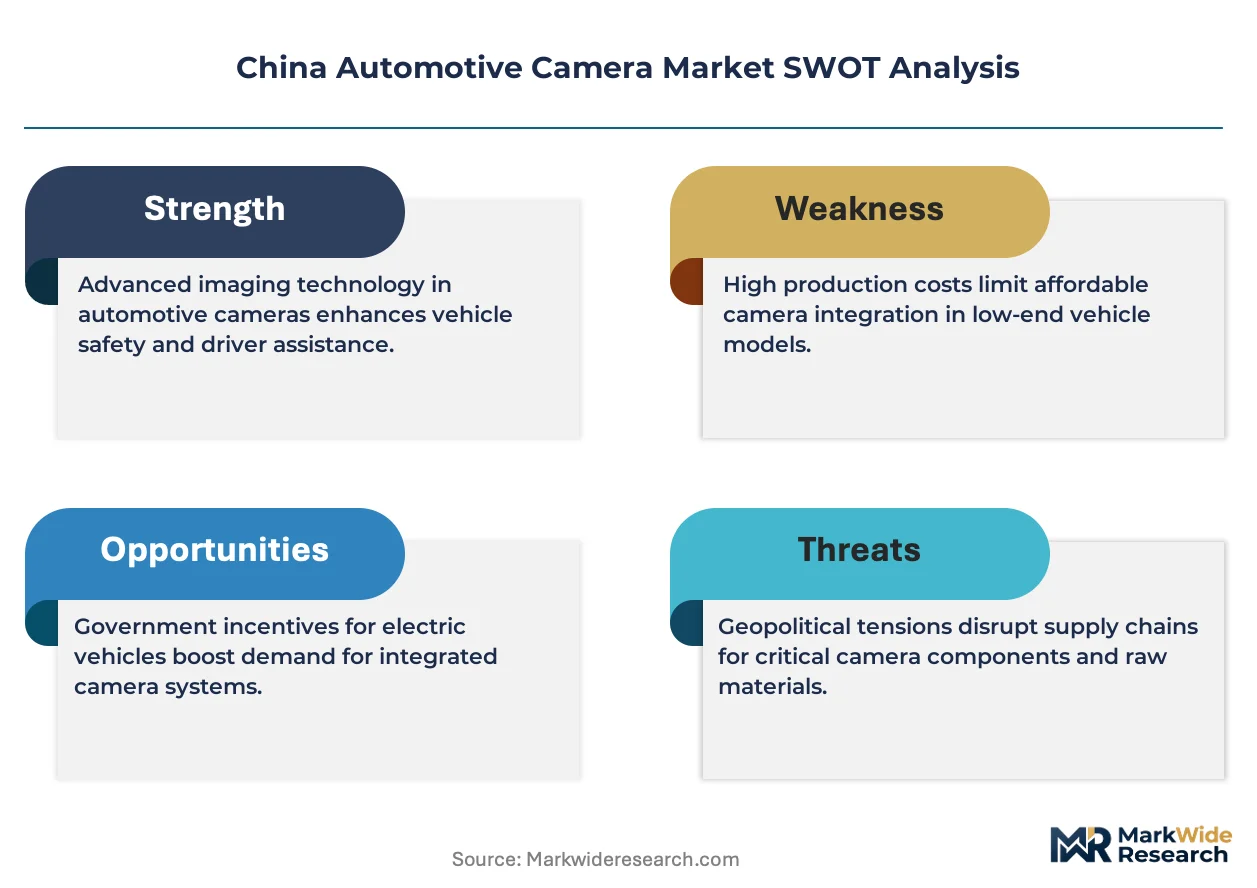
MIIT's GB/T mandates for camera-based advanced driver assistance systems are compressing certification timelines and forcing module suppliers to accelerate digital architecture transitions before analog inventory cycles complete.
Growth Catalysts
- MIIT GB/T Mandates:Compulsory camera-based safety features for new vehicle type approvals pull demand from premium nameplates into mass-market segments.
- Shanghai-Suzhou Manufacturing Cluster:Co-location of domestic suppliers and foreign joint ventures reduces logistics friction for tier-one OEM procurement teams.
- Digital Edge Processing:Raw image processing at the sensor level eliminates compression latency for real-time autonomous navigation systems.
Market Restraints
- Foundry Volatility:Image signal processor wafer supply concentrates at mature-node fabs, exposing margins to capacity allocation shocks.
- Analog Inventory Obsolescence:GB standard revisions threaten to strand analog camera stocks before replacement cycles conclude.
- Thermal Tolerance Costs:Automotive-grade specifications from negative forty to eighty-five degrees Celsius demand specialized packaging that inflates BOM costs versus consumer-grade alternatives.
Strategic Opportunities
- Yangtze River Delta Expansion:Tier-two cities in Jiangsu and Zhejiang provinces offer underpenetrated aftermarket channels for high-resolution replacement modules.
- Dual Carbon Policy Tailwind:MEE national goals accelerate electric vehicle platform launches that bundle higher camera counts per vehicle for automated driving efficiency.
- Sensor Fusion Convergence:Integration of camera data with lidar and radar streams creates specification premiums for semiconductor-module integrated suppliers.
Industry Challenges
- Optical Engineering Talent Scarcity:High-resolution lens design expertise concentrates at a handful of research institutes, constraining mid-tier supplier scaling.
- Compulsory Certification Timelines:SAMR quality certification gates for aftermarket distribution compress product development windows.
- Legacy System Integration Friction:Analog-to-digital architecture transitions disrupt established supply relationships with tier-two OEM electronics divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Camera Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $14.08 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rear View Camera, Front View Camera, 360-Degree Camera, Parking Assistance Camera Technology: Analog Camera, Digital Camera, LiDAR-Based Systems, Infrared Camera End User: OEMs, Aftermarket Providers, Fleet Operators, Commercial Vehicles Installation: Integrated Systems, Retrofit Solutions, Assembly Line Installation, DIY Kits |
| Companies Covered | Denso Corporation, Robert Bosch GmbH, Continental AG, Delphi Automotive PLC, Autoliv Inc, Panasonic Corporation, Sony Electronics, Sunny Smartlead, BYD Semiconductor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Camera Market Strategic Shifts
Automotive camera architectures are compressing from distributed analog chains toward integrated digital modules, with regulatory data requirements and edge computing demands rewriting component specifications across the supply base.
Automotive-grade CMOS image sensors are miniaturizing pixel architectures while maintaining low-light sensitivity thresholds required for nighttime autonomous operation. Tier-one OEMs are specifying sub-2-micron pixel pitches for 8-megapixel front-view systems to reduce lens barrel dimensions. This compression is miniaturizing module footprints, enabling windshield integration without structural redesign of vehicle A-pillars.
MIIT's connected vehicle data regulations are mandating raw image retention at the edge, prohibiting compressed signal transmission for safety-critical functions. This policy shift forces module suppliers to embed higher-capacity image signal processors directly into camera housings. Front-view camera systems face the steepest compliance burden, with OEMs redesigning electrical architectures to accommodate localized processing power.
Fleet operators and mobility service providers are consolidating procurement specifications around standardized camera modules that span multiple vehicle platforms. This buyer concentration is compressing SKU diversity at tier-one suppliers, who must engineer configurable firmware rather than hardware variants. The Yangtze River Delta cluster shows this pattern most acutely, where domestic electric vehicle brands negotiate volume commitments in exchange for exclusive module designs.
China Automotive Camera Market Segmentation
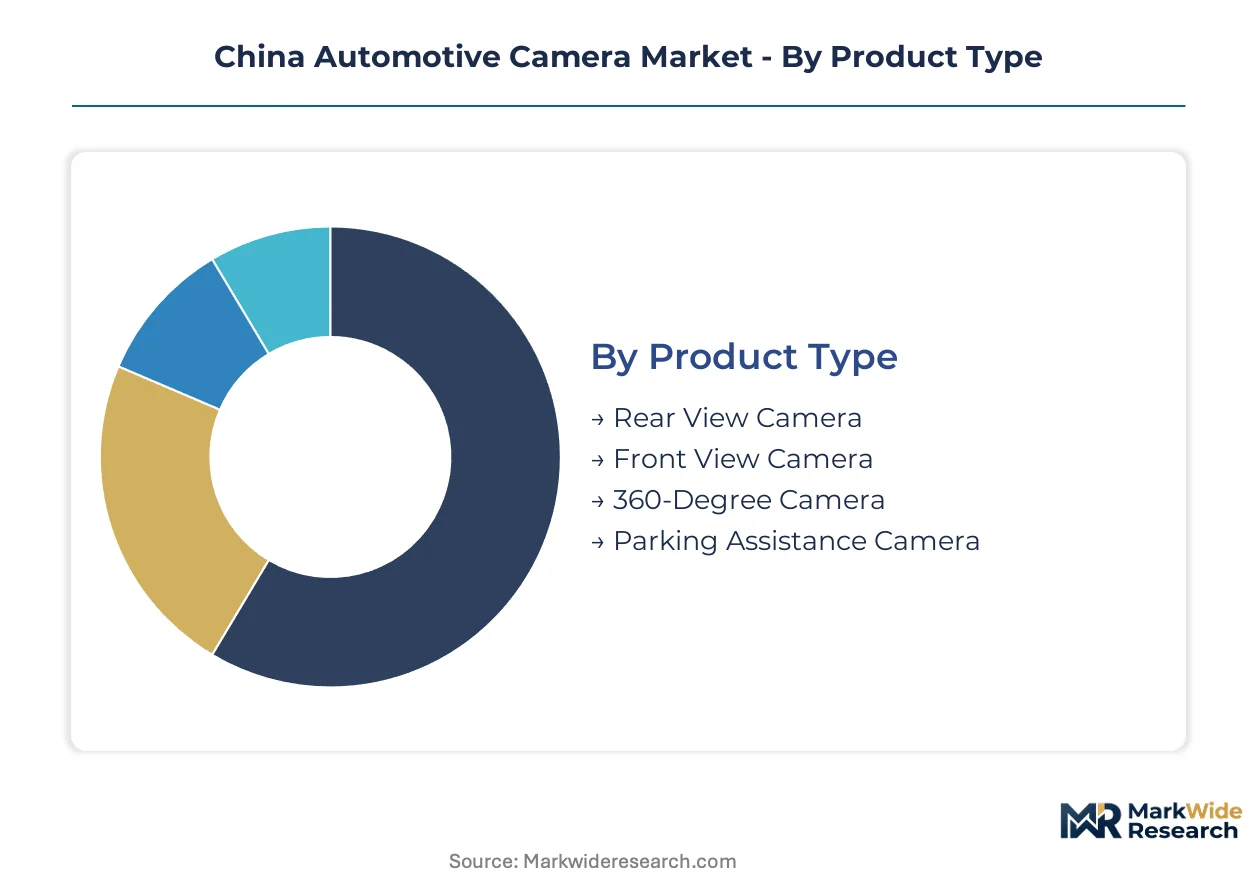
Camera module specifications diverge sharply across vehicle platforms in China, with MIIT compliance tiers and OEM integration strategies fragmenting procurement patterns. Segment boundaries blur as digital architectures displace analog chains and electric vehicle platforms bundle multi-camera arrays.
Product Type:
Front-view systems face the steepest substitution pressure from integrated sensor fusion stacks that combine camera feeds with radar and lidar streams.
- Front View Camera:1.3 to 8 megapixel systems with negative forty to eighty-five degrees Celsius tolerance anchor adaptive cruise and lane-keeping compliance under GB/T mandates. Yangtze River Delta OEMs concentrate procurement for mass-market electric vehicle platforms where MIIT type approvals require real-time visual processing.
- 360-Degree Camera:Multi-lens arrays synthesize surround-view imagery through embedded image signal processors, commanding specification premiums from domestic premium electric brands. Suzhou-based module houses scale production for parking assistance compliance in compact urban vehicle segments.
- Rear View Camera:Single-lens backup systems with standardized mounting interfaces dominate entry-grade vehicle configurations under compulsory safety equipment rules.
- Parking Assistance Camera:Short-range ultrasonic-fusion modules target confined-space maneuvering in high-density urban environments.
Front-view camera anchors the volume base while 360-degree camera gains share at the steepest rate.
Technology:
Cost tiers stratify sharply between legacy analog inventories and digital edge-processing modules with localized ISP architectures.
- Digital Camera:Raw image retention at the sensor level satisfies MIIT connected vehicle data regulations prohibiting compressed transmission for safety-critical functions. Module suppliers embed higher-capacity processors directly into housings, inflating BOM costs versus analog alternatives but eliminating latency for autonomous navigation.
- Analog Camera:Legacy signal chains face obsolescence risk as GB standard revisions threaten to strand inventory before replacement cycles conclude. Tier-two OEM electronics divisions maintain procurement relationships for cost-sensitive nameplates.
- LiDAR-Based Systems:Optical ranging modules with camera fusion target premium autonomous driving tiers.
- Infrared Camera:Thermal imaging for nighttime pedestrian detection occupies niche safety specifications.
Digital camera commands the margin premium while analog camera retains residual volume in cost-optimized segments.
End User:
Customer type determines specification rigor, with captive OEM supply chains enforcing tighter certification timelines than aftermarket channels.
- OEMs:Tier-one vehicle manufacturers specify automotive-grade temperature tolerance and MIIT-compliant image processing for new vehicle type approvals. Domestic electric vehicle brands negotiate volume commitments with Yangtze River Delta module houses in exchange for exclusive designs.
- Fleet Operators:Mobility service providers consolidate procurement around standardized modules spanning multiple vehicle platforms, compressing SKU diversity at suppliers. Configurable firmware replaces hardware variants for operational efficiency.
- Aftermarket Providers:SAMR quality certification gates distribution channels for replacement modules.
- Commercial Vehicles:Heavy-duty platform requirements emphasize durability specifications over resolution tiers.
OEMs dominate absolute volume while fleet operators are expanding most quickly through procurement consolidation.
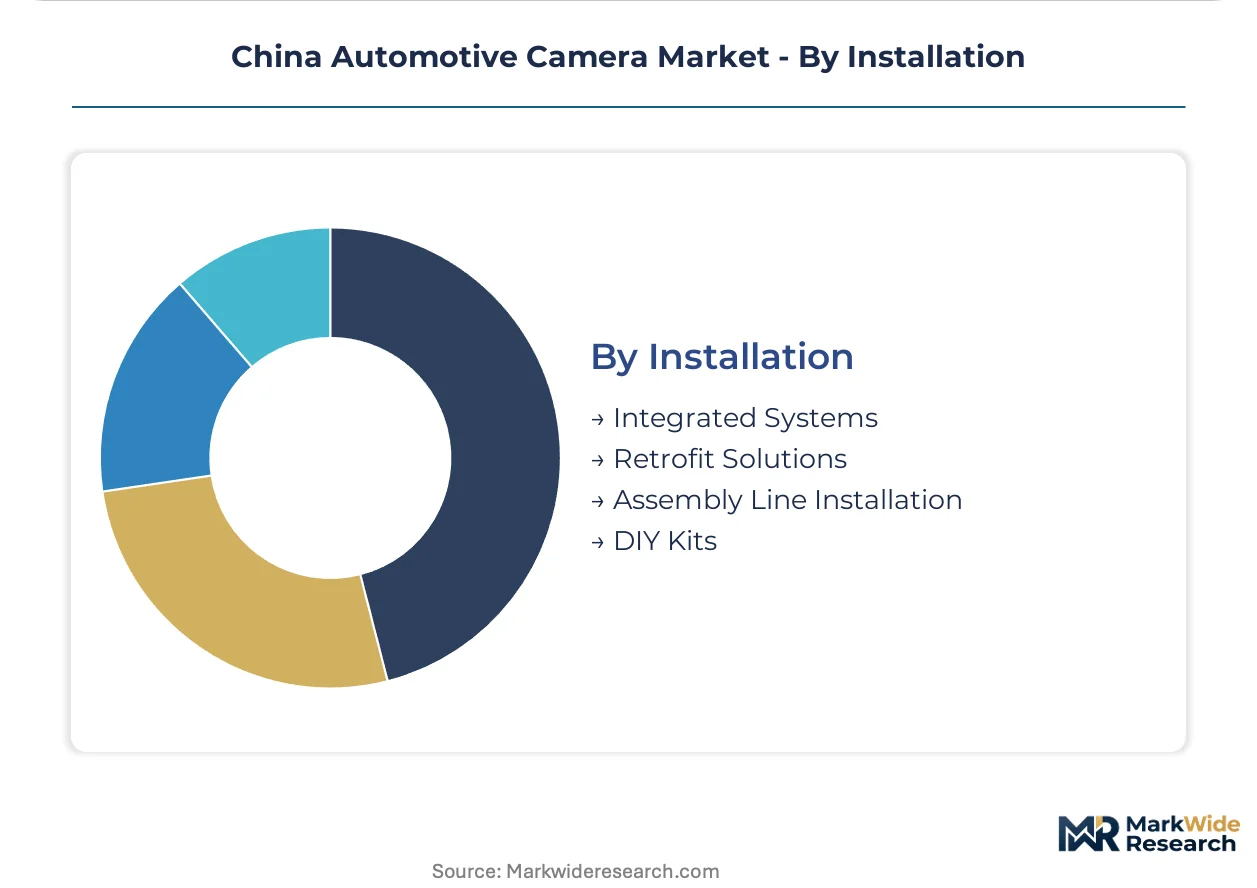
Installation:
Maturity gradients separate factory-integrated architectures from retrofit solutions with compressed development windows.
- Integrated Systems:Windshield-embedded modules with sub-2-micron pixel pitches enable A-pillar integration without structural redesign. Tier-one OEMs specify these for 8-megapixel front-view compliance.
- Assembly Line Installation:Conveyor-mounted calibration ensures optical alignment precision for mass production.
- Retrofit Solutions:Post-manufacture integration targets existing vehicle fleets with aftermarket safety upgrades.
- DIY Kits:Consumer-installable modules occupy price-sensitive replacement channels with reduced specification tiers.
Integrated systems capture the specification premium while assembly line installation handles the production volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive camera consumption diverges sharply from Western patterns, where aftermarket replacement dominates volume. Chinese demand concentrates in factory-integrated modules for new electric vehicle platforms, driven by MIIT mandates that compress certification timelines and favor domestic supply chains.
Yangtze River Delta
Shanghai and Suzhou anchor China's densest concentration of automotive camera module production, with tier-one OEM procurement teams co-locating to reduce logistics friction. MIIT's GB/T type approval requirements for camera-based ADAS pull demand from premium nameplates into mass-market electric vehicle segments. Domestic suppliers and foreign joint ventures operate side-by-side in Jiangsu and Zhejiang provinces, engineering high-resolution optical modules for windshield-integrated front-view systems.
Pearl River Delta
Shenzhen and Guangzhou drive demand through domestic electric vehicle brand headquarters that negotiate volume commitments for exclusive module designs. SAMR quality certification gates aftermarket distribution channels, compressing product development windows for replacement suppliers. The region's electronics manufacturing ecosystem supports embedded image signal processor integration directly into camera housings.
Beijing-Tianjin-Hebei
State-owned automotive groups in Beijing specify automotive-grade temperature tolerance modules for fleet operator procurement consolidation. MEE dual carbon goals accelerate electric vehicle platform launches that bundle higher camera counts per vehicle for automated driving efficiency. Tianjin's port infrastructure facilitates import of mature-node wafers for image signal processor production.
Sichuan-Chongqing
Western China's emerging automotive manufacturing base targets cost-optimized camera specifications for entry-grade vehicle configurations. Local governments offer incentives for tier-two suppliers to establish assembly operations serving inland OEM electronics divisions. Chongqing's logistics hub status reduces inland distribution costs for analog-to-digital architecture transitions.
China Automotive Camera Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capability gaps between semiconductor-camera module producers and pure-play lens assemblers reorganizing competitive tiers. The market structure favors suppliers with in-house sensor fusion stacks or captive wafer supply, insulating margins against foundry volatility. Three archetypes dominate: integrated semiconductor-module producers, optical lens specialists, and diversified automotive electronics conglomerates. Competitive moves center on backward integration into image signal processor supply and exclusive design contracts with domestic electric vehicle brands.
Among diversified automotive electronics conglomerates, Denso Corporation and Robert Bosch GmbH represent the integrated leader archetype with sensor fusion capabilities. Continental AG occupies a position within the tier-one supplier tier serving multiple OEM platforms. Panasonic Corporation and Sony Electronics exemplify the component technology anchor pattern, supplying image sensors across module houses. BYD Semiconductor and Sunny Smartlead sit within the domestic specialist tier, with the former representing captive vertical integration and the latter exemplifying optical module cost engineering for mid-tier channels.
| Leading Market Players |
|---|
| Denso Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Delphi Automotive PLC |
| Autoliv Inc |
| Panasonic Corporation |
| Sony Electronics |
| Sunny Smartlead |
| BYD Semiconductor |
| Others |
Value Chain & Pricing Dynamics
MIIT's GB/T type approval regime gates supplier qualification and simultaneously stratifies price tiers across the China automotive camera market, with compliance certification separating premium module houses from cost-optimized alternatives.
Pricing Analysis
Long-term offtake contracts dominate procurement between Yangtze River Delta module houses and domestic electric vehicle OEMs, while spot purchasing persists in aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with MIIT-compliant digital modules commanding premiums over analog alternatives. Pricing pressure stems from foundry volatility at mature-node fabs for image signal processors. Fleet operators exhibit lowest price sensitivity due to procurement consolidation, while DIY kit buyers in replacement channels drive cost compression.
Supply Chain Analysis
Mature-node wafer capacity at Taiwan and South Korea foundries anchors image signal processor supply for China automotive camera production. The supply chain draws from automotive-grade CMOS sensors, specialized lens glass, and high-tolerance packaging substrates. Single-source vulnerability concentrates at tier-one ISP wafer suppliers. Distribution runs through tier-one OEM procurement teams co-located in Shanghai-Suzhou clusters, with direct-to-assembly-line logistics bypassing traditional warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China automotive camera market sits in cyclical recovery as electric vehicle platform launches accelerate camera content per vehicle under MEE dual carbon policy enforcement.
For Market Incumbents: Secure exclusive design contracts with domestic electric vehicle brands before analog-to-digital architecture transitions complete. Lock in captive wafer supply agreements with Taiwan foundries to insulate margins against capacity allocation shocks. Prioritize backward integration into image signal processor design to defend against pure-play lens assemblers encroaching on premium tiers. For New Entrants and Emerging Players: Differentiate on firmware configurability for fleet operator procurement consolidation, where standardized modules span multiple vehicle platforms. Target tier-two cities in Jiangsu and Zhejiang provinces for aftermarket channel penetration under SAMR certification requirements. Lead with cost-engineered optical modules for entry-grade vehicle configurations where analog inventory still moves. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across semiconductor-module integrated production as edge processing requirements embed higher-capacity processors into camera housings. Acquisition targets should show in-house sensor fusion capabilities or captive image signal processor supply. Watch for GB standard revision announcements as the signal indicating analog inventory obsolescence timelines and digital architecture transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Stack Development | Robert Bosch GmbH anchors premium OEM contracts through integrated camera-radar-lidar data processing. |
| Captive Wafer Supply Agreement | BYD Semiconductor insulates margins against Taiwan foundry volatility through in-house image signal processor production. |
| Exclusive Module Design Contract | Domestic electric vehicle brands negotiate volume commitments with Yangtze River Delta suppliers for platform-specific configurations. |
| Firmware Configurability Investment | Fleet operators consolidate procurement around standardized modules replacing hardware SKU diversity with software-defined variants. |
| Aftermarket Certification Pathway | SAMR quality gates compress development windows for replacement channel entrants targeting high-resolution optical modules. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, vehicle production databases, and tier-one supplier procurement disclosures across the China automotive camera market. Primary interviews captured perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and optical lens design specialists. Secondary validation drew from GB standard revision notices, SAMR certification registries, and electric vehicle platform launch announcements. Bottom-up module shipment estimates triangulated against top-down vehicle production projections.
Segmentation dimensions modeled include product type, technology architecture, end-user category, and installation method across the projection horizon. Vehicle class, propulsion architecture, and content per vehicle informed volume scaling. CAGRs derived from regression analysis against historical adoption curves for camera-based ADAS features, adjusted for MIIT mandate acceleration effects and electric vehicle platform bundle rates.
Material uncertainties — foundry capacity reallocation, GB standard revision timing, and analog inventory obsolescence — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and electric vehicle penetration trajectories. Practitioners should keep alternative scenarios live as MIIT connected vehicle data requirements and MEE dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Automotive Smart Key Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Automotive Fuse Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market