
 Automotive Driver Drowsiness Detection System Market | 2026-2036
Automotive Driver Drowsiness Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Driver Drowsiness Detection System Market Intelligence
The drowsiness detection market is pivoting on a widening gap between embedded OEM systems and aftermarket add-ons. Valeo SA leverages its integrated sensor portfolio to anchor premium vehicle programs. Robert Bosch GmbH competes through manufacturing scale across European and Asian supply chains. Smart Eye Aktiebolag specializes in algorithm-driven eye-tracking software that differentiates its licensing model from hardware-centric rivals.
Automotive driver drowsiness detection systems combine optical sensors, infrared illumination, and machine-vision algorithms to measure eyelid closure duration, head pose angles, and gaze deviation with sub-millimeter precision at 60 Hz sampling rates. These systems issue real-time alerts to prevent fatigue-related collisions in long-haul trucking and passenger transport. Camera-based technology dominates current installations due to declining CMOS sensor costs and mature image-processing pipelines. Electric vehicle applications are expanding fastest as cabin-integration engineering cycles compress with skateboard platforms. Fleet operators represent a concentrated margin pool where volume procurement and telematics integration drive pricing power.
NHTSA guidelines in the United States, Euro NCAP assessment protocols in Europe, and Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval standards collectively mandate or incentivize driver monitoring capability in new vehicle categories. These frameworks shape product specifications around data privacy, alert latency thresholds, and fail-safe redundancies. Stakeholders must weigh algorithm accuracy against sensor hardware costs as regulatory timelines tighten and OEMs consolidate supplier bases.
Market Dynamics
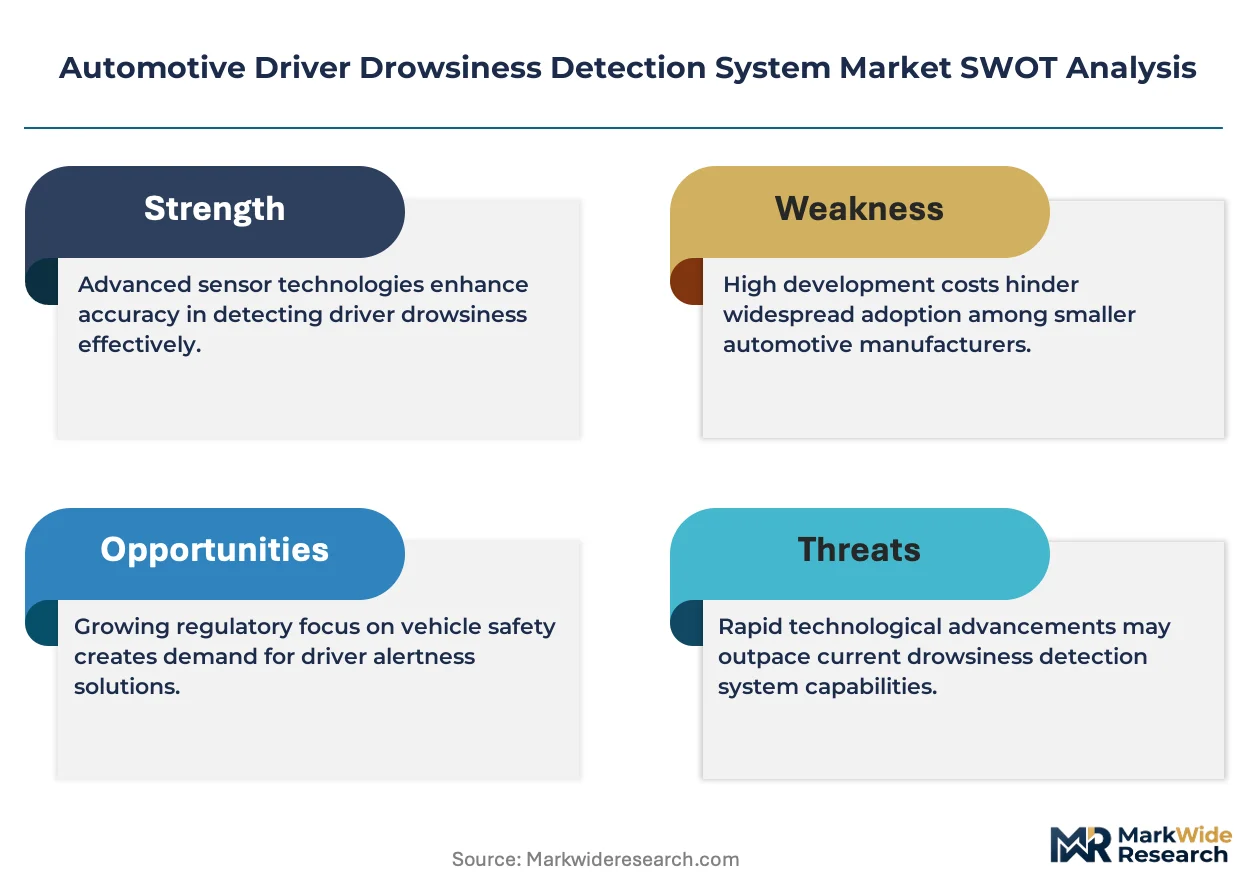
The automotive driver drowsiness detection market is bifurcating between embedded OEM architectures and modular aftermarket solutions, with regulatory mandates compressing integration timelines and forcing tier-one suppliers to consolidate software-hardware bundles.
Growth Catalysts
- Euro NCAP Protocols:The European safety body's 2023 assessment framework awards points for direct driver monitoring, compelling automakers to install camera-based systems in new vehicle platforms.
- CMOS Sensor Cost Decline:Near-infrared image sensors have dropped below unit economics thresholds that previously blocked mass-market penetration, enabling single-camera cabin monitoring.
- Long-Haul Fleet Concentration:North American trucking operators with 500+ vehicle fleets now mandate drowsiness alerts as standard equipment, creating predictable procurement volumes.
Market Restraints
- Algorithm Validation Burden:NHTSA's pending guidance on driver monitoring system performance testing requires multi-year field studies that delay product launches.
- Illumination Hardware Concentration:High-power infrared LED modules for night-capable eye tracking source from a narrow East Asian supplier base, exposing lead time volatility.
- Privacy Jurisdiction Friction:GDPR's biometric data classification in Europe forces separate hardware configurations from US and Japanese deployments, fragmenting engineering resources.
Strategic Opportunities
- Brazil ANVISA Pathway:Pending type-approval standards for commercial vehicle safety systems will open Latin America's largest automotive market to first-mover suppliers.
- Telematics Convergence:Integration of drowsiness alerts with fleet management platforms creates bundled data services that command recurring revenue models.
- India PLI Incentive:The country's production-linked incentive scheme for automotive electronics subsidizes local camera module assembly, reducing landed cost for domestic OEM programs.
Industry Challenges
- Embedded Software Talent Scarcity:Real-time machine vision engineering for 60 Hz inference pipelines faces acute hiring competition from consumer electronics and robotics sectors.
- ISO 26262 Certification Timelines:Functional safety qualification for ASIL-B rated driver monitoring systems extends development cycles by 18-24 months.
- Legacy CAN Bus Integration:Retrofitting drowsiness alerts into existing vehicle networks requires protocol bridging that adds hardware cost and diagnostic complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Driver Drowsiness Detection System Market |
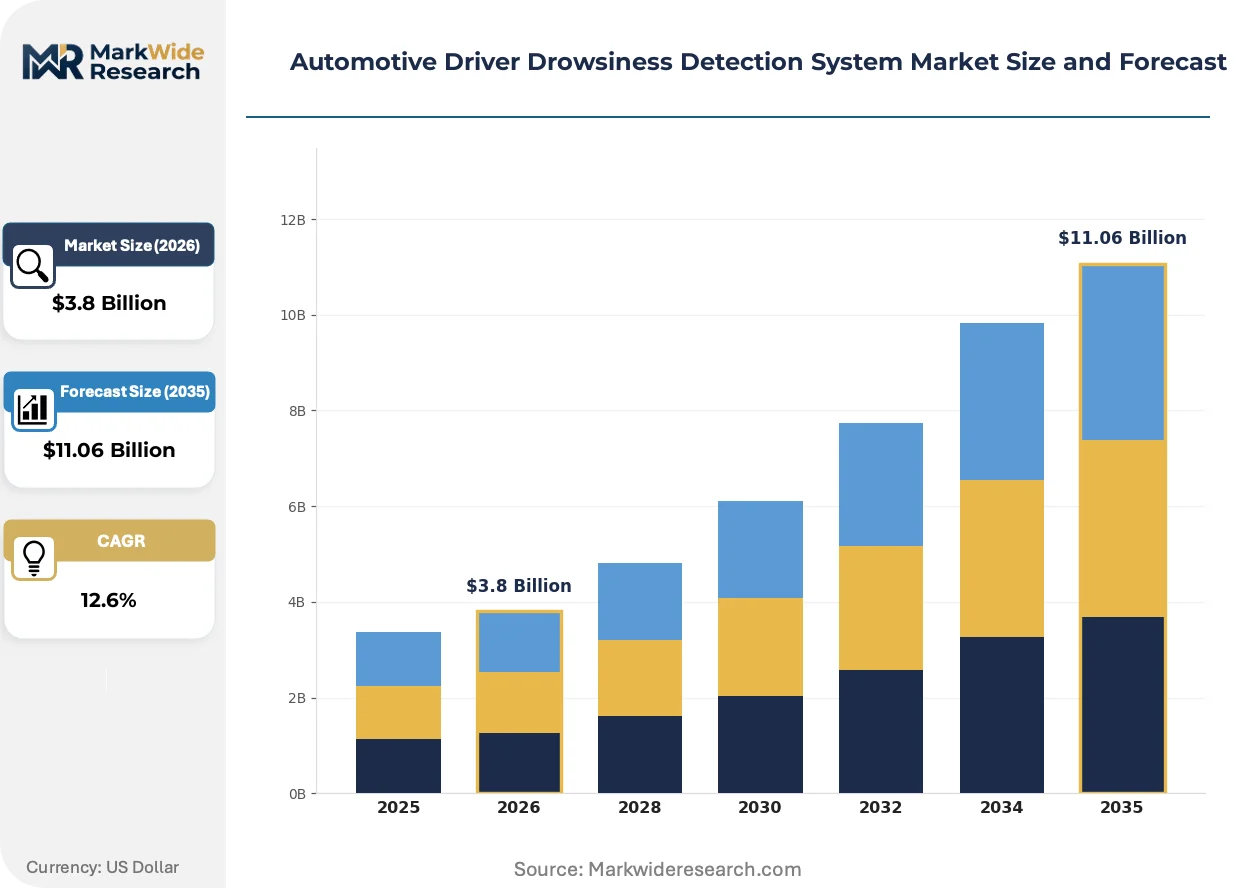
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Camera-Based, Infrared Sensors, EEG Sensors, Steering Pattern Analysis, Radar Sensors Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles, Public Transport Fleet End User: Vehicle Manufacturers, Fleet Operators, Insurance Companies, Ride-Hailing Services Deployment Type: Embedded Systems, Aftermarket Devices, Integrated Solutions, Smartphone-Based Apps |
| Companies Covered | Valeo SA, Smart Eye Aktiebolag, Robert Bosch GmbH, Magna International Inc., Autoliv Inc., Continental Aktiengesellschaft, Seeing Machines Limited, Toyota Motor, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Driver Drowsiness Detection System Market Strategic Shifts & Innovations
Sensor fusion architectures and edge computing migration are compressing the latency between fatigue detection and driver alert, while regulatory fragmentation forces modular platform designs.
Time-of-flight depth sensors are integrating with conventional RGB-I cameras to enable 3D head pose estimation without calibration-dependent 2D approximations. Tier-one seating suppliers are adopting these fused modules for integrated headrest monitoring. This convergence is integrating physiological signal capture—heart rate variability from micro-movements—into single hardware units that reduce per-vehicle bill-of-materials.
Japan's Ministry of Land, Infrastructure, Transport and Tourism revised type-approval standards in 2024 to mandate driver state monitoring for highway coaches and heavy trucks. The regulation requires fail-safe operation during sensor occlusion events. Domestic OEMs are responding with redundant camera placements and thermal fallback sensors that maintain compliance under sunglasses or low-light conditions.
Fleet procurement has moved from discrete hardware purchases to integrated safety-as-a-service contracts where drowsiness detection bundles with insurance premium reductions. Telematics providers are displacing standalone aftermarket vendors by offering camera hardware at marginal cost against multi-year data subscriptions. This shift concentrates buyer power among US and German fleet operators with sufficient scale to negotiate enterprise-wide rollouts.
Automotive Driver Drowsiness Detection System Market Segmentation
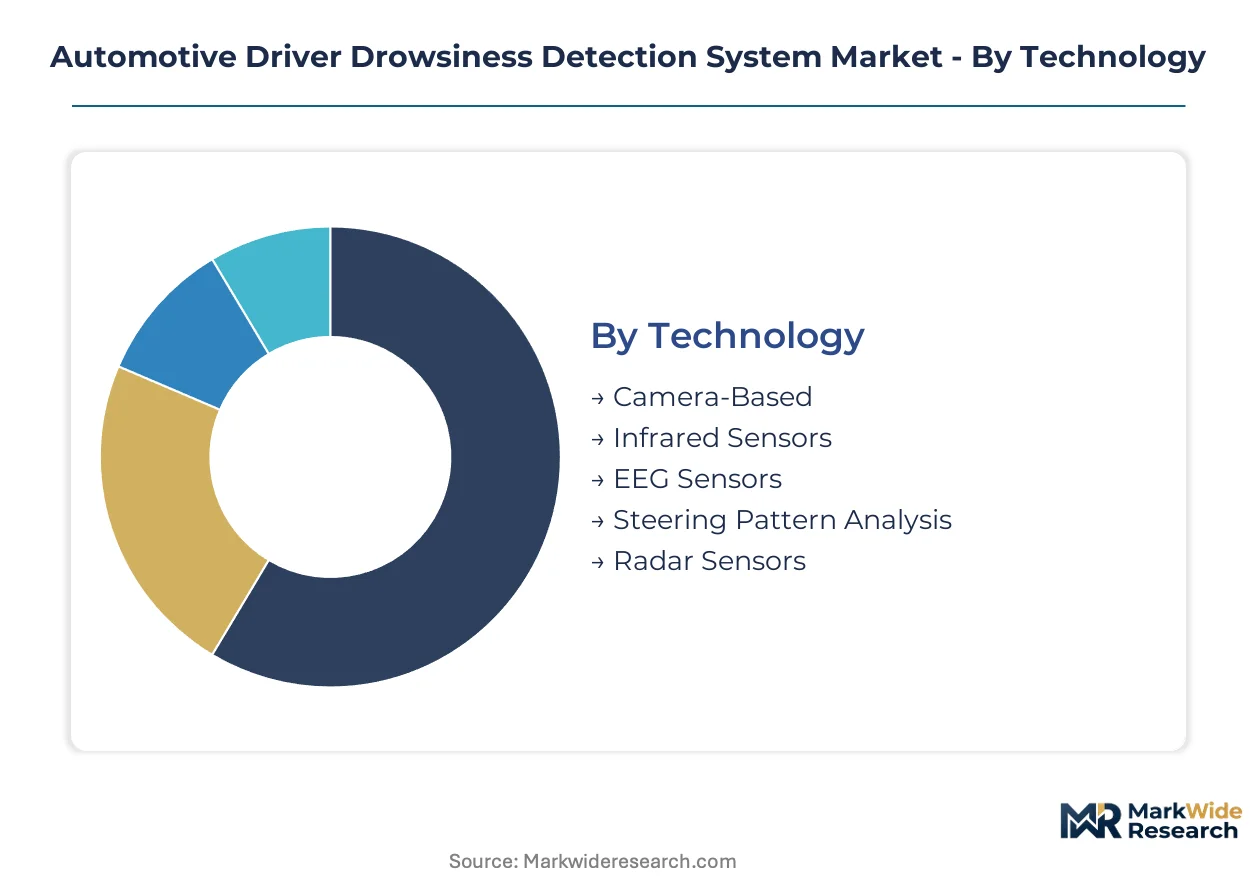
Segmentation in the drowsiness detection market reveals distinct engineering requirements across standalone and embedded integration paths. Each category shapes procurement patterns, supplier margins, and regulatory compliance obligations differently.
Technology:
Standalone deployments favor modular sensor packages, while embedded architectures demand tight integration with vehicle compute platforms and power distribution networks.
- Camera-Based:Near-infrared CMOS arrays with 940 nm illumination capture eyelid closure and head pose at 60 Hz frame rates. German OEM programs and North American fleet retrofits drive the bulk of unit demand, constrained by GDPR biometric classification in European deployments.
- Infrared Sensors:Discrete IR emitters and photodiodes measure periorbital reflectance patterns without full imaging pipelines. Japanese heavy truck mandates from the Ministry of Land, Infrastructure, Transport and Tourism accelerate adoption for highway coach compliance.
- EEG Sensors:Forehead-mounted dry electrodes detect alpha wave attenuation indicative of microsleep onset.
- Steering Pattern Analysis:Torque sensor fusion with EPS systems identifies erratic correction patterns without cabin-facing hardware.
- Radar Sensors:60 GHz FMCW modules monitor chest wall motion for respiration-derived fatigue indicators.
Volume placements concentrate in Camera-Based systems; the faster expansion belongs to Infrared Sensors.
Application:
Cost tier stratification separates premium cabin architectures from mass-market compliance-driven installations.
- Passenger Cars:Dashboard-integrated camera modules with ASIL-B functional safety ratings serve Euro NCAP point-scoring requirements. German and US OEMs embed these in B-segment and above platforms, with software licensing costs dominating per-unit economics.
- Commercial Vehicles:Long-haul trucking mandates from US fleet operators with 500+ vehicle holdings standardize drowsiness alerts. Insurance premium reductions tied to telematics integration create procurement bundles that squeeze standalone hardware margins.
- Electric Vehicles:Skateboard platform engineering cycles compress cabin integration timelines, enabling faster sensor fusion adoption.
- Luxury Vehicles:Multi-camera architectures with redundant coverage command premium pricing for occupant monitoring expansion.
- Public Transport Fleet:Municipal bus operators in Japan face type-approval deadlines requiring fail-safe operation during sensor occlusion.
Commercial Vehicles dominate current volume; Electric Vehicles are climbing the fastest as platform consolidation accelerates.
End User:
Customer type determines contract structure, with OEMs demanding multi-year supply agreements and fleet operators favoring safety-as-a-service subscriptions.
- Vehicle Manufacturers:Tier-one integration contracts span 7-10 year platform lifecycles with penalty clauses for ASIL certification delays. German and Japanese OEMs consolidate supplier bases around sensor-software bundles that reduce qualification overhead.
- Fleet Operators:Telematics providers displace aftermarket vendors by bundling camera hardware at marginal cost against recurring data subscriptions. US and German operators with enterprise scale negotiate volume pricing that compresses standalone device markets.
- Insurance Companies:Usage-based policy discounts incentivize retrofitted monitoring in commercial auto lines.
- Ride-Hailing Services:Driver verification and fatigue alerts address liability exposure in high-utilization vehicle pools.
Vehicle Manufacturers anchor procurement volume; Fleet Operators are gaining share fastest through subscription model displacement.
Deployment Type:
Integration depth shapes margin structure, with embedded systems capturing software recurring revenue and aftermarket devices competing on hardware cost.
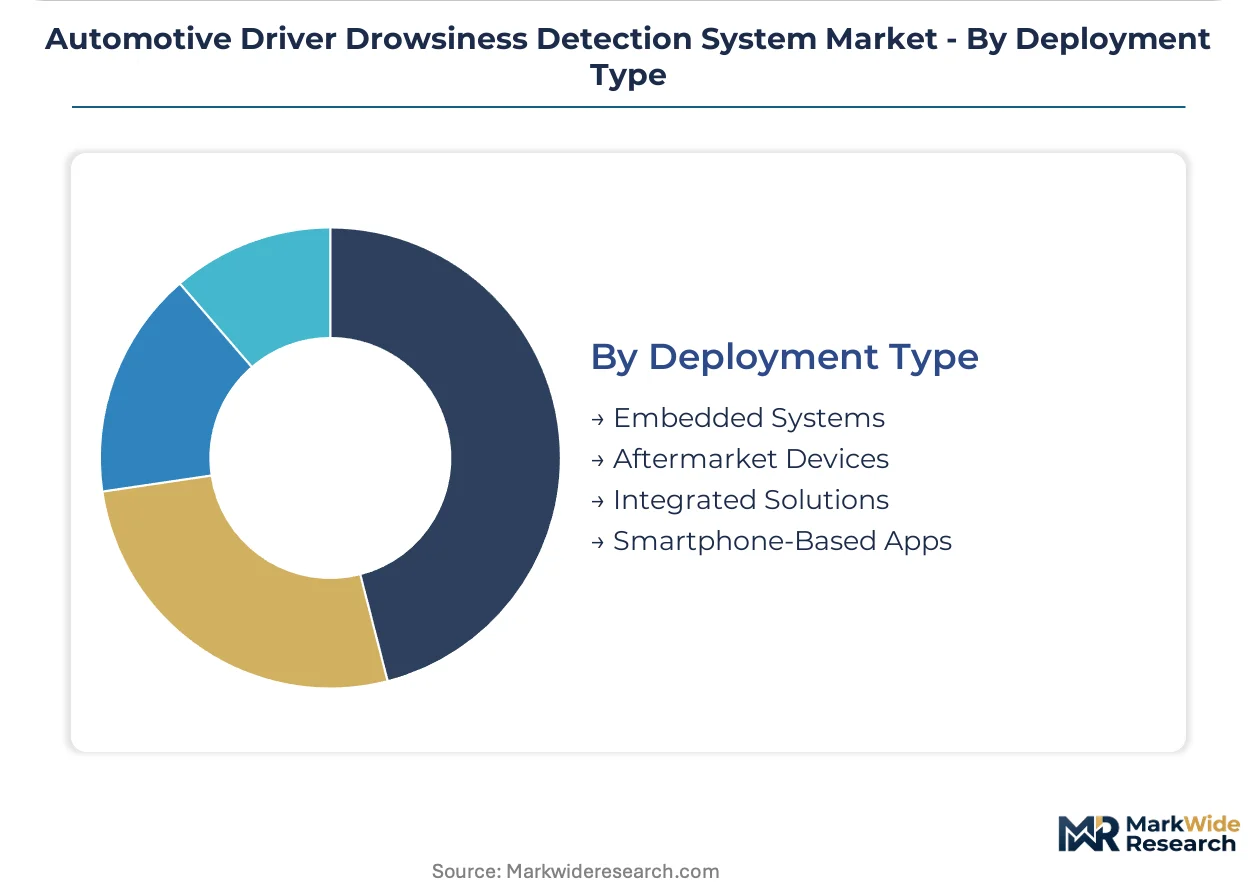
- Embedded Systems:Domain controller integration with centralized compute enables over-the-air algorithm updates and feature expansion. Japanese OEMs lead in redundant camera placements for regulatory compliance, while European programs navigate GDPR hardware fragmentation.
- Aftermarket Devices:Windshield-mounted cameras with standalone processing appeal to fleet retrofit budgets and legacy vehicle pools. Price competition from Chinese module suppliers erodes hardware margins in North American distribution channels.
- Integrated Solutions:Tier-one seating suppliers embed fused RGB-I and time-of-flight modules in headrest assemblies.
- Smartphone-Based Apps:Front-facing camera software leverages consumer device penetration for low-cost driver monitoring.
Embedded Systems command the steepest expansion trajectory; Aftermarket Devices retain volume concentration in fleet retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European sensor integration engineering, while Detroit and Tokyo drive divergent regulatory compliance paths for camera-based driver monitoring systems.
United States
Long-haul fleet operators with 500-plus vehicle holdings mandate drowsiness alerts as standard equipment. NHTSA guidelines on driver monitoring system performance testing shape product validation timelines. Michigan's automotive corridor concentrates tier-one supplier engineering centers for Detroit Three OEM programs.
Germany
Premium vehicle manufacturers embed camera-based systems to capture Euro NCAP safety rating points. KBA type-approval standards enforce functional safety requirements for series production. Baden-Württemberg hosts Valeo SA and Robert Bosch GmbH sensor development facilities serving domestic OEM platforms.
Japan
Highway coach and heavy truck operators face Ministry of Land, Infrastructure, Transport and Tourism deadlines for driver state monitoring compliance. Revised 2024 type-approval standards mandate fail-safe operation during sensor occlusion. Nagoya's Chubu region concentrates DENSO Corporation and Toyota Motor integration engineering for domestic commercial vehicle programs.
China
Electric vehicle skateboard platforms compress cabin integration timelines for sensor fusion adoption. MIIT automotive electronics standards shape domestic certification requirements. Yangtze River Delta clusters in Shanghai and Suzhou host CMOS sensor module assembly operations serving local OEM procurement.
India
Commercial vehicle safety retrofit demand concentrates in long-distance trucking corridors. PLI scheme subsidies for automotive electronics reduce landed costs for domestic camera module assembly. Tamil Nadu's Sriperumbudur automotive belt anchors supplier engineering for fleet operator procurement programs.
Automotive Driver Drowsiness Detection System Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the drowsiness detection value chain. Tier-one automotive suppliers with integrated manufacturing footprints face algorithm specialists licensing software to OEMs without captive sensor production. The market structure separates hardware-centric sensor integrators, software-driven eye-tracking licensors, and full-stack system architects. Consolidation pressures intensify as Euro NCAP deadlines force OEMs to reduce qualified supplier lists. Strategic moves concentrate on sensor-software bundling and cross-border engineering partnerships.
Within the tier-one integrated tier, Valeo SA and Robert Bosch GmbH exemplify capital-intensive manufacturing scale across European and Asian supply chains. Smart Eye Aktiebolag occupies a position among asset-light algorithm specialists licensing machine-vision software without hardware production obligations. These three anchors represent divergent competitive archetypes: full-stack system integration, manufacturing-scale component supply, and pure-play intellectual property licensing.
| Leading Market Players |
|---|
| Valeo SA |
| Smart Eye Aktiebolag |
| Robert Bosch GmbH |
| Magna International Inc. |
| Autoliv Inc. |
| Continental Aktiengesellschaft |
| Seeing Machines Limited |
| Toyota Motor |
| DENSO Corporation |
| Others |
Cost & Logistics Intelligence
Captive sensor-software bundling by tier-one suppliers anchors both supply positioning and pricing power in the drowsiness detection market. Euro NCAP compliance deadlines force OEMs to consolidate qualified supplier lists, compressing hardware margins while elevating licensing fees for algorithm providers.
Pricing Analysis
Value-based pricing anchored to insurance premium reductions and collision avoidance outcomes dominates fleet procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-B certified embedded systems from aftermarket retrofit modules and smartphone-based applications. Pricing pressure stems from Chinese CMOS module suppliers entering North American distribution channels. Fleet operators with enterprise scale exhibit lowest price sensitivity; standalone aftermarket buyers face highest cost compression.
Supply Chain Analysis
Dual-sourcing requirements for infrared LED modules and near-infrared image sensors force tier-one suppliers to qualify secondary vendors across Taiwan, South Korea, and Japan. High-power 940 nm illumination components and automotive-grade CMOS arrays feed from concentrated East Asian fabrication networks. Single-source vulnerability in specialized IR emitter production exposes lead time volatility. Distribution runs through tier-one seating suppliers and telematics platform providers rather than discrete hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures intensify as Euro NCAP deadlines compress OEM qualification timelines, forcing sub-scale algorithm developers toward acquisition or exit.
For Market Incumbents: To counter displacement by telematics providers bundling hardware at marginal cost, tier-one suppliers should deepen captive production of infrared illumination modules in Taiwan and South Korea. Certification investment in ISO 26262 ASIL-B pathways creates switching costs that protect long-term supply agreements with German and Japanese OEMs. For New Entrants and Emerging Players: The price-point gap between premium embedded systems and economy aftermarket devices offers entry space for modular camera-software bundles targeting Indian commercial vehicle retrofits. Brazil's pending ANVISA type-approval standards present the most penetrable regulatory window. Licensing algorithm IP to regional seating suppliers enables faster market access than hardware manufacturing scale-up. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by tier-one automotive suppliers seeking algorithm differentiation. Long-term viability favors asset-light software licensors with established OEM validation over capital-intensive hardware integrators. Watch NHTSA driver monitoring performance guidance release as inflection indicator for regulatory-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Software Bundle Consolidation | Reduces OEM qualification overhead ahead of Euro NCAP deadlines. |
| Dual-Sourcing Qualification Programs | Mitigates lead time volatility in East Asian IR component supply. |
| Telematics Platform Integration | Enables recurring revenue models through fleet safety-as-a-service contracts. |
| ASIL-B Certification Investment | Creates functional safety barriers against lower-tier competitors. |
| Regional Manufacturing Localization | Captures India PLI subsidies and reduces landed cost for domestic OEM programs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet telematics operators combined with secondary sources including NHTSA guidance documents, Euro NCAP assessment protocols, and vehicle production databases. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates.
Data-stream reconciliation across technology, application, and deployment type dimensions shaped the analytical framework over the projection horizon. Modeled segments span camera-based, infrared, and fusion architectures; passenger car, commercial vehicle, and electric vehicle applications; and embedded, aftermarket, and integrated deployment paths. CAGRs derived from regression analysis against regulatory mandate timelines and CMOS sensor cost curves. Forecast inputs incorporated fleet operator procurement survey data and OEM platform lifecycle disclosures.
Underlying measurement precision varies by segment; embedded system volumes carry tighter precision than aftermarket retrofit estimates due to consolidated OEM reporting. Forecasts reflect assumptions around regulatory enforcement timing and sensor cost trajectories. Deviation in NHTSA final rule publication or East Asian semiconductor export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Global Emergency Locking Retractor Seatbelt Market
Automotive Safety and Security Systems
Global Automotive Braking System Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Driving Armor Market