
 Automotive Speedometer Cable Market | 2026-2036
Automotive Speedometer Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Speedometer Cable Market Outlook
OEM-grade cable assemblies with enhanced vibration resistance is redrawing procurement criteria across the automotive speedometer cable landscape. Continental AG leverages its integrated powertrain electronics footprint to sustain aftermarket channel dominance in European passenger car segments. Yazaki Corporation anchors its position through specialized connector integration that bridges mechanical and digital instrumentation architectures. Sumitomo Electric Industries competes on material science leadership, particularly in alloy-core cables for heavy-duty commercial applications.
An automotive speedometer cable is a flexible mechanical transmission element, typically comprising a multi-layer steel wire core sheathed in lubricated polyethylene or metal housing, designed to translate rotational motion from a vehicle transmission output to an analog gauge display. The cable assembly segment commands the largest installed base due to persistent demand in legacy vehicle fleets and emerging-market commercial production, while the speed sensor category captures accelerated growth as electronic instrument clusters displace mechanical gauges in new vehicle platforms. OEMs and Tier-1 suppliers concentrate procurement on pre-terminated cable assemblies with integrated connector kits to reduce assembly-line labor, whereas aftermarket providers favor repair kit configurations that address fragmented vehicle parc maintenance needs across diverse model years.
NHTSA enforces odometer accuracy standards that mandate precise cable calibration and durability testing for US-market vehicles, while the EU ECE R39 regulation governs speedometer indication tolerances and directly influences cable specification thresholds for European type approval. India's BIS certification requirements for automotive components create additional compliance layers for suppliers targeting the country's expanding commercial vehicle and two-wheeler replacement markets. Stakeholders must monitor the pace of digital cluster penetration versus mechanical gauge retention across emerging-market vehicle segments to calibrate product portfolio allocations between traditional cable assemblies and electronic speed sensor modules.
Market Dynamics
The collision between mechanical gauge retention in cost-sensitive vehicle segments and electronic cluster penetration in premium platforms is fragmenting procurement patterns across automotive speedometer cable supply chains. Tier-1 suppliers face divergent tooling investments as OEMs split platform architectures between analog and digital instrumentation.
Growth Catalysts
- NHTSA odometer accuracy enforcement:Mandated calibration precision sustains replacement demand for certified cable assemblies in US commercial vehicle fleets.
- India BIS certification expansion:Strengthened domestic content requirements for automotive components protect local cable manufacturers from import competition.
- Polymer-sheathed alloy cores:Advanced material formulations extend service intervals in heavy-duty agricultural equipment operating across Brazil's Mato Grosso soybean belt.
Market Restraints
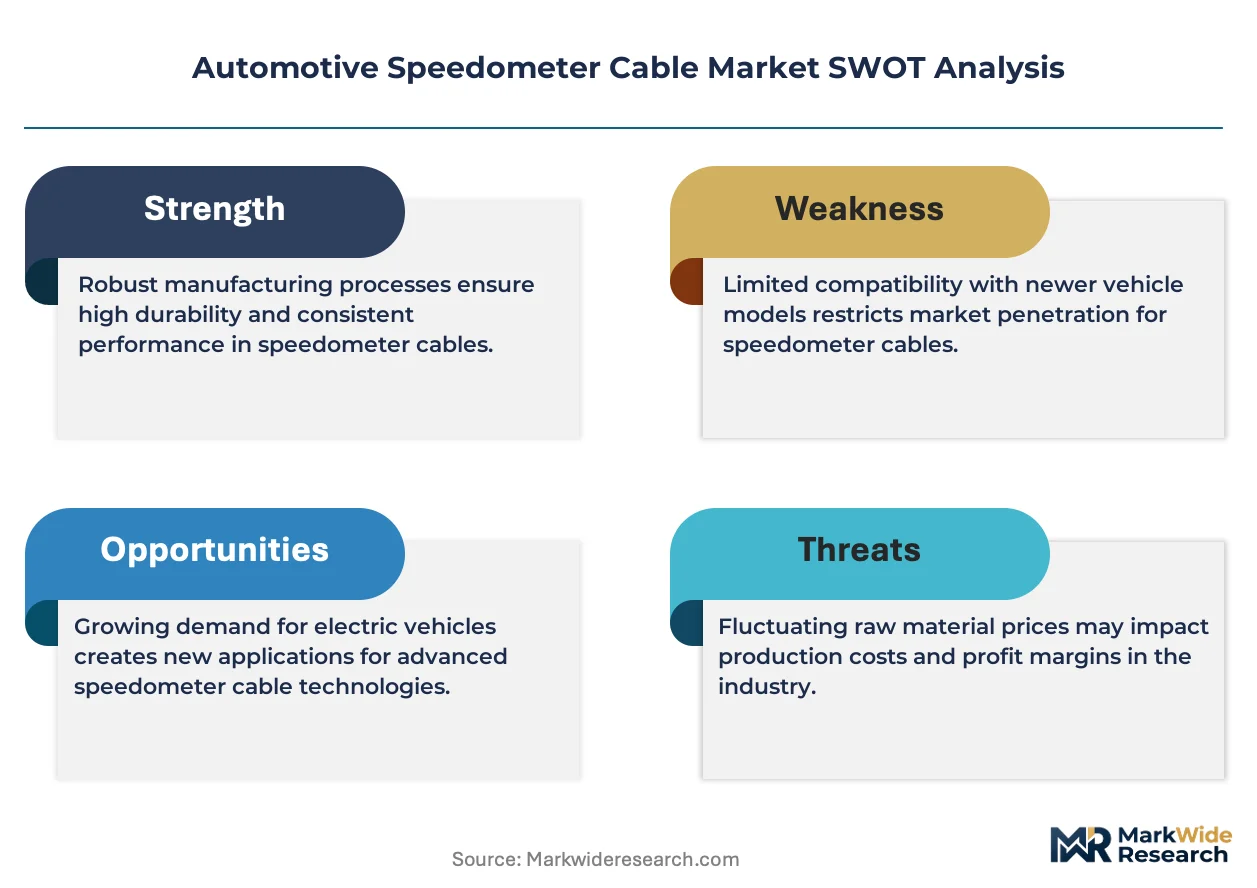
- Steel wire volatility:Fluctuations in high-carbon steel rod pricing compress margin stability for cable core manufacturers.
- Supplier concentration in Maharashtra:India's cable assembly production clusters around Pune-Nashik corridor, creating single-point disruption exposure.
- Electronic speed sensor substitution:Hall-effect and magnetoresistive sensors eliminate mechanical transmission needs in new passenger car platforms.
Strategic Opportunities
- Vietnam two-wheeler aftermarket:Expanding motorcycle parc in Hanoi and Ho Chi Minh City corridors generates replacement cable demand beyond domestic production capacity.
- EU ECE R39 revision pathway:Anticipated tolerance tightening for speedometer indication creates upgrade cycles for precision-calibrated assemblies.
- Hybrid analog-digital bridges:Connector-integrated cable systems serving transitional instrument clusters capture value from platform migration periods.
Industry Challenges
- Tooling amortization compression:Shortening vehicle platform lifecycles prevent full capital recovery on mechanical gauge-specific cable dies.
- Cross-platform certification stacking:Simultaneous NHTSA, ECE R39, and BIS compliance testing extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Speedometer Cable Market |
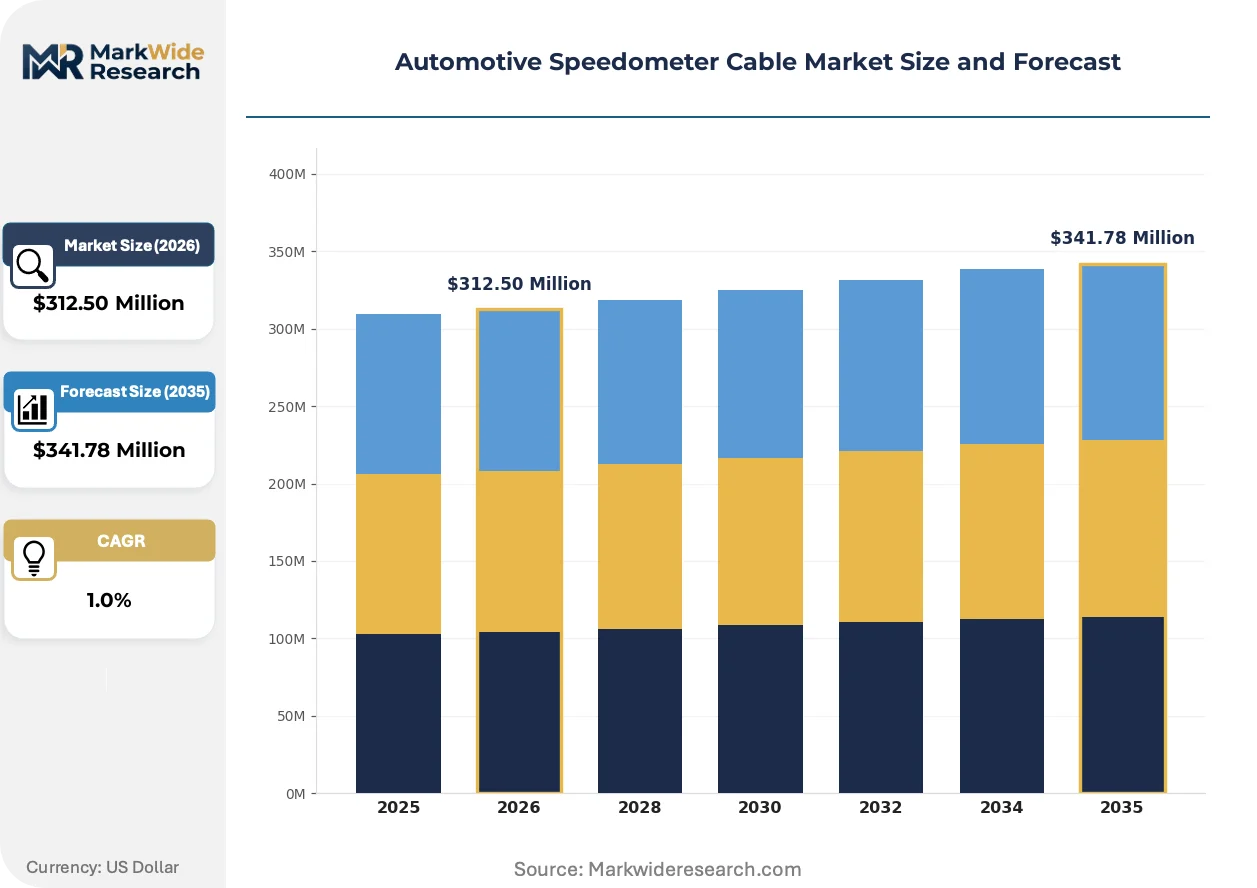
| Market Size in 2026 | $312.50 Million |
| Market Size in 2035 | $341.78 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Assembly, Speed Sensor, Connector Kit, Repair Kit End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation: Onboard Diagnostics, Manual Installation, Workshop Services, Retail Services Material: Copper, Plastic, Rubber, Alloy |
| Companies Covered | Silco Automotive Solution LLP, Continental AG, ATP Automotive, Yazaki Corporation, BorgWarner Inc., Speedy Cables (London) Ltd., Denso Corporation, Sumitomo Electric Industries, R.S. International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Speedometer Cable Market Strategic Shifts
Material science advances and regulatory precision mandates are splitting the speedometer cable market into distinct performance tiers. Manufacturers must now engineer simultaneously for legacy mechanical durability and transitional electronic compatibility.
Self-lubricating polymer compounds with embedded friction-reducing additives are extending cable service life in high-vibration commercial vehicle applications. Fleet operators in India's Tamil Nadu logistics corridor specify these formulations for tipper trucks operating on unpaved mining access roads. The technology is bifurcating procurement specifications between premium long-life cables and economy replacement grades.
ECE R39 speedometer tolerance standards are tightening calibration requirements for European type approval. Cable manufacturers must now implement laser-measured core winding processes to achieve sub-one-percent rotational variance. German KBA certification audits are driving consolidation among smaller suppliers unable to invest in precision metrology equipment.
Aftermarket distributors in Southeast Asia are unbundling cable repair kits from full assembly offerings to serve fragmented vehicle parc maintenance. Independent workshops in Indonesia's Surabaya commercial hub prefer component-level procurement over pre-terminated assemblies. This pattern concentrates margin pressure on kit assemblers while shifting value toward specialized connector and lubricant suppliers.
Automotive Speedometer Cable Market Segmentation
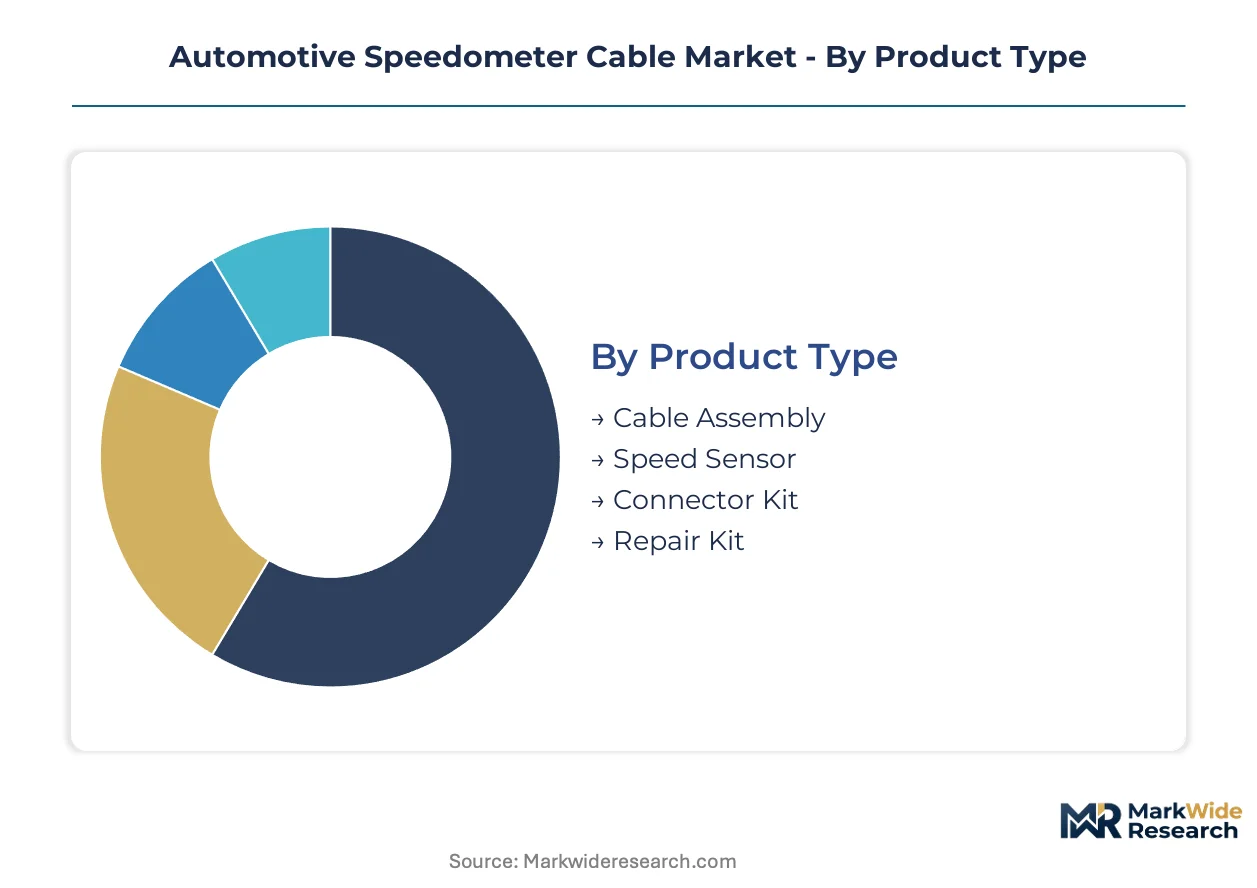
Automotive speedometer cable procurement splits sharply between legacy mechanical assemblies and emerging electronic substitutes. Channel strategy must align with whether customers need full OEM integration or fragmented aftermarket repair solutions.
Product Type:
OEMs and Tier-1 suppliers route cable assemblies and speed sensors through pre-terminated supply chains, while aftermarket providers push connector kits and repair kits through independent workshop networks.
- Cable Assembly:Multi-layer steel wire core sheathed in lubricated polyethylene translates rotational motion from transmission outputs to analog gauges. Demand concentrates in India's commercial vehicle hubs and Brazil's agricultural equipment belt where mechanical instrumentation persists in cost-sensitive applications. NHTSA odometer accuracy enforcement sustains replacement cycles in US commercial fleets.
- Speed Sensor:Hall-effect and magnetoresistive modules eliminate mechanical transmission by converting rotational data directly to electronic signals. Electronic cluster penetration in premium passenger vehicles accelerates sensor procurement through integrated powertrain electronics channels. EU ECE R39 tolerance tightening drives precision calibration requirements.
- Connector Kit:Specialized bridge components linking mechanical cables to transitional hybrid instrument clusters.
- Repair Kit:Unbundled components serving fragmented vehicle parc maintenance across diverse model years in Southeast Asia.
By volume, Cable Assembly leads. By growth pace, Speed Sensor is expanding most quickly.
End User:
Cost tier differentiation separates high-volume OEM contracts from margin-rich aftermarket services, with Tier-1 suppliers capturing intermediate value through integrated assembly provision.
- OEMs:Vehicle manufacturers specify pre-terminated cable assemblies with integrated connector kits to reduce assembly-line labor. Procurement concentrates on vibration-resistant formulations for platform durability.
- Aftermarket Providers:Distributors in India's Pune-Nashik corridor and Vietnam's Hanoi-Ho Chi Minh City corridors generate replacement cable demand beyond domestic production capacity. Repair kit configurations address fragmented maintenance needs.
- Vehicle Assemblers:Final-stage production facilities in emerging markets sourcing certified assemblies for local content compliance.
- Tier-1 Suppliers:Integrated powertrain specialists bridging mechanical and digital instrumentation architectures through specialized connector integration.
OEMs dominate absolute spend. Aftermarket Providers are gaining share fastest through emerging-market parc expansion.
Installation:
Application complexity determines whether installation flows through diagnostic-integrated service bays or basic retail counter sales.
- Onboard Diagnostics:Electronic speed sensor calibration requiring specialized equipment and software interfaces.
- Manual Installation:Direct cable replacement procedures performed by independent workshops without diagnostic tooling.
- Workshop Services:Full-service commercial vehicle maintenance facilities in Tamil Nadu logistics corridors specifying self-lubricating polymer formulations.
- Retail Services:Counter sales of repair kits to individual vehicle owners in Indonesia's Surabaya commercial hub.
Workshop Services handles the highest transaction volume. Onboard Diagnostics shows the steepest expansion trajectory as electronic clusters proliferate.
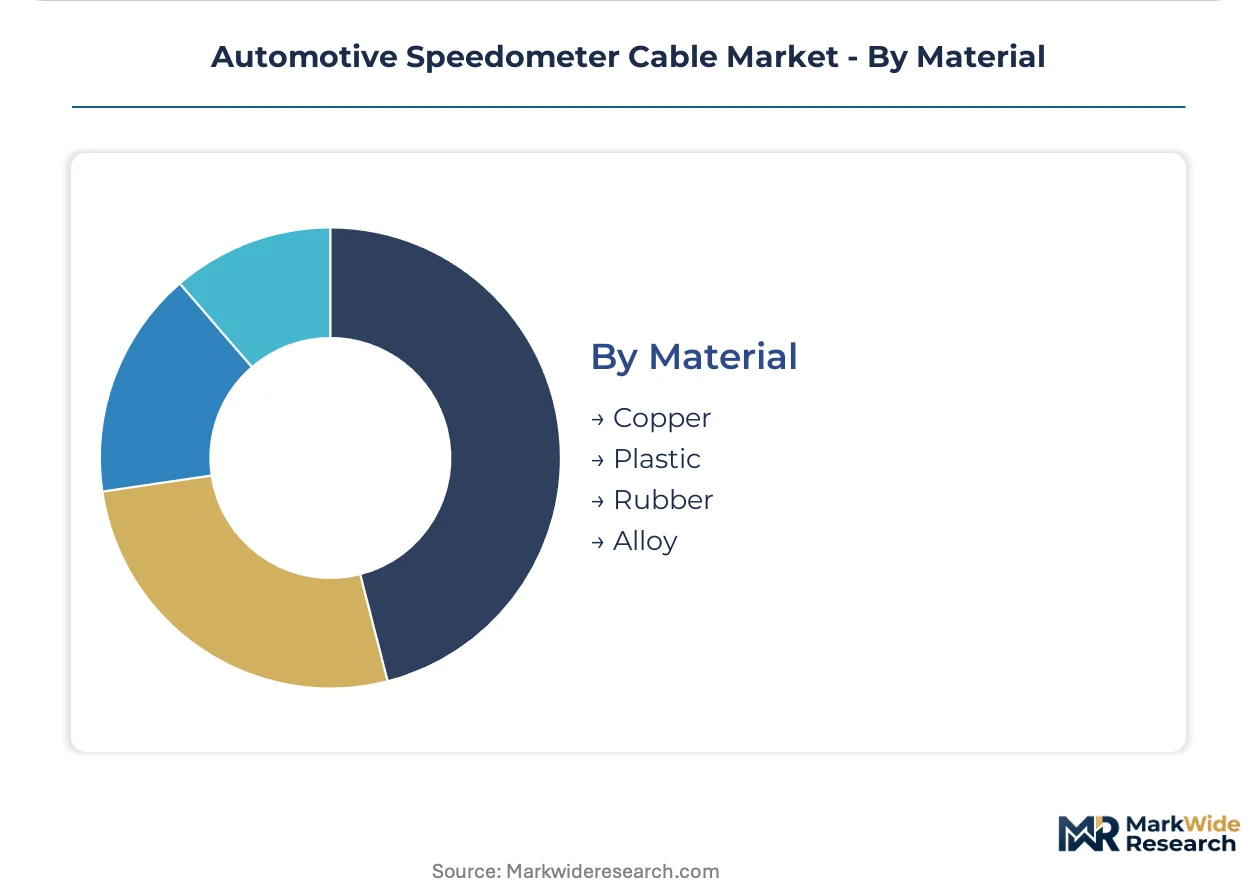
Material:
Supply concentration in Maharashtra's steel rod processing clusters shapes procurement economics for alloy and copper cores.
- Copper:High-conductivity cores for precision signal transmission in electronic speed sensor applications.
- Plastic:Polyethylene sheathing with embedded friction-reducing additives extends service life in high-vibration commercial vehicle applications.
- Rubber:Legacy housing material for economy-grade replacement cables in cost-sensitive emerging markets.
- Alloy:Advanced material formulations from Sumitomo Electric Industries for heavy-duty commercial applications requiring extended service intervals.
Alloy commands premium pricing. Plastic is climbing fastest on polymer science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cable assembly manufacturing clusters heavily in India's Maharashtra state and Germany's industrial belt, with aftermarket distribution networks extending through Brazil's agricultural regions and Southeast Asian commercial corridors. Regulatory divergence across NHTSA, ECE R39, and BIS certification regimes fragments procurement specifications by destination market.
India
Commercial vehicle production in Pune-Nashik corridor sustains mechanical cable demand as cost-sensitive fleets retain analog instrumentation. BIS certification requirements for automotive components protect domestic manufacturers from import competition and mandate specific alloy-core specifications. Tamil Nadu logistics operators specify self-lubricating polymer formulations for tipper trucks on unpaved mining access routes.
Germany
KBA certification audits for ECE R39 speedometer tolerance compliance drive precision metrology investment among cable core manufacturers. Laser-measured core winding processes achieve sub-one-percent rotational variance for European type approval. Stuttgart-area automotive suppliers bridge mechanical and digital instrumentation through specialized connector integration.
Brazil
Agricultural equipment operators across Mato Grosso soybean belt specify extended-service alloy-core cables for harvester fleets. ANVISA-equivalent automotive component standards govern replacement part certification for commercial vehicle maintenance. São Paulo-state distributors stock polymer-sheathed formulations for heavy-duty applications in remote farming regions.
United States
NHTSA odometer accuracy enforcement sustains replacement demand for certified cable assemblies in commercial vehicle fleets. California and Texas logistics hubs specify vibration-resistant formulations for long-haul trucking applications. Rust Belt manufacturing cities retain legacy mechanical gauge production for cost-sensitive fleet vehicle segments.
Vietnam
Expanding motorcycle parc in Hanoi and Ho Chi Minh City corridors generates replacement cable demand beyond domestic production capacity. Aftermarket distributors unbundle repair kits to serve independent workshop networks. Ho Chi Minh City commercial hubs source connector-integrated assemblies for transitional hybrid instrument clusters.
Automotive Speedometer Cable Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the speedometer cable supply base. The market structure tiers into precision-calibration specialists serving European OEMs, volume manufacturers capturing emerging-market aftermarket demand, and integrated powertrain electronics providers bridging mechanical-to-digital transitions. Dominant competitive moves include geographic expansion into Southeast Asian two-wheeler corridors and portfolio diversification toward hybrid analog-digital connector systems.
Within the integrated electronics tier, Continental AG and Yazaki Corporation occupy positions bridging mechanical transmission and digital instrumentation architectures. Sumitomo Electric Industries exemplifies material science specialization through alloy-core cable leadership for heavy-duty commercial applications. Speedy Cables (London) Ltd. represents legacy aftermarket-focused fabrication serving fragmented vehicle parc maintenance needs across diverse European model years.
| Leading Market Players |
|---|
| Silco Automotive Solution LLP |
| Continental AG |
| ATP Automotive |
| Yazaki Corporation |
| BorgWarner Inc. |
| Speedy Cables (London) Ltd. |
| Denso Corporation |
| Sumitomo Electric Industries |
| R.S. International |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates above 85 percent at Maharashtra's Pune-Nashik cable assembly clusters create scale economies that compress price floors for economy-grade mechanical cables while sustaining premium margins for ECE R39-certified precision assemblies. This concentration of alloy-core drawing capacity and polymer compounding infrastructure in western India shapes procurement negotiations across both OEM and aftermarket channels.
Pricing Analysis
ECE R39 speedometer tolerance standards dictate the pricing tier structure across European-bound cable assemblies, separating laser-calibrated precision grades from standard commercial vehicle specifications. Price differentiation hinges on KBA certification audit compliance and vibration-resistance formulation tiers. Cost compression in economy replacement cables is intensifying because of steel wire rod volatility and unbundled repair kit proliferation in Southeast Asian aftermarket channels. Fleet procurement officers at India's Tamil Nadu logistics operators demonstrate highest price sensitivity, while German OEM platform engineers prioritize calibration precision over unit cost.
Supply Chain Analysis
Strait of Malacca transit corridors underpin raw material flows for polymer-sheathed cable formulations serving Southeast Asian two-wheeler aftermarket demand. Manufacturing concentrates in India, Germany, and Brazil, with high-carbon steel rod, lubricated polyethylene compounds, and precision connector components as critical inputs. Single-source vulnerability concentrates in Maharashtra's alloy-core drawing facilities, where localized flooding or labor disruptions cascade through global aftermarket supply. Distribution runs through Tier-1 integrated powertrain channels for OEM pre-terminated assemblies and independent workshop networks for fragmented repair kit fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic speed sensor substitution threatens mechanical cable incumbents with platform-level displacement as digital clusters penetrate premium vehicle segments. Defense strategies must balance legacy fleet service retention against transitional hybrid architecture capture.
For Market Incumbents: Shield core revenue streams by deepening backward integration into alloy-core drawing capacity at India's Pune-Nashik corridor to offset steel rod price volatility. Accelerate ECE R39 precision calibration investments to capture upgrade cycles from tolerance tightening, while deploying connector-integrated cable systems for hybrid analog-digital bridge architectures during platform migration periods.
For New Entrants and Emerging Players: Lead with unbundled repair kit configurations targeting Vietnam's Hanoi-Ho Chi Minh City motorcycle parc expansion, where domestic production capacity lags replacement demand. Capture value from specialized lubricant and connector component supply to independent workshops in Indonesia's Surabaya commercial hub, bypassing capital-intensive full assembly manufacturing.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors material science specialists with alloy-core formulation patents and precision metrology capabilities over pure-play mechanical fabricators. Long-term viability rests on dual-use manufacturing assets serving both legacy cable assemblies and electronic speed sensor module housings. Monitor digital cluster penetration rates in India's commercial vehicle segment as the critical inflection signal for mechanical cable demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Metrology Investment | Laser-measured core winding achieves ECE R39 sub-one-percent rotational variance for KBA certification. |
| Polymer Formulation R&D | Self-lubricating compounds extend service intervals for Tamil Nadu tipper trucks on unpaved mining routes. |
| Connector Integration Development | Hybrid bridge systems capture value from transitional instrument cluster architectures. |
| Geographic Capacity Expansion | Vietnam assembly presence addresses Hanoi-Ho Chi Minh City corridor demand beyond domestic supply. |
| Aftermarket Channel Control | Direct distributor relationships in Surabaya commercial hub secure repair kit volume against fragmented competition. |
Study Parameters
A spread of perspectives from Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors in India's Pune-Nashik corridor, and commercial fleet maintenance directors converged on the working assumptions for cable assembly demand trajectories. Secondary validation drew from NHTSA odometer accuracy enforcement records, EU ECE R39 type approval databases, BIS certification registries, and vehicle production statistics across the analysis window. Bottom-up channel volume estimates triangulated against top-down OEM procurement spend allocations.
Segmentation dimensions modeled include product type, end user category, installation complexity, and material composition across the projection horizon. CAGRs were derived from replacement cycle timing analysis calibrated to regulatory enforcement patterns and fleet age distribution data. Industry-specific forecast inputs incorporated digital cluster penetration rates in premium passenger segments and mechanical gauge retention in cost-sensitive commercial vehicle production.
Underlying assumptions cover sustained NHTSA enforcement of odometer accuracy standards and stable BIS certification requirements for Indian domestic content, with deviation risk concentrated in accelerated electronic speed sensor substitution in emerging-market commercial platforms. Revision becomes warranted when digital cluster penetration in India's two-wheeler and light commercial segments crosses thresholds that compress mechanical cable replacement demand below sustaining volume levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market