
 Global Body Control Modules Market | 2026-2036
Global Body Control Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Global Body Control Modules Market Intelligence
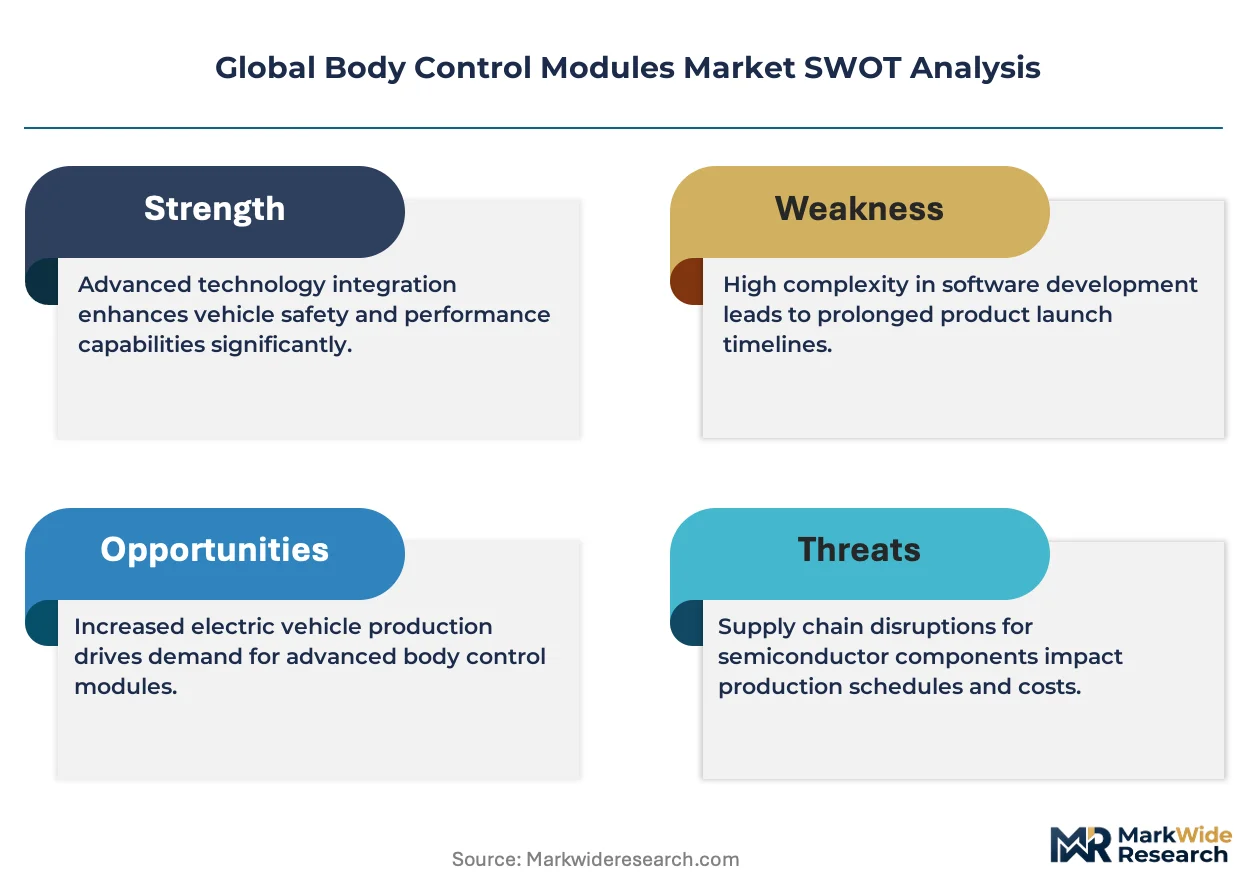
The ISO 26262 functional safety standard is rotating market access towards suppliers with verified software and hardware development processes. Robert Bosch GmbH leverages its deep systems integration expertise to supply complex, high-feature body control modules for premium automakers. Continental AG differentiates through its development of scalable BCM platforms compatible with emerging zonal vehicle architectures. Infineon Technologies AG specializes in the underlying semiconductor components, including AURIX microcontrollers, that are critical for BCM performance.
A Body Control Module (BCM) is a centralized electronic control unit within a vehicle responsible for managing body electronics. Typically built around a 32-bit microcontroller, it orchestrates functions like lighting, power windows, and door locks to reduce wiring complexity. Integrated BCMs that combine multiple functions are gaining share over standard BCMs, driven by OEM demands for cost and space optimization. While CAN Bus remains the dominant technology, automotive Ethernet is emerging for high-bandwidth data requirements.
Vehicle safety mandates from bodies like the US National Highway Traffic Safety Administration (NHTSA) influence BCM design. Similarly, the EU's type-approval framework and China's GB standards for automotive electronics dictate market entry requirements. Cybersecurity regulations are also becoming more stringent across major automotive markets. Suppliers must now decide whether to invest in developing software-defined BCMs or focus on optimizing hardware for legacy architectures.
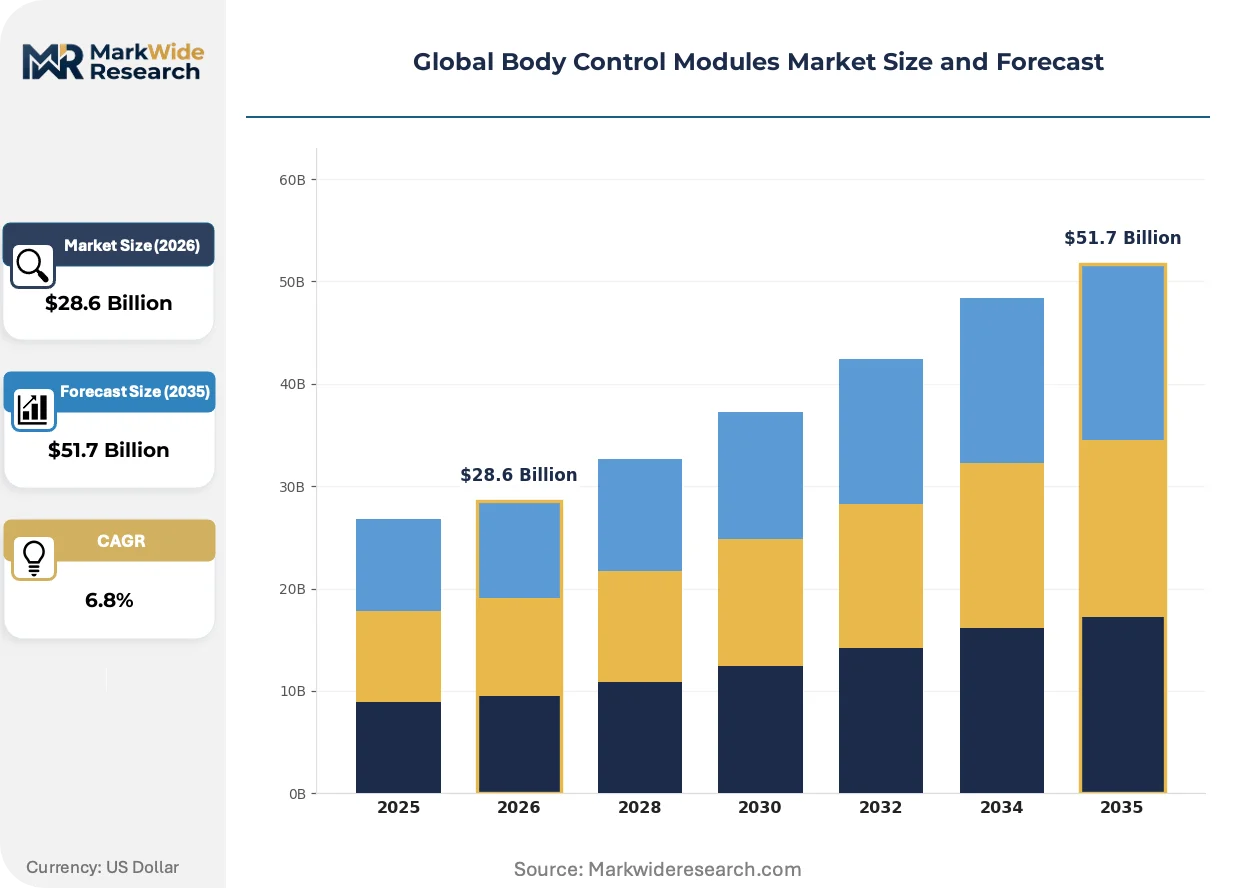
Market Dynamics
The industry-wide architectural migration from distributed electronic control units towards centralized zonal controllers is the central force shaping the body control module market. This transition redefines the BCM's role, increasing its processing power and software complexity.
Growth Catalysts
- Zonal E/E Architectures:The automotive industry's shift towards zonal electronic and electrical designs requires more powerful and integrated body domain controllers, consolidating functions that were previously separate and driving demand for advanced BCMs.
- Vehicle Safety Mandates:Regulations from bodies like the US NHTSA and the EU's type-approval framework, which increasingly require advanced safety and convenience features, compel OEMs to integrate more sophisticated BCMs into new passenger vehicles.
- Consumer Feature Demand:Strong consumer appetite for enhanced convenience features such as ambient lighting, keyless entry, and power liftgates, particularly within China's passenger car segment, necessitates BCMs with greater functional capacity.
Market Restraints
- Semiconductor Price Volatility:The high dependency on 32-bit microcontrollers and other specialized semiconductors makes BCM manufacturing costs susceptible to fluctuations and supply constraints in the global chip market, impacting supplier margins.
- Software Integration Complexity:Integrating and validating software from multiple sources onto a single BCM platform that must comply with the ISO 26262 standard introduces significant development overhead and extends testing timelines for suppliers.
- Legacy System Inertia:The vast number of existing vehicles using traditional, distributed CAN Bus architectures slows the overall replacement rate, limiting the addressable market for next-generation BCMs to new vehicle production and specific aftermarket applications.
Strategic Opportunities
- Software-Defined Vehicles:The emergence of software-defined vehicles creates an opportunity for suppliers to offer BCMs with over-the-air update capabilities, enabling new revenue streams from feature-on-demand services and post-sale upgrades.
- Cybersecurity Regulation Compliance:Upcoming regulations like UNECE WP.29 in Europe and equivalent standards in other regions create a market for BCMs with built-in, pre-certified hardware and software security features.
- BCM and Gateway Consolidation:Merging the functionality of a body control module with a central vehicle gateway into a single domain controller presents an opportunity to reduce cost, weight, and complexity for automotive OEMs.
Industry Challenges
- Functional Safety Expertise Gap:A persistent shortage of software and systems engineers with deep expertise in automotive-grade functional safety, particularly the ISO 26262 standard, constrains development capacity across the supplier base.
- Interoperability with Legacy Components:Ensuring that new, advanced BCMs can communicate effectively with older, existing electronic components within a mixed-architecture vehicle presents a significant and costly integration challenge for engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Body Control Modules Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard BCM, Advanced BCM, Integrated BCM, Networked BCM Technology: CAN Bus, LIN Bus, FlexRay, MOST, Ethernet Application: Lighting Control, Door Management, Climate Control, Security Systems, Power Management End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | HELLA GmbH & Co. KGaA, Mitsubishi Electric Corporation, Robert Bosch GmbH, ZF Friedrichshafen AG, Aptiv PLC, Continental AG, Infineon Technologies AG, Texas Instruments Inc., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Body Control Modules Market Strategic Shifts & Innovations
The evolution of the body control module is defined by its transformation from a fixed-function hardware component into a software-centric, updatable node within the vehicle's digital architecture. This shift alters the value chain, emphasizing software development and lifecycle management.
A software-defined BCM architecture allows for post-sale feature activation and system updates via over-the-air mechanisms. Automotive OEMs are adopting this approach to create new revenue models and respond faster to consumer preferences. This paradigm of updatable hardware is supplanting the traditional, fixed-function BCM, fundamentally changing how vehicle features are deployed and monetized over the vehicle's lifetime.
Global cybersecurity regulations, notably the UNECE WP.29 framework, are standardizing security requirements for vehicle electronics. This regulation mandates a certified cybersecurity management system for automakers, which flows down to component suppliers. The BCM, as a central node, is a primary focus, forcing suppliers to embed security features from the initial design phase.
Automaker procurement models are evolving from sourcing discrete components to co-developing scalable platforms with strategic suppliers. This collaborative approach allows OEMs to use a common BCM hardware and software base across multiple vehicle lines, reducing unit costs and development time. This trend is most prominent among large OEM groups in Germany and North America.
Global Body Control Modules Market Segmentation
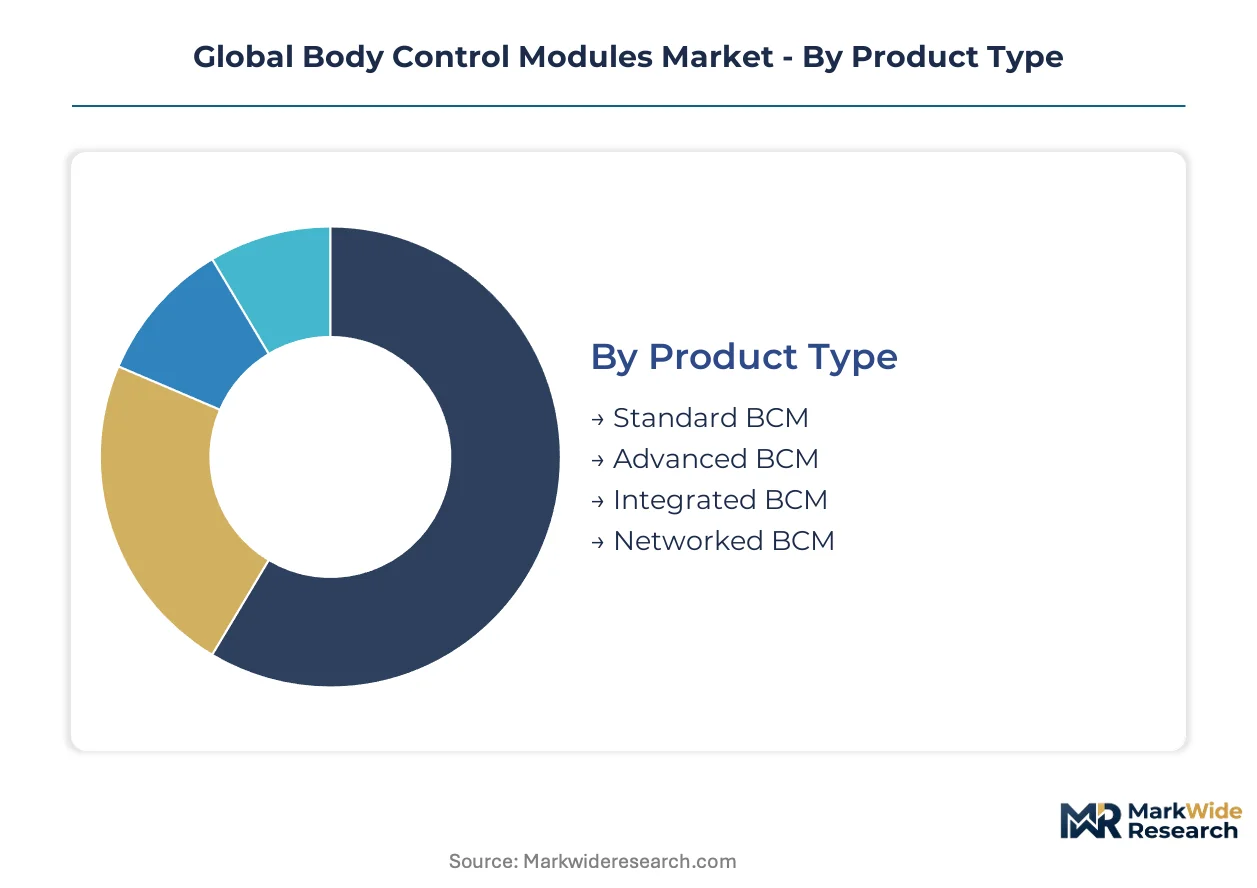
The Body Control Modules market is segmented to provide a granular understanding of the diverse technologies, applications, and customer bases that define its operational landscape. This segmentation highlights the critical shifts occurring as the automotive industry transitions towards more integrated and software-centric vehicle architectures.
Product Type:
The geographic distribution of Body Control Module types highlights varying adoption rates across regions, influenced by vehicle age and market maturity.
- Integrated BCM:Integrated BCMs combine multiple electronic functions into a single unit, reducing overall wiring complexity and vehicle weight. Demand for these modules concentrates within European and North American OEMs seeking cost and space optimization in new vehicle platforms.
- Networked BCM:Networked BCMs feature software-centric architectures capable of over-the-air updates and dynamic feature activation. This segment sees significant demand from global automakers developing software-defined vehicles for future revenue streams.
- Standard BCM:Standard BCMs manage basic body electronics functions like interior lighting and simple door locks. This product type remains prevalent in entry-level vehicles and established architectures.
- Advanced BCM:Advanced BCMs offer enhanced processing power and support for more complex features compared to standard units. These modules bridge the gap between basic and fully integrated solutions.
Standard BCM holds the largest share; momentum sits with Integrated BCM.
Technology:
Different BCM technologies are adopted based on specific performance and data bandwidth requirements within vehicle architectures.
- CAN Bus:CAN Bus remains the foundational communication protocol, offering robust and cost-effective data exchange for numerous vehicle functions. Its widespread integration in existing automotive architectures drives consistent demand across all major markets.
- Ethernet:Automotive Ethernet provides high-bandwidth, low-latency communication essential for advanced driver-assistance systems and zonal architectures. Demand is rapidly increasing within premium vehicle segments and electric vehicle platforms in China and Germany.
- LIN Bus:LIN Bus serves as a cost-effective sub-bus for non-critical applications, managing components like simple switches and sensors. It complements CAN Bus in less demanding vehicle domains.
- FlexRay:FlexRay offers deterministic, high-speed communication suitable for safety-critical applications requiring guaranteed data delivery. Its adoption is concentrated in specific high-performance and safety-focused vehicle systems.
- MOST:MOST (Media Oriented Systems Transport) is primarily used for multimedia and infotainment applications, enabling high-bandwidth audio and video streaming. This technology supports advanced in-car entertainment systems.
CAN Bus represents the foundational technology; Ethernet is rapidly expanding its footprint.
Application:
BCM applications are driven by evolving consumer expectations and stringent regulatory mandates across diverse vehicle segments.
- Lighting Control:Lighting Control applications manage interior and exterior illumination, including adaptive headlights and ambient lighting systems. Consumer appetite for enhanced convenience features in passenger cars, especially in China, fuels this segment.
- Security Systems:Security Systems encompass immobilizers, alarm functions, and intrusion detection, protecting vehicle integrity and occupant safety. Global regulatory bodies like NHTSA and UNECE WP.29 mandate advanced security features, driving BCM integration.
- Door Management:Door Management systems control functions such as power windows, central locking, and power liftgates. These features are standard across most modern vehicles, enhancing user convenience.
- Climate Control:Climate Control applications regulate heating, ventilation, and air conditioning systems within the vehicle cabin. BCMs integrate with sensors and actuators to maintain desired environmental conditions.
- Power Management:Power Management functions oversee the distribution and regulation of electrical power to various vehicle components. This ensures efficient operation and protects sensitive electronics.
Lighting Control and Door Management drive significant volume; Security Systems exhibit strong growth due to regulatory pressures.
End User:
The Body Control Module market's end-user landscape reflects the complex interplay of manufacturing, development, and service within the automotive value chain.
- OEMs:Original Equipment Manufacturers directly integrate BCMs into vehicle platforms, often co-developing solutions with strategic partners. This segment focuses on scalable architectures and software-defined capabilities for future vehicle generations.
- Tier-1 Suppliers:Tier-1 Suppliers specialize in the design, development, and mass production of BCMs, providing integrated solutions to global automakers. Their expertise in systems integration and functional safety is critical for complex module delivery.
- Aftermarket Providers:Aftermarket Providers offer replacement BCMs and upgrade kits for vehicle repair and enhancement. This segment caters to the maintenance and customization needs of the existing vehicle fleet.
- Vehicle Assemblers:Vehicle Assemblers integrate BCMs and other electronic components into the final vehicle during the manufacturing process. They ensure proper functionality and connectivity of all systems.
OEMs and Tier-1 Suppliers form the core demand; Aftermarket Providers address replacement and upgrade needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vehicle safety mandates and consumer demand for advanced features drive regional variations in Body Control Module adoption. Regulatory frameworks like the EU's type-approval and China's GB standards influence market entry and design. This shapes distinct development and procurement strategies across major automotive manufacturing hubs.
China
China's rapidly expanding electric vehicle manufacturing ecosystem fuels demand for advanced BCMs, driven by consumer appetite for enhanced convenience features. Its GB standards for automotive electronics dictate market entry and product specifications. Major EV manufacturing centers in the Yangtze River Delta concentrate BCM production and integration.
Germany
German premium automakers demand complex, high-feature BCMs, accelerating the transition to zonal electronic architectures. The EU's type-approval framework and UNECE WP.29 cybersecurity regulations influence BCM design. Automotive engineering centers in Bavaria are focal points for BCM research and system integration.
United States
United States vehicle safety mandates from NHTSA compel OEMs to integrate sophisticated BCMs for advanced safety and convenience. The push towards software-defined vehicles creates opportunities for over-the-air updates. Michigan's automotive hub remains central for BCM integration into new vehicle platforms.
Japan
Japanese automakers prioritize high-quality and reliable BCMs supporting advanced driver-assistance systems and robust vehicle electronics. METI policies encourage innovation in automotive electronics, influencing BCM development. The Aichi Prefecture automotive cluster drives demand for integrated BCM solutions in mass-market vehicles.
South Korea
South Korean automotive manufacturers, particularly in the EV segment, require advanced BCMs for integrated infotainment and body control functions. National automotive safety standards support domestic BCM innovation. The Gyeonggi Province manufacturing cluster is a key region for BCM design and production for local and export markets.
Global Body Control Modules Market Key Industry Players
Listed leaders compete with private specialists across the Body Control Module market, which exhibits a tiered structure. The competitive landscape features established automotive Tier-1 suppliers alongside specialized semiconductor manufacturers. Strategic archetypes include systems integration experts for complex BCMs and component providers for underlying microcontrollers. Companies leverage strategic partnerships with OEMs and portfolio diversification into software-defined solutions to gain market share.
Within the systems integration tier, Robert Bosch GmbH and Continental AG exemplify established automotive suppliers providing complex BCM solutions. Robert Bosch GmbH, a German-based company, leverages its deep systems integration expertise for premium automakers. Continental AG, also a German company, differentiates through scalable BCM platforms compatible with emerging zonal architectures. Infineon Technologies AG, a German semiconductor company, occupies a critical position as a specialist in underlying semiconductor components like AURIX microcontrollers, essential for BCM performance. These players anchor different segments of the value chain, from full system delivery to critical component supply.
| Leading Market Players |
|---|
| HELLA GmbH & Co. KGaA |
| Mitsubishi Electric Corporation |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| Continental AG |
| Infineon Technologies AG |
| Texas Instruments Inc. |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
High-volume automotive production scale creates significant economies for body control module manufacturing, concentrating supply among a few large Tier-1 suppliers. This scale directly influences price floors, favoring integrated solutions.
Pricing Analysis
ISO 26262 functional safety certification creates the primary spread in body control module pricing. The dominant pricing model is contract-based long-term agreements between OEMs and Tier-1 suppliers, with differentiation also stemming from software complexity and the degree of hardware integration. Pricing softness in standard BCMs reflects intense competition among component providers. OEMs are highly price-sensitive for basic modules, while premium automakers prioritize advanced features and certified safety.
Supply Chain Analysis
Taiwan's semiconductor manufacturing capacity underwrites the global supply of 32-bit microcontrollers critical for body control modules. Key component dependencies include specialized semiconductors and passive electronic components, with geographic supply concentrated in Germany, China, and Japan for automotive component manufacturing. Semiconductor price volatility represents a significant structural risk for BCM production. Distribution runs primarily through Tier-1 suppliers directly to automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The body control module market is experiencing a platform-economics inflection, driven by the industry-wide shift towards software-defined vehicle architectures. This transition emphasizes interoperability and ecosystem development for future revenue models.
For Market Incumbents: Secure long-term contracts with major automotive OEMs by offering scalable BCM platforms compatible with zonal E/E architectures. Invest heavily in software development capabilities to counter emerging software-centric competitors. Functional safety expertise, particularly ISO 26262, remains a critical lever against new entrants. Diversify semiconductor sourcing to mitigate supply chain volatility risks.
For New Entrants and Emerging Players: A streamlined functional safety certification pathway offers new entrants a strategic advantage in the body control module market. Target the rapidly expanding electric vehicle segment in China with integrated BCM solutions. Focus on software-defined BCMs offering over-the-air update capabilities as a compelling go-to-market angle. This approach can penetrate the market for advanced convenience features.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers offering software-defined body control modules with subscription-based feature upgrades. Long-term viability favors companies with deep expertise in automotive cybersecurity and functional safety. Acquisition targets should include specialized software firms capable of accelerating platform development. The signal to watch is the adoption rate of automotive Ethernet in new vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Software-Defined BCMs | This initiative enables over-the-air updates, creating new revenue streams for automotive OEMs through feature-on-demand services. |
| Strengthen ISO 26262 Expertise | Deepening functional safety knowledge ensures compliance with critical regulatory mandates for advanced vehicle electronics. |
| Diversify Semiconductor Sourcing | Mitigating reliance on single-source suppliers reduces vulnerability to global chip market fluctuations and supply constraints. |
| Form Zonal Architecture Partnerships | Collaborating with OEMs on zonal E/E architectures reduces development costs and accelerates market penetration for integrated BCMs. |
| Integrate Cybersecurity Features | Embedding robust security from design phase ensures compliance with UNECE WP.29 and protects vehicle integrity. |
Research Approach
A standing panel of Tier-1 supplier executives, OEM platform engineers, and automotive cybersecurity specialists provided ongoing calibration for market trends. This primary research involved in-depth interviews, complemented by extensive secondary validation. Secondary data sources included vehicle production databases, automotive electronics standards, and regulatory body reports from NHTSA and UNECE WP.29. Bottom-up and top-down triangulation ensured data integrity.
External benchmarks, including historical vehicle production volumes and technology adoption rates, validated all volume and value outputs. The analytical framework modeled segmentation dimensions by product type, technology, application, and end-user across the analysis window. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs included projected electric vehicle sales and regulatory timelines.
The analysis sits within stated boundaries; outcomes outside current geopolitical stability or semiconductor supply chain resilience would require recalibration. Forecasts reflect assumptions documented regarding technological adoption curves and regulatory enforcement. Practitioners should keep alternative scenarios live as OEM investment priorities and regional trade policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Automotive Split-View Camera Module Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market