
 Global Automotive Backup Camera Market | 2026-2036
Global Automotive Backup Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Backup Camera Market Intelligence
The integration of high-definition CMOS sensors with vehicle-wide data networks is reshaping the architecture of automotive backup cameras. This transition enables features beyond simple rear-view, including object detection and dynamic guidelines. Robert Bosch GmbH leverages its expertise in automotive electronics to offer integrated solutions. Valeo SA specializes in comprehensive ADAS suites where cameras are a core component, while Gentex Corporation leads in digital rearview mirrors incorporating camera feeds.
An automotive backup camera is an electronic device, typically featuring a wide-angle lens of 120-180 degrees, designed to capture real-time video of the area behind a vehicle. Its primary purpose is to enhance driver visibility, mitigate blind spots, and prevent low-speed collisions during reversing. While wired systems remain the standard for OEMs, 360-degree camera systems are a fast-growing premium product type. CMOS sensor technology dominates production over CCD sensors due to superior integration capabilities and cost-effectiveness.
Regulatory frameworks are a primary market accelerator. The United States' NHTSA regulations and similar UNECE standards in Europe mandate rearview visibility systems in all new light vehicles. China's GB standards also enforce strict safety requirements, driving OEM adoption. The critical decision for suppliers now involves navigating the transition from standalone safety devices to fully integrated components within broader autonomous driving sensor suites.
Market Dynamics
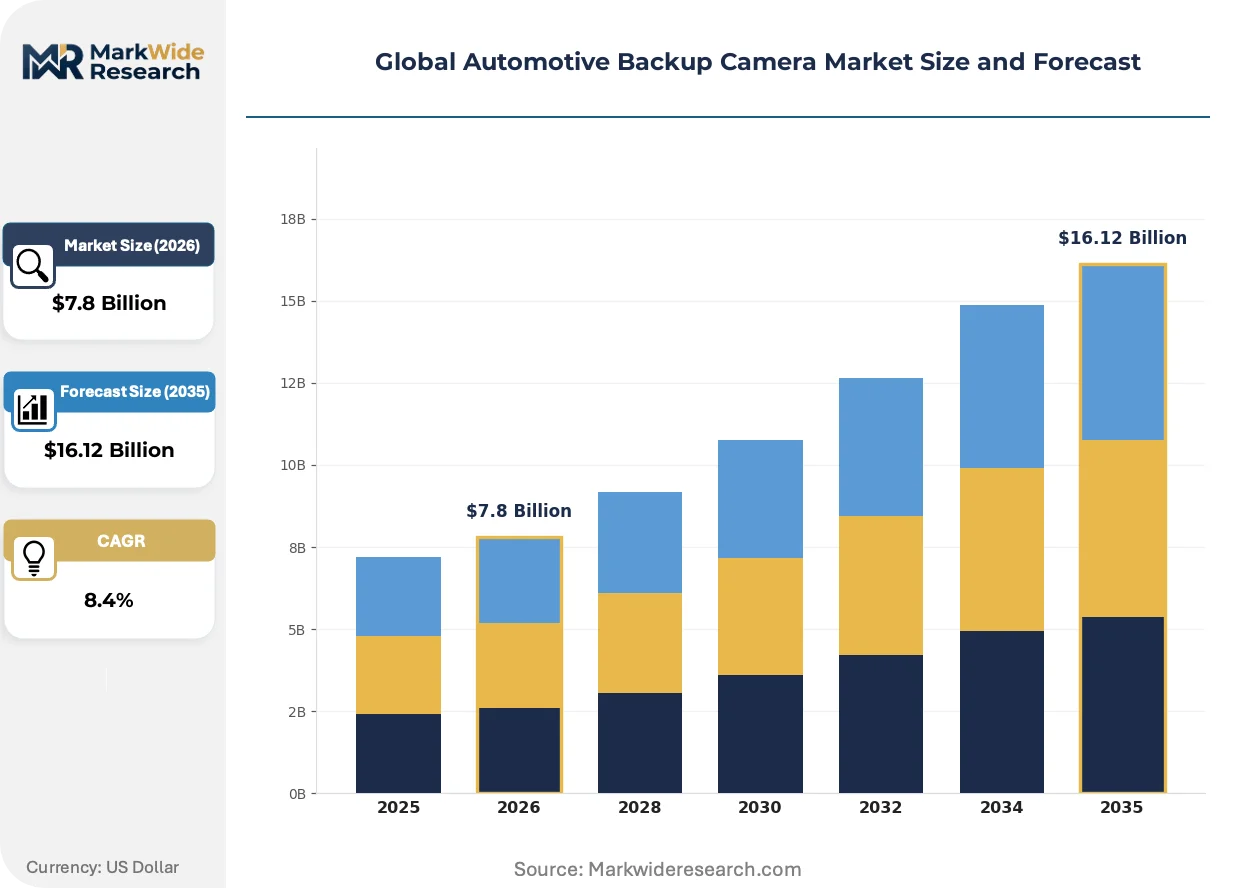
The fundamental market dynamic is the transition of backup cameras from standalone safety devices into essential data nodes within integrated Advanced Driver-Assistance Systems. This shift is driven by the automotive industry's pursuit of higher levels of vehicle automation.
Growth Catalysts
- Regulatory Mandates:Safety regulations, including NHTSA rules in the United States and UNECE standards in Europe, compel the installation of rearview visibility systems in all new light passenger vehicles, creating a baseline volume demand.
- Sensor Technology Advancement:The falling cost and improving low-light performance of CMOS image sensors make high-definition cameras economically viable for mass-market vehicles, not just premium segments.
- Manufacturing Scale in China:As the world's largest vehicle production hub, China's domestic demand and export-oriented manufacturing provide immense economies of scale for camera component suppliers, reducing global unit costs.
Market Restraints
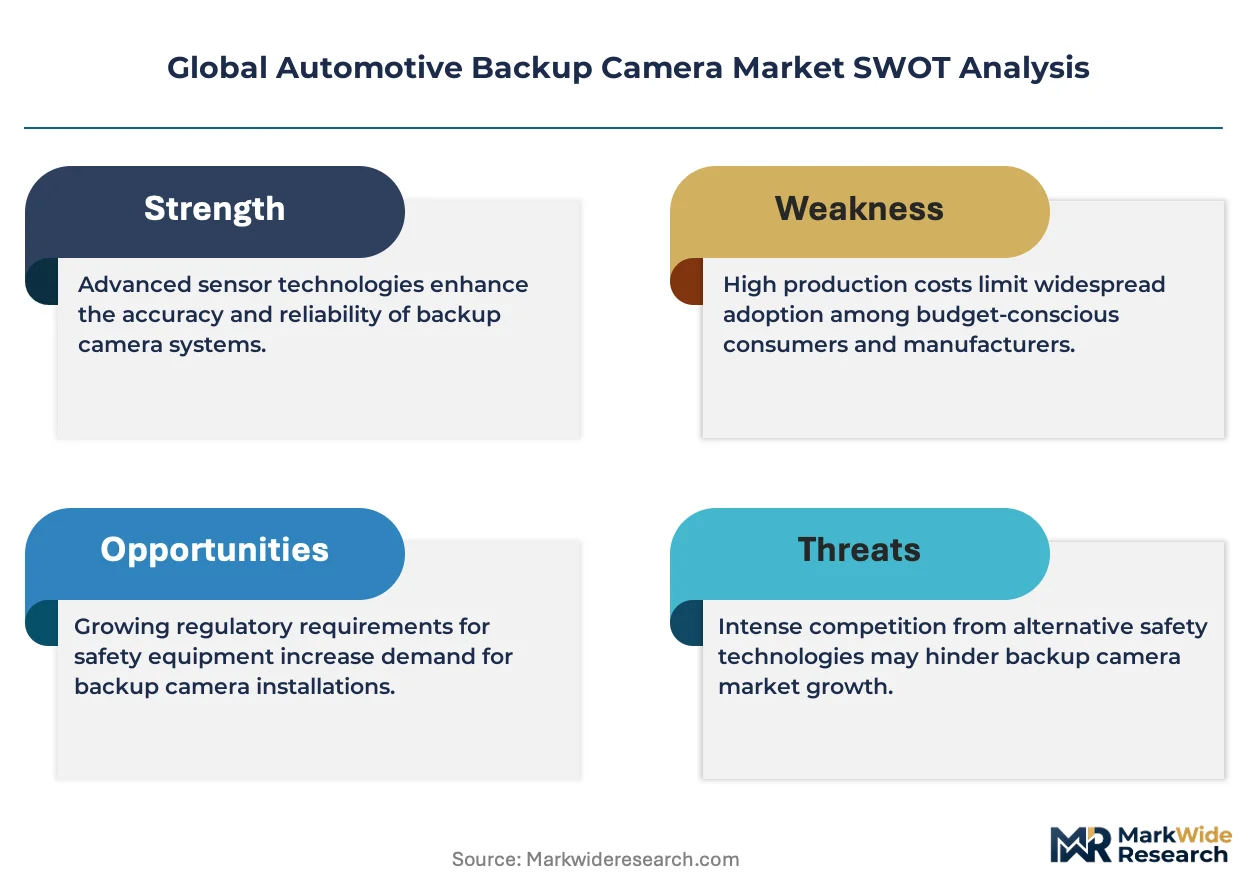
- Cost Commoditization Pressure:Intense competition in the standard-definition, single-function backup camera segment has led to significant price erosion, compressing profit margins for suppliers focused on the low-end market.
- Performance in Adverse Conditions:Camera effectiveness is significantly degraded by environmental factors like rain, snow, mud, or lens glare, often requiring additional systems like washers or coatings that increase cost and complexity.
- Semiconductor Supply Chain Risk:The reliance on a concentrated group of specialized foundries for automotive-grade CMOS image sensors creates vulnerability to supply chain disruptions, geopolitical trade friction, and capacity allocation shortages.
Strategic Opportunities
- Commercial Vehicle Penetration:The market for backup and multi-camera systems in heavy-duty trucks, buses, and off-highway vehicles remains significantly underpenetrated, offering substantial growth potential beyond the saturated passenger car segment.
- Sensor Fusion for ADAS:Opportunities exist in developing sophisticated software that fuses camera data with inputs from radar and lidar, enabling more reliable object classification and path prediction for autonomous driving functions.
- Digital Mirrors and Displays:The replacement of traditional glass side and rearview mirrors with camera-based digital displays represents a high-value opportunity, expanding the total addressable market per vehicle.
Industry Challenges
- Data Bandwidth and Processing:Integrating multiple high-definition cameras generates vast amounts of data that challenge the capacity of current in-vehicle networks and require powerful, energy-efficient processing units, adding cost and engineering complexity.
- Cybersecurity Vulnerabilities:As cameras become networked components connected to critical vehicle control systems, they introduce new attack surfaces for malicious actors, necessitating robust and continuously updated cybersecurity protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Backup Camera Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, 360-Degree, Digital, Analog Technology: Night Vision, Ultrasonic, Infrared, CMOS Sensor, CCD Sensor Application: Passenger Vehicles, Commercial Vans, Heavy-Duty Trucks, Construction Vehicles, Agricultural Equipment End User: OEMs, Aftermarket Dealers, Fleet Operators, Vehicle Assemblers, Automotive Retailers |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Magna International Inc., Valeo SA, Gentex Corporation, HELLA GmbH & Co. KGaA, OmniVision Technologies Inc., Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Backup Camera Market Strategic Shifts & Innovations
The evolution from passive imaging devices to active perception sensors marks the central innovation theme. Automotive backup cameras are becoming critical data sources that enable machine vision and contribute to the vehicle's overall environmental awareness and decision-making capabilities.
High-definition CMOS image sensors provide the foundational technology for next-generation systems, offering superior resolution and high dynamic range. Automakers are rapidly adopting these sensors to power ADAS features like automated emergency braking and lane-keeping assist. This advancement is digitizing the vehicle's perception layer, transforming passive video into machine-readable data for object recognition and scene understanding.
New safety frameworks, such as the upcoming UNECE regulations on driver availability monitoring systems, are creating demand for inward-facing cameras. This policy shift requires automakers to integrate cabin-monitoring cameras to ensure driver engagement when semi-autonomous systems are active. The passenger vehicle segment, particularly for models with Level 2+ automation, is most directly affected, redesigning interiors to accommodate these new sensors.
Consumer preference is shifting toward valuing software-enabled camera features over static hardware specifications. This disrupts the traditional model of selling a fixed-function camera, pushing demand toward systems that support over-the-air updates for new features like enhanced dynamic guidelines or 3D surround-view modes. This trend is most prominent in the global electric vehicle market, where software upgradability is a key competitive differentiator.
Global Automotive Backup Camera Market Segmentation
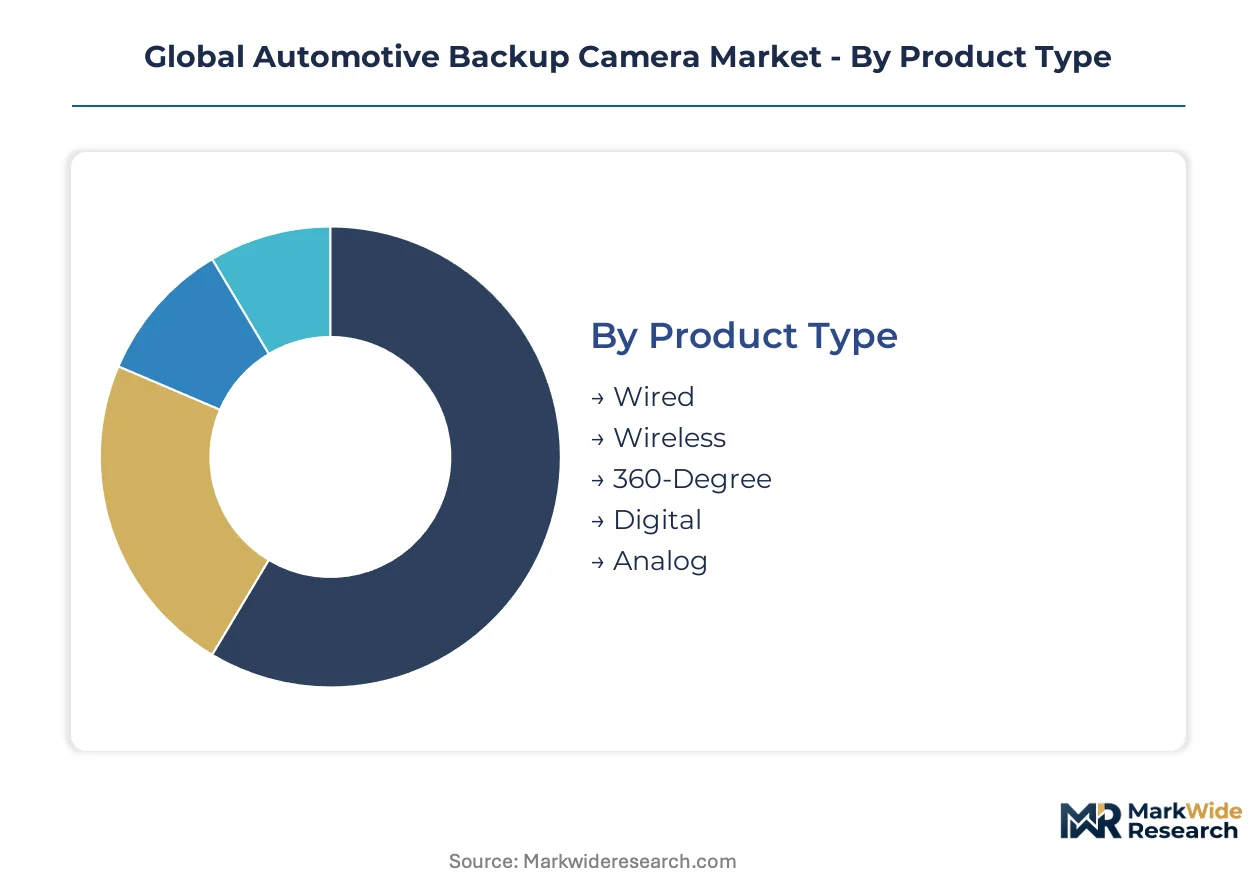
Understanding the varied requirements across the automotive backup camera market is crucial for strategic positioning and product development. Segmentation highlights the diverse demands from original equipment manufacturers to specialized aftermarket solutions, impacting after-sales service and integration complexity.
Product Type:
The market for automotive backup cameras often sees significant after-sales service intensity, particularly across different product types where installation complexity and feature sets vary.
- 360-Degree:This system integrates multiple wide-angle cameras around the vehicle, stitching their feeds together to provide a comprehensive, bird's-eye view. Demand concentrates in premium passenger vehicles in Germany, driven by advanced parking assistance features and consumer preference for enhanced spatial awareness.
- Wired:These cameras establish a direct electrical connection to the vehicle's power and display systems, ensuring reliable signal transmission and minimal interference. Demand is strong in OEM installations for new light vehicles in the United States, primarily due to regulatory mandates for rear visibility systems.
- Wireless:Transmits video signals via radio frequency, offering easier installation without extensive cabling, commonly used in aftermarket upgrades.
- Digital:Utilizes high-resolution image processing and integrates seamlessly with modern infotainment screens, delivering crisp, clear visuals.
- Analog:Provides standard definition video output, typically found in older vehicle models or budget-conscious aftermarket solutions.
Wired product type holds the largest share; momentum sits with 360-Degree systems.
Technology:
Technology choices for backup cameras directly influence production costs, creating distinct tiers for automakers and aftermarket providers.
- CMOS Sensor:Complementary Metal-Oxide-Semiconductor technology offers superior integration capabilities, lower power consumption, and cost-effectiveness for mass production. Demand is high in mass-market passenger vehicles in China, driven by the need for economical yet high-performance imaging solutions.
- Night Vision:This technology employs infrared or thermal imaging to provide clear visibility in low-light or complete darkness, significantly enhancing safety during nighttime maneuvers. Demand is notable in luxury and premium vehicle segments across Europe, where advanced safety features are a key differentiator.
- Ultrasonic:Emits sound waves to detect obstacles in close proximity, commonly integrated with parking sensors to provide audible alerts.
- Infrared:Detects heat signatures, enabling visibility in pitch-dark conditions for specialized applications like commercial vehicle monitoring.
- CCD Sensor:Charge-Coupled Device sensors are known for high image quality and light sensitivity but typically come with higher manufacturing costs and power requirements.
CMOS Sensor technology dominates the market, while Night Vision technology shows the steepest expansion trajectory.
Application:
Application segments vary significantly in volume requirements, from high-production passenger vehicles to specialized off-highway equipment.
- Passenger Vehicles:Backup cameras are integrated into light-duty cars for rear visibility, parking assistance, and collision prevention. Demand is primarily driven by new vehicle production in the United States, propelled by NHTSA safety regulations mandating rearview cameras.
- Heavy-Duty Trucks:These applications require robust, weather-resistant camera systems with wide fields of view to manage large blind spots and improve maneuverability. Demand is expanding in commercial fleet upgrades in Canada, focusing on enhancing driver safety and reducing accident liability.
- Commercial Vans:Provides essential rear visibility for delivery and service vehicles, often incorporating blind spot monitoring for urban environments.
- Construction Vehicles:Features durable camera systems designed to withstand harsh operating conditions, assisting operators with heavy machinery and site awareness.
- Agricultural Equipment:Specialized cameras monitor implements, trailers, and surroundings, improving efficiency and safety during farming operations.
Passenger Vehicles constitute the largest application segment, with Heavy-Duty Trucks gaining share fastest.
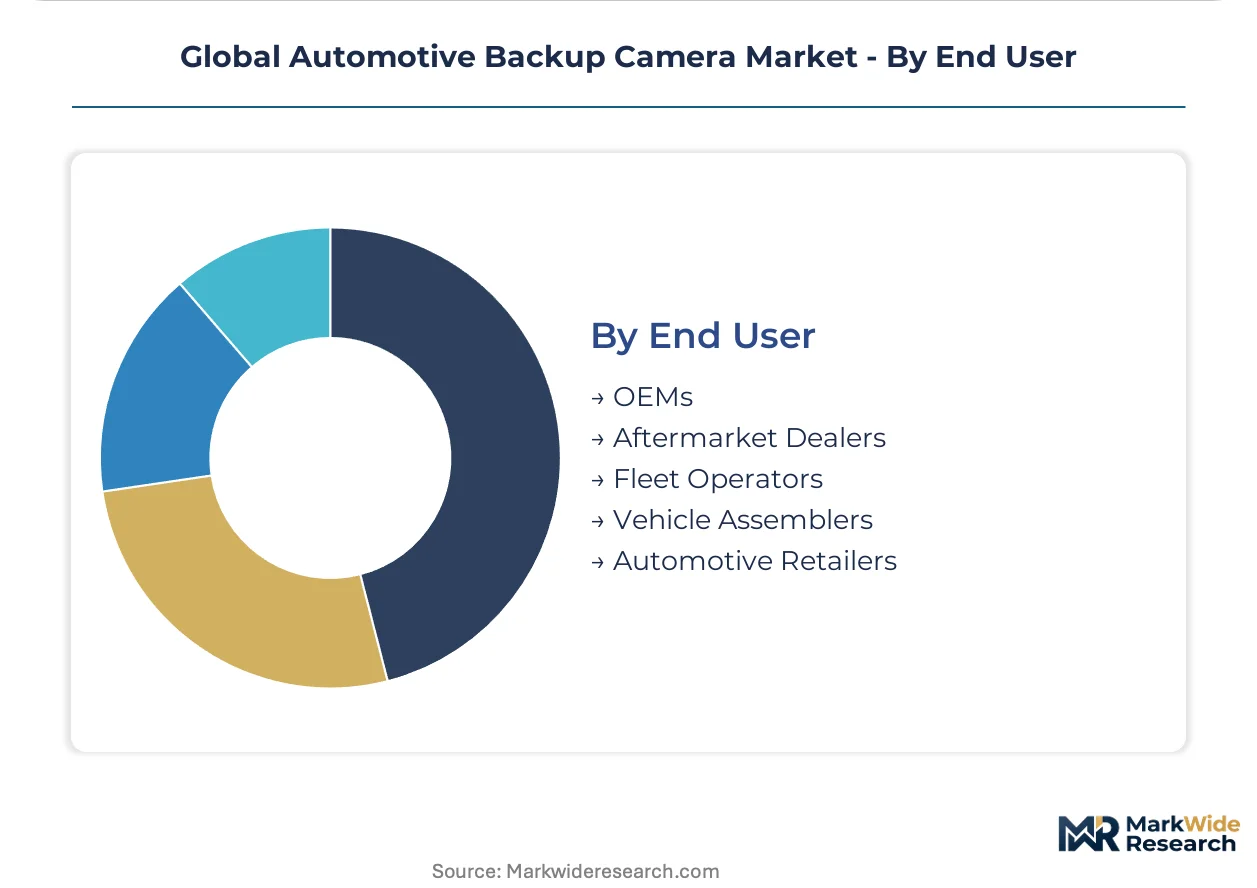
End User:
Supply chain configuration for backup cameras is heavily influenced by end-user procurement models, from direct OEM supply to fragmented aftermarket channels.
- OEMs:Original Equipment Manufacturers integrate camera systems directly into the vehicle's design and manufacturing process during initial production. Demand originates from new vehicle assembly plants in Mexico, driven by initial component supply contracts and regulatory compliance.
- Aftermarket Dealers:These entities sell and install standalone or add-on backup camera kits for vehicles after their initial purchase. Demand is significant in vehicle customization markets in Australia, catering to consumers seeking upgrades or enhanced safety features.
- Fleet Operators:Purchase and install camera systems for their existing vehicle fleets to improve operational safety, driver accountability, and asset protection.
- Vehicle Assemblers:Integrate camera components into vehicles during the final stages of production, ensuring compatibility with infotainment and safety systems.
- Automotive Retailers:Offer backup camera solutions directly to individual consumers, often providing installation services as part of the sale.
OEMs represent the dominant end-user segment, while Fleet Operators show expanding demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese automotive manufacturers export backup camera systems to markets like the United States, driven by cost-effective production and increasing global vehicle demand. This trade flow significantly influences regional market dynamics and pricing structures. Regulatory mandates across continents continue to shape market growth.
United States
Consumer safety preferences and NHTSA regulations drive strong demand for backup cameras in the United States. The NHTSA mandates rearview visibility systems in all new light vehicles, ensuring a baseline market volume. Detroit, Michigan, remains a key automotive hub, where OEMs integrate advanced camera systems into new vehicle architectures.
Germany
Germany's luxury vehicle segment and demand for advanced safety features propel backup camera market growth. UNECE standards, particularly those for driver assistance systems, shape product specifications for German manufacturers. Stuttgart, a major automotive center, sees significant R&D investment in digital mirror and sensor fusion technologies.
China
China's position as the world's largest automotive manufacturing hub fuels immense demand for backup cameras. GB standards enforce strict safety requirements, driving OEM adoption of integrated camera solutions. Shanghai's robust automotive industry focuses on mass production and economical yet high-performance CMOS sensor integration.
Japan
Japanese automakers prioritize advanced ADAS integration and high technology adoption rates for backup camera systems. METI initiatives encourage the development of cutting-edge automotive safety and perception technologies. Nagoya's automotive cluster drives innovation in sensor fusion and digital mirror applications for next-generation vehicles.
Mexico
Mexico's expanding new vehicle assembly plants generate substantial OEM demand for backup camera systems. USMCA trade agreements influence the integration of automotive components and manufacturing processes. Puebla's thriving automotive manufacturing sector secures initial component supply contracts for major global automakers.
Global Automotive Backup Camera Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic competitive environment. The market structure exhibits a tiered consolidation, with large automotive electronics suppliers dominating the OEM segment. These established players pursue strategic partnerships for technology co-development and engage in portfolio diversification to integrate camera systems into broader ADAS suites. Smaller, agile firms often focus on niche aftermarket solutions or specialized component supply.
Among established automotive electronics suppliers, Robert Bosch GmbH exemplifies comprehensive integrated solutions across vehicle platforms. Continental AG, a Germany-based entity, represents another key player, focusing on advanced ADAS components and safety systems. Valeo SA, a French automotive supplier, occupies a position in comprehensive ADAS suites where camera systems form a core component. These firms anchor the market's high-value segments through extensive R&D, global manufacturing capabilities, and strategic investments in sensor fusion technologies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Magna International Inc. |
| Valeo SA |
| Gentex Corporation |
| HELLA GmbH & Co. KGaA |
| OmniVision Technologies Inc. |
| Aptiv PLC |
Cost & Logistics Intelligence
CMOS sensor manufacturing in China dictates the cost structure for automotive backup cameras, influencing margin capture for integrated ADAS solution providers. This concentration of component supply impacts pricing power throughout the value chain.
Pricing Analysis
Cost-plus contracts, often indexed to semiconductor and raw material costs, govern pricing for OEM backup camera suppliers. Price differentiation stems from resolution quality, advanced ADAS integration capabilities, and volume scale. Commoditization pressure in the standard-definition segment causes significant price erosion. OEMs integrating advanced ADAS systems show lower price sensitivity than aftermarket consumers seeking basic functionality.
Supply Chain Analysis
Upstream feedstock for automotive backup cameras primarily centers on specialized foundries producing CMOS image sensors. Supply concentration resides heavily in China for mass production, complemented by advanced component manufacturing in Japan and Germany. The reliance on a concentrated group of semiconductor foundries introduces single-source vulnerability. Downstream distribution primarily flows directly to OEMs for initial vehicle integration, with aftermarket channels serving upgrades and repairs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive backup camera market is an early-cycle expansion story, driven by regulatory mandates for rearview visibility and increasing penetration of ADAS features. This creates opportunities across various vehicle segments.
For Market Incumbents:Entrench market position by investing heavily in advanced sensor fusion capabilities, integrating camera data with radar and lidar for enhanced ADAS. Expand comprehensive ADAS suites to mitigate commoditization pressure from basic camera systems. Strategic partnerships with software developers can accelerate the transition from hardware-centric to software-defined camera features. This approach counters the threat from agile firms focused on niche aftermarket solutions.
For New Entrants and Emerging Players:Build out specialized solutions for the underpenetrated commercial vehicle segment, focusing on robust, multi-camera systems for heavy-duty trucks and buses. Target the replacement of traditional glass mirrors with camera-based digital displays, offering superior visibility and safety features. A go-to-market strategy emphasizing durability, specialized features for fleet management, and ease of integration into existing vehicle architectures will create market entry points.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized software firms enabling advanced sensor fusion and machine vision capabilities, critical for long-term ADAS evolution. The market offers viable long-term returns due to persistent regulatory tailwinds and increasing integration into autonomous driving systems. Target niche component suppliers with proprietary high-dynamic-range CMOS sensor technology. Watch for accelerated OEM commitments to Level 2+ automation as a key inflection indicator for advanced camera system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion R&D | Enables higher levels of autonomous driving and object classification. |
| Commercial Vehicle Portfolio Expansion | Captures growth in an underpenetrated segment beyond passenger cars. |
| Digital Mirror Technology Development | Expands the total addressable market per vehicle for camera systems. |
| Cybersecurity Protocol Integration | Protects networked camera systems from malicious attacks and data breaches. |
| CMOS Sensor Manufacturing Partnerships | Secures critical component supply and manages semiconductor supply chain risks. |
Research Approach
Desk research of regulatory mandates, automotive production statistics, and company financial filings preceded structured interviews with OEM procurement managers, Tier 1 ADAS engineers, and aftermarket distributors. This primary research validated secondary data points and captured qualitative insights into market dynamics. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy.
Assumptions regarding stable regulatory environments and continued technological advancement underpinned the forecast framework across the analysis window. The market was segmented by product type, technology, application, end-user, and regional production clusters. Compound annual growth rates were calculated from historical performance and projected ADAS penetration rates. Vehicle production forecasts served as a key input for volume estimations.
Practitioners should monitor geopolitical trade friction, semiconductor supply disruptions, and evolving safety regulations for early signals of forecast revision. These forecasts reflect assumptions about market conditions. Cross-checking against OEM production schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market