
 Brake Cables Market | 2026-2036
Brake Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Brake Cables Market Outlook
A shortage of precision wire-drawing technicians is unwinding capacity expansion plans at several brake cable foundries. Hi-Lex leverages its captive steel-wire production to insulate margins from raw material volatility. Suprajit anchors its position through dense aftermarket distribution across India's two-wheeler service network. Küster specializes in coated cable assemblies for European premium vehicle programs.
Brake cables are tensile control elements, typically constructed from galvanized or stainless steel wire strands wound around a polymer core, that transmit mechanical force from pedal or lever actuation to braking mechanisms at the wheel hub. Standard cables retain dominance in cost-sensitive two-wheeler and entry passenger car platforms, while electronic connection types capture expanding value pools as brake-by-wire architectures displace hydraulic circuits. Heavy-duty cables sustain premium pricing in commercial vehicle applications where fatigue resistance and corrosion protection determine replacement cycles.
NHTSA's Federal Motor Vehicle Safety Standards govern brake system performance thresholds in the United States, while ECE R90 and REACH compliance frameworks in Europe mandate material composition disclosure and aftermarket component equivalency testing. China's GB/T automotive cable standards, administered by SAMR, impose additional localization requirements on foreign suppliers seeking domestic OEM qualification. Stakeholders must weigh regulatory divergence against platform standardization economics when configuring regional production footprints.
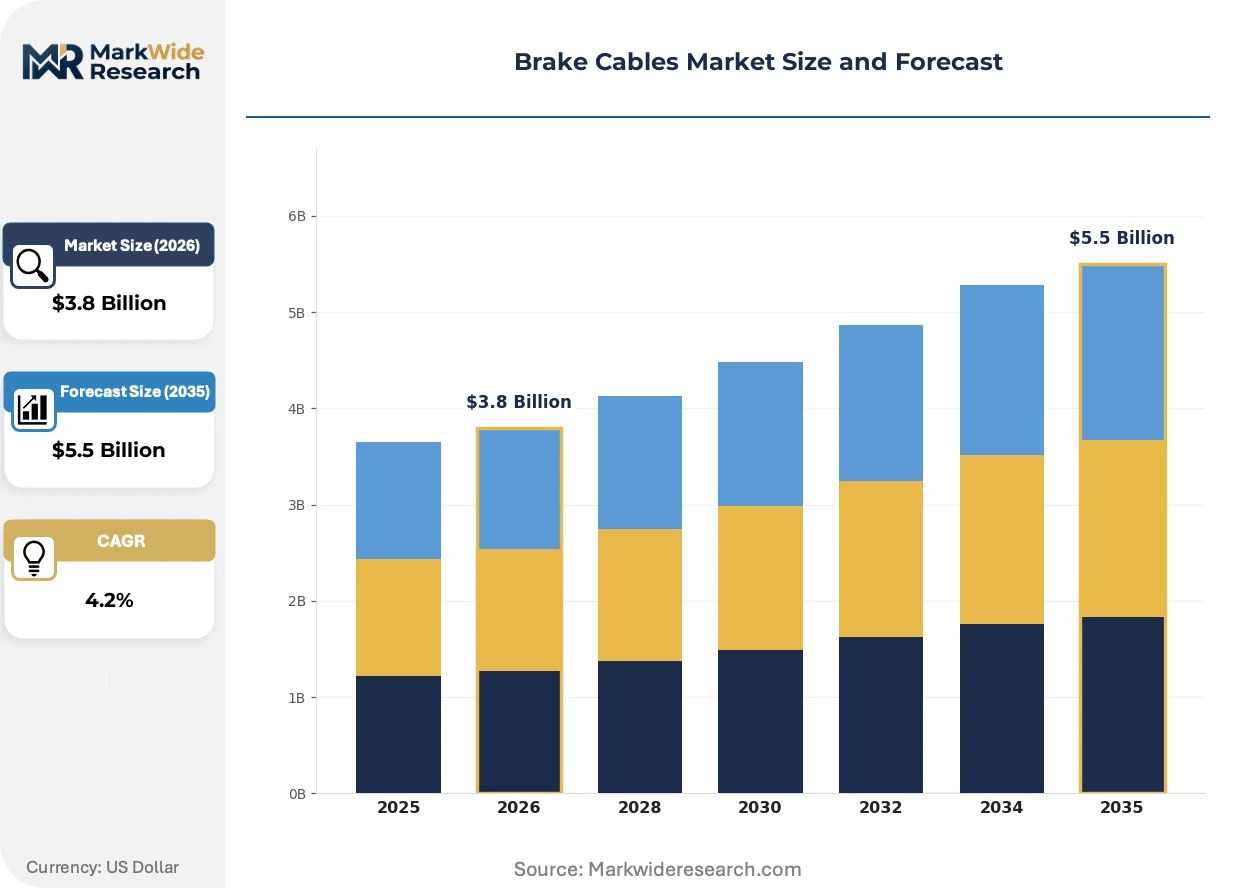
Market Dynamics
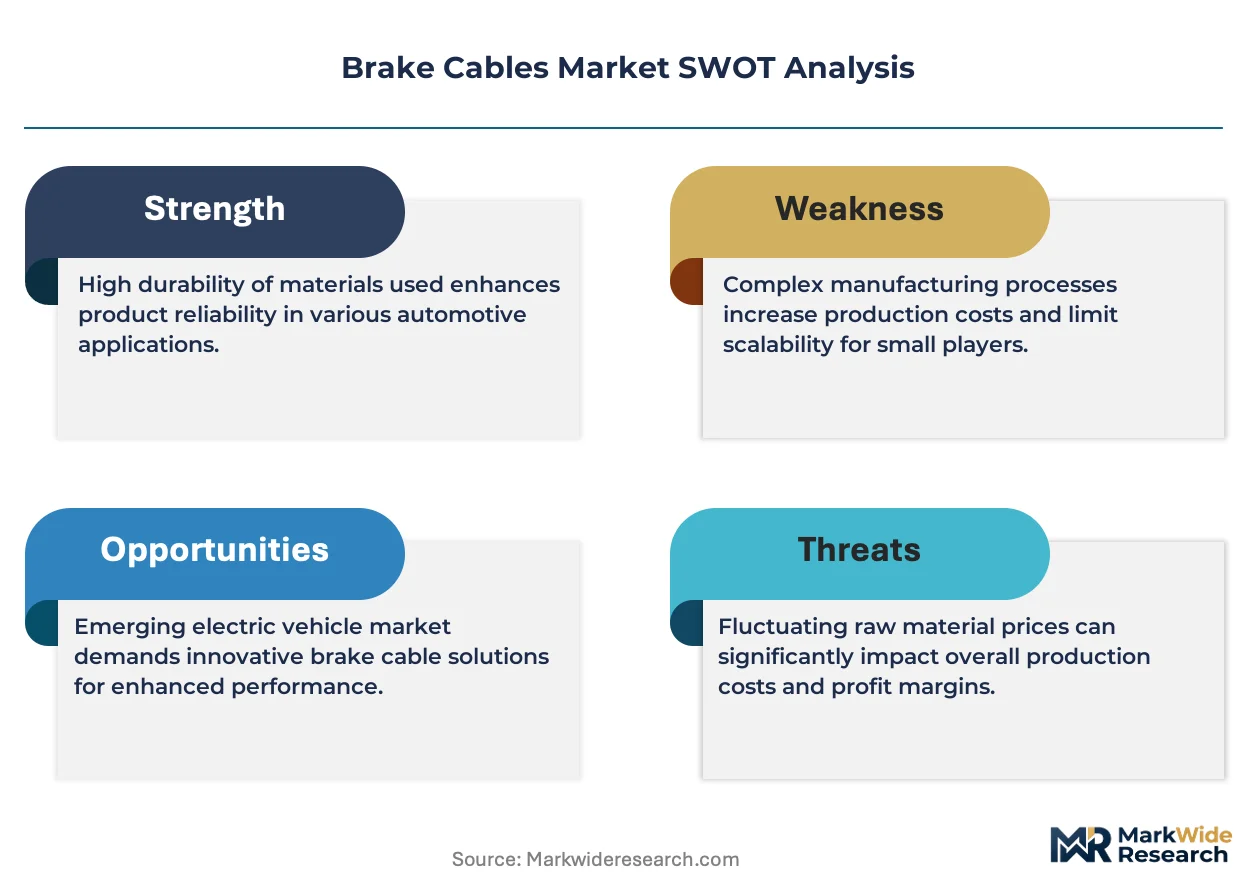
Brake-by-wire electrification is compressing demand for mechanical cable assemblies while simultaneously elevating specification requirements for the electronic connection types that remain. This technological displacement is redistributing value capture across the supplier base.
Growth Catalysts
- ECE R90 Certification:Europe's brake component equivalency framework mandates material traceability and performance testing, creating pull for certified cable assemblies in aftermarket channels.
- Commercial Vehicle Fatigue Standards:Heavy-duty applications require corrosion-resistant coated cables with extended replacement cycles, sustaining premium pricing tiers.
- Stuttgart-Wolfsburg Supplier Corridor:Germany's automotive engineering concentration generates dense OEM procurement activity for precision cable assemblies.
Market Restraints
- Steel Wire Volatility:Galvanized and stainless steel input costs fluctuate with raw material markets, squeezing foundry margins unpredictably.
- Precision Technician Scarcity:Shortage of wire-drawing specialists is unwinding capacity expansion plans at multiple production facilities.
- Hydraulic Circuit Persistence:Cost-sensitive vehicle platforms continue specifying conventional brake systems, delaying full electrification timelines.
Strategic Opportunities
- India Two-Wheeler Aftermarket:Dense service network penetration offers volume expansion for replacement cable suppliers.
- GB/T Localization:China's SAMR-administered automotive cable standards create qualification pathways for domestic OEM supply.
- Polymer-Core Convergence:Advanced polymer materials combined with electronic integration enable lighter, smarter cable designs for next-generation platforms.
Industry Challenges
- ECE R90 Equivalency Testing:Extended certification timelines delay aftermarket component market entry and tie up engineering resources.
- Legacy System Integration:Electronic brake-by-wire architectures must interface with existing vehicle platforms, complicating design validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brake Cables Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cables, Heavy-Duty Cables, Specialty Cables, Adjustable Cables End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Maintenance Providers Connection Type: Mechanical, Hydraulic, Electronic, Pneumatic Material: Steel, Aluminum, Composite, Rubber |
| Companies Covered | Hi-Lex, Suprajit, Minda, Dura Automotive Systems, Ficosa, Küster, TSC, Kongsberg Automotive, AGS Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brake Cables Market Strategic Shifts
Material science advances and regulatory precision are reshaping competitive advantage in cable assemblies. Suppliers now compete on traceability depth and electronic integration capability rather than commodity volume.
Coated cable assemblies are bifurcating the European premium vehicle segment. Küster and comparable specialists apply polymer-over-steel constructions that withstand salt-spray corrosion cycles. OEMs specify these for warranty-critical brake systems. The technology is bifurcating procurement into certified premium tiers versus standard commodity supply.
REACH material disclosure mandates in Europe are compressing formulation flexibility for polymer core suppliers. ECHA registration requirements now extend to cable coating chemistries. Asian compounders are responding by establishing EU-based testing partnerships to maintain qualification status.
Aftermarket distribution is consolidating around certified-equivalence positioning. Independent service channels increasingly stock ECE R90-documented cables rather than unbranded alternatives. This preference shift is most visible in Germany's dense workshop networks, where liability exposure drives specification discipline.
Brake Cables Market Segmentation
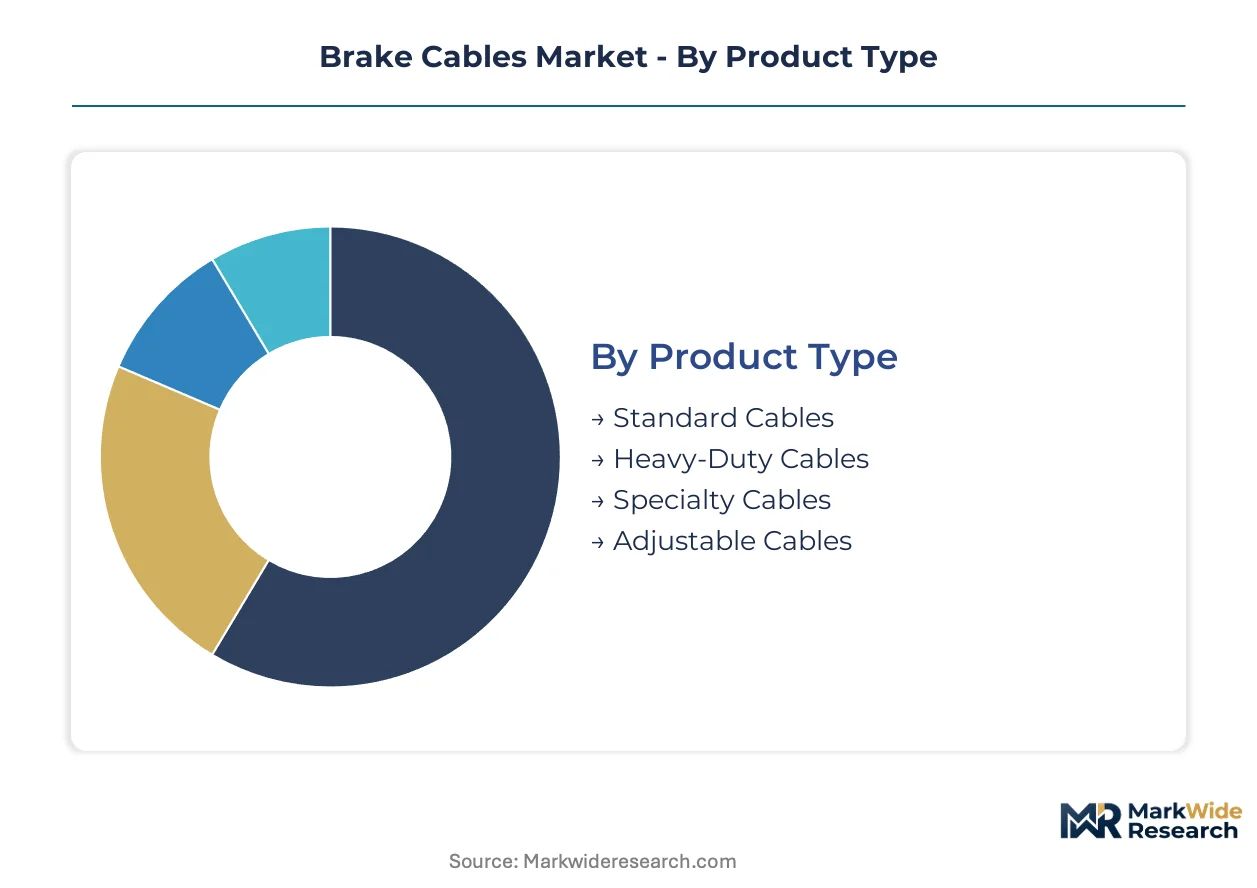
Brake cable segmentation reveals how value migrates across mechanical, hydraulic, and electronic architectures. Suppliers configure production footprints differently depending on which tier they target.
Product Type:
Margin pools concentrate in fatigue-resistant specifications where replacement cycles extend and warranty exposure justifies premium pricing.
- Standard Cables:Galvanized steel wire strands wound around polymer cores serve cost-sensitive two-wheeler and entry passenger car platforms. India's dense service network generates replacement volume for these commodity-grade assemblies.
- Heavy-Duty Cables:Coated steel constructions with enhanced corrosion protection sustain premium positioning in commercial vehicle applications. ECE R90 certification requirements in Germany's automotive corridor reinforce specification discipline for this tier.
- Specialty Cables:Custom-engineered assemblies for extreme temperature or chemical exposure environments.
- Adjustable Cables:Length-modifiable designs accommodating platform variations across vehicle model ranges.
The dominant share belongs to Standard Cables, while Heavy-Duty Cables is closing the gap fastest.
End User:
Procurement patterns diverge sharply between specification-driven OEM channels and price-sensitive aftermarket flows.
- OEMs:Vehicle manufacturers specify brake-by-wire electronic cable assemblies as mechanical linkages phase out. Stuttgart-Wolfsburg engineering concentration generates dense qualification activity for precision suppliers.
- Aftermarket Suppliers:Independent distribution channels stock ECE R90-documented cables to manage liability exposure. Germany's workshop networks exhibit strongest preference for certified-equivalence positioning.
- Vehicle Assemblers:Contract manufacturers integrating brake systems into complete vehicle builds.
- Maintenance Providers:Service operators performing cable replacement across fleet and consumer vehicle bases.
OEMs command the largest procurement volumes, though Aftermarket Suppliers are expanding most quickly as vehicle parc ages.
Connection Type:
Technology displacement is redistributing value capture as brake-by-wire architectures displace legacy mechanical systems.
- Mechanical:Tensile steel cable assemblies transmitting pedal force directly to wheel mechanisms. Cost-sensitive platforms in India and Southeast Asia sustain demand for these proven constructions.
- Hydraulic:Fluid-pressure circuits with cable-actuated master cylinders dominating mid-market passenger vehicles. Persistent cost engineering delays full electrification timelines across volume segments.
- Electronic:Sensor-integrated cable assemblies enabling brake-by-wire architectures with no mechanical backup. European premium vehicle programs specify these for weight reduction and packaging flexibility.
- Pneumatic:Air-pressure systems in heavy commercial and industrial vehicle applications.
Mechanical connections retain the widest installed base, while Electronic types are gaining share fastest as OEMs redesign platforms.
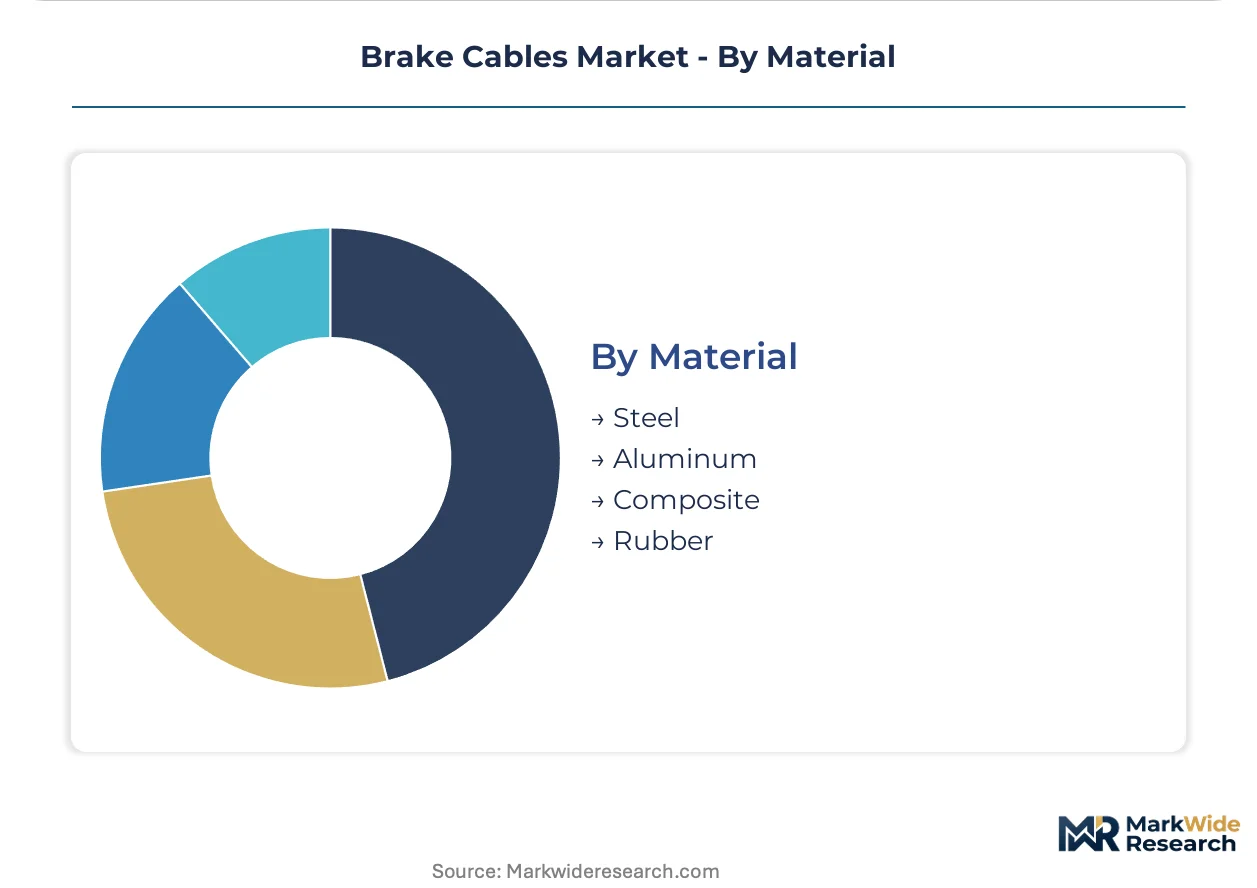
Material:
Input cost volatility and REACH disclosure mandates are compressing formulation flexibility for compounders.
- Steel:Galvanized and stainless wire grades providing tensile strength and fatigue resistance. Raw material price swings squeeze foundry margins unpredictably.
- Aluminum:Lightweight alloy conductors reducing unsprung mass in performance-oriented applications.
- Composite:Advanced polymer-over-steel constructions specified for salt-spray corrosion resistance in European premium programs.
- Rubber:Elastomeric sheathing and core materials providing environmental sealing and vibration damping.
Steel dominates material consumption, while Composite formulations are climbing the fastest on specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cable assemblies in Germany command pricing multiples over commodity-grade Indian production, creating a structural margin asymmetry that shapes supplier investment decisions across both markets.
Germany
Stuttgart and Wolfsburg anchor dense automotive engineering clusters where OEMs specify ECE R90-certified coated cable assemblies for warranty-critical brake systems. KBA vehicle-type approval processes enforce material traceability documentation that extends certification timelines. Suppliers in Baden-Württemberg and Lower Saxony concentrate on fatigue-resistant specifications for commercial vehicle programs.
China
Domestic OEMs accelerate brake-by-wire platform development while SAMR-administered GB/T standards impose localization requirements on foreign cable suppliers. Dual carbon policy targets drive material efficiency mandates across automotive component manufacturing. Yangtze River Delta production bases scale electronic cable assembly capacity for next-generation vehicle architectures.
United States
NHTSA Federal Motor Vehicle Safety Standards govern brake system performance thresholds that sustain demand for heavy-duty corrosion-resistant cables in commercial fleets. Rust Belt manufacturing corridors around Detroit and Cleveland retain precision wire-drawing capabilities for OEM supply. Aftermarket channels in the Midwest and Southeast stock certified-equivalence cables to manage liability exposure.
India
Two-wheeler replacement volume concentrates in Maharashtra and Tamil Nadu service networks where dense aftermarket distribution sustains commodity-grade cable demand. BIS automotive component standards create compliance pathways for domestic suppliers. Gujarat and Karnataka manufacturing bases expand capacity for standard cable exports to Southeast Asian markets.
Japan
METI industrial policy supports brake-by-wire technology development through targeted R&D partnerships between cable specialists and vehicle manufacturers. JIS standards govern material specifications for precision automotive wire products. Chubu region suppliers around Nagoya maintain captive steel-wire production to buffer raw material cost volatility.
Brake Cables Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium specialists and scale-driven fabricators rarely compete directly for the same procurement decisions. The vendor base fragments across three distinct tiers: integrated wire-to-cable manufacturers, precision assembly specialists, and regional volume producers. Strategic differentiation concentrates in captive raw material control, ECE R90 certification depth, and aftermarket distribution density. Competitive moves center on backward integration into steel-wire production and geographic expansion into China and India's domestic OEM supply bases.
Among integrated Japanese and European manufacturers, Hi-Lex and Küster occupy positions that exemplify technology-forward specialization, while Suprajit represents the scale-driven, aftermarket-anchored archetype prevalent in emerging market supply. These three entities illustrate how competitive positioning diverges between premium OEM qualification and high-volume replacement channel penetration.
| Leading Market Players |
|---|
| Hi-Lex |
| Suprajit |
| Minda |
| Dura Automotive Systems |
| Ficosa |
| Küster |
| TSC |
| Kongsberg Automotive |
| AGS Company |
| Others |
Value Chain & Pricing Dynamics
Electronic brake-by-wire cable assemblies displacing mechanical linkages simultaneously concentrate supply geography in Germany's Stuttgart-Wolfsburg corridor and compress pricing premiums for commodity-grade standard cables. This substitution dynamic bifurcates procurement into specification-driven OEM tiers versus price-sensitive aftermarket channels.
Pricing Analysis
Premium cable assemblies in Germany command multiples over Indian commodity production, with ECE R90 certification and coated corrosion-resistant constructions driving premium-mid-economy pricing differentiation. Steel wire input volatility squeezes foundry margins unpredictably, intensifying cost compression in standard cable tiers. OEM vehicle manufacturers exhibit lowest price sensitivity due to warranty exposure, while India's two-wheeler aftermarket channels prioritize unit economics over certification depth.
Supply Chain Analysis
Germany, China, and India anchor brake cable manufacturing, with Baden-Württemberg and Lower Saxony specializing in precision coated assemblies while Maharashtra and Tamil Nadu service dense replacement networks. Galvanized steel wire, polymer core compounds, and electronic sensor modules constitute critical input dependencies. Single-source vulnerability concentrates in European specialty coating chemistries subject to REACH disclosure mandates. Distribution runs through certified-equivalence aftermarket channels in Germany and OEM-direct supply in China's Yangtze River Delta production bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brake-by-wire platform economics create an inflection where mechanical cable suppliers must pivot toward electronic integration or cede OEM qualification to wiring harness specialists. The interoperability shift between legacy hydraulic architectures and sensor-integrated brake systems redistributes value capture across the supply base.
For Market Incumbents: Compound defensive positioning through captive steel-wire production and ECE R90 certification depth to insulate margins from raw material volatility and aftermarket liability exposure. Hi-Lex's backward integration model and Küster's coated assembly specialization illustrate how technology-forward suppliers defend share against emerging electronic-focused entrants. Prioritize qualification pathways for China's GB/T standards to retain domestic OEM access.
For New Entrants and Emerging Players: Differentiate on polymer-core electronic integration capabilities targeting European premium vehicle programs where brake-by-wire architectures displace mechanical systems. India's two-wheeler aftermarket offers the most penetrable white space for volume-driven entrants, with dense Maharashtra and Tamil Nadu service networks sustaining replacement demand. Pursue ECE R90 equivalency documentation as the primary go-to-market credential for liability-conscious German workshop channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive cable specialists lacking electronic integration roadmaps or China localization capabilities. Long-term viability across the analysis window hinges on brake-by-wire platform penetration rates and regulatory divergence between ECE R90, NHTSA, and GB/T frameworks. Monitor OEM procurement shifts toward sensor-integrated cable assemblies as the inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel-Wire Production | Hi-Lex's captive supply buffers margin compression from galvanized steel volatility. |
| ECE R90 Certification Investment | Küster's coated assembly qualification secures warranty-critical premium vehicle programs. |
| GB/T Localization Partnership | SAMR-administered standards create domestic OEM supply pathways for foreign suppliers. |
| Polymer-Core Electronic Integration | Advanced materials enable lighter, smarter cable designs for brake-by-wire platforms. |
| India Aftermarket Distribution Expansion | Suprajit's dense two-wheeler service network penetration captures replacement volume. |
Study Parameters
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution heads, and precision wire-drawing technicians provided ongoing calibration across primary fieldwork. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, ECE R90 certification databases, SAMR GB/T standard disclosures, vehicle production registries, and SEC automotive supplier filings. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured consistency across value and volume outputs.
Consistency checks validated projections against external benchmarks including IHS Markit vehicle registration data, automotive wire harness production indices, and regional OEM procurement disclosures. The analytical framework modeled segmentation across connection type, material composition, end-user channel, and regional regulatory cluster throughout the forecast period. CAGRs were derived from trend-line extrapolation of brake-by-wire platform penetration, steel price cycle assumptions, and certification timeline compression.
Decision-makers should treat outputs as directional under base assumptions of gradual brake-by-wire adoption and stable ECE R90 equivalency timelines; material deviation in electrification speed or regulatory divergence would warrant model refresh. Specific risks include hydraulic circuit persistence in cost-sensitive segments, precision technician scarcity constraining capacity expansion, and REACH disclosure mandates compressing polymer formulation flexibility. Recalibration cycles align with material shifts in OEM platform electrification roadmaps and regional certification requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Electric and Autonomous Vehicles Wiring Harness Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market