
 North America Automotive Smart Key Market | 2026-2036
North America Automotive Smart Key Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Smart Key Market Analytics
Market Context
Fleet procurement consolidation among premium electric vehicle OEMs is repositioning supplier negotiation leverage across the North American supply base. Continental AG leverages its integrated body electronics division to sustain long-term platform contracts with Detroit-based manufacturers. Denso Corporation anchors its regional position through dedicated R&D facilities in Tennessee focused on low-frequency antenna miniaturization.
Technical Definition and Structural Segments
North America automotive smart keys are encrypted radio-frequency transponder assemblies operating at 125 kHz for low-frequency wake-up and 433 MHz for ultra-high-frequency data exchange, designed to authenticate vehicle access without physical key insertion. Bluetooth-enabled systems dominate current OEM fitment due to smartphone integration compatibility, while biometric authentication represents the fastest-growing feature category as fingerprint sensors achieve automotive-grade temperature cycling validation. Passive entry modules command premium margin pools because they require multi-antenna vehicle architectures and sophisticated proximity detection algorithms.
Regulatory Frame and Outlook
NHTSA cybersecurity guidelines and Transport Canada's motor vehicle safety standards are mandating encrypted communication protocols between key fobs and vehicle immobilizer units, directly shaping hardware design requirements. The EPA's incidental radiator emissions framework and FCC Part 15 rules govern permissible frequency spectrums for keyless entry transmission power. Stakeholders must monitor evolving insurance industry premium structures tied to vehicle theft rates, as these increasingly influence OEM specification decisions for anti-theft feature bundling.
Market Dynamics
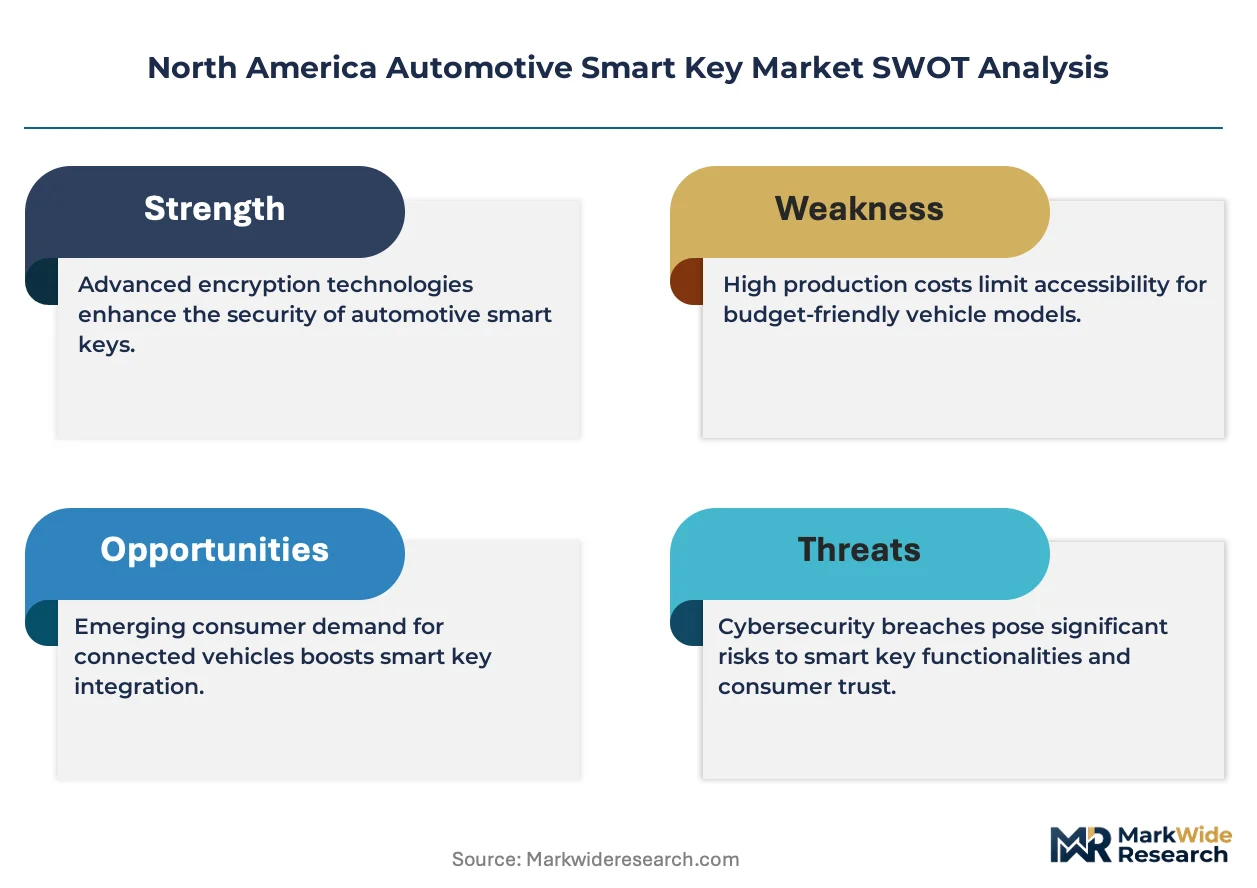
Passive entry system proliferation across Detroit Three and premium EV lineups is compressing supplier development cycles while elevating hardware encryption standards mandated by NHTSA cybersecurity guidelines.
Growth Catalysts
- NHTSA Cybersecurity Guidelines:Federal mandates for encrypted immobilizer-to-fob communication are compelling Tier-1 suppliers to redesign RF transponder architectures, accelerating hardware refresh cycles across US assembly corridors.
- Biometric Authentication:Fingerprint sensors achieving AEC-Q100 qualification are unlocking premium feature bundling in luxury electric vehicle segments, creating new margin pools for authentication module suppliers.
- Midwest Manufacturing Concentration:Michigan, Ohio, and Illinois assembly plants account for disproportionate smart key procurement volumes, anchoring supplier R&D facility placement decisions.
Market Restraints
- Semiconductor Input Volatility:RF transceiver chip supply constraints from concentrated Asian foundry capacity expose North American module assemblers to allocation risk and extended lead times.
- FCC Part 15 Emission Limits:Strict ultra-high-frequency transmission power caps constrain passive entry range extension, forcing antenna array complexity increases that elevate BOM costs.
- Smartphone Digital Key Substitution:Apple CarKey and Google Wallet vehicle integration threaten dedicated fob attachment rates in entry-luxury segments, compressing unit volume forecasts.
Strategic Opportunities
- Canada Theft Prevention Mandates:Transport Canada's evolving motor vehicle safety standards for immobilizer effectiveness create regulatory tailwind for encrypted smart key specification in cross-border vehicle platforms.
- UWB + Bluetooth Convergence:Ultra-wideband precision ranging fused with Bluetooth Low Energy stack is enabling centimeter-accurate passive entry, differentiating next-generation systems from incumbent RF-only architectures.
- Insurance Premium Linkage:US property-casualty carriers are tiering comprehensive coverage rates by factory-installed anti-theft feature sets, incentivizing OEMs to bundle smart keys across trim levels.
Industry Challenges
- Embedded Firmware Talent Scarcity:Cryptographic protocol engineering and RF antenna simulation expertise shortages in Tennessee and Michigan R&D clusters are elongating product validation timelines.
- Legacy Vehicle Integration Complexity:Retrofitting encrypted immobilizer architectures into carryover platforms designed for unidirectional transponder communication demands extensive gateway ECU reprogramming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Smart Key Market |
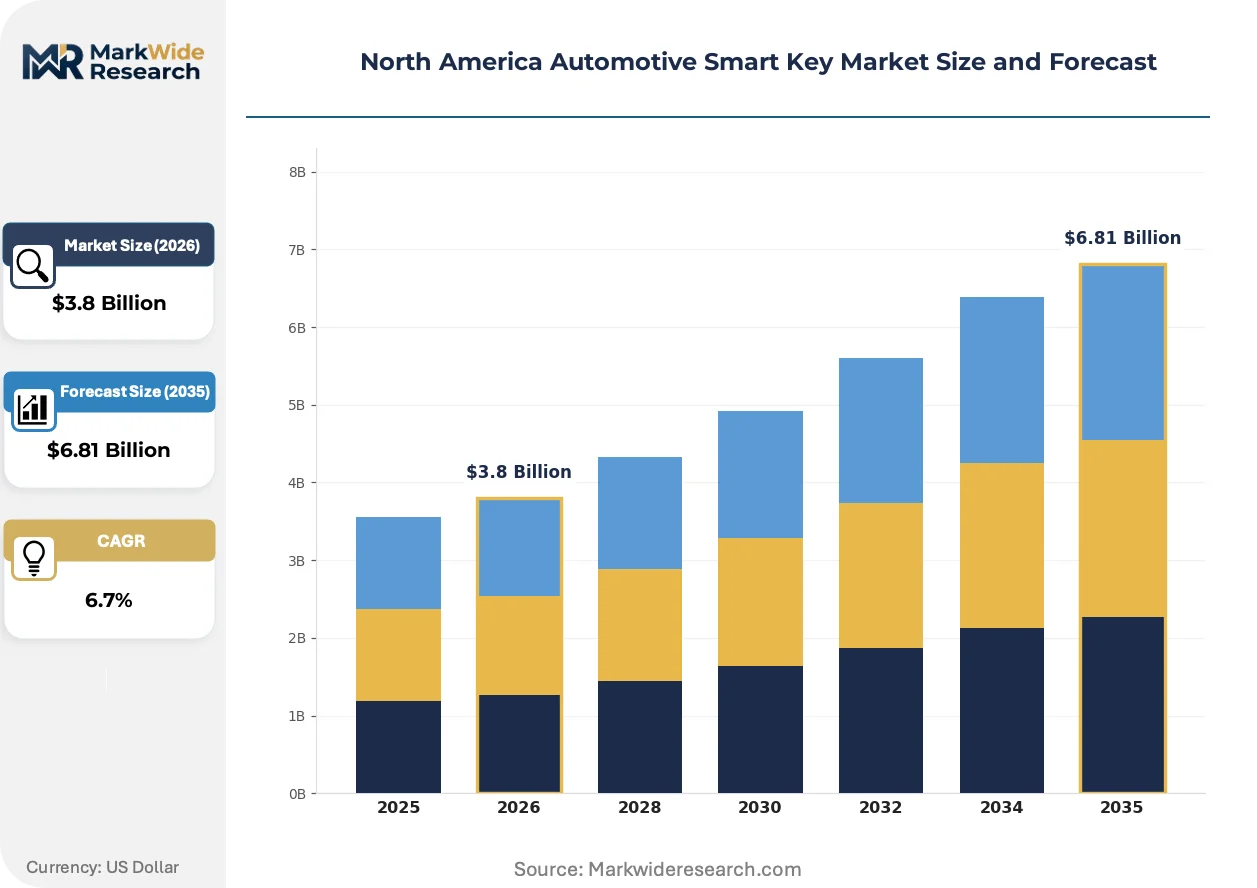
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth, RFID, NFC, Biometric End User: OEMs, Dealerships, Aftermarket Providers, Vehicle Assemblers Feature: Remote Start, Keyless Entry, Anti-Theft, Passive Entry Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | Continental AG, Denso Corporation, HELLA GmbH & Co. KGaA, ZF Friedrichshafen AG, Valeo SA, Tokai Rika Co. Ltd, Alpha Corp, Huf Hulsbeck & Furst GmbH & Co. KG, Hyundai Mobis Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Smart Key Market Evolving Landscape
Smartphone-centric access architectures are fragmenting traditional fob-centric business models while elevating software-defined security requirements across North American OEM roadmaps.
Ultra-wideband positioning technology is decentralizing proximity detection responsibilities from vehicle-mounted LF antenna arrays to distributed UWB anchors embedded in door handles and cabin pillars. Cadillac and BMW are deploying UWB-enabled smart keys in MY2024-2025 electric vehicle launches, achieving 10-centimeter spatial accuracy for hands-free entry authentication. This spatial precision is decentralizing security trust boundaries from perimeter-based to occupant-zone-based access authorization, compressing the relevance of legacy multi-antenna LF architectures.
NHTSA cybersecurity guidelines finalized in 2024 mandate cryptographic message authentication between key fobs and immobilizer units, prohibiting unidirectional transponder protocols in new vehicle certifications. The regulation forces hardware security module integration into previously cost-optimized entry-segment smart key designs, elevating per-unit silicon content. Suppliers serving the US Midwest manufacturing corridor are responding with FCC pre-certified module platforms that accelerate OEM homologation timelines.
Fleet procurement consolidation among premium electric vehicle OEMs is compressing supplier negotiation leverage and elevating long-term platform contract durations. Detroit-based manufacturers are consolidating smart key sourcing across multiple nameplates, displacing spot-buy arrangements with multi-year sole-source agreements. This concentration is most visible in Michigan assembly plants where single-source passive entry module awards now span five-year vehicle lifecycles.
North America Automotive Smart Key Market Segmentation
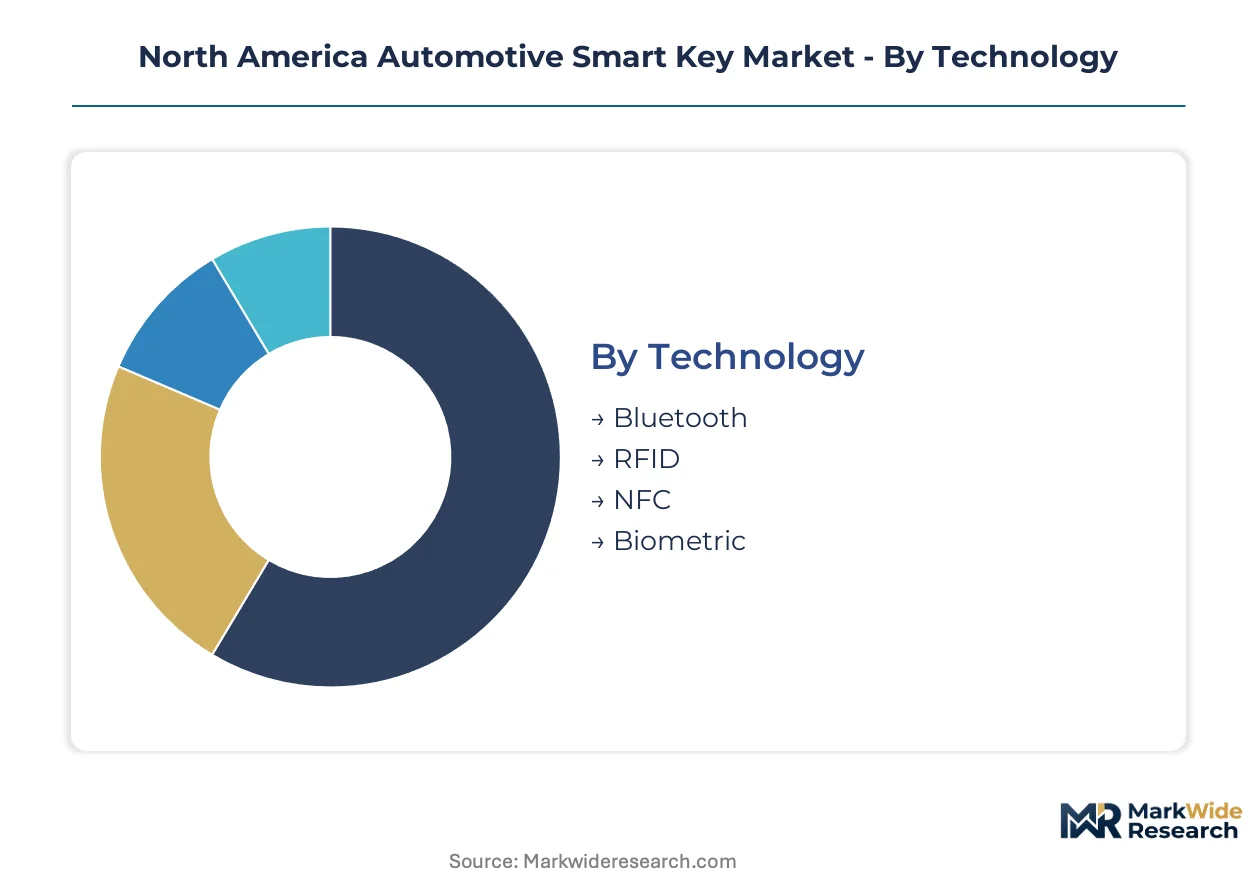
Technology differentiation and feature bundling strategies create distinct procurement patterns across North American automotive smart key channels. OEM specification decisions cascade through tiered supply chains, compressing margin structures for standardized offerings while elevating premium authentication modules.
Technology:
Procurement teams prioritize wireless protocol compatibility against existing vehicle electronic architectures and smartphone ecosystem integration roadmaps.
- Bluetooth:Dominant protocol for smartphone digital key integration, with Low Energy stack enabling sub-10-meter proximity detection. Demand concentrates in Detroit Three and premium EV lineups across Michigan and Ohio assembly plants, driven by Apple CarKey and Google Wallet compatibility requirements.
- Biometric:Fingerprint and facial recognition sensors achieving AEC-Q100 automotive qualification. Adoption clusters in luxury electric vehicle segments from California-based OEMs, propelled by NHTSA cybersecurity guidelines mandating multi-factor authentication for immobilizer systems.
- RFID:Legacy 125 kHz low-frequency wake-up architectures with unidirectional transponder communication.
- NFC:Near-field pairing for smartphone tap-to-unlock functionality in entry-luxury nameplates.
Volume sits with Bluetooth; growth tilts toward Biometric.
End User:
Contract duration and specification authority vary sharply across direct OEM supply versus fragmented aftermarket channels.
- OEMs:Platform-level procurement with five-year sole-source agreements and embedded firmware customization. Sourcing concentrates among Detroit-based manufacturers consolidating multi-nameplate smart key awards, shaped by FCC pre-certification requirements and NHTSA homologation timelines.
- Vehicle Assemblers:Contract manufacturing arrangements for cross-border production platforms serving US Midwest and Ontario corridors. Procurement patterns track Transport Canada theft prevention mandate compliance for unified North American vehicle specifications.
- Dealerships:Replacement key programming and lost-key recovery services.
- Aftermarket Providers:Third-party fob cloning and universal remote start modules.
Revenue concentrates with OEMs; margin expansion favors Vehicle Assemblers.
Feature:
Hardware complexity and antenna array requirements segment pricing tiers across passive versus active authentication modes.
- Passive Entry:Hands-free door unlock requiring multi-antenna vehicle architectures and sophisticated proximity detection algorithms. Fitment expands across premium EV and luxury internal combustion nameplates from Tennessee and Michigan production facilities, driven by insurance premium tiering for factory-installed anti-theft feature sets.
- Anti-Theft:Encrypted immobilizer-to-fob communication with hardware security module integration. Specification accelerates under NHTSA cybersecurity guidelines prohibiting unidirectional transponder protocols in new vehicle certifications.
- Remote Start:Two-way RF transceiver enabling climate preconditioning from extended range.
- Keyless Entry:Button-activated door unlock without physical key insertion.
Unit volume clusters around Remote Start; value capture peaks with Passive Entry.
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and regional regulatory pre-certification needs.
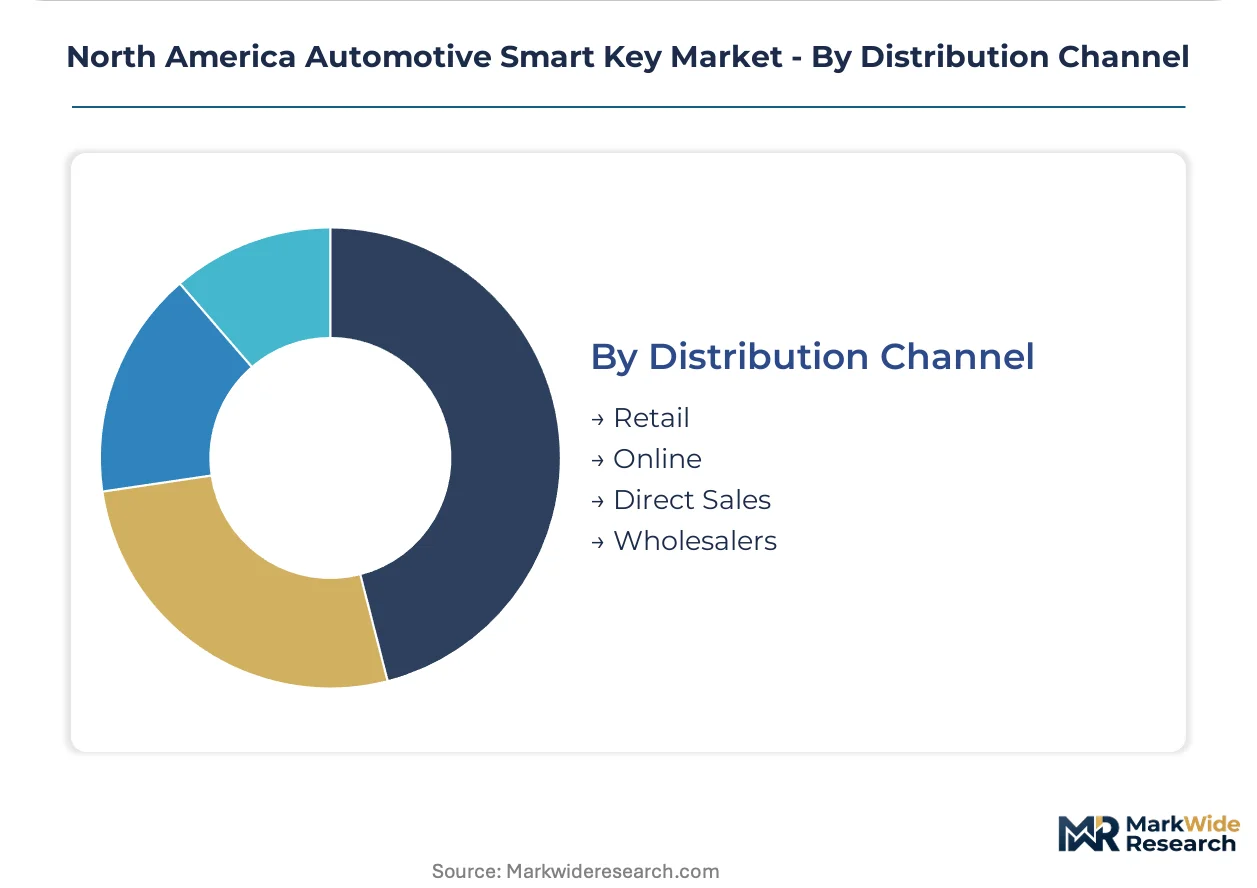
- Direct Sales:Long-term platform contracts with dedicated engineering support and FCC pre-certified module platforms. Procurement anchors in US Midwest automotive manufacturing corridor spanning Michigan, Ohio, and Illinois assembly plants, compelled by NHTSA cybersecurity guideline compliance and accelerated OEM homologation timelines.
- Wholesalers:Aggregated procurement for mid-tier aftermarket providers and regional dealership networks.
- Retail:Consumer-facing replacement fob sales through auto parts chains.
- Online:E-commerce channels for universal remote start kits and programming tools.
Transaction volume flows through Retail; contract value concentrates in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart key procurement concentrates in the US Midwest automotive manufacturing corridor, where Michigan, Ohio, and Illinois assembly plants generate disproportionate demand volumes for encrypted immobilizer and passive entry systems.
United States
Detroit Three manufacturers consolidate multi-nameplate smart key sourcing through five-year sole-source agreements, compressing supplier negotiation leverage. NHTSA cybersecurity guidelines finalized in 2024 mandate cryptographic message authentication for all new vehicle certifications, forcing hardware security module integration into previously cost-optimized designs. Tennessee R&D clusters anchor antenna miniaturization development for low-frequency wake-up architectures serving regional assembly plants.
Canada
Transport Canada's evolving motor vehicle safety standards for immobilizer effectiveness create regulatory tailwind for encrypted smart key specification in cross-border vehicle platforms. Ontario production facilities serving unified North American specifications drive demand for FCC pre-certified module platforms that accelerate OEM homologation timelines. Quebec-based vehicle assemblers track US Midwest procurement patterns for passive entry system fitment across premium EV nameplates.
Mexico
Bajío Region and Northern Border States assembly plants integrate smart key modules for export-oriented production serving US market specifications. The country's automotive manufacturing growth concentrates encrypted transponder demand near Mexico City Metro and Nuevo León industrial corridors. Mexican facilities adopt NHTSA-aligned cybersecurity protocols for vehicles destined for US Midwest distribution channels.
North America Automotive Smart Key Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biometric authentication and ultra-wideband precision ranging adjacent spaces. The supplier base consolidates around integrated body electronics divisions capable of delivering FCC pre-certified platforms with embedded firmware customization. Three archetypes dominate: diversified automotive electronics conglomerates with regional R&D facilities, specialized transponder and antenna module fabricators, and smartphone ecosystem integrators pursuing digital key substitution. Competitive dynamics center on multi-year platform contract duration extension and hardware security module integration capabilities.
Among Germany-based automotive suppliers, Continental AG and ZF Friedrichshafen AG exemplify diversified electronics conglomerates with integrated body electronics divisions. Denso Corporation represents Japanese-tier specialists anchoring regional positions through dedicated R&D facilities. These three occupy positions spanning the premium passive entry module tier where multi-antenna vehicle architectures and sophisticated proximity detection algorithms command premium margin pools.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| HELLA GmbH & Co. KGaA |
| ZF Friedrichshafen AG |
| Valeo SA |
| Tokai Rika Co. Ltd |
| Alpha Corp |
| Huf Hulsbeck & Furst GmbH & Co. KG |
| Hyundai Mobis Co. Ltd |
| Others |
Value Network & Pricing Analysis
RF transceiver silicon from concentrated Asian foundry capacity flows through three distinct pricing tiers before reaching Detroit Three assembly plants, with hardware security module integration mandated by NHTSA cybersecurity guidelines compressing margins at the standard tier while elevating premium authentication module valuations.
Pricing Analysis
Volume concentrates in Bluetooth-enabled entry-segment modules while value capture peaks with biometric-enabled passive entry systems. Pricing stratifies across premium, standard, and economy tiers based on antenna array complexity and FCC pre-certification status. Cost compression in the economy tier is intensifying because smartphone digital key substitution threatens dedicated fob attachment rates. Fleet procurement teams at premium EV OEMs exhibit lowest price sensitivity; aftermarket providers face acute margin pressure from universal remote start commoditization.
Supply Chain Analysis
USMCA domestic-content thresholds are reshaping sourcing patterns for encrypted transponder assemblies, compelling module assemblers to qualify alternative RF chip suppliers outside traditional Asian foundry networks. Manufacturing draws from Taiwan and South Korea for RF transceiver silicon, Japan for precision antenna components, and Mexico for final module integration. Single-source vulnerability in 125 kHz wake-up controller supply creates allocation risk exposure. Distribution runs through direct OEM platform contracts with embedded engineering support, bypassing wholesale aggregation for new vehicle fitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into RF semiconductor sourcing and antenna miniaturization R&D represents the critical vertical-integration race, as NHTSA cybersecurity mandates force hardware security module capabilities that only captive silicon design can deliver cost-effectively.
For Market Incumbents: Acquire RF antenna simulation expertise and cryptographic firmware engineering talent in Tennessee and Michigan R&D clusters. Consolidate five-year sole-source platform contracts across Detroit Three multi-nameplate awards before UWB precision ranging displaces legacy LF architectures. Deepen backward integration into FCC pre-certified module platforms to accelerate OEM homologation timelines against emerging smartphone ecosystem integrators.
For New Entrants and Emerging Players: Begin with biometric authentication module supply for California-based luxury electric vehicle OEMs, where AEC-Q100 qualified fingerprint sensors remain undersupplied. Target vehicle assembler contract manufacturing arrangements in Ontario and Quebec corridors, where Transport Canada theft prevention mandates create specification tailwind for encrypted immobilizer platforms. Pursue insurance premium linkage as go-to-market angle, positioning hardware security modules as factory-installed anti-theft features that tier comprehensive coverage rates.
For Investors and Strategic Acquirers: Cadillac and BMW UWB-enabled smart key deployments in MY2024-2025 electric vehicle launches are the leading indicator that centimeter-accurate spatial positioning will compress legacy RF-only architectures within the next vehicle lifecycle. Target specialized transponder fabricators with embedded firmware customization capabilities and existing FCC pre-certification portfolios. Watch for NHTSA cybersecurity guideline enforcement actions against unidirectional transponder protocols as signal that hardware refresh cycles are accelerating.
| Strategic Initiative | Industry Significance |
|---|---|
| UWB + Bluetooth Convergence Investment | Fuses ultra-wideband precision ranging with smartphone ecosystem compatibility for next-generation passive entry. |
| Hardware Security Module Integration | Embeds cryptographic authentication silicon mandated by NHTSA cybersecurity guidelines for new vehicle certifications. |
| Midwest R&D Facility Expansion | Anchors antenna miniaturization development near Michigan, Ohio, and Illinois assembly plant demand concentration. |
| Cross-Border Platform Standardization | Unifies encrypted immobilizer specifications across USMCA production corridors for Transport Canada compliance. |
| Insurance Industry Partnership | Positions factory-installed anti-theft features to influence property-casualty carrier premium tiering structures. |
Research Methodology
Document review covered SEC 10-K filings from automotive electronics suppliers, FCC equipment authorization databases, NHTSA rulemaking dockets, and vehicle production data from IHS Markit, complemented by interviews with Tier 1 supplier procurement executives, OEM platform engineers, aftermarket distributors, and dealership operations managers. Primary fieldwork across Tennessee and Michigan R&D clusters validated secondary estimates against antenna miniaturization development timelines and encrypted module production ramp schedules. Bottom-up bill-of-materials analysis triangulated against top-down OEM procurement budget disclosures.
Cross-referencing historical fitment rates against panel input from platform engineering teams shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include wireless protocol architecture, vehicle propulsion type, content per vehicle tier, OEM premium positioning, and regional production cluster. CAGRs were derived from S-curve adoption modeling for biometric authentication and UWB precision ranging penetration. Forecast inputs incorporated NHTSA cybersecurity guideline implementation schedules and Transport Canada motor vehicle safety standard evolution timelines.
Underlying measurement precision varies by segment; Bluetooth-enabled entry-segment modules carry tighter precision than biometric authentication systems where AEC-Q100 qualification timelines remain fluid. Forecasts reflect assumptions regarding semiconductor supply normalization and USMCA domestic-content threshold enforcement. Unidirectional transponder protocol phase-out acceleration or smartphone digital key substitution rates exceeding baseline scenarios would revise volume projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market