
 Automotive Sparking Cable Market | 2026-2036
Automotive Sparking Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Sparking Cable Market Outlook
Asset-light leasing models for production tooling are fragmenting competitive barriers in automotive sparking cable manufacturing. NGK Spark Plug leverages captive ceramic technology leadership to anchor premium ignition system bundling. Denso sustains integrated coil-on-plug architectures that reduce standalone wire demand in Japanese OEM supply chains. Federal-Mogul competes through aftermarket channel density across North American repair networks.
Automotive sparking cables are high-tension conductors engineered to deliver precisely timed electrical pulses from ignition coils to spark plugs, typically rated between 5,000 and 40,000 volts and insulated with silicone or ethylene-propylene-diene rubber to resist thermal degradation and electromagnetic interference. Their primary function ensures complete combustion in internal combustion engines while suppressing radio-frequency emissions that disrupt onboard electronics. Silicone-insulated spark plug wires command the dominant material position due to superior temperature tolerance and aging resistance, while PVC formulations retain cost-sensitive aftermarket penetration where service intervals compress replacement cycles. Coil wire assemblies represent the fastest-expanding product type as distributorless ignition architectures displace traditional multi-wire harnesses in modern engine bays.
EPA emissions certification and NHTSA electromagnetic compatibility standards in the United States compel OEMs to specify suppression-core cables that minimize interference with advanced driver-assistance sensors. ECE R10 regulations administered under UN Economic Commission for Europe frameworks govern sparking cable electromagnetic emission limits across type-approved vehicles sold in EU member states and affiliated markets. China's GB standards for automotive electrical components, enforced by SAMR conformity assessment procedures, mandate localized testing protocols that shape market access for imported cable assemblies. Stakeholders must monitor evolving powertrain electrification roadmaps to calibrate ignition component portfolios against declining internal combustion engine production volumes.
Market Dynamics
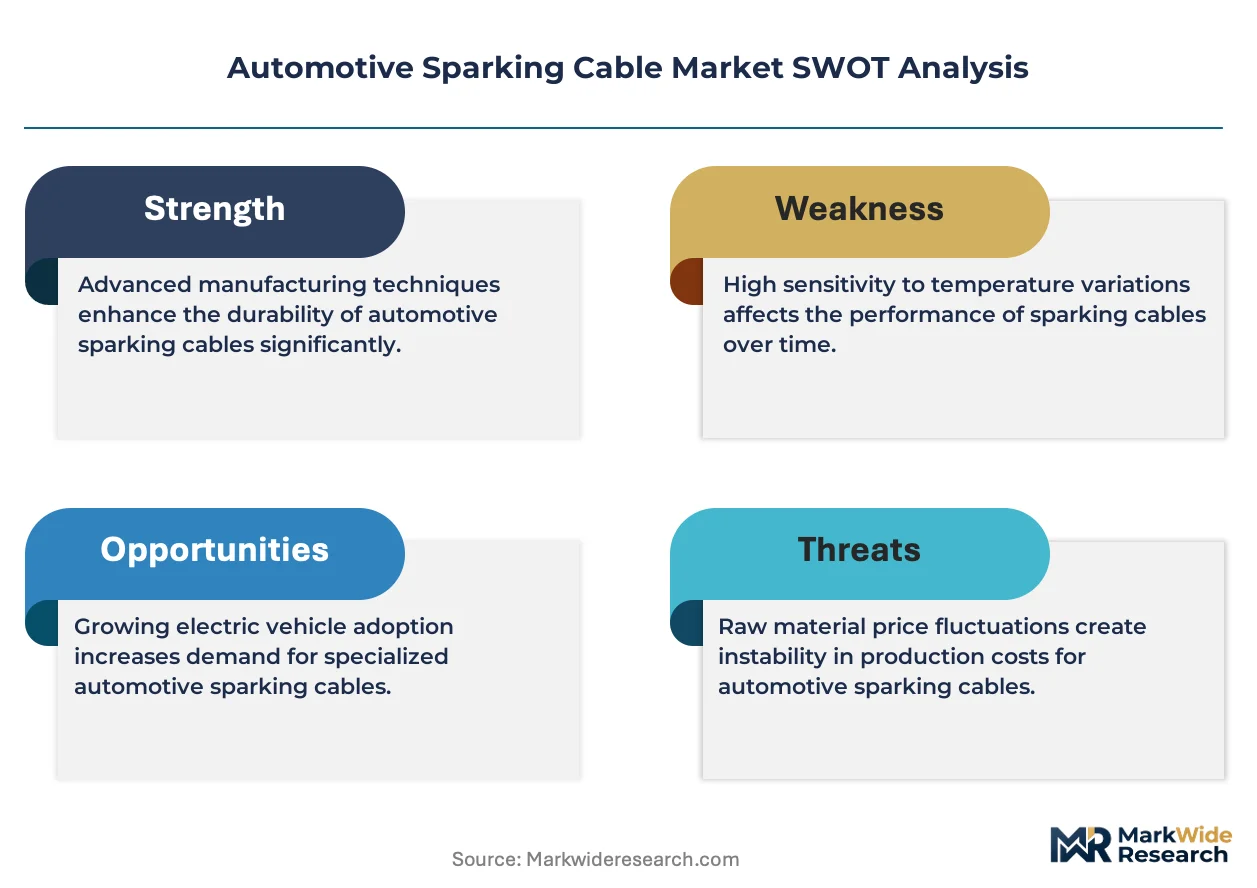
Powertrain electrification roadmaps are fragmenting ignition component demand as OEMs accelerate hybrid system deployments while phasing out pure internal combustion architectures. This structural tension between sustaining legacy sparking cable volumes and pivoting toward high-voltage-compatible assemblies defines current supplier strategy.
Growth Catalysts
- Hybrid powertrain proliferation:Mild-hybrid and full-hybrid vehicle programs sustain ignition system procurement volumes even as battery-electric platforms expand. Japanese and Korean OEM supply chains maintain robust coil-on-plug assembly demand.
- ECE R10 electromagnetic compliance:European type-approval mandates for radio-frequency suppression accelerate silicone-insulated cable substitution across supplier networks serving EU member states.
- China's GB standard localization:SAMR conformity assessment procedures for automotive electrical components compel domestic testing protocols that favor localized ignition system sourcing in eastern manufacturing corridors.
Market Restraints
- Copper and silicone rubber input volatility:Raw material cost swings compress margin structures for cable assemblers lacking backward integration into compound formulation.
- Ignition system supplier concentration:Tier-1 coil-on-plug module producers in Germany and Japan internalize wire harness production, reducing standalone cable procurement opportunities.
- Powertrain electrification substitution:Battery-electric platforms eliminate spark ignition entirely, creating terminal demand erosion for traditional high-tension cable categories.
Strategic Opportunities
- India's expanding passenger vehicle production:Domestic automaker capacity additions in Tamil Nadu and Gujarat create localized ignition component demand as BIS certification requirements favor regional suppliers.
- High-voltage hybrid cable assemblies:48V and 400V mild-hybrid architectures require redesigned insulation systems that merge sparking function with electromagnetic shielding competence.
- Aftermarket channel digitization:E-commerce platforms and direct-to-repair-shop fulfillment models displace traditional distributor layers in North American and European replacement markets.
Industry Challenges
- Compound formulation expertise scarcity:Silicone rubber compounding for thermal and electrical performance requires polymer science capabilities concentrated among legacy suppliers.
- Dual certification timeline compression:Simultaneous OEM qualification for both traditional ignition and emerging high-voltage hybrid cable variants strains engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Sparking Cable Market |
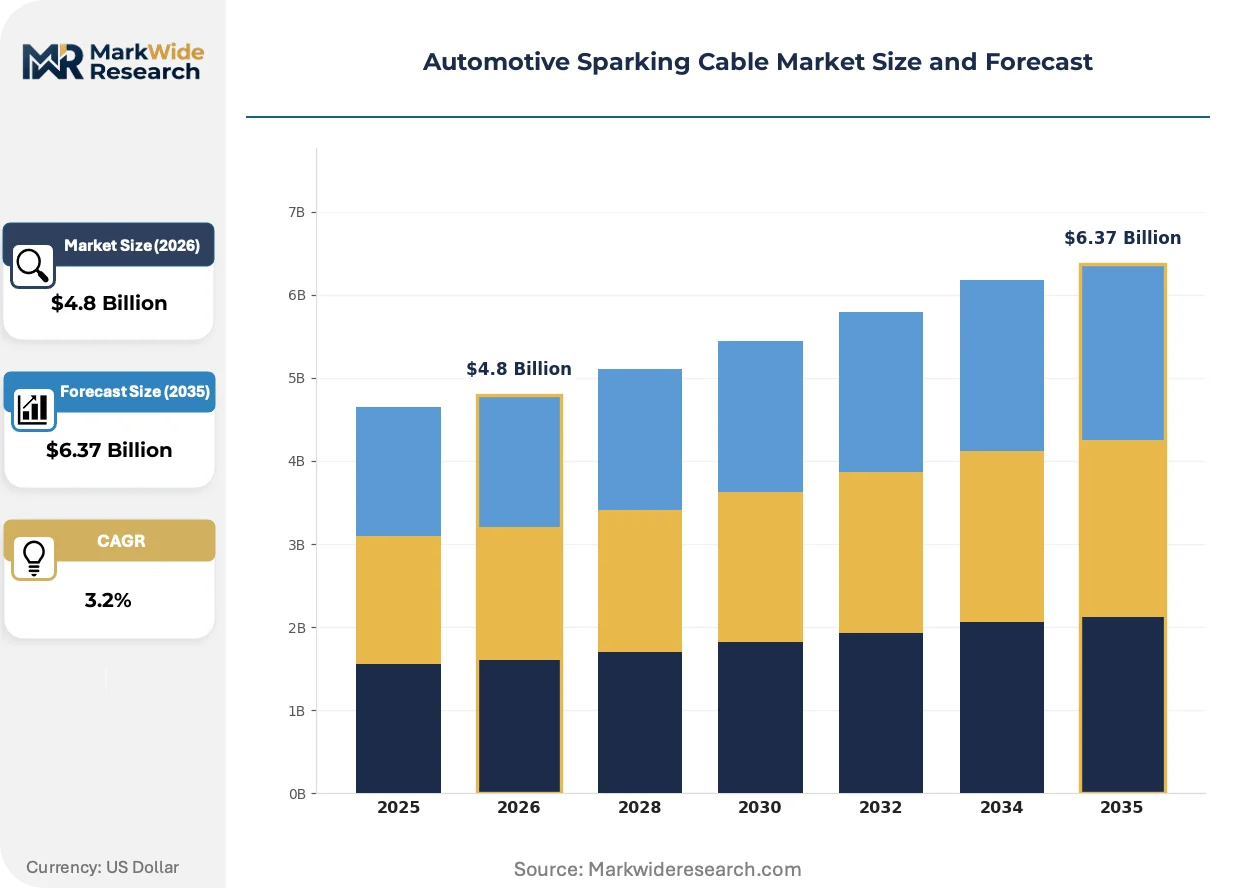
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ignition Cables, Coil Wires, Spark Plug Wires, Distribution Wires Material: Silicone, PVC, Rubber, Fiberglass Installation Type: Aftermarket, OEM, DIY, Professional Connector Type: Push-On, Screw-On, Snap-On, Clip-On |
| Companies Covered | NGK Spark Plug, Denso, Delphi Technologies, Sumitomo Electric Industries, Federal-Mogul, Borg Warner, Valeo, Taylor Cable Products, MSD Spark Wires, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Sparking Cable Market Strategic Shifts
Active material science development is reshaping insulation system performance as thermal envelope requirements expand under downsized turbocharged engine architectures. Supplier R&D priorities now split between sustaining legacy formulations and engineering next-generation compounds.
Smart sparking cable architectures with embedded diagnostic sensors are digitizing condition monitoring capabilities for predictive maintenance applications. Fleet operators and commercial vehicle OEMs in North America are piloting these systems to optimize replacement intervals. The technology is digitizing traditional aftermarket revenue models toward subscription-based health monitoring services.
EPA emissions certification protocols for onboard diagnostic systems are tightening electromagnetic interference thresholds for ignition components. Tier-1 suppliers serving US OEMs must recalibrate suppression-core designs to maintain compliance with NHTSA-adjacent standards. Passenger vehicle platforms with advanced driver-assistance sensor arrays face the most stringent cable specification revisions.
Repair network consolidation is compressing aftermarket channel structures as national service chains centralize procurement authority. Independent repair shops in Germany and France are losing price negotiation leverage against distributor networks. This concentration is most visible in Western European markets where regulatory inspection intervals sustain steady replacement demand.
Automotive Sparking Cable Market Segmentation
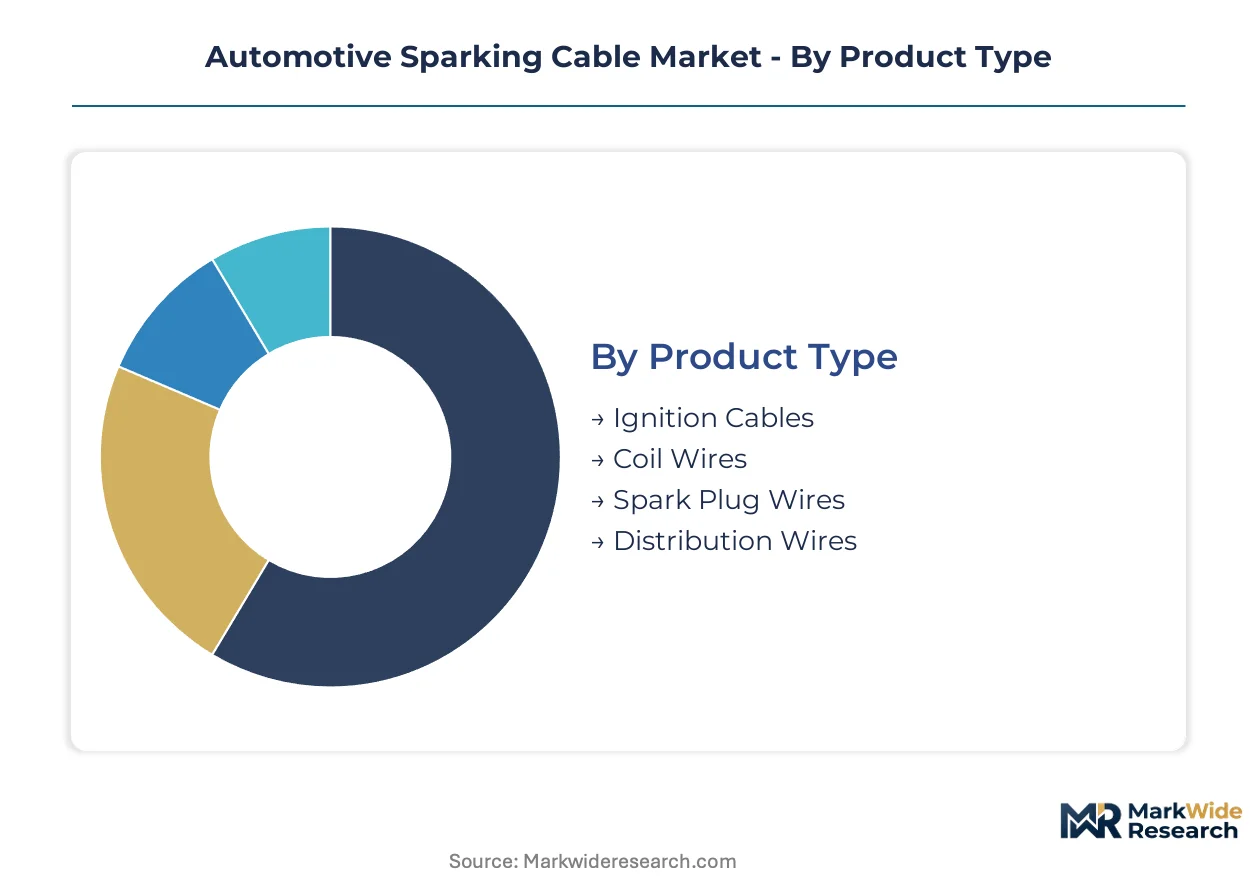
Segmentation in automotive sparking cables reveals divergent margin profiles and replacement cadences across product architectures. Material selection and installation channel determine pricing power and customer loyalty in ways that reshape supplier portfolio priorities.
Product Type:
Replacement cycle velocity varies dramatically across product architectures, with some segments turning over every service interval while others persist for vehicle lifetimes.
- Ignition Cables:Multi-conductor harness assemblies bundling coil-to-distributor and distributor-to-plug pathways in traditional ignition architectures. Demand concentrates in aftermarket channels across North American and European repair networks where aging vehicle fleets sustain replacement volumes.
- Coil Wires:Single-conductor high-tension leads connecting ignition coils to spark plugs in distributorless systems. Coil-on-plug module proliferation in Japanese and Korean OEM supply chains is accelerating procurement of these shortened, precision-terminated assemblies.
- Spark Plug Wires:Individual high-tension conductors with terminal boots at each end, historically the dominant standalone replacement category. Cost-conscious aftermarket penetration persists where service intervals compress replacement cycles.
- Distribution Wires:Legacy harness segments routing voltage from central distributors to multiple cylinders. Terminal demand erosion proceeds as engine architectures abandon distributor-based ignition entirely.
Ignition cables dominate installed base. Coil wires are where expansion concentrates.
Material:
Cost tier stratification separates premium thermal performance from economy-grade substitutions in aftermarket procurement.
- Silicone:Cross-linked polysiloxane insulation systems rated for continuous operation above 200°C with superior ozone and UV resistance. European OEM procurement under KBA electromagnetic compatibility requirements accelerates silicone substitution across German and French supplier networks.
- PVC:Polyvinyl chloride compounds offering cost-minimized insulation for temperature-moderate applications. Budget aftermarket channels in developing markets retain PVC penetration where replacement price sensitivity dominates specification decisions.
- Rubber:Ethylene-propylene-diene monomer and natural rubber formulations balancing flexibility with moderate thermal tolerance. Commercial vehicle applications in high-vibration environments specify reinforced rubber constructions.
- Fiberglass:Braided glass fiber overwraps providing mechanical protection and thermal shielding for extreme-duty engine compartments. Performance and racing aftermarket segments specify fiberglass-reinforced assemblies for turbocharged and downsized engine architectures.
Silicone commands premium OEM specification. PVC retains economy aftermarket volume.
Installation Type:
Channel structure determines margin capture and customer relationship durability across the value chain.
- Aftermarket:Replacement demand through distributor networks, repair shops, and retail channels serving vehicle parc maintenance. E-commerce platform expansion in North America and Europe is digitizing procurement authority away from traditional distributor layers.
- OEM:Original equipment supply contracts with automakers and engine manufacturers for new vehicle production. Japanese and Korean OEM supply chains maintain robust coil-on-plug assembly demand through integrated Tier-1 relationships.
- DIY:Direct consumer purchase for self-installation, concentrated in mature automotive cultures with high vehicle age and enthusiast ownership patterns. North American retail auto parts chains capture this segment through private-label cable assortments.
- Professional:Service bay installation at dealer and independent repair facilities with labor-bundled pricing. National service chain consolidation in Germany and France is compressing price negotiation leverage for independent distributors.
Aftermarket channels dominate transaction volume. OEM supply relationships concentrate margin capture.
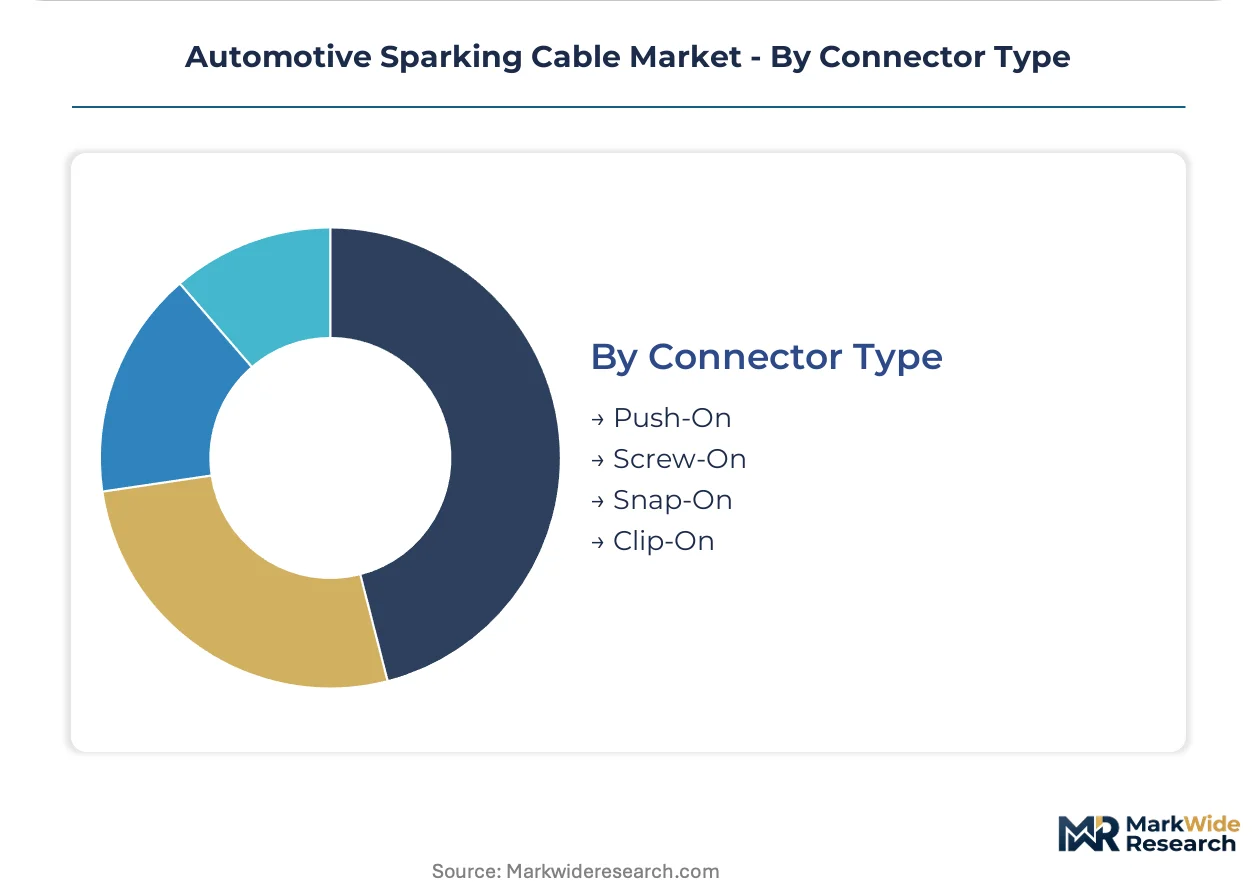
Connector Type:
Mechanical termination geometry shapes assembly automation compatibility and field service reliability.
- Push-On:Friction-fit terminal interfaces enabling rapid assembly and replacement without specialized tooling. High-volume OEM production lines specify push-on designs for coil-on-plug module integration.
- Screw-On:Threaded terminal engagements providing positive mechanical retention in high-vibration commercial vehicle applications. Heavy-duty truck and off-highway equipment specifications favor screw-on security.
- Snap-On:Latching mechanisms combining rapid engagement with positive retention verification. European aftermarket channels specify snap-on designs for technician efficiency in inspection-interval service environments.
- Clip-On:Spring-clip retention systems for legacy distributor and coil applications with standardized terminal posts. Aging vehicle parc maintenance sustains clip-on demand in replacement markets.
Push-on terminals dominate new vehicle specification. Snap-on designs are climbing fastest in professional installation channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese OEM supply chains, while Chinese and Indian markets fragment procurement authority across competing domestic assemblers. This asymmetry shapes margin capture and supplier selection criteria across regional production networks.
China
Domestic automaker electrification programs sustain ignition cable demand despite battery-electric expansion. SAMR conformity assessment procedures for GB standards compel localized testing protocols that favor regional suppliers. Manufacturing concentrates in the Yangtze River Delta, where Zhejiang and Jiangsu province cable assemblers scale production for BYD and Geelong supply contracts.
Germany
KBA type-approval requirements for electromagnetic compatibility accelerate silicone-insulated cable substitution across supplier networks. ECE R10 regulations administered under UN frameworks govern emission limits for type-approved vehicles. Production clusters in Baden-Württemberg and Bavaria host Tier-1 coil-on-plug module producers that internalize precision wire harness assembly.
United States
EPA emissions certification and NHTSA electromagnetic compatibility standards compel OEM specification of suppression-core cables. Advanced driver-assistance sensor proliferation tightens interference thresholds for ignition components. Aftermarket channel density concentrates in Michigan and Ohio, where national service chains centralize procurement authority away from independent distributors.
Japan
Integrated coil-on-plug architectures from Denso and NGK reduce standalone wire demand in domestic OEM supply chains. METI industrial standards shape polymer compound specifications for thermal performance. Manufacturing concentrates in Aichi Prefecture's Chubu region, where captive ceramic technology anchors premium ignition system bundling strategies.
India
Passenger vehicle capacity additions in Tamil Nadu and Gujarat create localized ignition component demand for Maruti Suzuki and Hyundai Motor India. BIS certification requirements favor regional suppliers over imported cable assemblies. Supplier networks in the Chennai-Bengaluru industrial corridor scale silicone compounding capabilities for domestic OEM qualification programs.
Automotive Sparking Cable Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying insulation compounds and conductor materials. The market structures around three tiers: captive Tier-1 module producers, independent cable assemblers, and raw material compounders. Strategic differentiation follows two dominant moves: backward integration into silicone rubber formulation, and geographic expansion into emerging OEM production corridors.
Within the ceramic technology tier, NGK Spark Plug and Denso occupy positions anchored by material science capabilities. Federal-Mogul exemplifies aftermarket channel density strategies across North American repair networks. These three represent distinct competitive archetypes: technology-led system bundling, integrated coil-on-plug architecture, and distribution scale.
| Leading Market Players |
|---|
| NGK Spark Plug |
| Denso |
| Delphi Technologies |
| Sumitomo Electric Industries |
| Federal-Mogul |
| Borg Warner |
| Valeo |
| Taylor Cable Products |
| MSD Spark Wires |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Chinese silicone rubber compounding facilities is tightening raw material availability for cable assemblers while simultaneously elevating input cost pass-through leverage among backward-integrated suppliers in Germany and Japan.
Pricing Analysis
Configured-to-order pricing for OEM-specified coil-on-plug assemblies commands substantial premiums over standard aftermarket spark plug wire assortments. Three-tier pricing structure across premium silicone-insulated, standard EPDM, and economy PVC levels reflects certification grade and thermal performance differentiation. Cost compression in the PVC aftermarket tier is intensifying because of e-commerce platform disintermediation and private-label sourcing from Zhejiang province manufacturers. Fleet maintenance operators exhibit lowest price sensitivity due to bundled labor-service contracts, while independent repair shops in North America face acute margin pressure from consolidated national service chains.
Supply Chain Analysis
Contract manufacturing concentration among Yangtze River Delta cable assemblers and Aichi Prefecture precision wire harness specialists shapes global capacity allocation for ignition components. Geographic supply concentration centers on China, Germany, and Japan, with Mexico emerging as a near-shore alternative for North American OEM qualification. Raw material dependencies draw from copper rod producers, silicone rubber compounders, and ceramic ferrule manufacturers. Single-source vulnerability in high-purity silicone polymer supply creates exposure to KBA electromagnetic compliance-driven demand surges. Distribution runs through Tier-1 module producers for OEM channels and consolidated distributor networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where coil-on-plug module standardization across hybrid architectures is collapsing standalone wire demand into integrated system procurement.
For Market Incumbents: Insulate core margin pools by deepening backward integration into silicone compounding capabilities and securing captive supply agreements with copper rod producers. Battery-electric platform proliferation threatens terminal demand for traditional high-tension categories, necessitating accelerated qualification for 48V and 400V hybrid cable assemblies. Priority investment in SAMR-aligned testing infrastructure protects Chinese OEM supply relationships. For New Entrants and Emerging Players: Pursue aftermarket digitization opportunities in North American and European e-commerce channels where traditional distributor layers retain excessive margin capture. India's Tamil Nadu and Gujarat manufacturing corridors offer the most penetrable geography, with BIS certification requirements favoring regional suppliers over established import competition. Direct-to-repair-shop fulfillment models bypass consolidated national service chain procurement gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compound formulation specialists with captive silicone rubber technology and long-term OEM supply contracts. Five-to-ten-year viability hinges on portfolio pivot toward high-voltage hybrid architectures as pure internal combustion engine volumes contract. Acquisition targets should demonstrate dual certification capability for both legacy ignition and emerging electrified powertrain cable variants. The signal to watch is OEM electrification roadmap acceleration announcements from Japanese and Korean automakers.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Cable Assembly Qualification | 48V and 400V hybrid architectures from BMW and Toyota require redesigned insulation systems with electromagnetic shielding competence. |
| Silicone Rubber Backward Integration | Captive compounding capabilities insulate margin structures from raw material volatility and accelerate KBA compliance timelines. |
| Aftermarket Channel Digitization | E-commerce platforms displace traditional distributor layers in North American repair networks, compressing fulfillment costs. |
| India Manufacturing Footprint Expansion | Tamil Nadu and Gujarat capacity additions align with Maruti Suzuki and Hyundai Motor India localization requirements under BIS standards. |
| Smart Cable Diagnostic Development | Embedded sensor architectures enable predictive maintenance subscriptions for North American fleet operators optimizing replacement intervals. |
Study Parameters
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and silicone rubber compound technical directors converged on the working assumptions shaping demand trajectories. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SAMR conformity assessment filings, and KBA type-approval records. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers to establish volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning propulsion architecture, material insulation grade, installation channel, and regional production cluster. CAGRs derived from fitted growth curves applied to baseline production volumes and electrification penetration assumptions. Industry-specific forecast inputs incorporated OEM powertrain roadmap disclosures and GB standards evolution under SAMR administration.
Macroeconomic conditions sit as an overlay; deviation in copper price volatility, automotive production schedules, or electrification subsidy policies would shift the trajectory. Forecasts reflect documented assumptions regarding hybrid system deployment rates and internal combustion engine phase-out timelines. Quarterly review of OEM electrification announcements, raw material price indices, and regulatory certification timeline changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Automotive Logging Device Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market