
 Automotive Digital Mirror Market | 2026-2036
Automotive Digital Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Mirror Market Analytics
Software-defined feature subscriptions for digital mirror systems is pivoting how tier-one suppliers monetize hardware deployments. Gentex Corporation leverages its long-standing OEM relationships to sustain dominance in interior display integration. Magna International anchors North American production scale through captive camera module manufacturing. Robert Bosch GmbH differentiates via embedded AI processing for real-time blind spot detection algorithms.
Automotive digital mirrors replace conventional reflective glass surfaces with camera-monitor systems that stream live video feeds to interior displays, typically operating at 60 frames per second with latency below 50 milliseconds to prevent motion sickness and ensure safe lane-change decisions. LCD technology currently leads installed volume due to cost efficiency and supply maturity, while OLED panels capture premium margin pools through superior contrast ratios and faster response times in low-light conditions. Camera-based architectures are displacing projection systems as the dominant technology pathway, driven by falling image sensor costs and improved dynamic range performance under adverse weather.
NHTSA in the United States and the United Nations ECE R46 framework in Europe govern camera-monitor system approval, with both bodies expanding permissible field-of-view specifications that directly enlarge addressable product configurations. Japan's Ministry of Land, Infrastructure, Transport and Tourism maintains distinct certification timelines that create staggered market entry patterns across major automotive manufacturing regions. Stakeholders must monitor regulatory divergence on mirror-replacement permissibility versus supplementation mandates, as this distinction determines whether digital systems qualify as standard equipment or remain optional upgrades.
Market Dynamics
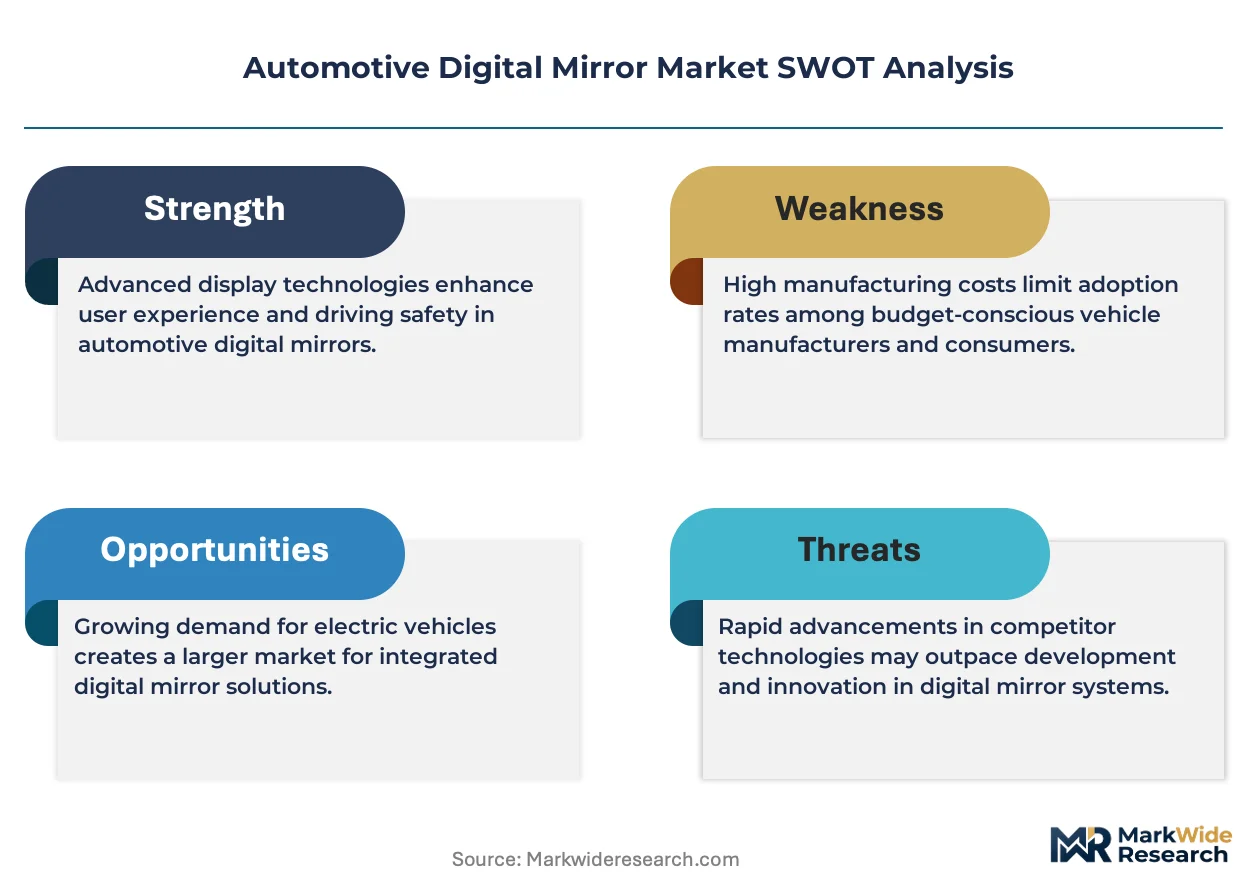
Camera-based mirror systems are compressing the technology transition timeline as image sensor costs fall below projection-based alternatives, forcing tier-one suppliers to reconfigure manufacturing footprints around solid-state camera module assembly.
Growth Catalysts
- NHTSA-ECE Harmonization:The United States and European regulatory frameworks for camera-monitor systems are converging on field-of-view specifications, eliminating dual-certification burdens that previously delayed product launches across Atlantic markets.
- Electric Vehicle Architecture:Battery-electric platforms from Mercedes-Benz, BMW, and Audi integrate digital mirrors as standard equipment to maximize aerodynamic efficiency and extend range through reduced drag coefficients.
- Image Sensor Cost Curve:CMOS sensor pricing has fallen below critical thresholds for automotive-grade applications, enabling camera-based systems to undercut projection technologies on bill-of-materials.
Market Restraints
- LCD Panel Supply Concentration:Display manufacturing for automotive applications concentrates in East Asian foundries, creating single-source vulnerability for tier-one integrators outside that geography.
- Adverse Weather Performance:Camera lens soiling and water droplet interference degrade image clarity below safety thresholds in heavy precipitation, requiring redundant sensor arrays that inflate system cost.
- Japan's Distinct Certification Timeline:MLIT approval processes operate on staggered schedules versus NHTSA and ECE R46, fragmenting product launch synchronization across major automotive manufacturing regions.
Strategic Opportunities
- Software-Defined Subscriptions:Feature-as-a-service monetization for blind-spot detection algorithms and parking assistance overlays creates recurring revenue streams atop hardware deployments.
- OLED Premium Tier Penetration:Superior contrast ratios in low-light conditions position organic light-emitting diode panels to capture margin pools in flagship sedan and luxury electric vehicle segments.
- Aftermarket Channel Development:Independent service networks and direct-to-consumer installation partnerships offer pathways to vehicle parc retrofit demand outside OEM-controlled distribution.
Industry Challenges
- Embedded AI Talent Scarcity:Real-time image processing for object detection and latency optimization requires specialized machine learning engineers whose supply constrains algorithm development velocity.
- Legacy Mirror Supply Chain Reconfiguration:Glass mirror manufacturers face stranded asset risk as OEMs shift procurement toward camera module and display panel suppliers, forcing supplier base rationalization.
- 50-Millisecond Latency Compliance:Motion sickness prevention standards mandate sub-50ms video processing pipelines that stress thermal management and signal routing in compact mirror housings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Mirror Market |
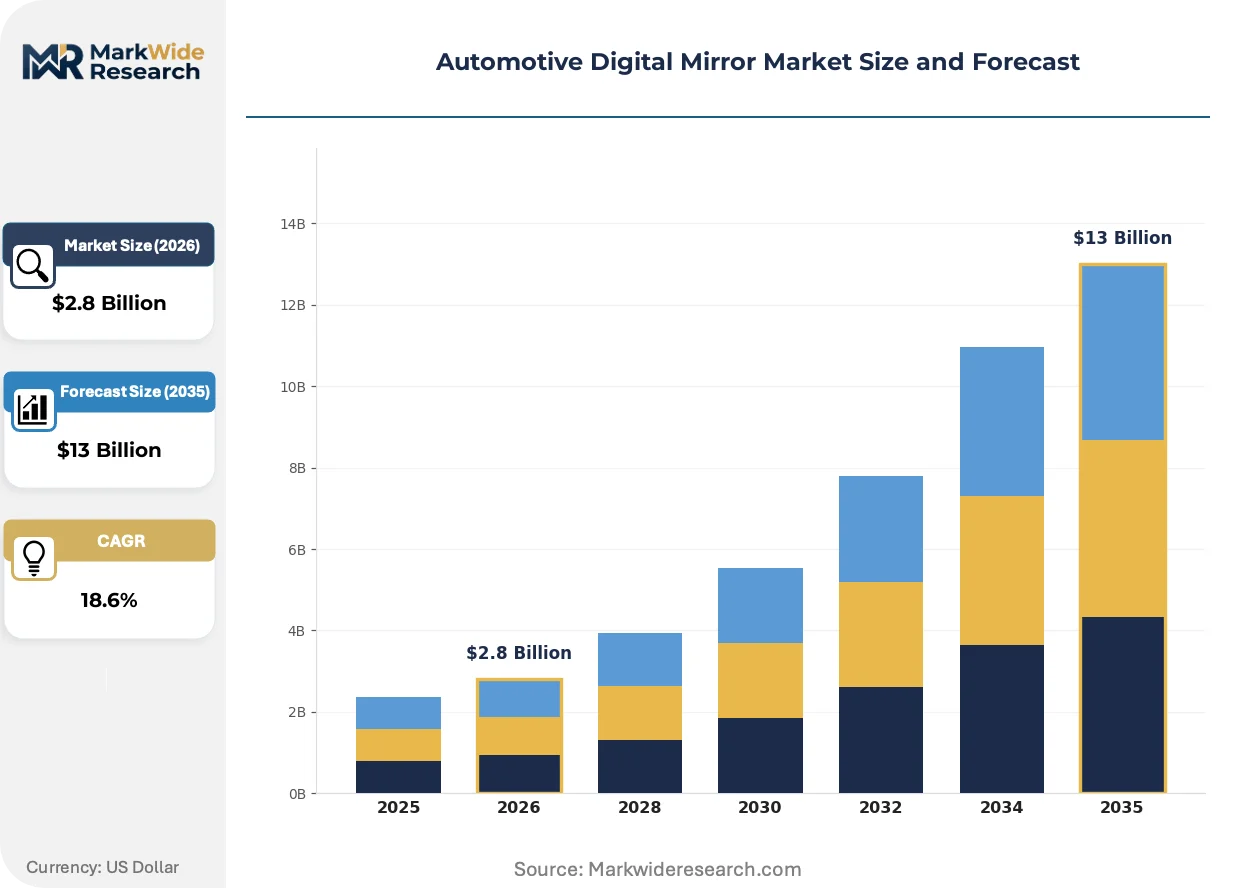
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rearview Mirrors, Side Mirrors, Interior Displays, Digital Interfaces Technology: LCD, OLED, Camera-Based, Projection End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Feature: Night Vision, Blind Spot Detection, Enhanced GPS, Touchscreen |
| Companies Covered | Gentex Corporation, Ficosa International SA, Magna International Inc, Denso Corp, Robert Bosch GmbH, Continental AG, Hyundai Mobis, Panasonic Corporation, Samvardhana Motherson Reflectec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Mirror Market Evolving Landscape
Three distinct vectors are compressing product development cycles and redrawing competitive boundaries: solid-state imaging overtaking projection architectures, regulatory harmonization accelerating multi-region certification, and procurement models shifting from component supply toward integrated system responsibility.
Camera-based architectures are overtaking projection systems as the dominant technology pathway in automotive digital mirrors. Solid-state CMOS sensors deliver superior dynamic range under variable lighting conditions while eliminating moving parts that degrade in vibration-intensive automotive environments. Premium passenger vehicle OEMs in Germany and Japan have standardized on camera modules for new electric vehicle platforms. This technology transition is compressing the addressable market for projection-based alternatives to niche commercial vehicle applications.
REACH and RoHS compliance frameworks in Europe are tightening material restrictions on display panel manufacturing, forcing suppliers to reformulate backlighting phosphors and solder compositions. The industrial consequence is accelerated qualification timelines for new display technologies seeking European market entry. OLED panel suppliers are responding fastest, having preemptively eliminated restricted substances from their vapor deposition processes to maintain access to German OEM supply chains.
Fleet procurement departments are consolidating vendor relationships from discrete component sourcing toward single-source system integration contracts. Tier-one suppliers now assume full liability for camera, display, and processing module interoperability rather than OEMs managing multi-vendor integration. This consolidation is most visible in North American commercial vehicle segments, where large fleet operators demand unified warranty coverage across the complete mirror replacement system.
Automotive Digital Mirror Market Segmentation
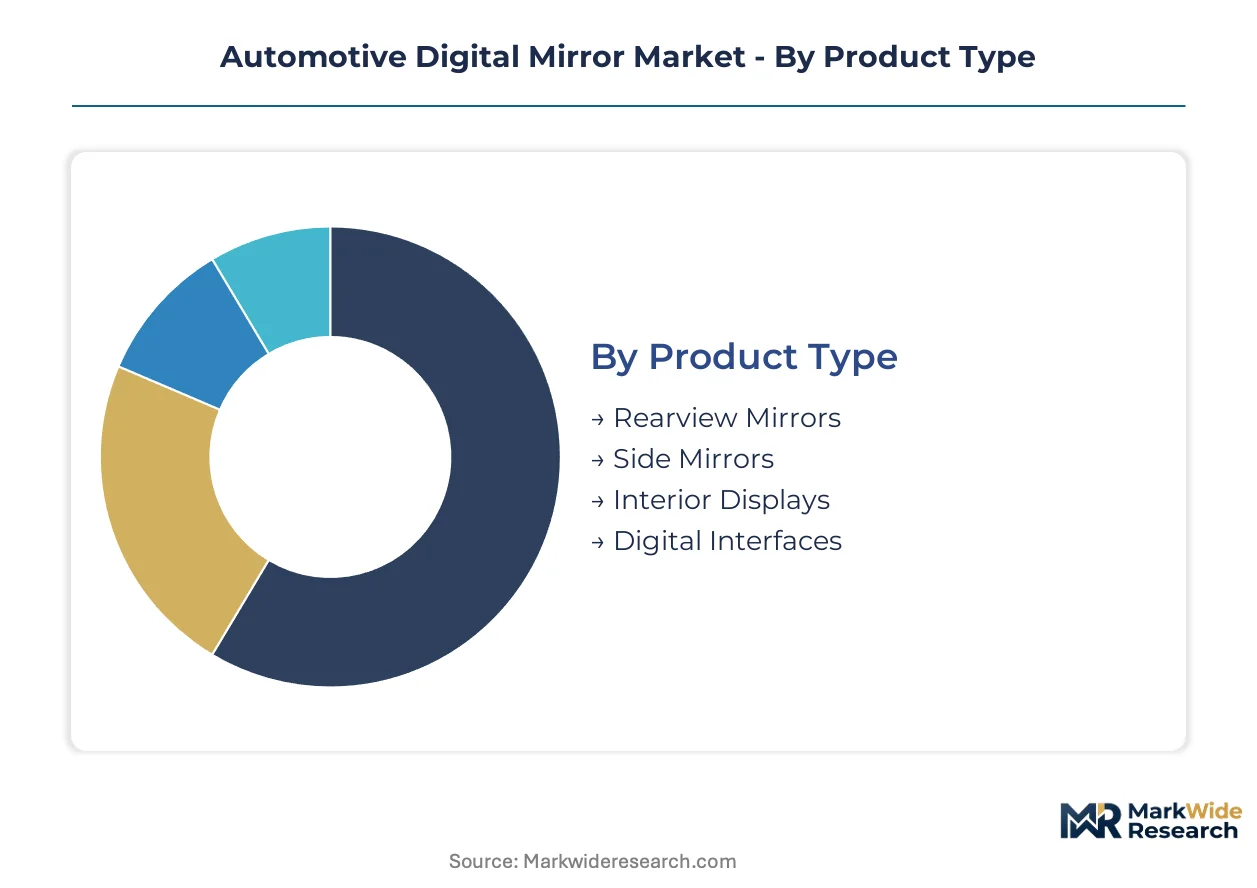
Segmentation in automotive digital mirrors reveals how procurement patterns split between standardized fleet deployments and bespoke premium configurations. Understanding these divisions exposes where margin pools concentrate and which technology pathways command pricing power across passenger and commercial vehicle applications.
Product Type:
Standardization dominates mass-market exterior mirror replacement, while interior display configurations fragment across cabin architectures and OEM design languages.
- Rearview Mirrors:Camera-monitor systems replace traditional reflective glass with interior-mounted displays, typically integrating with windshield-mounted CMOS sensors. Mercedes-Benz and BMW deploy these as standard equipment across electric sedans manufactured in Germany, driven by aerodynamic drag reduction targets that extend battery range.
- Side Mirrors:Exterior camera pods eliminate protruding mirror housings entirely, streaming feeds to door-mounted or A-pillar displays. Adoption concentrates in Japan's premium manufacturing corridor where MLIT certification timelines have aligned with NHTSA-ECE harmonization, enabling synchronized product launches.
- Interior Displays:Centralized screen configurations consolidate multiple camera feeds into unified dashboard interfaces.
- Digital Interfaces:Software layers enabling gesture control and augmented reality overlays atop base video feeds.
Leading the category by volume: Rearview Mirrors. Growing fastest: Side Mirrors.
Technology:
Cost tiers separate mature LCD supply from emerging OLED premium positioning, while underlying imaging architectures determine system latency compliance.
- LCD:Thin-film transistor liquid crystal displays dominate installed volume through established automotive qualification and East Asian foundry scale. Tier-one suppliers outside that geography face single-source vulnerability for panel procurement, compressing margin capture on standard equipment programs.
- OLED:Organic light-emitting diode panels deliver superior contrast ratios below 5 lux ambient lighting, eliminating backlight bleed that degrades night driving safety. German OEMs specify OLED for flagship sedan segments where display performance justifies material cost premiums.
- Camera-Based:Solid-state CMOS architectures displace projection systems through falling sensor costs and vibration durability.
- Projection:Head-up display alternatives limited to niche commercial vehicle applications requiring windshield-integrated imagery.
Volume leadership: LCD. Steepest expansion trajectory: Camera-Based.
End User:
Procurement concentration varies sharply between captive OEM supply chains and fragmented aftermarket retrofit demand.
- OEMs:Original equipment manufacturers consolidate vendor relationships toward single-source system integration contracts, transferring full interoperability liability from multi-vendor management to tier-one suppliers. This shift is most visible in North American commercial vehicle segments where fleet operators demand unified warranty coverage.
- Aftermarket Providers:Independent service networks and direct-to-consumer installation partnerships address vehicle parc retrofit demand outside OEM-controlled distribution channels. Regulatory divergence on mirror-replacement permissibility versus supplementation mandates determines addressable market size in each jurisdiction.
- Fleet Operators:Large-scale procurement departments prioritize total cost of ownership over unit acquisition price.
- Dealerships:Authorized retail channels handle warranty-integrated upgrades and trade-in program conversions.
Procurement volume concentrates with OEMs. Aftermarket Providers are expanding most quickly.
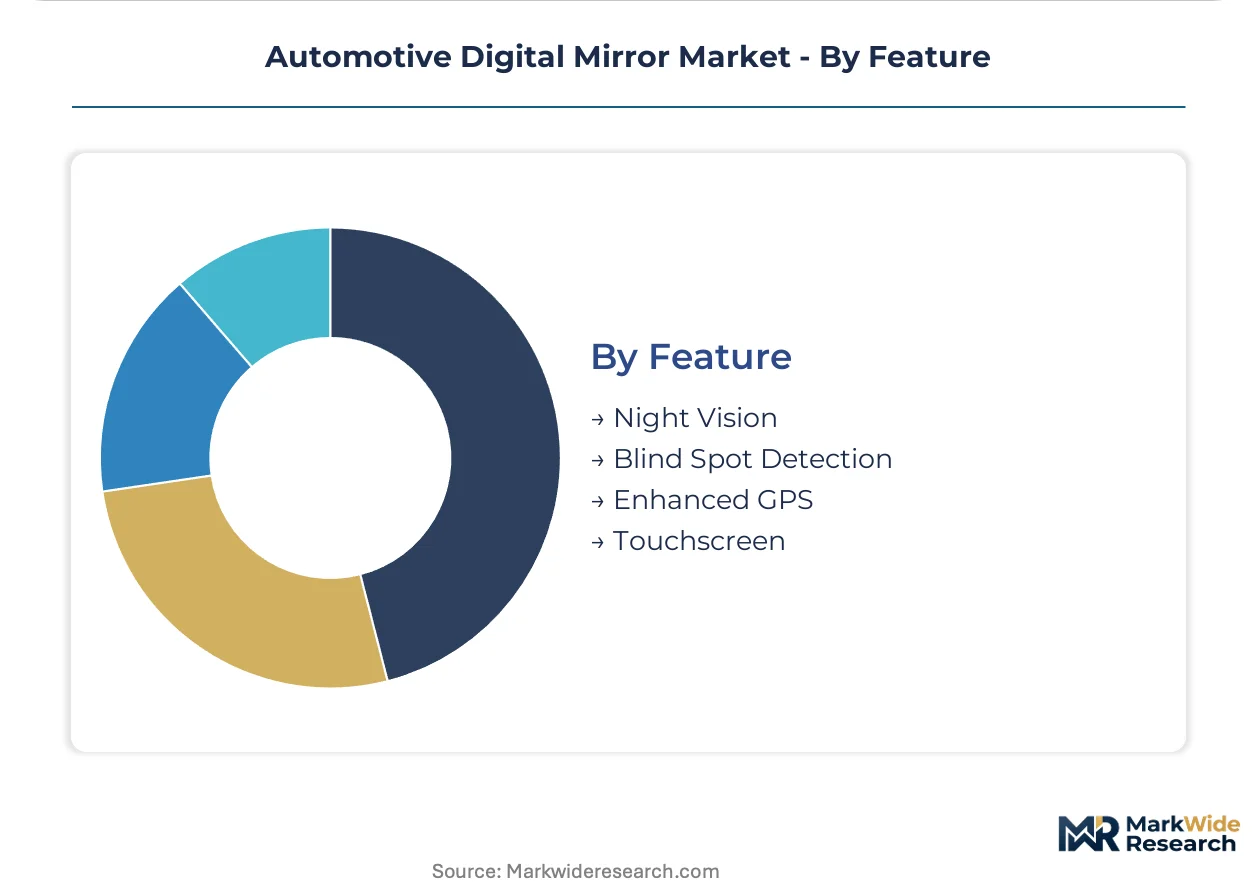
Feature:
Software-defined functionality creates tiered monetization pathways atop common hardware platforms.
- Night Vision:Infrared-augmented imaging extends driver visibility below human photopic thresholds, requiring sensor fusion with thermal cameras or low-light optimized CMOS arrays. Demand clusters in premium segments where safety feature differentiation supports transaction pricing.
- Blind Spot Detection:Embedded AI processing for real-time object classification and collision trajectory prediction. Robert Bosch GmbH differentiates through proprietary algorithm development, though talent scarcity for machine learning engineers constrains deployment velocity across the supplier base.
- Enhanced GPS:Navigation overlays integrating real-time traffic and hazard warnings into mirror display fields.
- Touchscreen:Haptic input surfaces enabling direct manipulation of camera angles and display settings.
Adoption leadership: Blind Spot Detection. Feature-as-a-service revenue growth: Night Vision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, Japan, and the United States where premium OEMs anchor manufacturing, while consumption patterns diverge based on regulatory approval timelines and fleet electrification rates.
United States
NHTSA field-of-view specification expansions are accelerating camera-monitor system deployment across electric vehicle platforms. The regulator's harmonization with ECE R46 frameworks eliminates dual-certification burdens for suppliers. Detroit's automotive manufacturing corridor sees tier-one integrators reconfiguring assembly lines around solid-state camera module production.
Germany
Mercedes-Benz, BMW, and Audi specify digital mirrors as standard equipment across flagship electric sedans to maximize aerodynamic efficiency. REACH and RoHS compliance frameworks tighten material restrictions on display panel manufacturing. Stuttgart, Munich, and Ingolstadt form a premium manufacturing corridor where OLED panel qualification timelines accelerate.
Japan
MLIT certification timelines for camera-monitor systems have aligned with NHTSA-ECE harmonization, enabling synchronized product launches. Toyota and Honda integrate side-view camera pods to eliminate protruding mirror housings on battery-electric platforms. Nagoya and Tokyo metropolitan manufacturing clusters concentrate CMOS sensor assembly and display integration capacity.
South Korea
Hyundai Mobis and domestic OEMs are expanding camera-based mirror adoption following regulatory convergence with European standards. The country's national automotive regulator maintains distinct homologation procedures that create staggered entry patterns versus Atlantic markets. Gyeonggi-do and Ulsan industrial zones host captive camera module manufacturing for domestic and export programs.
China
Domestic OEMs including BYD and NIO are piloting digital mirror systems on premium electric vehicle lineups despite stricter certification timelines. GB standards for camera-monitor systems are evolving toward convergence with UN ECE frameworks. Yangtze River Delta manufacturing clusters concentrate LCD panel supply for cost-sensitive mass-market applications.
Automotive Digital Mirror Market Competitive Landscape
Top-tier vendors anchor integrated system supply, while specialized component suppliers occupy niche positions in sensor and display manufacturing. The vendor base spans three strategic tiers: full-system integrators with OEM direct relationships, camera module specialists with captive semiconductor partnerships, and display panel foundries with automotive qualification. Consolidation pressures favor tier-one suppliers assuming full interoperability liability. Competitive moves center on strategic partnerships for AI algorithm licensing and capacity expansion in East Asian display manufacturing.
Within the full-system integration tier, Gentex Corporation and Magna International occupy positions representing North American production scale and long-standing OEM relationships. Robert Bosch GmbH anchors European embedded processing capabilities. These three exemplify the shift toward single-source contracts where suppliers assume unified warranty coverage across camera, display, and processing modules.
| Leading Market Players |
|---|
| Gentex Corporation |
| Ficosa International SA |
| Magna International Inc |
| Denso Corp |
| Robert Bosch GmbH |
| Continental AG |
| Hyundai Mobis |
| Panasonic Corporation |
| Samvardhana Motherson Reflectec |
| Others |
Value Network & Pricing Analysis
Captive camera module manufacturing anchors tier-one supplier positioning in North America while outsourcing display procurement to East Asian foundries compresses margin capture. This integration asymmetry concentrates pricing power with semiconductor suppliers and fragments negotiating leverage for system integrators outside Korea, Japan, and Taiwan.
Pricing Analysis
Margin tightening in LCD-equipped systems reflects East Asian foundry concentration and single-source panel procurement. Three-tier pricing structure across premium OLED, standard LCD, and economy projection configurations separates German flagship programs from mass-market deployments. Cost-down pressure accelerates as fleet operators consolidate vendor relationships and demand unified warranty coverage. Aftermarket providers exhibit highest price sensitivity due to regulatory uncertainty on mirror-replacement permissibility.
Supply Chain Analysis
Single-source vulnerability sits with East Asian display manufacturing, where automotive-qualified LCD and OLED panels concentrate in Korean and Taiwanese foundries. CMOS image sensors draw from Japanese and Korean semiconductor houses, while camera module assembly localizes in Germany, Japan, and Michigan. Tariff exposure on display imports threatens margin stability for North American integrators lacking captive panel supply. Distribution runs through OEM direct contracts and tier-one system integrators, with aftermarket channels fragmenting across independent service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive digital mirror procurement is consolidating around full-system integrators as OEMs transfer interoperability liability, forcing component specialists to exit or sell. Single-source warranty demands from fleet operators accelerate this shakeout.
For Market Incumbents: Lock in OLED panel allocation through multi-year offtake agreements with Korean suppliers before premium sedan programs expand. Deepen embedded AI capabilities through captive hiring of machine learning engineers, as algorithm development velocity constrains blind-spot detection deployment. Defend against tier-two camera module specialists by securing MLIT-NHTSA-ECE triple certification ahead of regulatory harmonization completion.
For New Entrants and Emerging Players: Direct-to-consumer installation partnerships offer the most penetrable route into aftermarket retrofit demand outside OEM-controlled channels. Target commercial vehicle fleet operators in North America with unified warranty propositions that incumbent glass mirror manufacturers cannot match. White-space exists in software-defined subscription overlays for parking assistance and night vision features atop third-party hardware.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by tier-one system integrators seeking embedded AI capabilities or captive camera module manufacturing. Long-term viability favors vertically integrated suppliers with in-house semiconductor partnerships and triple-regulatory certification. Watch for NHTSA-ECE field-of-view specification expansion as the inflection signal accelerating multi-region program awards.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables recurring revenue from blind-spot detection and parking assistance algorithm subscriptions. |
| Geographic Manufacturing Footprint | Localizes camera module assembly in Germany, Japan, and Michigan to satisfy OEM proximity requirements. |
| Platform Standardization | Reduces engineering redundancy across Mercedes-Benz, BMW, and Audi electric vehicle lineups. |
| Strategic Partnership | Secures OLED panel allocation from Korean foundries for premium sedan display specifications. |
| Acquisition of Specialist Firm | Captures embedded AI talent for real-time object detection and sub-50ms latency compliance. |
Research Methodology
Multi-period observation of NHTSA-ECE regulatory harmonization timelines, CMOS sensor cost curves, and OEM platform deployment schedules anchored the trend analysis, supplemented by interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed automotive suppliers, and UN ECE R46 amendment tracking. Bottom-up bill-of-materials modeling and top-down OEM program sizing were triangulated against disclosed supplier contract values.
Segment-weighting across vehicle class, propulsion architecture, content per vehicle, and regional production cluster informed the analytical framework. CAGRs were derived from regression analysis of historical adoption curves and OEM electrification commitments across the projection horizon. Industry-specific forecast inputs included battery-electric platform launch timelines and MLIT certification schedule convergence assumptions.
The model holds under continued NHTSA-ECE field-of-view expansion and stable East Asian display supply; deviation in tariff imposition or semiconductor export controls would shift adoption trajectories. Forecasts reflect documented assumptions on regulatory harmonization pace and sensor cost decline rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Germany Automotive Camera Market