
 Automotive Voice Recognition System Market | 2026-2036
Automotive Voice Recognition System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Voice Recognition System Market Analysis
Aftermarket service revenue is reconfiguring toward embedded software licensing and over-the-air feature activation. Cerence Inc dominates automotive-specific natural language platforms through OEM direct integration. Alphabet Inc leverages its cloud infrastructure to supply voice AI backends across multiple vehicle brands. Harman International Industries anchors premium cabin electronics, bundling acoustic hardware with voice processing software.
Automotive voice recognition systems capture spoken commands through microphone arrays, convert acoustic signals via digital signal processors, and execute vehicle functions using natural language understanding engines with latency thresholds below 200 milliseconds. Their primary purpose is to minimize manual interface interaction and reduce driver distraction during vehicle operation. Embedded Systems command the largest installed base due to OEM pre-installation requirements and offline functionality mandates. Cloud-Based Services represent the fastest-expanding segment as 5G connectivity enables real-time language model updates and expanded command vocabularies. Machine Learning underpins accuracy improvements in noisy cabin environments, shifting competitive advantage toward firms with proprietary training datasets.
NHTSA guidelines, Euro NCAP assessment protocols, and China's MIIT connected-vehicle standards collectively mandate reduced manual device interaction, directly expanding voice interface requirements across regulatory jurisdictions. ECE R79 steering equipment regulations and GDPR data processing constraints further shape microphone data handling and biometric voiceprint storage architectures. Stakeholders must evaluate whether to build captive speech recognition stacks or depend on third-party platform licensing as regulatory fragmentation around data sovereignty intensifies.
Market Dynamics
Cloud-based natural language processing is virtualizing cockpit electronics architectures, decoupling voice AI from fixed hardware and enabling continuous feature deployment without physical redesign cycles. This shift compresses OEM development timelines while expanding aftermarket monetization pathways.
Growth Catalysts
- 5G Vehicle Connectivity:Real-time cloud access eliminates embedded storage constraints for multilingual acoustic models. German and Chinese OEMs now mandate cellular-enabled voice stacks.
- Euro NCAP Safety Protocols:Hands-free interface requirements in assessment criteria force voice control adoption across vehicle classes. Compliance directly shapes cockpit design specifications.
- Edge AI Chipsets:Dedicated neural processing units enable hybrid architectures combining offline command recognition with cloud-based complex queries. This dual-mode operation satisfies latency and privacy requirements simultaneously.
Market Restraints
- GDPR Voiceprint Storage:Biometric data classification creates architectural constraints for persistent speaker identification. European deployments require explicit consent frameworks and local data residency.
- Microphone Array Cost Concentration:Precision acoustic hardware supply clusters in East Asian manufacturing zones. Single-source dependency for beamforming components exposes OEMs to logistics volatility.
- Accent Recognition Limitations:Training data gaps for regional dialects degrade command accuracy in emerging markets. This technical boundary restricts voice interface utility outside standardized language domains.
Strategic Opportunities
- Commercial Vehicle Integration:Fleet operators in the United States demand voice-enabled logistics coordination without driver distraction. This application segment remains underpenetrated relative to passenger vehicles.
- Over-the-Air Feature Activation:Software licensing models allow tiered capability unlocking post-sale. OEMs capture recurring revenue from premium voice functions without hardware differentiation.
- MIIT Connected-Vehicle Standards:China's mandate for intelligent cockpit interfaces creates regulatory tailwind for domestic and foreign platform providers. Compliance certification opens access to the largest vehicle production base.
Industry Challenges
- Acoustic Engineer Scarcity:Cabin noise cancellation expertise concentrates in automotive audio specialists. OEMs struggle to recruit talent capable of optimizing microphone placement across vehicle platforms.
- Legacy Infotainment Integration:Decade-old head unit architectures lack processing headroom for modern NLP engines. Retrofit complexity delays voice feature deployment in mid-cycle vehicle refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Voice Recognition System Market |
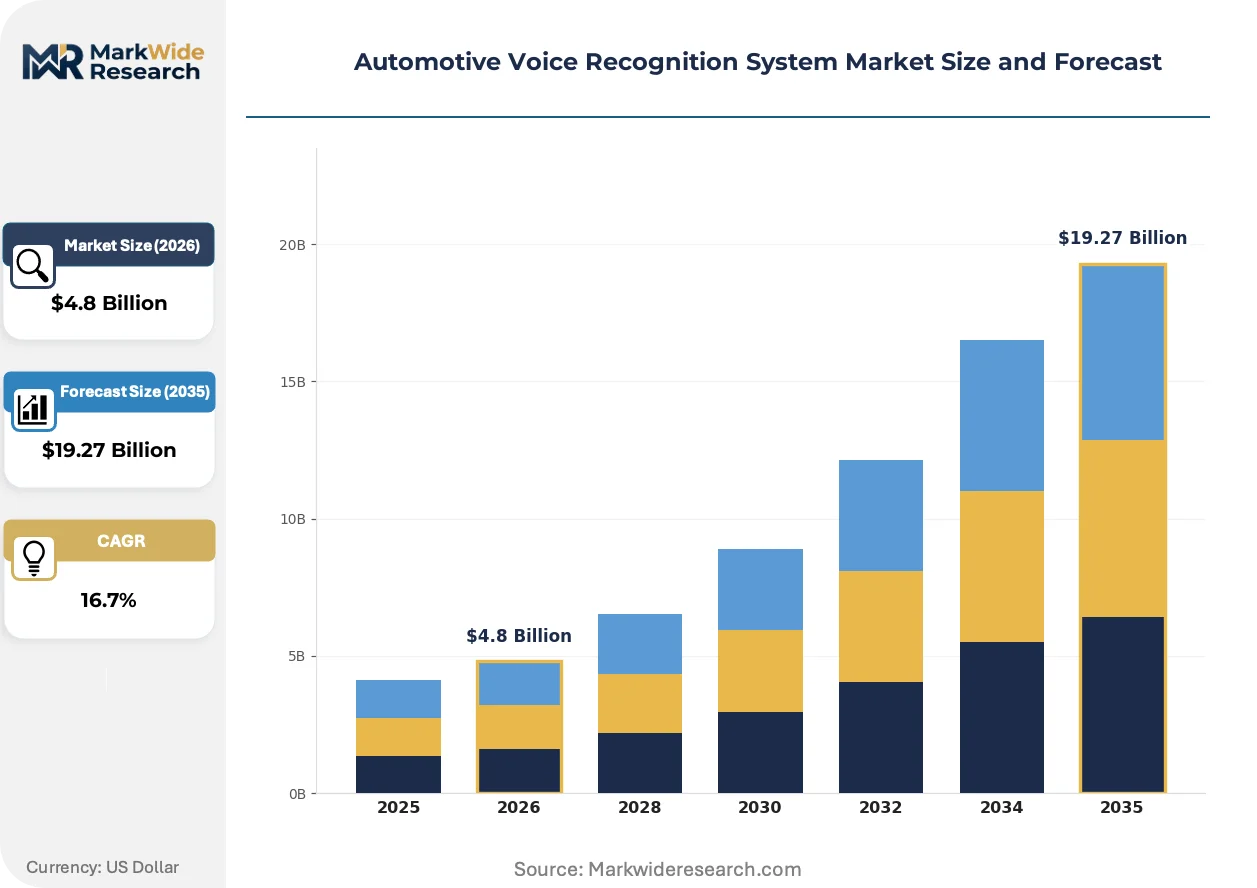
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Aftermarket Solutions, Software Applications, Cloud-Based Services Technology: Natural Language Processing, Machine Learning, Acoustic Models, Speech Synthesis End User: Passenger Vehicles, Commercial Vehicles, Fleet Operators, Rental Services Application: Navigation, Voice Commands, Infotainment, Driver Assistance |
| Companies Covered | Harman International Industries, Alphabet Inc, Nuance Communications Inc, Amazon.com Inc, Apple Inc, Cerence Inc, Robert Bosch GmbH, Continental AG, SoundHound AI Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Voice Recognition System Market Emerging Trajectories
Automotive voice systems are migrating from command-and-control interfaces toward conversational agents capable of contextual multi-turn dialogue. This evolution demands fundamental restructuring of cockpit electronics and software stack architecture.
Edge-cloud hybrid processing is virtualizing voice recognition deployment models. Tier-1 suppliers embed lightweight acoustic models for offline wake-word detection while streaming complex natural language queries to centralized infrastructure. German luxury OEMs now specify this architecture as standard. The technology is virtualizing traditional boundaries between embedded and connected vehicle electronics.
NHTSA distracted-driving guidelines are tightening manual interface restrictions across vehicle classes. The regulation mandates eyes-on-road compliance metrics that effectively prohibit touchscreen-dependent workflows. Premium passenger vehicle segments in the United States are responding with expanded voice-first cockpit designs. Compliance-driven specification changes now precede consumer preference in feature prioritization.
Fleet procurement patterns are fragmenting voice platform sourcing decisions. Large commercial operators in North America now specify acoustic hardware separately from NLP software, unbundling traditional tier-1 integrated offerings. This disintermediation pressures established suppliers to defend margin through software licensing rather than bundled electronics. The shift is most visible in heavy-duty truck segments where total cost of ownership calculations dominate acquisition criteria.
Automotive Voice Recognition System Market Segmentation
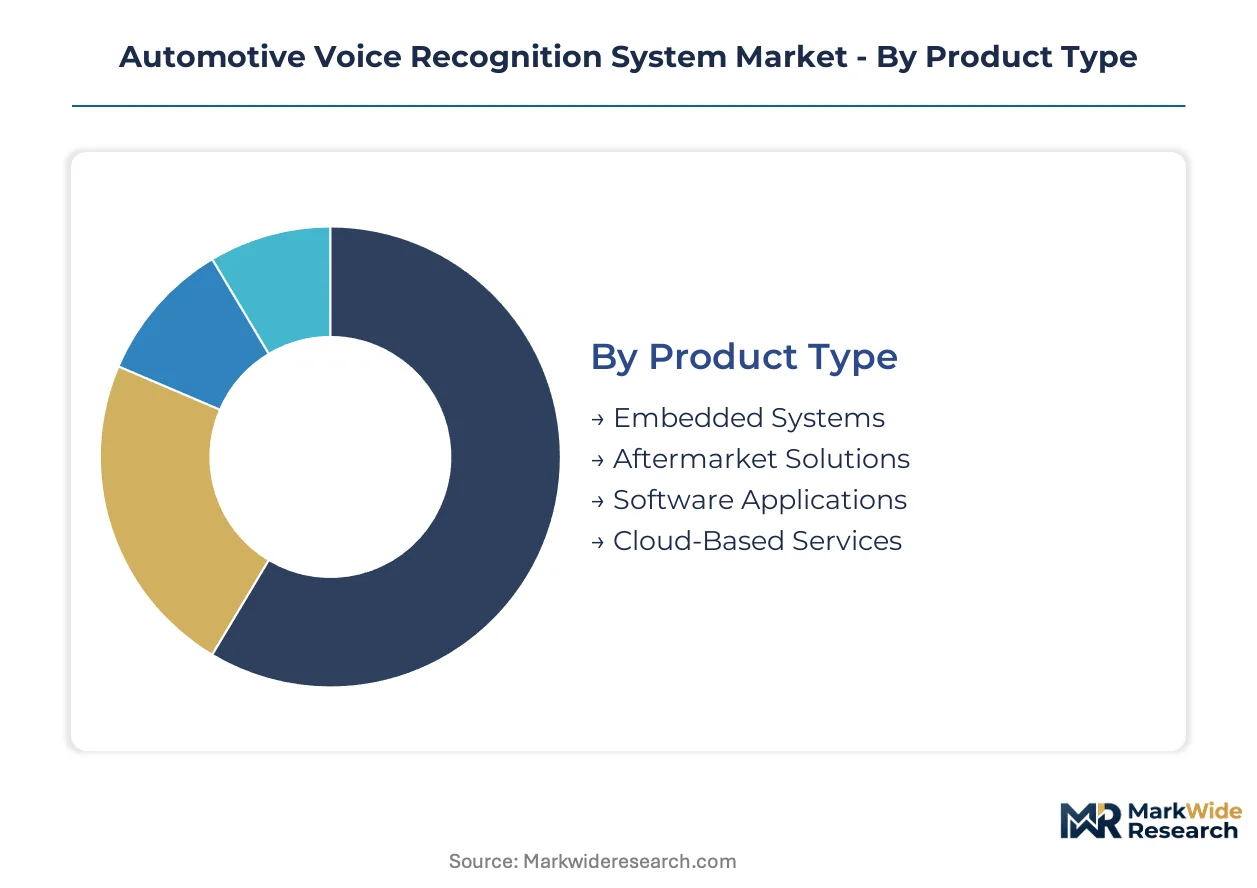
Voice recognition deployment patterns vary sharply by integration depth and update frequency. After-sales service intensity differs dramatically between fixed embedded installations and continuously refreshed cloud architectures. These structural variations determine margin durability and customer lifetime value across supplier portfolios.
Product Type:
After-sales service intensity peaks where software update cycles outpace hardware replacement schedules. Cloud-enabled products demand perpetual platform maintenance, while embedded systems monetize through extended warranty programs.
- Embedded Systems:Pre-installed voice processing hardware with offline acoustic models and fixed-function DSP architectures. OEMs in Germany and the United States specify these for baseline trim levels where connectivity costs must be minimized. NHTSA offline functionality mandates reinforce this segment's installed base dominance.
- Cloud-Based Services:Streaming natural language processing with real-time model updates and expanded multilingual vocabularies. Chinese OEMs mandate cellular-enabled voice stacks under MIIT connected-vehicle standards. 5G vehicle connectivity eliminates storage constraints for complex acoustic models.
- Aftermarket Solutions:Retrofit microphone arrays and head unit adapters for legacy vehicle platforms.
- Software Applications:Licensed NLP engines and voice AI middleware sold separately from acoustic hardware.
Embedded Systems holds the largest share; momentum sits with Cloud-Based Services.
Technology:
Cost tier stratification separates foundational acoustic processing from premium contextual understanding capabilities. Entry-level implementations license standardized acoustic models, while premium tiers demand proprietary training datasets.
- Natural Language Processing:Semantic parsing engines converting transcribed speech into executable vehicle commands with intent classification. Passenger vehicle OEMs in Germany specify conversational multi-turn dialogue capabilities as standard equipment. Euro NCAP hands-free interface requirements accelerate NLP specification across vehicle classes.
- Machine Learning:Neural network architectures optimizing recognition accuracy in noisy cabin environments through continuous model refinement. Fleet operators in the United States deploy ML-enabled voice systems for logistics coordination without driver distraction. Training data gaps for regional dialects constrain deployment in emerging markets.
- Acoustic Models:Statistical representations of phoneme patterns enabling speech-to-text conversion.
- Speech Synthesis:Text-to-speech engines generating naturalistic audio responses for driver feedback.
Natural Language Processing dominates current revenue; Machine Learning is climbing the fastest as accuracy requirements intensify.
End User:
Volume concentration varies by procurement sophistication and total cost of ownership sensitivity. Fleet operators unbundle hardware from software, while passenger vehicle OEMs prefer integrated tier-1 offerings.
- Passenger Vehicles:Private consumer automobiles with voice-controlled cockpit integration across premium and mass-market segments. German luxury OEMs specify edge-cloud hybrid architectures as standard. NHTSA distracted-driving guidelines mandate eyes-on-road compliance metrics.
- Commercial Vehicles:Heavy-duty trucks and delivery vans requiring voice-enabled logistics coordination. Fleet procurement patterns in North America now specify acoustic hardware separately from NLP software. Total cost of ownership calculations dominate acquisition criteria in this segment.
- Fleet Operators:Multi-vehicle commercial purchasers with centralized platform management requirements.
- Rental Services:Short-term vehicle providers prioritizing standardized interface familiarity across mixed fleets.
Passenger Vehicles commands current volume; Commercial Vehicles shows the steepest expansion trajectory as fleet digitization accelerates.
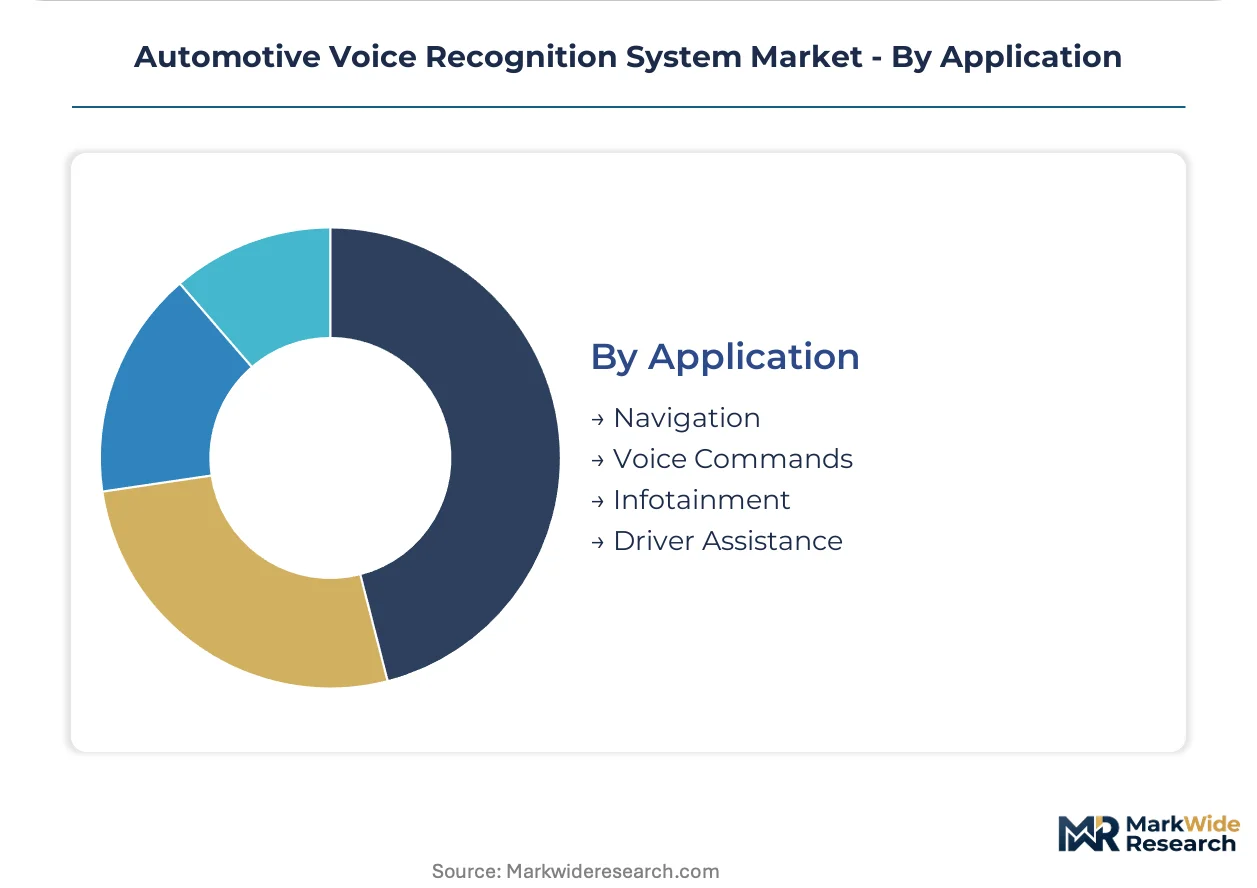
Application:
Customer type differentiation separates safety-critical functions from convenience features. Driver assistance applications face stricter latency requirements than infotainment systems.
- Navigation:Destination entry and route modification through spoken address input and POI search. Voice-first cockpit designs in United States premium segments prioritize navigation commands. NHTSA manual interface restrictions effectively prohibit touchscreen-dependent address entry.
- Driver Assistance:Voice activation of advanced driver-assistance systems and emergency protocols. Euro NCAP assessment protocols incorporate hands-free interface requirements in safety scoring. Latency thresholds below 200 milliseconds are mandatory for this application.
- Voice Commands:Climate control, window operation, and seat adjustment through spoken instructions.
- Infotainment:Media selection, phone connectivity, and third-party app control via speech.
Navigation retains the largest deployment base; Driver Assistance is gaining share fastest as safety regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in the United States exhibit the lowest price elasticity, absorbing premium voice AI licensing costs for safety compliance. Chinese OEM procurement shows intermediate sensitivity, balancing MIIT mandates with margin pressure. European buyers face the highest elasticity due to GDPR compliance overhead and fragmented language requirements.
United States
NHTSA distracted-driving guidelines mandate eyes-on-road compliance metrics that prohibit touchscreen-dependent workflows. Fleet operators in Texas and Michigan now specify acoustic hardware separately from NLP software. Detroit anchors premium passenger vehicle voice-first cockpit design, with German luxury OEMs mandating edge-cloud hybrid architectures for US-bound production.
Germany
Euro NCAP assessment protocols incorporate hands-free interface requirements that force voice control adoption across vehicle classes. KBA type-approval processes scrutinize biometric data handling for persistent speaker identification systems. Stuttgart and Munich cluster automotive-specific natural language platform development, with OEMs specifying conversational multi-turn dialogue as standard equipment.
China
MIIT connected-vehicle standards mandate intelligent cockpit interfaces that accelerate cellular-enabled voice stack deployment. BYD and NIO in Shenzhen and Shanghai specify 5G-native architectures to eliminate embedded storage constraints for multilingual acoustic models. Domestic platform providers capture compliance certification advantages in the largest vehicle production base.
Japan
METI carbon neutrality roadmaps pressure automotive electronics suppliers to optimize processing efficiency in voice recognition chipsets. Toyota and Honda procurement in Nagoya and Tokyo favors hybrid edge-cloud architectures that minimize data transmission energy intensity. JIS standards for in-vehicle information systems shape microphone array placement specifications.
South Korea
MFDS data protection guidelines intersect with automotive voiceprint storage requirements for biometric driver identification systems. Hyundai and Kia in Seoul and Ulsan mandate sub-200-millisecond latency thresholds for driver assistance voice activation. Domestic semiconductor foundries supply dedicated neural processing units for cabin noise cancellation.
Automotive Voice Recognition System Market Vendor Landscape
Capability concentration sits with automotive-specific natural language specialists; scale advantage sits with cloud infrastructure operators with cross-industry AI deployments. The vendor base stratifies across three tiers: integrated tier-1 electronics suppliers bundling acoustic hardware with software, pure-play voice AI platform licensors, and hyperscale cloud providers supplying backend infrastructure. Dominant competitive moves include unbundling hardware from software procurement and over-the-air feature activation licensing.
Within the automotive-specialist tier, Cerence Inc and SoundHound AI Inc exemplify platform-centric positioning that decouples NLP engines from fixed hardware. Alphabet Inc anchors the cloud-native vector, supplying voice AI backends across multiple vehicle brands through existing data center infrastructure. Harman International Industries occupies the integrated electronics position, bundling precision microphone arrays with voice processing software for premium cabin deployments.
| Leading Market Players |
|---|
| Harman International Industries |
| Alphabet Inc |
| Nuance Communications Inc |
| Amazon.com Inc |
| Apple Inc |
| Cerence Inc |
| Robert Bosch GmbH |
| Continental AG |
| SoundHound AI Inc |
| Others |
Supply Flow & Price Mechanics
Shenzhen's microphone array manufacturing cluster determines downstream pricing power for precision acoustic hardware, with beamforming component shortages in East Asian zones forcing OEMs into long-term offtake commitments that compress margin flexibility for voice recognition system integrators.
Pricing Analysis
Long-term offtake contracts dominate procurement between Tier 1 electronics suppliers and German luxury OEMs, locking in volume commitments for neural processing units and microphone arrays. Price differentiation hinges on certification grade under ECE R79 steering equipment regulations and vertical integration depth in acoustic hardware production. Cost compression in standard-tier embedded systems is intensifying because Chinese OEMs mandate cellular-enabled voice stacks under MIIT standards without commensurate price tolerance. Fleet operators in North America exhibit the lowest price sensitivity, absorbing premium voice AI licensing costs for NHTSA compliance, while European buyers face acute elasticity from GDPR compliance overhead.
Supply Chain Analysis
Tariff exposure between Taiwan and mainland China dominates supply chain risk planning for dedicated neural processing units, with foundry capacity allocation decisions in South Korean and Japanese semiconductor zones creating allocation bottlenecks for automotive voice chipsets. Raw material dependencies center on rare earth elements for microphone magnet assemblies, silicon wafers for DSP fabrication, and copper alloys for connector components. Single-source vulnerability concentrates in beamforming algorithm IP held by acoustic engineering specialists clustered in Stuttgart and Detroit. Distribution runs through Tier 1 electronics integrators bundling hardware with NLP software licensing, though fleet procurement patterns increasingly unbundle these components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gesture control and haptic feedback interfaces pose credible substitution threats to voice-first cockpit designs, forcing incumbents to defend position through continuous accuracy improvement and regulatory compliance embedding that alternative modalities cannot easily replicate.
For Market Incumbents: Insulate platform stickiness by deepening backward integration into proprietary training datasets for cabin noise cancellation, neutralizing the accent recognition limitations that expose incumbents to cloud-native challengers. Secure exclusive microphone array supply commitments from Shenzhen manufacturing clusters before allocation constraints tighten. Anchor defensive positioning in ECE R79 and Euro NCAP certification pathways that emerging entrants cannot rapidly duplicate.
For New Entrants and Emerging Players: Establish a beachhead in commercial vehicle fleet specifications where hardware-software unbundling creates procurement entry points absent in passenger vehicle OEM relationships. Target Texas and Michigan logistics operators demanding voice-enabled coordination without driver distraction, exploiting the underpenetrated heavy-duty truck segment relative to premium passenger vehicles. Lead with over-the-air feature activation licensing models that bypass capital-intensive acoustic hardware manufacturing.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated Tier 1 electronics parents seeking to monetize voice AI software assets separately from declining-margin hardware operations. Long-term viability favors platform licensors with automotive-specific natural language capabilities over commodity cloud infrastructure providers. Watch for inflection in fleet procurement patterns specifying acoustic hardware and NLP software through separate RFPs, signaling durable unbundling that rewards pure-play software valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Cloud Hybrid Architecture Deployment | Enables German luxury OEMs to satisfy both NHTSA offline mandates and MIIT connected-vehicle standards simultaneously. |
| Over-the-Air Feature Activation Licensing | Captures recurring revenue from premium voice functions without hardware differentiation across vehicle trim levels. |
| Proprietary Training Dataset Accumulation | Builds defensible accuracy advantages in noisy cabin environments that generic acoustic models cannot match. |
| GDPR-Compliant Voiceprint Storage Architecture | Unlocks European fleet deployments blocked by biometric data classification constraints under CNIL and KBA scrutiny. |
| Commercial Vehicle Fleet Specification Capture | Penetrates the heavy-duty truck segment where total cost of ownership calculations dominate procurement criteria. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers; and secondary validation against SEC filings from voice AI platform providers, vehicle production databases, IHS Markit registration data, and NHTSA regulatory dockets. Bottom-up triangulation across microphone array shipment volumes and top-down reconciliation against OEM voice stack specification rates anchored market sizing.
Forecast inputs considered vehicle class stratification, propulsion architecture differentiation, content per vehicle trajectories, OEM tier positioning, and regional production cluster dynamics across the projection horizon. CAGRs were derived from regression analysis of historical voice system penetration rates against regulatory mandate implementation timelines, with neural processing unit cost curves and 5G connectivity deployment schedules as primary industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles and automotive production volumes would shift the trajectory materially. Forecasts reflect assumptions regarding sustained regulatory enforcement of hands-free interface mandates and stable East Asian manufacturing zone access. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
Global Vehicle Camera Market