
 Europe Automotive Airfilters Market | 2026-2036
Europe Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Airfilters Market Foresight
The EU Green Deal is consolidating demand for high-efficiency automotive filtration across European vehicle production networks. Mann+Hummel GmbH leverages its integrated filter media operations to supply major German OEM assembly lines. MAHLE GmbH anchors its position through R&D intensity in synthetic fiber substrates for next-generation engine air filters. Freudenberg Filtration Technologies competes on geographic dominance, operating dedicated manufacturing facilities serving French and Italian automotive clusters.
Europe Automotive Airfilters are engineered filtration media designed to remove particulate matter, pollen, and gaseous contaminants from intake air streams, with HEPA-grade media capturing particles as small as 0.3 microns to protect engine components and cabin environments. Cabin filters incorporating activated carbon layers command premium positioning as European consumers prioritize interior air quality during urban commutes. Engine air filters utilizing nanofiber technology represent the fastest-expanding material segment, displacing conventional paper substrates in premium vehicle platforms where extended service intervals reduce total cost of ownership.
EMA's MDR-aligned quality expectations and REACH chemical compliance protocols shape material selection and supplier qualification across the European supply base. The F-Gas Regulation indirectly elevates cabin filtration standards as HVAC system redesigns demand compatible high-performance filters. Stakeholders must monitor how ECHA substance restriction proposals affect synthetic fiber chemistries and assess whether CE marking evolution will tighten conformity assessment burdens for aftermarket filter imports.
Market Dynamics
The EU Green Deal's emissions benchmarks are compressing replacement cycles and forcing filter media upgrades across European vehicle production networks, while Eastern European manufacturing corridors concentrate assembly capacity and reshape procurement geography.
Growth Catalysts
- REACH chemical compliance protocols:Manufacturers are reformulating synthetic fiber substrates to eliminate restricted substances, creating pull for certified filter media suppliers.
- Nanofiber technology:Premium vehicle platforms are adopting extended-service-interval engine air filters, reducing total cost of ownership and driving material substitution.
- Eastern European manufacturing corridors:Assembly plant expansion in Poland, Czech Republic, and Romania is localizing filter demand and shortening supply lines.
Market Restraints
- Petrochemical input volatility:Synthetic fiber production depends on polymer feedstock pricing, compressing margin stability for non-integrated suppliers.
- F-Gas Regulation compliance costs:HVAC system redesigns require compatible high-performance cabin filters, elevating R&D expenditure for smaller manufacturers.
- Conventional paper substrate displacement limits:Economy vehicle segments retain cellulose-based filters due to cost sensitivity, fragmenting material standardization.
Strategic Opportunities
- Activated carbon cabin filter penetration:Urban commuters in France and Italy are prioritizing interior air quality, expanding premium positioning for multi-layer media.
- EMA MDR-aligned aftermarket qualification:CE marking evolution is creating entry barriers for non-compliant imports, defending incumbent supplier positions.
- Commercial fleet telematics integration:Connected filter monitoring systems are enabling predictive replacement scheduling in German logistics operations.
Industry Challenges
- ECHA substance restriction timeline uncertainty:Pending proposals on synthetic fiber chemistries are freezing long-term material roadmaps and capex commitments.
- Cross-border aftermarket certification fragmentation:Divergent national implementation of EU directives is complicating pan-European distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Airfilters Market |
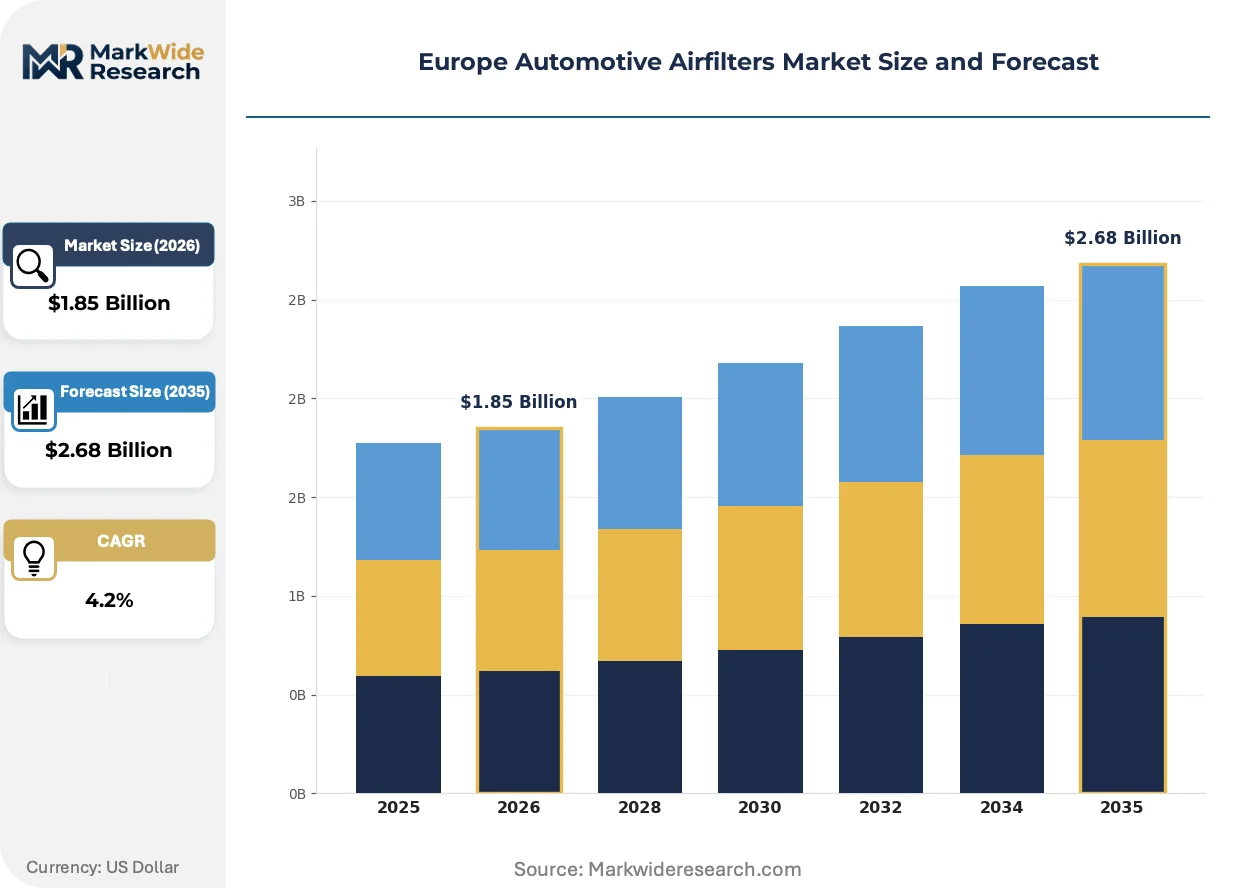
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabin Filters, Engine Air Filters, Fuel Filters, Oil Filters Material: Paper, Foam, Cotton, Synthetic End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Technology: HEPA, Electrostatic, Activated Carbon, Nanofiber |
| Companies Covered | Mann+Hummel GmbH, MAHLE GmbH, Hengst SE, Robert Bosch GmbH, Sogefi Group, Donaldson Company, Ahlstrom Corporation, Freudenberg Filtration Technologies, UFI Filters, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Airfilters Market Shifts & Advancements
Filter media technology is bifurcating between premium nanofiber platforms and cost-optimized synthetic blends, while regulatory chemistry constraints and fleet digitization reshape competitive requirements.
Nanofiber engine air filter media is consolidating its position in premium European OEM specifications. German and Swedish luxury vehicle manufacturers are specifying sub-micron filtration layers for extended drain intervals. This technology is consolidating supplier relationships around vertically integrated fiber producers capable of in-house nanofiber spinning.
The F-Gas Regulation is mandating HVAC system redesigns that elevate cabin filtration compatibility requirements. Automotive thermal management suppliers are qualifying higher-efficiency filters to match refrigerant transition timelines. French and Italian OEMs are most affected, accelerating validation cycles for activated carbon composite media.
Fleet operators are unbundling filter procurement from traditional service contracts. German commercial vehicle managers are sourcing directly from certified filter manufacturers, bypassing multi-brand distributors. This pattern is most visible in long-haul logistics corridors connecting the Ruhr Valley to Polish border manufacturing zones.
Europe Automotive Airfilters Market Segmentation
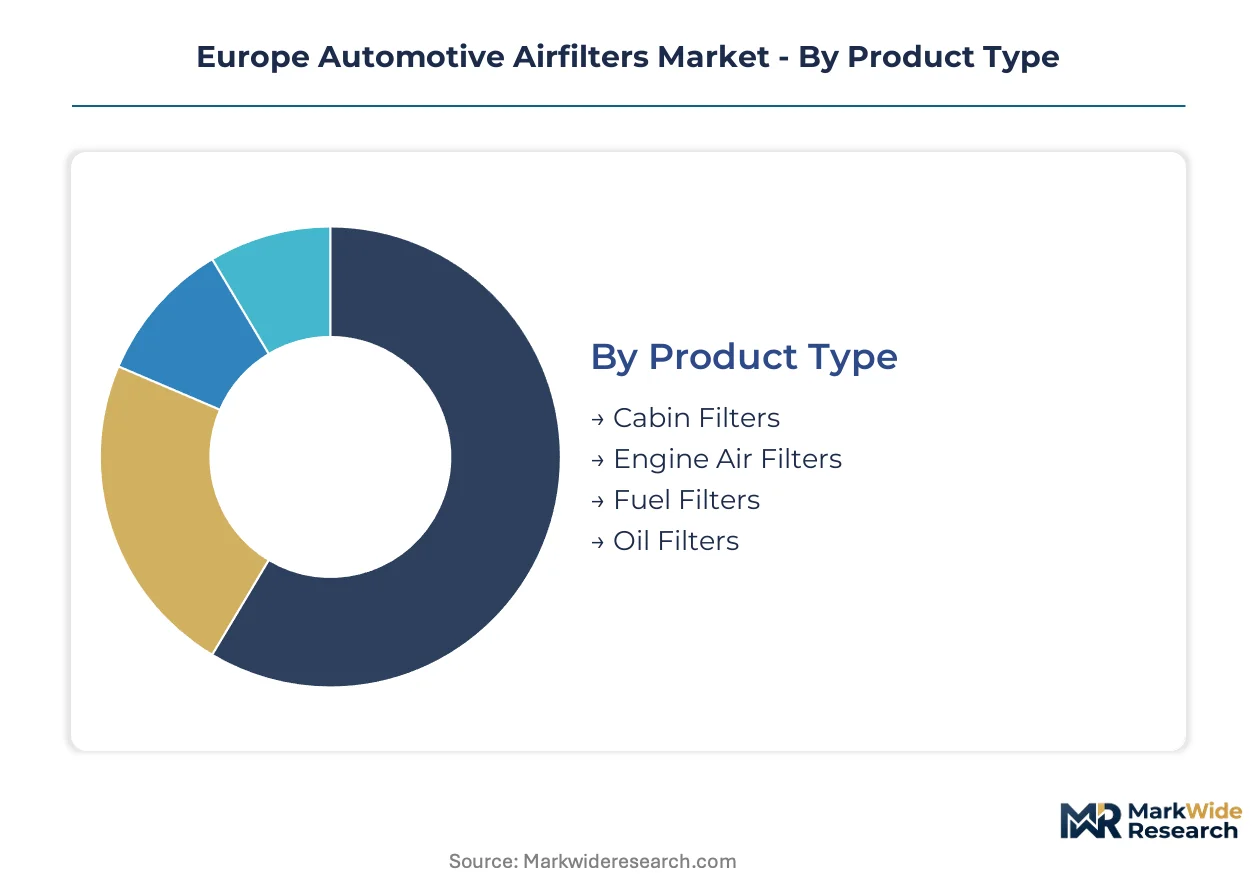
European automotive airfilter segmentation reflects divergent technical requirements across cabin comfort systems and engine protection architectures. Material chemistry and filtration efficiency specifications create distinct procurement patterns between OEM assembly lines and aftermarket service networks.
Product Type:
Standalone cabin filtration systems operate independently from embedded engine intake protection, creating divergent replacement economics and supplier qualification pathways across European vehicle platforms.
- Cabin Filters:Multi-layer media combining particulate barriers with activated carbon adsorption layers remove pollen, dust, and NOx from HVAC intake streams. Urban commuter preferences in French and Italian metropolitan corridors elevate demand for premium carbon-composite variants that address interior air quality concerns during congested traffic conditions.
- Engine Air Filters:Pleated media assemblies protect combustion chambers from abrasive particulate ingress, with nanofiber-enhanced specifications gaining specification in German and Swedish premium vehicle platforms where extended service intervals reduce total cost of ownership for fleet operators.
- Fuel Filters:Water-separating media and contaminant barriers safeguard high-pressure injection systems from particulate damage and corrosion.
- Oil Filters:Full-flow and bypass configurations maintain lubricant cleanliness across extended drain intervals mandated by OEM service schedules.
Volume placements concentrate in Engine Air Filters; the faster expansion belongs to Cabin Filters.
Material:
Cost tier stratification separates commodity cellulose substrates from performance-engineered synthetics, with polymer feedstock volatility compressing margin structures for non-integrated converters.
- Synthetic:Melt-blown polypropylene and polyester nonwovens deliver calibrated fiber diameters for sub-micron efficiency without flow restriction penalties. REACH chemical compliance protocols are forcing reformulation of fiber binders and surface treatments, pulling procurement toward certified suppliers with validated substance dossiers.
- Paper:Resin-bonded cellulose remains dominant in economy vehicle segments and high-volume aftermarket replacement due to raw material cost advantages and established manufacturing infrastructure.
- Foam:Polyurethane reticulated structures provide coarse pre-filtration and custom-fit applications in specialty vehicle conversions.
- Cotton:Washable woven media serve enthusiast aftermarket segments prioritizing reusability over disposable convenience.
Standard-grade paper commands the largest unit volumes; synthetic media is climbing the fastest as OEM specifications tighten.
End User:
Customer type determines certification burden and pricing leverage, with direct OEM supply relationships requiring full IATF 16949 traceability versus transactional aftermarket procurement.
- OEMs:Original equipment manufacturers specify filter performance through validated component specifications with multi-year supply agreements. German and Czech vehicle assemblers are consolidating supplier panels around vertically integrated media producers capable of simultaneous cabin and engine filter qualification.
- Aftermarket Providers:Independent distributors and private-label converters serve replacement demand through fragmented retail and wholesale channels.
- Dealerships:Authorized service networks execute warranty-compliant replacements using OEM-branded or approved-equivalent components.
- Vehicle Assemblers:Contract manufacturers and kit builders procure filters as part of module integration contracts.
Aftermarket channels move the highest unit volumes; OEM direct supply is gaining share fastest through platform consolidation.
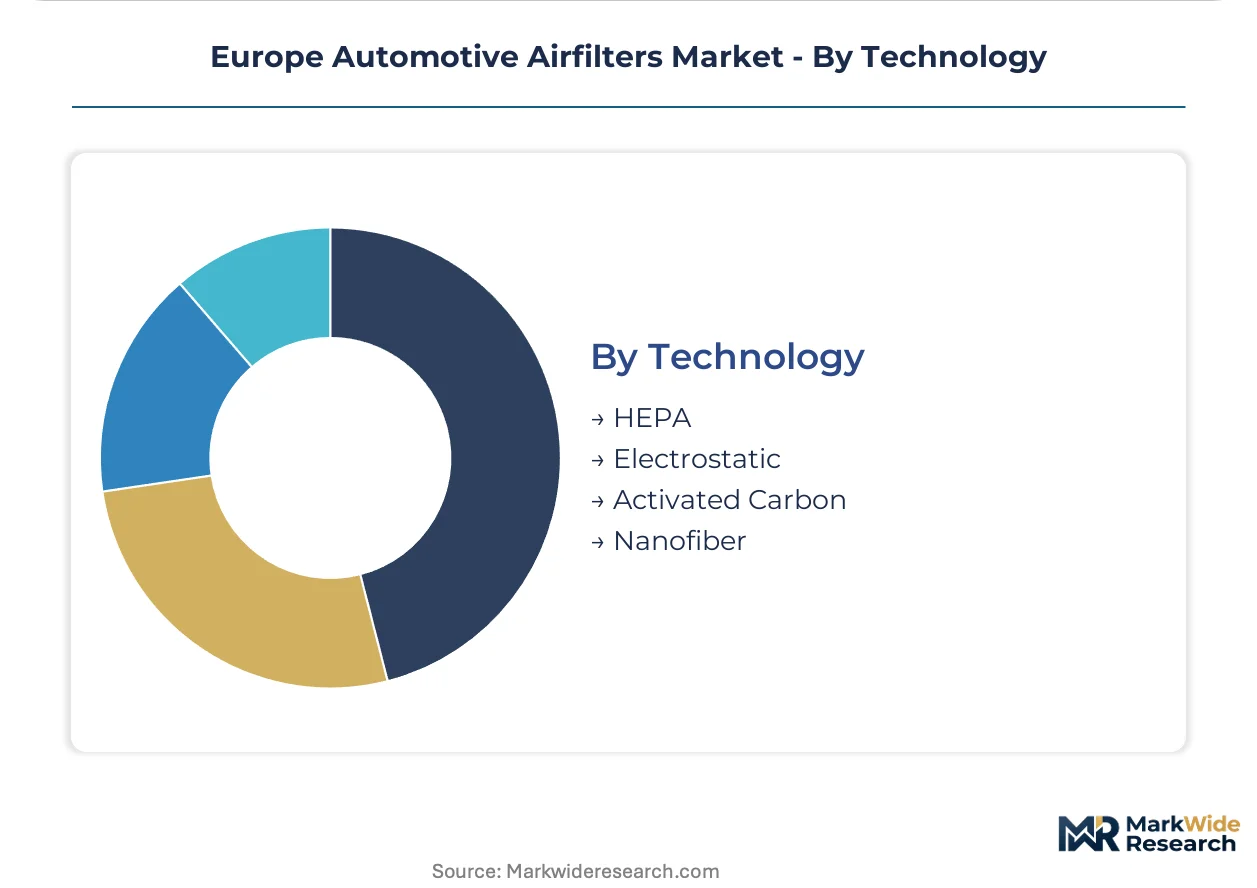
Technology:
Filtration mechanism selection tracks application severity and regulatory pressure, with activated carbon and nanofiber platforms displacing conventional mechanical media in premium positioning.
- Nanofiber:Electrospun polymer layers create tortuous paths for sub-micron particle capture without the flow restriction of denser conventional media. Extended service interval specifications from German luxury OEMs are accelerating validation of nanofiber-enhanced engine air filters.
- Activated Carbon:Impregnated granular or fiber-based adsorption media remove gaseous contaminants and odors from cabin air streams. F-Gas Regulation-driven HVAC system redesigns in French and Italian vehicle platforms are elevating compatibility requirements for carbon-composite cabin filters.
- HEPA:High-efficiency particulate air specifications capture particles at 0.3 microns with 99.97% efficiency for allergen-sensitive vehicle occupants.
- Electrostatic:Charged fiber media enhance particle attraction without dense mechanical packing, balancing efficiency and pressure drop.
HEPA-grade mechanical filtration maintains the broadest installed base; nanofiber technology is expanding most quickly in premium OEM specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European automotive airfilter production concentrates in Germany and Czech Republic assembly corridors, while consumption spreads across Western and Eastern European vehicle fleets. The EU Green Deal's emissions benchmarks are compressing replacement cycles unevenly across national markets. Eastern European manufacturing expansion is shortening supply lines and reshaping procurement geography.
Germany
German commercial vehicle fleets are expanding filter replacement schedules through connected telematics systems. KBA vehicle certification requirements enforce stringent filtration efficiency standards for domestic OEM assembly. The Ruhr Valley to Bavaria corridor anchors integrated filter media production serving Mercedes-Benz and BMW assembly networks.
France
French urban commuters are prioritizing activated carbon cabin filters for interior air quality during congested Paris and Lyon traffic. ANSM-aligned quality expectations shape aftermarket qualification protocols for imported filter components. The Île-de-France automotive cluster is validating higher-efficiency filters to match F-Gas Regulation HVAC redesign timelines.
Italy
Italian OEMs are accelerating validation cycles for carbon-composite cabin filters under refrigerant transition pressures. REACH chemical compliance protocols are forcing reformulation of fiber binders among Turin-based suppliers. The Piedmont and Emilia-Romagna manufacturing zones concentrate filter demand from Fiat and Ferrari assembly operations.
Poland
Polish assembly plant expansion is localizing filter demand from German and Korean vehicle manufacturers. EU structural funds are supporting supplier park development around Wrocław and Poznań production hubs. The Silesian automotive corridor is attracting tier-one filter manufacturers seeking proximity to Kia and Volkswagen assembly lines.
Czech Republic
Czech vehicle assemblers are consolidating supplier panels around vertically integrated media producers. CE marking evolution is creating entry barriers for non-compliant aftermarket imports from Asian sources. The Mladá Boleslav and Nošovice industrial zones anchor Škoda and Hyundai filter procurement networks.
Europe Automotive Airfilters Market Competitive Landscape
The competitive structure tilts toward integrated filtration specialists with captive media production capabilities. German and Italian suppliers dominate OEM direct supply through long-term platform agreements, while smaller converters serve fragmented aftermarket channels. Three archetypes define positioning: vertically integrated fiber producers, specialized automotive tier-one suppliers, and regional private-label converters. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers defend positions against Eastern European cost competition.
Among Germany-based filtration specialists, Mann+Hummel GmbH and MAHLE GmbH occupy positions exemplifying integrated media-to-module supply capabilities. Freudenberg Filtration Technologies represents the geographic diversification archetype with manufacturing presence serving multiple European automotive clusters. These three anchors illustrate how scale and integration separate OEM direct suppliers from aftermarket-focused competitors.
| Leading Market Players |
|---|
| Mann+Hummel GmbH |
| MAHLE GmbH |
| Hengst SE |
| Robert Bosch GmbH |
| Sogefi Group |
| Donaldson Company |
| Ahlstrom Corporation |
| Freudenberg Filtration Technologies |
| UFI Filters |
| Others |
Supply & Pricing Matrix
Nanofiber spinning technology adoption is simultaneously elevating production capital intensity and concentrating supplier relationships around German and Czech vertically integrated media producers capable of in-house fiber production. This manufacturing transition compresses margin structures for non-integrated converters while amplifying pricing leverage for backward-integrated specialists with captive polymer feedstock processing.
Pricing Analysis
Margin tightening in synthetic cabin filter tiers reflects REACH chemical compliance reformulation costs and activated carbon layer qualification expenses. Three-tier pricing structure across premium nanofiber, standard synthetic blend, and economy cellulose levels tracks certification grade and volume scale. Cost compression accelerates in paper-based segments as Eastern European converters exploit labor arbitrage. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership optimization, while independent aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Dual-sourcing mandates from German and Czech OEMs require qualified backup suppliers for nanofiber media, fragmenting procurement volumes across certified converter networks. Geographic supply concentrates in Germany, Czech Republic, and Poland, drawing from melt-blown polypropylene and polyester nonwoven feedstocks. Single-source vulnerability persists in electrospun nanofiber equipment and specialized activated carbon impregnation lines. Distribution runs through Tier 1 module suppliers for OEM channels and fragmented wholesale networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Automotive Airfilters Market functions as a cost-of-compliance arena where REACH substance dossiers and CE marking protocols erect formidable barriers against unqualified imports, entrenching incumbents with validated certification infrastructure.
For Market Incumbents: Deploy backward integration into polymer fiber spinning to capture margin compression from petrochemical volatility and defend against Eastern European cost competition. Accelerate ECHA pre-registration for next-generation synthetic fiber chemistries before substance restriction timelines crystallize. Consolidate supplier panels around German and Czech manufacturing corridors to match OEM platform standardization demands. For New Entrants and Emerging Players: Polish contract manufacturers serving Korean and German vehicle assemblers represent the most penetrable entry point for certified filter media supply. Target activated carbon cabin filter qualification for French and Italian OEMs undergoing F-Gas Regulation HVAC redesigns. Pursue direct fleet procurement relationships in German logistics corridors as telematics-enabled predictive replacement disrupts traditional distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automotive thermal management conglomerates seeking filtration capabilities for electrification thermal systems. Five-to-ten-year viability hinges on nanofiber technology scale and regulatory chemistry adaptation capacity. Watch ECHA substance restriction proposal finalization as the critical inflection signal for synthetic fiber chemistry capex commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Media Production | Captive polypropylene spinning insulates margin structures from polymer feedstock volatility affecting non-integrated competitors. |
| REACH-Compliant Synthetic Fiber Reformulation | ECHA-validated substance dossiers defend OEM supply positions against restricted chemistry proposals freezing competitor roadmaps. |
| Telematics-Enabled Fleet Service Contracts | Predictive replacement scheduling in German logistics corridors bypasses fragmented aftermarket distribution channels. |
| Activated Carbon Composite Validation | F-Gas Regulation HVAC redesign timelines in French and Italian OEMs accelerate premium cabin filter specification cycles. |
| Eastern European Manufacturing Footprint Expansion | Proximity to Polish and Czech assembly plants shortens supply lines for Kia, Volkswagen, and Hyundai procurement networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and ECHA regulatory affairs specialists. Vehicle production databases, REACH substance dossiers, and EU Green Deal implementation trackers provided demand-side validation. Bottom-up filter unit consumption estimates triangulated against top-down automotive assembly projections across the analysis window.
Data-stream reconciliation integrated filtration efficiency specifications, material chemistry roadmaps, and replacement cycle assumptions across vehicle class, propulsion architecture, and regional production cluster dimensions. CAGRs derived from normalized growth rate convergence between historical trajectory extrapolation and driver-based elasticity modeling. Nanofiber penetration curves and fleet telematics adoption rates served as industry-specific forecast inputs throughout the projection horizon.
Revisions become necessary when ECHA substance restriction timelines accelerate, F-Gas Regulation implementation diverges across member states, or Eastern European manufacturing expansion outpaces supplier park development. Deviation in polymer feedstock price volatility or REACH compliance cost escalation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Automotive Headliners Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Active Seat Headrests Market
Automotive Components
Regenerative Suspension System Market