
 Brake-By-Wire System Market | 2026-2036
Brake-By-Wire System Market Size, Share, and Industry Trends Forecast 2026-2036
Brake-By-Wire System Market Outlook
Commercial vehicle electrification is broadening the addressable base for brake-by-wire suppliers beyond premium passenger cars. Robert Bosch GmbH leverages its cross-domain electronics portfolio to anchor integrated braking and vehicle dynamics solutions across European and North American OEM programs. Continental AG competes through sustained R&D intensity in electro-hydraulic actuation architectures, while ZF Friedrichshafen AG dominates integrated chassis systems with its brake-by-wire positioning within broader motion control strategies.
Brake-by-wire systems replace mechanical or hydraulic linkages with electronic signal transmission to braking actuators, typically operating via redundant controller area network buses with sub-100-millisecond latency requirements and ASIL-D functional safety ratings under ISO 26262. The primary purpose is decoupled pedal feel generation, energy recuperation optimization, and foundation brake modulation for autonomous emergency stopping. Electro-hydraulic technology leads current revenue contribution due to its retrofit compatibility and transitional risk profile for OEMs, while pure electric architectures represent the fastest-expanding segment as dedicated EV platforms shed hydraulic fluid entirely. Sensor subsystems concentrate margin pools where multi-axis inertial measurement and pedal position encoding command specialist calibration capabilities.
NHTSA Federal Motor Vehicle Safety Standards and UN ECE R13-H braking harmonization protocols shape product certification requirements and cross-border market access timelines for brake-by-wire suppliers. ISO 26262 functional safety and ISO/SAE 21434 cybersecurity frameworks add compliance layers that favor established tier-ones with dedicated validation infrastructure. Stakeholders must monitor OEM platform consolidation decisions that bundle braking with steering and suspension into single supplier contracts.
Market Dynamics
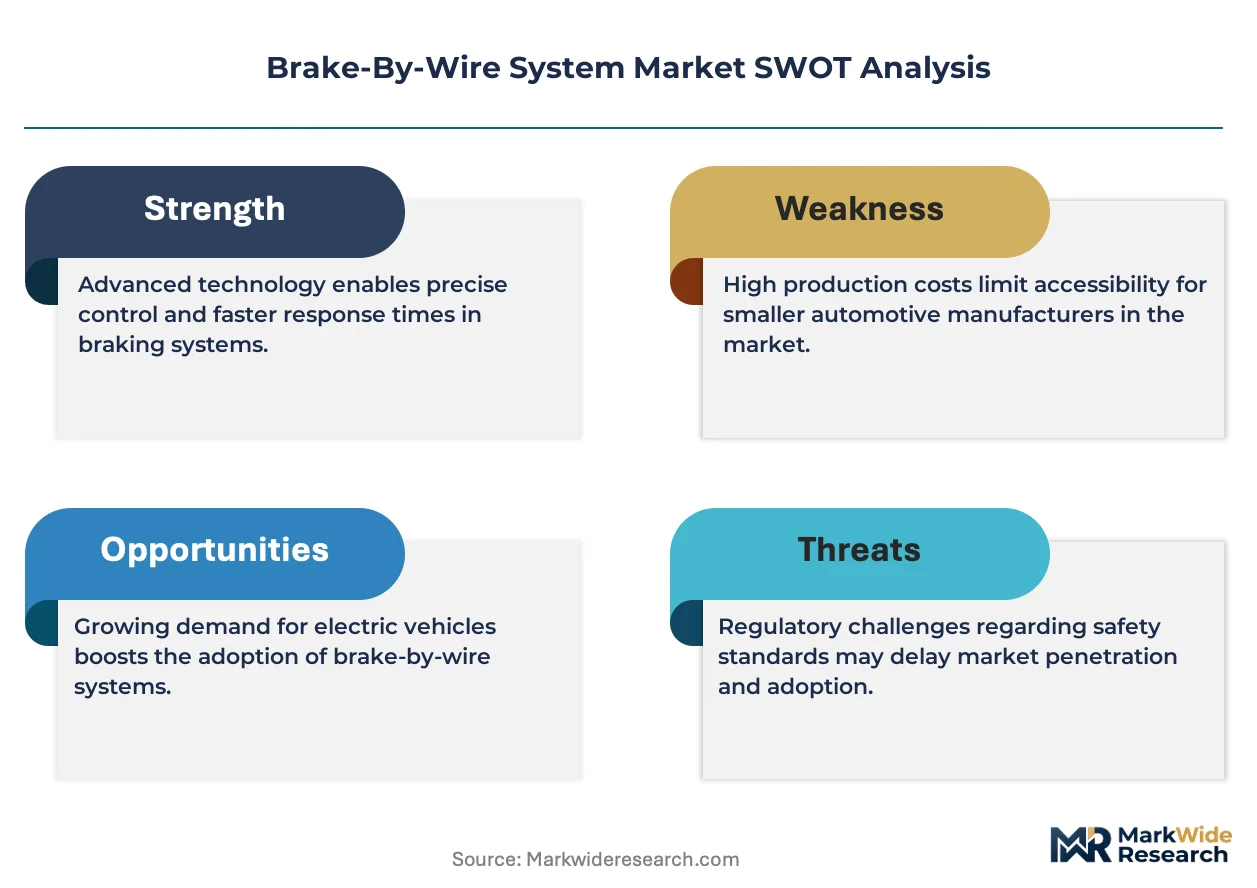
Platform electrification is dissolving the mechanical-hydraulic legacy in braking architectures, forcing suppliers to reconstitute their value propositions around software-defined actuation and energy recuperation integration.
Growth Catalysts
- UN ECE R79-H harmonization:Cross-border braking and steering standardization accelerates OEM platform consolidation decisions across European and Japanese vehicle programs.
- Commercial vehicle electrification:Heavy-duty fleet operators in Germany and the United States demand brake-by-wire compatibility with regenerative braking systems for total cost of ownership reduction.
- ASIL-D functional safety mandates:ISO 26262 certification requirements under NHTSA guidance pull redundant electronic architectures into mainstream passenger vehicle specifications.
Market Restraints
- Semiconductor input volatility:Redundant controller area network chips and power electronics face allocation constraints from concentrated foundry capacity in East Asia.
- Hydraulic retrofit compatibility:Electro-hydraulic transitional architectures extend program complexity for OEMs managing dual supply chains during platform migration.
- Validation infrastructure scarcity:Dedicated ASIL-D testing facilities concentrate among established tier-ones, elevating barriers for new entrants.
Strategic Opportunities
- India commercial vehicle penetration:Domestic OEM platform decisions for electric buses and medium-duty trucks remain uncommitted, opening supplier positioning windows.
- Autonomous emergency braking convergence:Integration of brake-by-wire with lidar and radar perception stacks creates bundled system opportunities.
- Japan METI carbon-neutral incentives:Subsidies for EV component localization accelerate dedicated electric architecture adoption versus transitional electro-hydraulic designs.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering and real-time control algorithm development outpaces graduate pipeline output in Germany and Japan.
- Multi-domain certification timelines:Simultaneous ISO 26262 and ISO/SAE 21434 cybersecurity validation extends program launch schedules by 18-24 months.
- Legacy hydraulic supplier transition friction:Incumbent brake manufacturers face stranded asset risk in casting and machining capacity during electrification migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brake-By-Wire System Market |
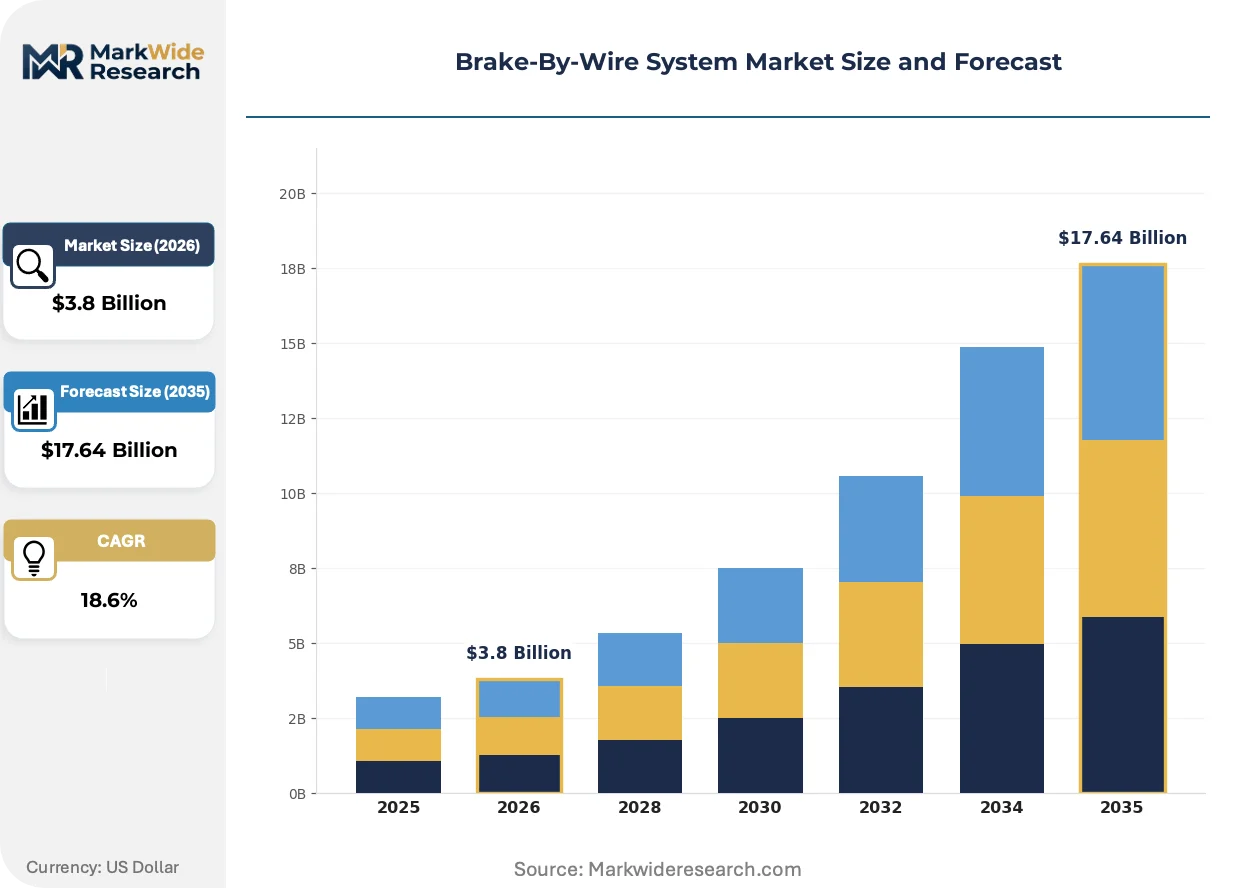
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Module, Actuator, Sensor, Interface Technology: Electric, Electro-Hydraulic, Fiber Optic, Hybrid End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Aerospace Application: Dynamic Braking, Emergency Braking, Passive Braking, Adaptive Interfaces |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Hitachi Astemo, Hyundai Mobis, Brembo, Denso Corporation, Knorr-Bremse AG, Akebono Brake Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brake-By-Wire System Market Strategic Shifts
Software-defined braking architectures are compressing hardware differentiation windows while elevating firmware and calibration capabilities as primary competitive moats for system suppliers.
Electro-hydraulic brake-by-wire is consolidating transitional market share as OEMs balance energy recuperation demands against platform risk tolerance. European and North American passenger vehicle programs adopt these architectures at accelerated cadences to preserve pedal feel continuity. The technology is consolidating supplier relationships around tier-ones with integrated chassis electronics portfolios.
NHTSA Federal Motor Vehicle Safety Standard 135 and its harmonization with UN ECE R13-H braking protocols mandate specific performance envelopes for electronic braking systems. These rules compress development timelines for suppliers seeking multi-region type approval. Commercial vehicle segments in the United States face the steepest compliance curve due to divergent legacy test procedures.
Buyer concentration among megaplatform OEMs is compressing supplier negotiation cycles and unbundling traditional brake system specifications. Tier-one contracts now separate foundation brake hardware from pedal simulators and energy management software. This pattern is most visible in German and Japanese OEM program structures where single-supplier chassis integration mandates prevail.
Brake-By-Wire System Market Segmentation
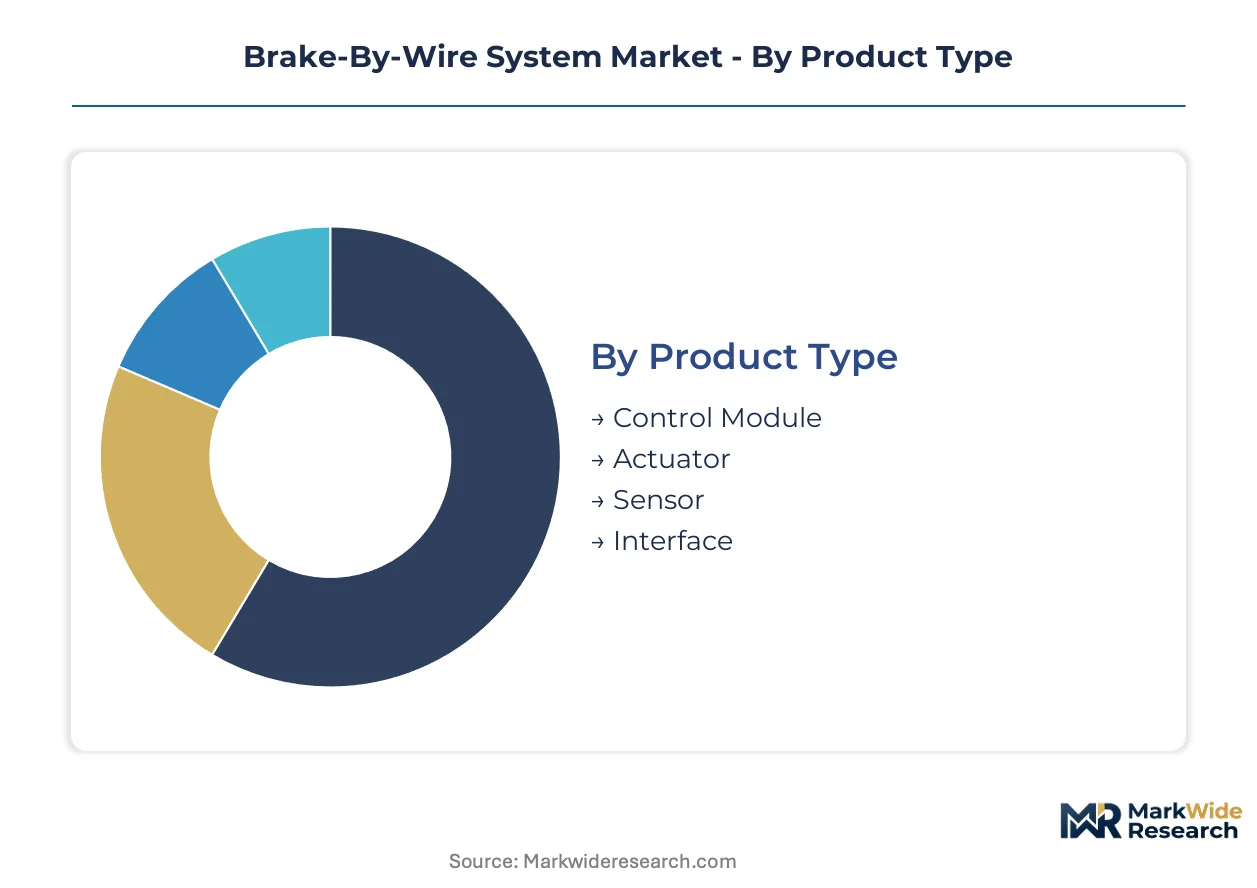
Brake-by-wire architectures fragment across hardware, software, and integration layers, with each segment carrying distinct margin profiles and certification burdens. Supplier positioning depends on matching technical capabilities to OEM platform consolidation timelines.
Product Type:
Upgrade cycles for brake-by-wire components track ASIL-D validation timelines and platform electrification roadmaps, with modular designs enabling phased retrofit across vehicle generations.
- Control Module:Redundant microcontroller units process pedal position signals and coordinate actuator responses via dual CAN bus architectures. German and Japanese OEM programs concentrate procurement for integrated chassis control modules that bundle braking with steering domain management.
- Actuator:Electro-mechanical caliper motors and hydraulic pump assemblies convert electrical commands into friction force, requiring sealed enclosures against thermal cycling and vibration. Demand clusters around European passenger vehicle platforms transitioning from vacuum-boosted hydraulic systems.
- Sensor:Multi-axis inertial measurement units and pedal position encoders feed real-time state estimation algorithms.
- Interface:Haptic pedal simulators and driver feedback systems decouple mechanical feel from actual braking force generation.
Volume placements concentrate in Control Module procurement; the faster expansion belongs to Actuator demand as pure-electric architectures displace transitional electro-hydraulic designs.
Technology:
Cost tier stratification separates premium electric architectures from transitional electro-hydraulic systems, with fiber optic and hybrid variants occupying niche performance segments.
- Electro-Hydraulic:Retains hydraulic fluid for final brake actuation while replacing mechanical linkages with electronic signal transmission, preserving pedal feel continuity for risk-averse OEM migration paths. North American and European passenger vehicle programs favor this architecture for platform compatibility during electrification transitions.
- Electric:Pure electro-mechanical actuation eliminates hydraulic fluid entirely, enabling packaging flexibility and simplified maintenance for dedicated EV platforms. Japanese METI carbon-neutral incentives accelerate adoption versus transitional designs.
- Fiber Optic:Immunity to electromagnetic interference supports military and aerospace applications with extreme signal integrity requirements.
- Hybrid:Combines electric primary actuation with hydraulic backup for fail-operational redundancy in commercial vehicle specifications.
Revenue concentration sits with Electro-Hydraulic architectures today; Electric systems are climbing the fastest as dedicated EV platforms reach production scale.
End User:
Application maturity varies sharply across mobility modes, with automotive segments leading certification infrastructure and aerospace imposing specialized reliability standards.
- Passenger Vehicles:Premium and mass-market electric platforms drive standardization of brake-by-wire as baseline equipment, with NHTSA Federal Motor Vehicle Safety Standard 135 mandating performance envelopes for electronic braking systems. United States and German OEM integration timelines are most advanced.
- Commercial Vehicles:Heavy-duty fleet operators demand compatibility with regenerative braking for total cost of ownership reduction in electrified logistics applications. Germany and United States heavy-duty segments face the steepest compliance curves.
- Two-Wheelers:Compact packaging constraints and cost sensitivity limit adoption to premium electric motorcycle platforms.
- Aerospace:Fly-by-wire braking for electric vertical takeoff and landing aircraft imposes extreme reliability and weight specifications.
Procurement volume clusters in Passenger Vehicles; Commercial Vehicles are gaining share fastest as fleet electrification broadens the addressable base.
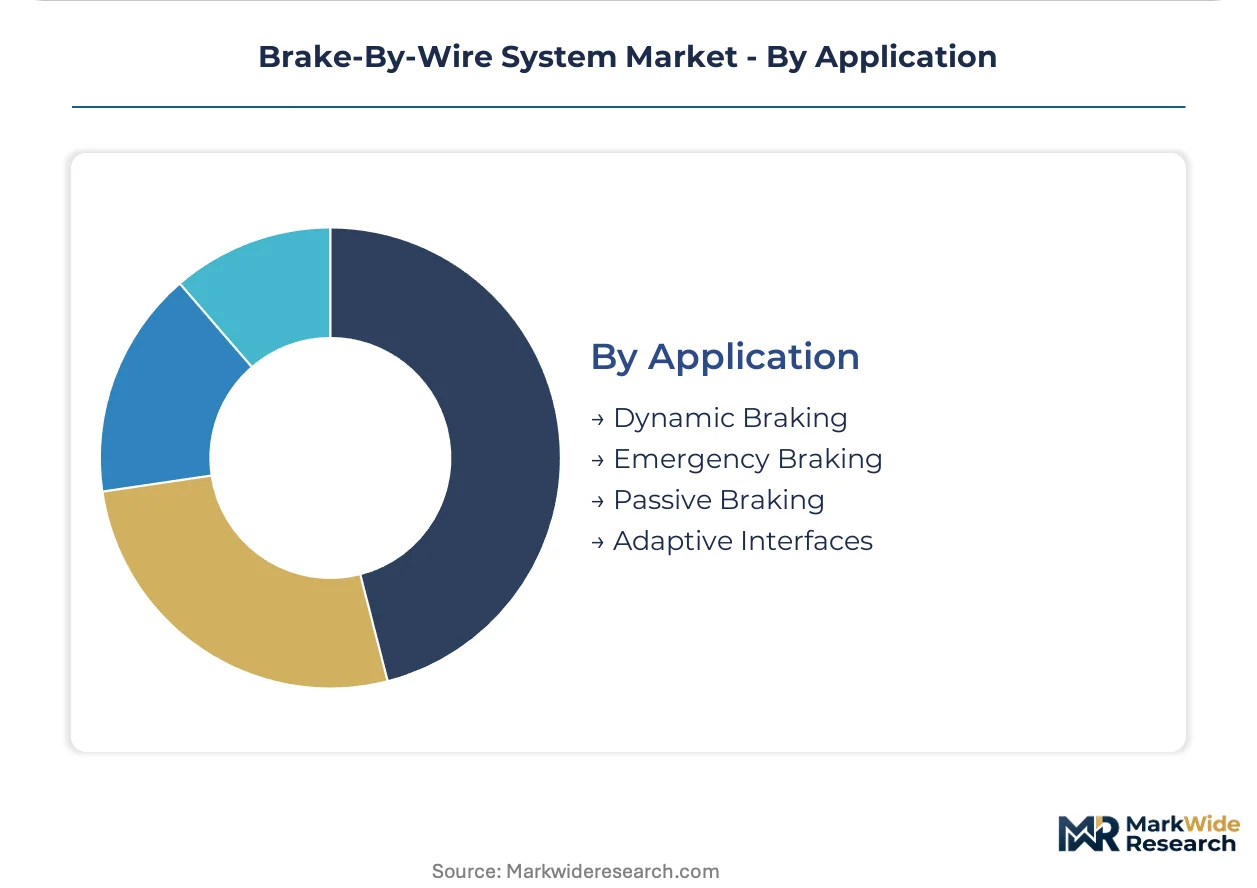
Application:
Functional differentiation separates safety-critical emergency systems from comfort-oriented adaptive interfaces, with dynamic braking commanding the dominant share of embedded software complexity.
- Dynamic Braking:Real-time modulation of friction and regenerative blending optimizes energy recuperation while maintaining vehicle stability through integrated chassis control. This application concentrates R&D investment from tier-one suppliers with motion control portfolios.
- Emergency Braking:Autonomous emergency stopping systems demand sub-100-millisecond latency from perception to actuator response, with redundant signal paths satisfying ASIL-D requirements under ISO 26262.
- Passive Braking:Parking brake and hill-hold functions leverage brake-by-wire actuators for automated engagement.
- Adaptive Interfaces:Personalized pedal response mapping and haptic feedback customization enhance driver experience differentiation.
Development resources concentrate in Dynamic Braking; Emergency Braking integration with perception stacks shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive special economic zones in Stuttgart, Wolfsburg, and Shanghai concentrate brake-by-wire engineering talent and validation infrastructure. These clusters anchor OEM integration timelines and tier-one supplier positioning across three continents.
Germany
Premium passenger vehicle electrification and commercial fleet decarbonization drive procurement intensity. KBA type-approval requirements under UN ECE R13-H compress development cycles for multi-region certification. Stuttgart and Wolfsburg engineering clusters host integrated chassis control development for German OEM platform consolidation.
United States
Heavy-duty logistics electrification and autonomous vehicle testing corridors expand addressable demand. NHTSA Federal Motor Vehicle Safety Standard 135 mandates specific electronic braking performance envelopes. Michigan and California automotive clusters concentrate brake-by-wire validation for Detroit and Silicon Valley OEM programs.
Japan
Domestic OEM dedicated EV platform roadmaps accelerate pure electric architecture adoption. METI carbon-neutral component localization subsidies favor domestic supply chain development. Nagoya and Tokyo metropolitan areas anchor motion control engineering for integrated braking-steering systems.
China
New energy vehicle production quotas and domestic brand platform independence reshape supplier procurement patterns. MIIT intelligent connected vehicle regulations mandate redundant braking architectures for autonomous operation. Yangtze River Delta manufacturing clusters concentrate electro-mechanical actuator production scaling.
South Korea
Chaebol-affiliated tier-one vertical integration and dedicated EV skateboard platforms drive captive supply decisions. MFDS automotive component certification aligns with UN ECE harmonization protocols. Seoul Capital Area R&D centers focus on brake-by-wire software calibration for global OEM export programs.
Brake-By-Wire System Market Competitive Environment
Top-tier vendors anchor integrated chassis electronics, while mid-scale specialists occupy component niches. The supplier base consolidates around motion control portfolios and cross-domain electronics capabilities. Three archetypes dominate: diversified tier-one conglomerates with braking-steering integration, electro-hydraulic transitional specialists, and pure-electric actuator pure-plays. Competitive moves concentrate on ASIL-D validation infrastructure expansion and software-defined braking platform partnerships.
Among diversified European tier-ones, Robert Bosch GmbH and Continental AG exemplify the integrated chassis control archetype, each leveraging cross-domain electronics portfolios to anchor multi-OEM program participation. ZF Friedrichshafen AG occupies a position within motion control system bundling, representing the convergence strategy where braking, steering, and suspension domains consolidate under single-supplier contracts. These three entities collectively illustrate how established tier-ones defend positioning through functional safety certification depth and firmware calibration capabilities.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Hitachi Astemo |
| Hyundai Mobis |
| Brembo |
| Denso Corporation |
| Knorr-Bremse AG |
| Akebono Brake Industry |
| Others |
Value Chain & Pricing Dynamics
Semiconductor input costs for redundant controller area network chips and power electronics flow from concentrated East Asian foundry capacity through tier-one suppliers into three-tier pricing structures across premium, standard, and economy levels for brake-by-wire system procurement. OEM platform consolidation decisions bundle braking with steering domains, compressing supplier negotiation cycles and amplifying cost pass-through sensitivity for electro-mechanical actuator components.
Pricing Analysis
Lead-time-driven pricing stratification rewards premium positioning for short-lead-time ASIL-D certified modules while spot inventory of transitional electro-hydraulic architectures trades at discounted contract rates. Three-tier pricing separates integrated chassis control modules from standalone actuator assemblies from economy sensor subsystems, with certification grade and volume scale as primary differentiation drivers. Cost compression in economy-tier sensor procurement is intensifying because of second-source qualification delays, while commercial vehicle fleet operators demonstrate the highest price sensitivity against premium passenger car OEMs with captive supply agreements.
Supply Chain Analysis
Specialty semiconductor supply rests on Taiwanese and South Korean foundry capacity, with German and Japanese tier-one system integrators anchoring downstream module assembly. Redundant microcontroller units, high-voltage power electronics, and sealed electro-mechanical caliper motors constitute critical input dependencies. Single-source vulnerability concentrates in advanced node chip fabrication for ASIL-D rated controllers. Distribution runs through just-in-time sequenced delivery to OEM platform engineering centers in Stuttgart, Wolfsburg, and Nagoya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASIL-D validation infrastructure scarcity props supplier pricing power across the brake-by-wire system market, with dedicated testing facility capacity representing the binding constraint on new entrant expansion.
For Market Incumbents: Deepen firmware calibration capability moats through acquisition of specialist sensor subsystem developers in Japan and Germany. Expand captive foundry partnerships for redundant controller area network chips to offset semiconductor allocation risk from East Asian concentration. Anchor integrated chassis control contracts before OEM platform consolidation decisions finalize single-supplier mandates for braking-steering-suspension bundling. For New Entrants and Emerging Players: Electric bus and medium-duty truck OEMs in India represent the most penetrable buyer archetype, with domestic platform decisions for commercial vehicle electrification remaining uncommitted. Target aftermarket retrofit compatibility programs for legacy hydraulic fleet migration as a lower-certification-burden entry path. Pursue joint development agreements with emerging EV pure-play OEMs seeking alternatives to established tier-one supply dependence. For Investors and Strategic Acquirers: METI subsidy announcements for EV component localization are the leading indicator that Japanese domestic supply chain development is accelerating toward pure electric architecture preference over transitional designs. Acquisition targets with ISO 26262 validation infrastructure and existing OEM program relationships command durable positioning across the projection horizon. Watch for OEM platform standardization decisions that unbundle foundation brake hardware from software-defined pedal simulators as the signal for vertical integration pressure release.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Validation Infrastructure Expansion | Dedicated testing facility investment secures OEM program access against new entrant competition in Germany and Japan. |
| Software-Defined Braking Platform Partnership | Firmware calibration alliances with OEMs elevate competitive moats beyond hardware commodity differentiation. |
| Semiconductor Supply Agreement | Long-term foundry contracts for redundant controller chips mitigate allocation risk from East Asian concentration. |
| Integrated Chassis Control Integration | Single-supplier contracts bundling braking with steering domains capture expanded content per vehicle. |
| Commercial Vehicle Electrification Positioning | Heavy-duty fleet compatibility opens addressable demand beyond premium passenger car segments in Germany and the United States. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and ASIL-D validation facility operators. KBA type-approval documentation, NHTSA Federal Motor Vehicle Safety Standard filings, and METI subsidy program disclosures provided regulatory trajectory inputs. Vehicle production databases and IHS Markit registration data supported demand-side calibration. Bottom-up component demand modeling and top-down OEM platform adoption timelines were cross-referenced for triangulation.
Data-stream reconciliation across the projection horizon integrated vehicle class, propulsion architecture, and content per vehicle segmentation with regional production cluster dynamics. CAGRs were derived from weighted average of OEM platform rollout schedules and supplier contract visibility. Electro-mechanical actuator scaling curves and electro-hydraulic transitional architecture phase-out assumptions informed technology transition pacing. Energy recuperation integration depth and autonomous emergency braking penetration served as automotive-specific forecast anchors.
Revisions become necessary when NHTSA regulatory delays, semiconductor allocation shocks, or OEM platform consolidation decision reversals materialize. Forecasts reflect documented assumptions regarding EV platform adoption curves and functional safety certification timeline compression. A small set of triggers—UN ECE harmonization protocol amendments, East Asian foundry capacity expansion announcements, and India commercial vehicle OEM platform commitments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Automotive Console Box Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive AR HUD Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Construction Machinery Wiring Harness Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
North America Automotive Camera Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market