
 United States Automotive Pneumatic Actuators Market | 2026-2036
United States Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Pneumatic Actuators Market Analytics
The gap between precision-engineered pneumatic actuators for electric vehicle platforms and conventional commodity units for internal combustion drivetrains is broadening. Emerson Electric Co. leverages its fluid control expertise to supply high-tolerance diaphragm actuators for hybrid powertrain applications. SMC Corporation sustains dominance in compact pneumatic cylinder architectures favored by Japanese transplant assemblers in the Southeast. Parker Hannifin Corporation anchors its position through captive distribution networks serving Detroit-based OEM tier-one suppliers.
Automotive pneumatic actuators are electromechanical devices that convert compressed air energy into linear or rotary mechanical motion, typically operating at pressures between 0.4 and 1.0 MPa to control throttle bodies, clutch mechanisms, and exhaust gas recirculation valves. Their primary purpose is to deliver rapid response, high force-to-weight actuation, and fail-safe positioning in powertrain and chassis systems where electrical alternatives risk thermal or spark hazards. Linear actuators and pneumatic cylinders command the largest volume share in fuel system and engine component applications, while rotary actuators exhibit faster growth in electrified transmission architectures. Electro-pneumatic technology captures expanding margin pools as OEMs demand integrated sensor feedback for predictive maintenance protocols.
NHTSA brake performance standards, EPA emissions compliance requirements, and ISO 9001 quality certifications collectively dictate product validation cycles and material specifications for suppliers seeking OEM qualification. The EPA's evolving greenhouse gas rules for heavy-duty trucks directly expand addressable demand for pneumatically actuated exhaust aftertreatment systems. Stakeholders must monitor NHTSA rulemaking on automated emergency braking mandates, as these provisions will determine whether electro-pneumatic or fully electric actuator architectures prevail in next-generation commercial vehicle platforms.
Market Dynamics
NHTSA brake performance mandates and EPA emissions standards are compressing validation cycles for pneumatic actuator suppliers serving Detroit-based OEM tier-ones, forcing simultaneous investment in electro-pneumatic architectures and heavy-duty pneumatic systems for commercial fleets.
Growth Catalysts
- Commercial Fleet Expansion:Heavy-duty brake and suspension procurement by fleet operators is accelerating demand for high-force pneumatic cylinders in Class 8 trucks and transit buses.
- NHTSA Safety Mandates:Automated emergency braking requirements for commercial vehicles are tightening specification thresholds for actuator response times and fail-safe positioning.
- Exhaust Aftertreatment:EPA greenhouse gas rules for heavy-duty trucks are expanding procurement of pneumatically actuated EGR valves and selective catalytic reduction systems.
Market Restraints
- Aluminum and Steel Input Volatility:Cylinder body and piston rod material costs fluctuate with commodity markets, compressing margin visibility for mid-tier suppliers.
- Electrification Substitution:Fully electric actuators are capturing share in light-duty powertrain applications where thermal and spark hazards are manageable.
- ISO 9001 Validation Burden:OEM qualification timelines extend 18-24 months, freezing out capital-constrained entrants from tier-one supply chains.
Strategic Opportunities
- Southeast Manufacturing Corridor:Japanese transplant assemblers in Tennessee, Alabama, and South Carolina favor compact pneumatic architectures for just-in-time chassis assembly.
- Predictive Maintenance Integration:Electro-pneumatic actuators with embedded sensor feedback are opening service revenue streams for condition-monitoring contracts.
- Hybrid Powertrain Positioning:Diaphragm actuators for clutch and throttle control bridge internal combustion and electrified architectures during the transition period.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-functional engineers fluent in pneumatic systems, sensor integration, and embedded software command premium wages in the Great Lakes region.
- Legacy System Integration:Retrofitting electro-pneumatic feedback into existing compressed air infrastructure requires custom manifold and valve block engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Pneumatic Actuators Market |
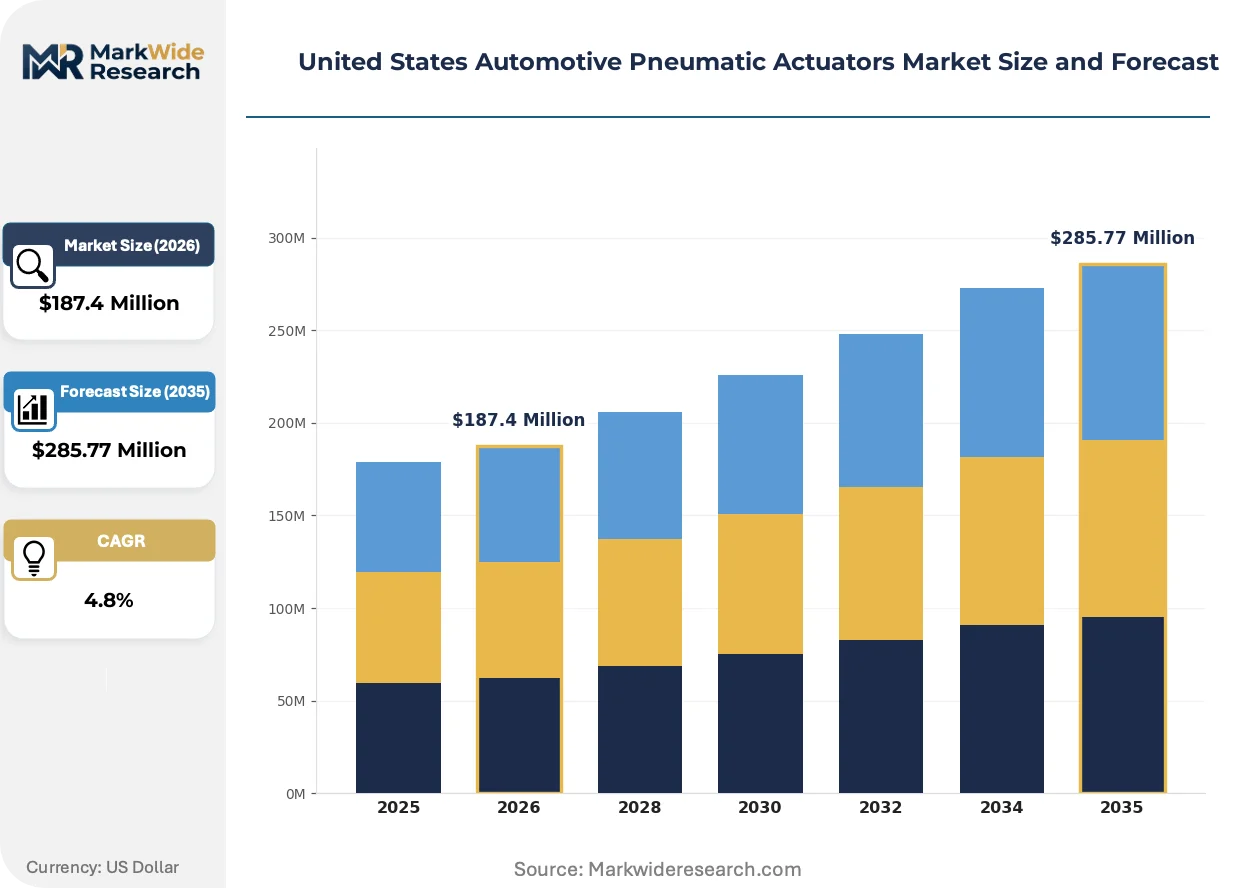
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Diaphragm Actuators, Pneumatic Cylinders Application: Fuel Systems, Brake Systems, Suspension Systems, Engine Components End User: OEMs, Aftermarket Providers, Commercial Fleets, Vehicle Assemblers Technology: Electro-Pneumatic, Manual Pneumatic, Mechanical Pneumatic, Digital Pneumatic |
| Companies Covered | Emerson Electric Co., SMC Corporation, Robert Bosch GmbH, BorgWarner, Hitachi Astemo Ltd, Continental AG, Parker Hannifin Corporation, Bosch Rexroth AG, Denso Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Pneumatic Actuators Market Evolving Landscape
Electro-pneumatic convergence is compressing the traditional boundary between fluid power and electronic control, with sensor-embedded actuators enabling predictive maintenance and real-time performance optimization across commercial and passenger vehicle platforms.
Smart diaphragm actuators with integrated pressure transducers and position feedback are integrating closed-loop control into throttle body and clutch applications. Tier-one suppliers serving hybrid powertrain programs are adopting these architectures at accelerating pace. The technology is integrating predictive maintenance protocols that were previously exclusive to fully electric systems.
NHTSA rulemaking on automated emergency braking mandates is forcing commercial vehicle suppliers to validate actuator response times below 150 milliseconds. The regulation is compressing development cycles for fail-safe pneumatic architectures. Heavy-duty brake system manufacturers in Michigan and Ohio are responding with redundant air supply circuits and faster-acting solenoid valves.
Fleet procurement teams are consolidating supplier relationships around integrated brake and suspension system providers rather than discrete component vendors. The distributor channel serving independent repair facilities is losing share to direct OEM service contracts. This concentration is most visible in long-haul trucking operations across the Interstate 80 and Interstate 95 corridors.
United States Automotive Pneumatic Actuators Market Segmentation
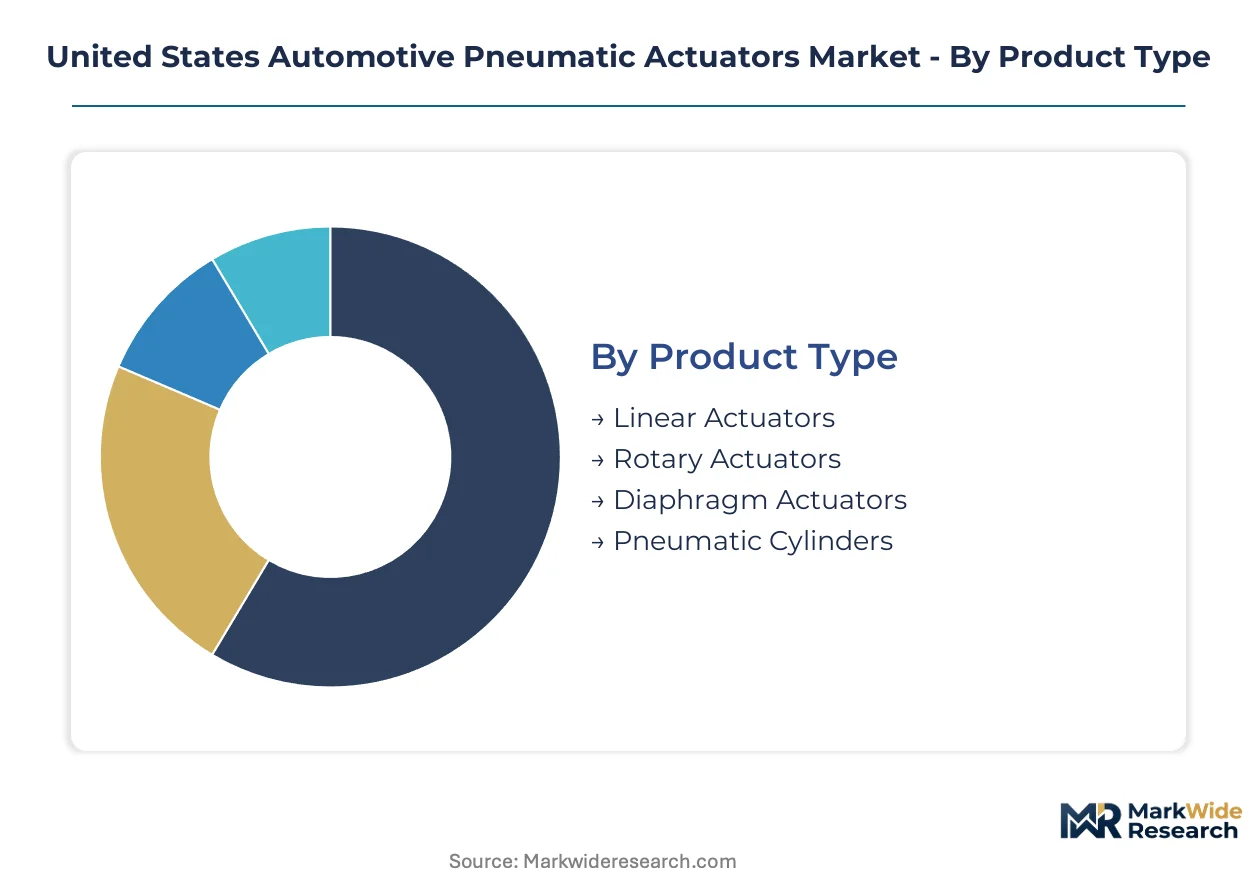
Pneumatic actuator procurement patterns diverge sharply across product architectures and customer tiers in the United States. OEM qualification requirements, fleet maintenance protocols, and electrification roadmaps each reshape how suppliers prioritize segment-specific development investments.
Product Type:
Technical specifications governing force density, stroke length, and fail-safe positioning separate architectures serving heavy-duty commercial applications from precision-engineered passenger vehicle systems.
- Linear Actuators:Rod-style and rodless configurations translate compressed air energy into straight-line motion for throttle linkages and clutch engagement mechanisms. Demand concentrates in Michigan-based powertrain tier-ones supplying Detroit OEMs with high-cycle-life units for automatic transmission valve bodies.
- Pneumatic Cylinders:Single-acting and double-acting cylinder architectures dominate heavy-duty brake and suspension applications where force-to-weight ratios exceed electromechanical alternatives. Procurement by Ohio-based commercial vehicle brake system integrators is accelerating under NHTSA automated emergency braking mandates.
- Rotary Actuators:Rack-and-pinion and vane-style rotary motion converters address limited-angle positioning requirements in exhaust gas recirculation valves.
- Diaphragm Actuators:Flexible membrane designs provide proportional control for clutch and throttle applications in hybrid powertrain transition architectures.
Pneumatic cylinders lead on scale; linear actuators lead on momentum.
Application:
Regulatory pressure points from EPA emissions rules and NHTSA safety standards concentrate procurement volume in systems where pneumatic actuation delivers unmatched response speed.
- Brake Systems:Air brake actuators, spring brake chambers, and slack adjusters constitute the largest addressable volume in Class 8 truck and transit bus platforms. Fleet operators across the Interstate 80 corridor are consolidating supplier relationships around integrated brake system providers offering predictive maintenance integration.
- Engine Components:Throttle body actuators, wastegate controllers, and variable geometry turbocharger mechanisms demand sub-100-millisecond response times. Indiana-based engine component suppliers are qualifying electro-pneumatic architectures with embedded position feedback for hybrid powertrain programs.
- Fuel Systems:Direct injection pressure regulators and fuel rail pressure control valves utilize compact pneumatic pilots.
- Suspension Systems:Air spring leveling valves and height control modules serve vocational truck and motorcoach applications.
Brake systems lead on scale; engine components lead on momentum.
End User:
Customer procurement authority determines whether suppliers pursue direct OEM qualification, tier-one integration partnerships, or aftermarket distribution channels.
- OEMs:Detroit Three automakers and Japanese transplant headquarters specify actuator performance envelopes, material certifications, and validation protocols that freeze out capital-constrained entrants. Direct relationships require 18-24 month qualification timelines and ISO 9001 quality system certification.
- Commercial Fleets:Long-haul trucking operators and transit authorities are shifting procurement toward integrated brake and suspension system contracts with predictive maintenance service riders. Fleet maintenance depots in the Great Lakes corridor favor standardized actuator architectures that minimize spare parts inventory complexity.
- Vehicle Assemblers:Contract manufacturing operations in the Southeast automotive corridor specify compact pneumatic architectures for just-in-time chassis assembly.
- Aftermarket Providers:Independent distributors serving repair facilities face margin compression as OEMs expand direct service contract coverage.
OEMs lead on scale; commercial fleets lead on momentum.
Technology:
Control methodology selection determines whether actuators operate as standalone pneumatic devices or as sensor-integrated nodes within vehicle electronic architectures.
- Electro-Pneumatic:Solenoid-driven valve blocks with integrated pressure transducers and position feedback enable closed-loop control and predictive maintenance protocols. Tier-one suppliers serving hybrid powertrain programs in Michigan and Ohio are adopting these architectures at accelerating pace.
- Manual Pneumatic:Pilot-operated and direct-acting designs without electronic control persist in cost-sensitive aftermarket replacement and legacy fleet maintenance applications.
- Mechanical Pneumatic:Cam-operated and linkage-driven actuation survives in specialized off-highway equipment where electronic infrastructure is limited.
- Digital Pneumatic:Fieldbus-integrated smart actuators with embedded diagnostics are emerging in premium commercial vehicle platforms.
Manual pneumatic leads on scale; electro-pneumatic leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechatronics engineers fluent in pneumatic systems, sensor integration, and embedded software command premium wages across the Great Lakes automotive corridor, anchoring the industry's geographic concentration.
Great Lakes Manufacturing Corridor
Michigan-based powertrain tier-ones and Ohio commercial vehicle brake system integrators drive procurement of high-cycle-life linear actuators and heavy-duty pneumatic cylinders. NHTSA automated emergency braking mandates compress qualification timelines for suppliers serving Detroit-based OEMs. Industrial clusters in Detroit, Toledo, and Cleveland concentrate electro-pneumatic development for hybrid powertrain transition architectures.
Southeast Automotive Corridor
Japanese transplant assemblers in Tennessee, Alabama, and South Carolina favor compact pneumatic cylinder architectures for just-in-time chassis assembly operations. SMC Corporation sustains dominance in this geography through localized supply relationships. Huntsville and Nashville manufacturing hubs specify standardized actuator platforms that minimize spare parts inventory complexity for regional vehicle assembly.
Southwest Industrial Zone
Texas-based oilfield service vehicle manufacturers and Mexico-crossing commercial fleet operators generate demand for heavy-duty air brake actuators and suspension leveling systems. EPA greenhouse gas rules for heavy-duty trucks expand procurement of pneumatically actuated exhaust aftertreatment systems. Dallas-Fort Worth logistics hubs consolidate supplier relationships around integrated brake system providers with predictive maintenance service riders.
Pacific Northwest Technology Cluster
Seattle-area autonomous vehicle testing programs and Portland-based electric vehicle startups pilot electro-pneumatic architectures with embedded sensor feedback for predictive maintenance protocols. Washington State clean transportation incentives accelerate qualification of smart diaphragm actuators for hybrid powertrain applications. Vancouver-Portland corridor engineering centers recruit cross-functional talent from aerospace and marine pneumatic control sectors.
United States Automotive Pneumatic Actuators Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the United States automotive pneumatic actuators market. The supplier base organizes into three tiers: integrated motion control conglomerates with captive distribution networks, specialized pneumatic component manufacturers serving regional transplant assemblers, and commodity cylinder fabricators competing on aftermarket replacement volume. Dominant competitive moves include backward integration into aluminum extrusion and precision machining capabilities, plus strategic partnerships with commercial fleet operators seeking predictive maintenance integration.
Within the integrated motion control tier, Emerson Electric Co. and Parker Hannifin Corporation exemplify fluid power conglomerates leveraging distribution infrastructure to anchor OEM tier-one relationships. SMC Corporation represents the specialized pneumatic component archetype, occupying a position among Japanese-origin manufacturers serving Southeast transplant assembly operations. Bosch Rexroth AG and Continental AG sit within the European-headquartered multinational tier, competing through technology licensing arrangements and regional engineering support centers.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| SMC Corporation |
| Robert Bosch GmbH |
| BorgWarner |
| Hitachi Astemo Ltd |
| Continental AG |
| Parker Hannifin Corporation |
| Bosch Rexroth AG |
| Denso Corporation |
| Others |
Value Network & Pricing Analysis
EPA greenhouse gas compliance mandates for heavy-duty trucks gate access to premium-tier electro-pneumatic actuator contracts, compressing qualified supplier pools and stratifying pricing power between certified tier-ones and commodity aftermarket fabricators. Fleet procurement consolidation around integrated brake system providers rewards bundled predictive maintenance offerings with margin premiums while squeezing discrete component vendors.
Pricing Analysis
Bundled service contracts incorporating predictive maintenance riders command 15-25% premiums over unbundled hardware transactions across commercial fleet procurement. Pricing stratifies across NHTSA-certified, ISO 9001-compliant, and economy aftermarket tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in commodity pneumatic cylinders intensifies as aluminum extrusion input volatility squeezes mid-tier fabricators. Aftermarket distributors serving independent repair facilities exhibit highest price sensitivity; OEM direct service contracts show lowest.
Supply Chain Analysis
Domestic-content requirements under Buy America provisions reshape sourcing patterns for federally funded transit bus procurement, favoring Michigan and Ohio-based machining operations over offshore component supply. Manufacturing concentration centers on the United States, Mexico, and Japan for precision-actuation subassemblies. Raw material dependencies span aluminum extrusions, specialty steel alloys, and fluoropolymer diaphragm membranes. Single-source vulnerability in precision-machined valve blocks represents structural risk. Distribution runs through captive OEM tier-one networks and consolidated fleet service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States automotive pneumatic actuators market functions as a geographic-arbitrage play where NHTSA validation timelines in Michigan-Ohio corridor compress development costs versus Southeast transplant markets demanding premium-priced compact architectures.
For Market Incumbents: To counter electrification substitution in light-duty powertrain applications, anchor Detroit OEM relationships through captive distribution networks while deepening backward integration into aluminum extrusion capabilities. Prioritize ISO 9001 certification maintenance to freeze out capital-constrained challengers from tier-one supply chains. For New Entrants and Emerging Players: Enter via the Southwest Industrial Zone oilfield service vehicle segment where heavy-duty air brake demand outruns established supplier coverage. Target Texas-based fleet operators seeking predictive maintenance integration with unbundled hardware-plus-software offerings. Pursue direct commercial fleet contracts rather than OEM qualification pathways. For Investors and Strategic Acquirers: Roll-up economics work for regional pneumatic component specialists because NHTSA brake mandate compression extends qualification timelines beyond private-equity holding periods. Five-to-ten-year viability hinges on electro-pneumatic sensor integration capabilities. Monitor EPA heavy-duty truck rulemaking velocity as inflection signal for exhaust aftertreatment actuator demand.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Pneumatic Platform Integration | Embedded sensor feedback enables predictive maintenance contracts with commercial fleet operators across Interstate 80 corridors. |
| Backward Integration into Aluminum Extrusion | In-house production of cylinder bodies insulates margin visibility from commodity price volatility affecting mid-tier competitors. |
| NHTSA Certification Fast-Track Investment | Compressed validation timelines for automated emergency braking mandates secure tier-one positioning with Detroit OEMs. |
| Southeast Manufacturing Footprint Expansion | Localized supply relationships with Tennessee and Alabama transplant assemblers capture compact pneumatic cylinder demand. |
| Hybrid Powertrain Diaphragm Development | Proportional control architectures bridge internal combustion and electrified platforms during extended transition period. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, commercial fleet maintenance directors, and aftermarket distribution heads grounded qualitative findings in operational reality. Secondary validation drew from NHTSA rulemaking dockets, EPA emissions compliance filings, vehicle production databases, and SEC disclosures from motion control conglomerates. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segment-level projections across product type, application, end user, and technology dimensions fed into analytical framework spanning the projection horizon. CAGRs derived from regression against vehicle production forecasts, regulatory mandate implementation schedules, and fleet replacement cycle patterns. Propulsion architecture transition curves and content-per-vehicle assumptions for brake, engine, and suspension systems served as core forecast inputs.
Inputs from NHTSA, EPA, and OEM production planning sources were available through the study window; gaps in commercial fleet maintenance contract terms introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions regarding electrification substitution rates and regulatory implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automobile Accessories Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
France Automotive Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Automotive Fender Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Automotive Key Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Pressure Plate Market