
 Remote Automotive Exhaust Sensing Market | 2026-2036
Remote Automotive Exhaust Sensing Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Automotive Exhaust Sensing Market Analytics
Euro 7 emission standards is expanding the cost-of-entry calculus for exhaust sensing suppliers, forcing investments in wireless telemetry and cloud-validated measurement protocols. Robert Bosch GmbH leverages its integrated sensor-to-ECU architecture to dominate European OEM channels. Continental AG sustains competitive positioning through MEMS fabrication scale across German production lines. PHINIA Inc. specializes in NOx sensing modules calibrated for heavy-duty fleet retrofit applications.
Remote automotive exhaust sensing deploys non-contact optical, infrared, or ultrasonic transducers to quantify O2, NOx, particulate, and pressure signatures without physical probe insertion into the exhaust stream, achieving measurement accuracy within milliseconds while eliminating sensor degradation from corrosive exhaust gases. The technology serves emission monitoring, compliance testing, and predictive engine diagnostics across vehicle platforms. NOx sensors command the largest product-type revenue pool due to Euro 7 and EPA Tier 3 enforcement stringency, while optical sensors represent the fastest-expanding technology segment as solid-state photonic arrays displace electrochemical cells. Fleet operators constitute the most concentrated end-user margin pool, driven by telematics-integrated regulatory reporting mandates.
EPA, Euro 7, and Japan's Ministry of Land, Infrastructure, Transport and Tourism (MLIT) shape product certification pathways, test-cycle definitions, and cross-border homologation requirements for remote exhaust sensing hardware. The EU AI Act and GDPR impose additional constraints on automated emission data processing and cross-border fleet telemetry flows. Stakeholders must monitor regulatory divergence between California Air Resources Board pilot programs and federal EPA rulemaking to anticipate validation cost shifts and regional product specification splits.
Market Dynamics
Optical sensing architectures are compressing validation cycles and eroding the installed base of wired probe systems across OEM and aftermarket channels.
Growth Catalysts
- Euro 7 stringency:The European emission framework mandates real-time NOx monitoring, forcing fleet operators toward remote sensing infrastructure.
- MEMS fabrication scale:German production lines now output solid-state pressure transducers at unit economics that undercut electrochemical alternatives.
- Heavy-duty retrofit demand:North American freight operators face EPA enforcement deadlines, accelerating hardware procurement for existing vehicle pools.
Market Restraints
- Photonic component concentration:Infrared laser diodes and avalanche photodiodes depend on Japanese and Taiwanese substrate suppliers, exposing OEMs to single-source fragility.
- GDPR telemetry friction:Cross-border fleet data flows face consent and anonymization requirements that delay cloud-validated measurement deployment.
- Inductive power limits:Wireless energy transfer to exhaust-mounted sensors caps operating temperature ranges below what corrosive high-load streams demand.
Strategic Opportunities
- India commercial vehicle enforcement:The country's national automotive regulator is piloting remote sensing at inspection stations, creating first-mover positioning for calibrated module suppliers.
- Predictive diagnostics convergence:Integration of exhaust signatures with engine control unit telemetry enables prognostic maintenance contracts.
- California Air Resources Board pilot programs:State-level rulemaking precedes federal EPA adoption, offering validation pathway advantages for compliant hardware.
Industry Challenges
- Photonics integration talent scarcity:Packaging solid-state arrays for 150°C exhaust proximity requires rare optomechanical engineering competencies concentrated in German and Japanese supplier bases.
- Homologation timeline compression:Euro 7 test-cycle definitions remain under revision, forcing parallel certification tracks that duplicate engineering expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Automotive Exhaust Sensing Market |
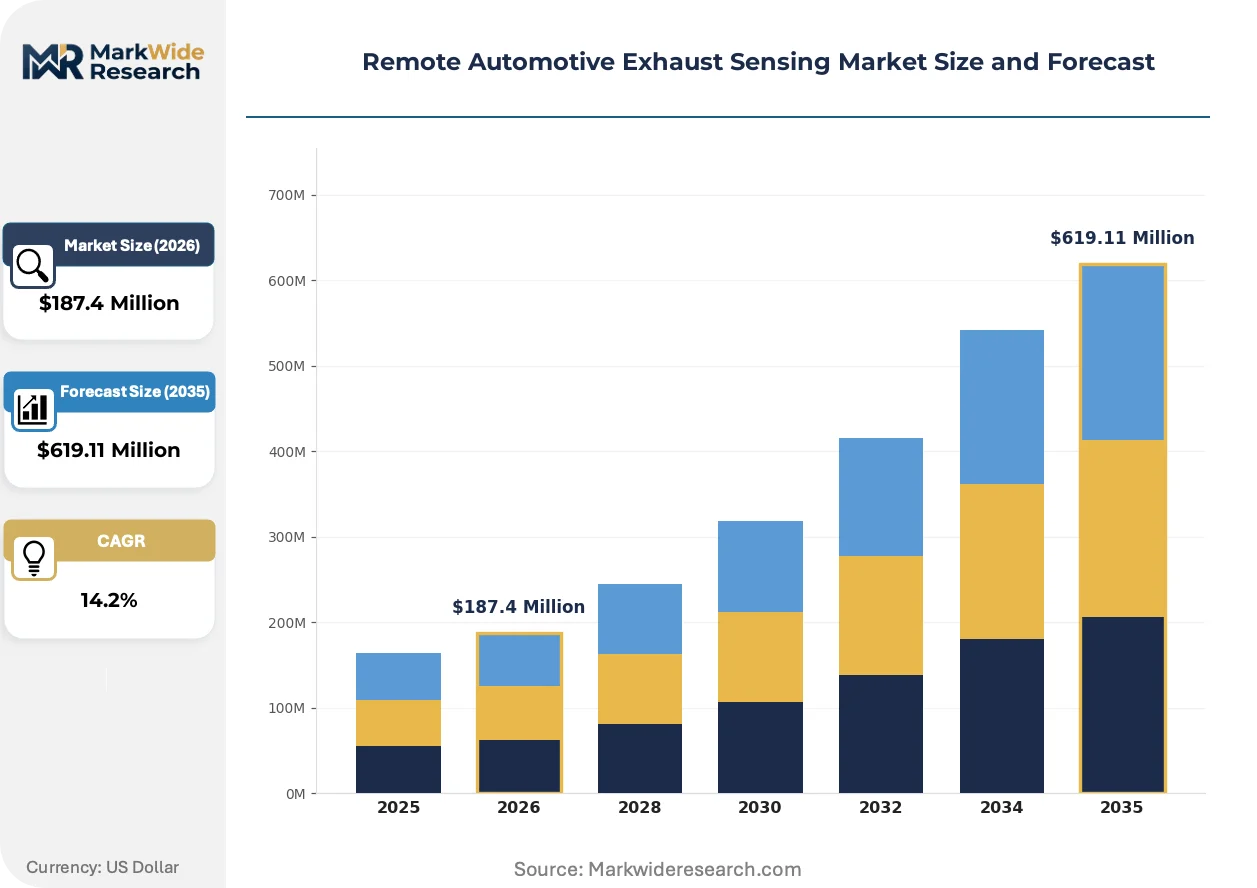
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O2 Sensors, NOx Sensors, Exhaust Flow Sensors, Pressure Sensors Technology: Infrared Sensing, Ultrasonic Technology, MEMS, Optical Sensors Application: Emission Monitoring, Performance Tuning, Compliance Testing, Engine Diagnostics End User: OEMs, Tier-1 Suppliers, Aftermarket Installers, Fleet Operators |
| Companies Covered | Robert Bosch GmbH, Continental AG, PHINIA Inc., Denso Corporation, Sensata Technologies, Honeywell, Valeo SA, AVL List GmbH, Hager Environmental & Atmospheric Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Automotive Exhaust Sensing Market Evolving Landscape
Measurement modality migration, regulatory data architecture mandates, and fleet procurement centralization are restructuring competitive requirements across hardware and service layers.
Solid-state photonic arrays are overtaking electrochemical NOx cells in European OEM validation programs. Tier 1 suppliers now specify non-contact infrared absorption spectroscopy for prototype testing, compressing sensor replacement intervals from months to years. The shift is collapsing aftermarket service revenue pools while expanding upfront hardware margins.
EPA and Euro 7 are mandating encrypted, timestamped emission data streams for regulatory audit trails. Hardware suppliers must embed secure element chips and blockchain-anchored certificates, transforming sensor units into connected compliance endpoints. Fleet telematics providers in Germany and the United States are absorbing this functionality to defend platform stickiness.
Consolidated procurement through fleet management companies is fragmenting direct OEM sensor relationships. Large freight operators now specify hardware through telematics integrators, compressing supplier visibility into end-use specifications. This channel shift is most pronounced in North American long-haul segments where asset managers control specification authority.
Remote Automotive Exhaust Sensing Market Segmentation
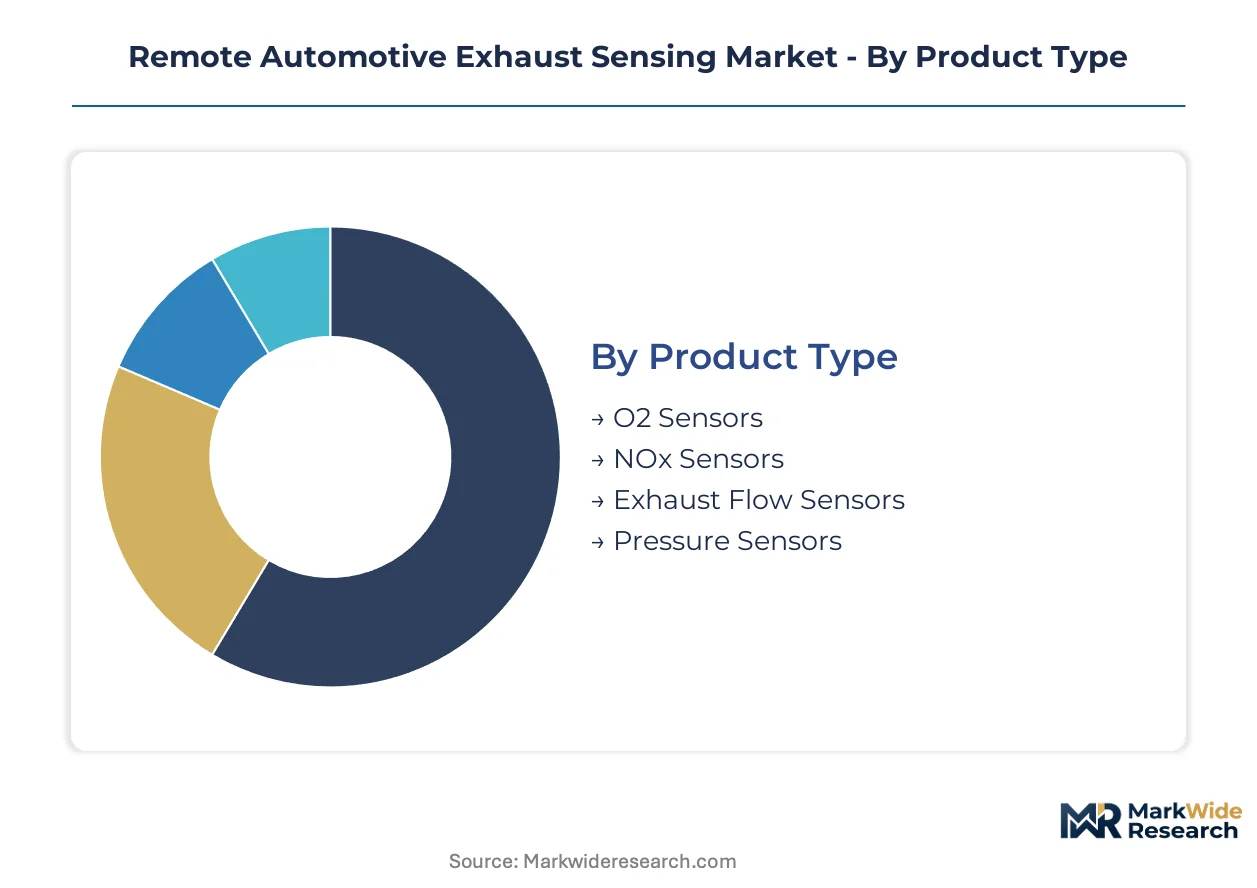
Segmentation in remote automotive exhaust sensing reveals how regulatory pressure and technology substitution reshape procurement patterns across hardware categories. Understanding where demand concentrates by product type, technology, and end-user channel exposes margin pressure points and investment priorities for suppliers navigating Euro 7 and EPA compliance cycles.
Product Type:
Supply concentration in NOx and O2 sensing modules dominates OEM procurement volumes, with foundry capacity for ceramic substrates and precious metal electrodes limiting qualified supplier pools.
- NOx Sensors:Electrochemical cells measuring nitrogen oxide concentrations through zeolite-based sensing elements face displacement by solid-state photonic alternatives. German OEM validation programs and California Air Resources Board pilot fleets drive procurement concentration, though Euro 7 test-cycle uncertainty delays final specification lock.
- O2 Sensors:Zirconia-based wideband lambda probes remain the highest-volume category due to universal gasoline and diesel engine requirements. Japanese substrate suppliers control stabilized zirconia supply, creating single-source exposure for module integrators serving EPA Tier 3 enforcement markets.
- Exhaust Flow Sensors:Thermal mass flow measurement for EGR and SCR dosing control.
- Pressure Sensors:Differential pressure monitoring across diesel particulate filters and SCR catalysts.
Today's leader: NOx Sensors. Tomorrow's challenger: O2 Sensors.
Technology:
Cost tier differentiation separates MEMS fabrication scale from optical sensing premium positioning, with infrared architectures commanding validation timeline advantages.
- Optical Sensors:Non-contact infrared absorption spectroscopy eliminates probe degradation from corrosive exhaust streams. Solid-state photonic arrays from German and Japanese suppliers compress replacement intervals while satisfying encrypted data stream mandates from EPA and Euro 7 regulators.
- MEMS:Micro-electromechanical pressure and flow transducers leverage semiconductor fabrication economics. German production lines achieve unit costs that undercut electrochemical alternatives for fleet retrofit applications facing EPA enforcement deadlines.
- Infrared Sensing:Tunable diode laser absorption spectroscopy for remote plume measurement.
- Ultrasonic Technology:Time-of-flight exhaust flow measurement without flow restriction.
Optical Sensors are gaining share fastest in European OEM channels. MEMS dominates North American heavy-duty retrofit procurement.
Application:
Customer type segmentation shows fleet operators consolidating procurement authority while OEMs fragment specification across platform variants.
- Emission Monitoring:Continuous regulatory compliance measurement with encrypted, timestamped data streams for EPA and Euro 7 audit trails. Fleet telematics providers in Germany and the United States embed secure element chips to defend platform stickiness.
- Compliance Testing:Periodic verification for vehicle registration and roadside enforcement. India's national automotive regulator pilots remote sensing at inspection stations, creating first-mover positioning for calibrated module suppliers.
- Engine Diagnostics:Predictive maintenance through exhaust signature analysis integrated with ECU telemetry.
- Performance Tuning:Aftermarket optimization of air-fuel ratios and boost pressure.
Fleet procurement centralization favors Emission Monitoring. Aftermarket fragmentation sustains Performance Tuning margins.
End User:
Volume concentration in Tier-1 supplier channels masks specification authority migration toward fleet management companies and telematics integrators.
- Fleet Operators:Consolidated freight and logistics procurement through asset managers controlling specification authority. North American long-haul segments show pronounced channel shift as telematics integrators absorb sensor selection decisions.
- Tier-1 Suppliers:Module integration for OEM platform supply with MEMS fabrication scale advantages. Robert Bosch GmbH and Continental AG dominate European channels through sensor-to-ECU architecture control.
- OEMs:Direct specification for new vehicle platforms with extended validation cycles.
- Aftermarket Installers:Retrofit hardware distribution for independent service channels.
Current procurement gravity: Tier-1 Suppliers. Emerging specification authority: Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive exhaust sensing standardization through its KBA certification framework, establishing the technical foundation that shaped Euro emission protocols and sensor validation methodologies now adopted across multiple jurisdictions.
Germany
Stuttgart and Munich host concentrated OEM validation facilities where solid-state photonic arrays undergo Euro 7 pre-certification. KBA mandates encrypted data streams for NOx monitoring, compressing supplier qualification timelines. Baden-Württemberg production lines now output MEMS pressure transducers at unit economics that undercut electrochemical alternatives for fleet retrofit channels.
United States
Detroit's Tier-1 corridors and California's emissions testing clusters drive divergent procurement patterns. EPA Tier 3 enforcement deadlines accelerate heavy-duty freight operator hardware procurement, while CARB pilot programs in Los Angeles and Sacramento create validation pathway advantages for compliant hardware suppliers ahead of federal rulemaking adoption.
Japan
Tokyo and Nagoya anchor substrate supply chains for stabilized zirconia and infrared laser diodes that module integrators depend upon. METI and MLIT coordinate test-cycle definitions with Euro 7 frameworks, reducing homologation duplication for suppliers serving both markets. Kyushu fabrication facilities concentrate avalanche photodiode production for optical sensing architectures.
India
Maharashtra and Tamil Nadu commercial vehicle corridors face tightening enforcement from the national automotive regulator's remote sensing pilot programs at inspection stations. Delhi-NCR air quality mandates create immediate retrofit demand for calibrated NOx modules. Pune-based fleet operators now specify hardware through telematics integrators rather than direct OEM channels.
South Korea
Seoul Capital Area R&D clusters develop tunable diode laser absorption spectroscopy for export-oriented module suppliers. MFDS-aligned emission protocols for domestic commercial vehicle fleets lag Euro 7 stringency, creating a timing arbitrage for suppliers validating hardware first in European markets before Korean homologation.
Remote Automotive Exhaust Sensing Market Competitive Landscape
The competitive structure tilts toward integrated sensor-to-ECU architects with semiconductor fabrication scale. Tier-1 module integrators dominate European OEM channels through direct platform supply relationships, while specialized NOx sensing suppliers capture heavy-duty retrofit procurement in North America. Three archetypes define positioning: diversified automotive electronics conglomerates with MEMS foundry access, exhaust-specific sensing specialists with calibration IP, and telematics-integrated platform providers absorbing specification authority. Consolidation pressure intensifies through fleet procurement centralization and encrypted data stream mandates that favor integrated secure element capabilities.
Among German-based diversified suppliers, Robert Bosch GmbH and Continental AG occupy positions as integrated architects controlling sensor-to-ECU validation cycles. PHINIA Inc. exemplifies the exhaust-specific specialist archetype with concentrated positioning in heavy-duty fleet retrofit channels. Denso Corporation anchors Japanese substrate-to-module integration for optical sensing architectures serving Asian OEM validation programs. These three represent divergent strategic bets on whether fabrication scale, calibration specificity, or substrate supply security determines sustainable margin capture.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| PHINIA Inc. |
| Denso Corporation |
| Sensata Technologies |
| Honeywell |
| Valeo SA |
| AVL List GmbH |
| Hager Environmental & Atmospheric Technologies |
| Others |
Value Network & Pricing Analysis
Captive production of ceramic substrates and photonic arrays in German and Japanese facilities anchors supplier pricing power against electrochemical alternatives. Euro 7 encrypted data mandates force secure element integration that bundles hardware with compliance services, compressing pure component margins while expanding recurring revenue pools.
Pricing Analysis
The bundled hardware-plus-telemetry service split separates OEM validation programs from aftermarket retrofit procurement. Premium-mid-economy pricing differentiation tracks certification tier and encrypted data capability, with Euro 7-compliant modules commanding margin premiums over EPA Tier 3 equivalents. Cost compression in electrochemical cells is intensifying because MEMS fabrication scale achieves unit economics below ceramic substrate alternatives. Fleet operators show highest price sensitivity due to consolidated volume procurement, while OEM platform engineers prioritize validation timeline certainty over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German and US platform engineering teams, while telematics integrators absorb specification authority for North American heavy-duty retrofit pools. Stabilized zirconia supply draws from Japanese substrate suppliers, with infrared laser diodes and avalanche photodiodes sourced from Taiwanese foundries. Single-source vulnerability in photonic component supply exposes module integrators to substrate allocation constraints. Distribution runs through Tier 1 module suppliers with sensor-to-ECU architecture control, though fleet management companies now intermediate hardware selection in consolidated procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in remote exhaust sensing rests on MEMS cost-down curves displacing electrochemical alternatives, while encrypted data service tiers capture recurring revenue above hardware depreciation cycles.
For Market Incumbents: Lock in sensor-to-ECU architecture control through calibration IP investments that resist photonic array substitution. Secure ceramic substrate supply agreements with Japanese suppliers before allocation constraints tighten. Backward integration into MEMS fabrication capacity defends cost position against emerging German competitors. For New Entrants and Emerging Players: The premium-to-economy price-point gap in heavy-duty fleet retrofit channels offers white-space entry below Bosch and Continental validation premiums. India's inspection station pilot programs present the most penetrable geography with first-mover positioning for calibrated module suppliers. Target telematics integrator partnerships rather than direct OEM channel development. For Investors and Strategic Acquirers: Roll-up economics work for exhaust-specific sensing specialists because Euro 7 homologation timelines compress and duplicate engineering expenditure favors consolidated calibration IP portfolios. Target acquisition archetypes include NOx module suppliers with heavy-duty fleet retrofit relationships and photonic array packagers with 150°C optomechanical competencies. Watch CARB pilot program adoption rates as inflection signal for federal EPA rulemaking convergence.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Scale-Up | Semiconductor unit economics undercut electrochemical alternatives for EPA enforcement deadlines. |
| Secure Element Integration | Encrypted data streams satisfy Euro 7 audit trail mandates and defend platform stickiness. |
| Telematics Platform Partnership | Fleet procurement centralization shifts specification authority toward integrator channels. |
| Photonic Array Certification | Solid-state validation compresses replacement intervals from months to years. |
| India Market Entry | National automotive regulator pilots create first-mover positioning for calibrated suppliers. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, fleet telematics directors, and aftermarket distribution heads grounded qualitative assessment in operational constraints. Secondary validation drew from EPA enforcement filings, Euro 7 regulatory drafts, vehicle production databases, and customs records for ceramic substrate trade flows. Bottom-up and top-down triangulation reconciled module shipment data with fleet installation estimates across the analysis window.
Bottom-up modeling tracked unit economics by technology architecture, while top-down approaches validated aggregate market size against OEM platform launch schedules and regulatory enforcement timelines. Segmentation dimensions included sensing modality, vehicle propulsion architecture, content per vehicle, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and compliance deadline clustering. Forecast inputs incorporated MEMS fabrication yield improvements and photonic array cost curves.
The model assumes a particular technology adoption path; alternative pathways for solid-state photonic displacement would alter the outlook if electrochemical cells achieve comparable encrypted data capability. Forecasts reflect assumptions regarding Euro 7 test-cycle finalization and EPA enforcement resource allocation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Regenerative Suspension System Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
China Automotive Composites Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Global Automotive Bumpers Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
Automotive Differential Market