
 Asia-Pacific AC Electric Motor Market | 2026-2036
Asia-Pacific AC Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific AC Electric Motor Market Outlook
Multi-source procurement for stator laminations and permanent magnet assemblies is expanding across the Asia-Pacific AC electric motor supply base. Toshiba Corporation leverages captive rare-earth sourcing partnerships to secure neodymium supply chains against price volatility. Wolong Electric Group anchors its competitive position through integrated manufacturing of both asynchronous and synchronous motor platforms for industrial automation clients. Nidec Corporation specializes in ultra-high-efficiency brushless designs that dominate EV traction motor nominations from Japanese and Korean automakers.
An Asia-Pacific AC electric motor converts alternating current electrical energy into mechanical rotation through electromagnetic induction between stator windings and a rotor assembly, typically operating at 50 Hz or 60 Hz grid frequencies with efficiency classes spanning IE1 through IE4 under IEC 60034 standards. These machines drive compressors, pumps, conveyors, and vehicle propulsion systems across industrial and consumer applications. Asynchronous motors retain volume leadership across manufacturing and HVAC end users due to simpler construction and lower capital cost, while brushless synchronous architectures capture margin pools in electric vehicle applications where power density and thermal management command premium pricing. The above 10 HP power rating band concentrates value in heavy industrial equipment and rail traction, though the 1-5 HP segment sustains broader unit volumes across commercial heating systems and material handling.
China's MIIT enforces GB 18613 efficiency mandates that phase out IE2 motors from industrial applications, directly reshaping replacement demand and manufacturer certification requirements. Japan's METI administers Top Runner standards that compel successive efficiency improvements across general-purpose and inverter-duty motor categories. India's BIS aligns with IEC frameworks while adding local testing protocols that condition market access for imported and domestic products alike. Stakeholders must monitor how China's dual carbon goals and India's PLI scheme for advanced manufacturing redistribute capacity investments and technology licensing patterns across the regional motor value chain.
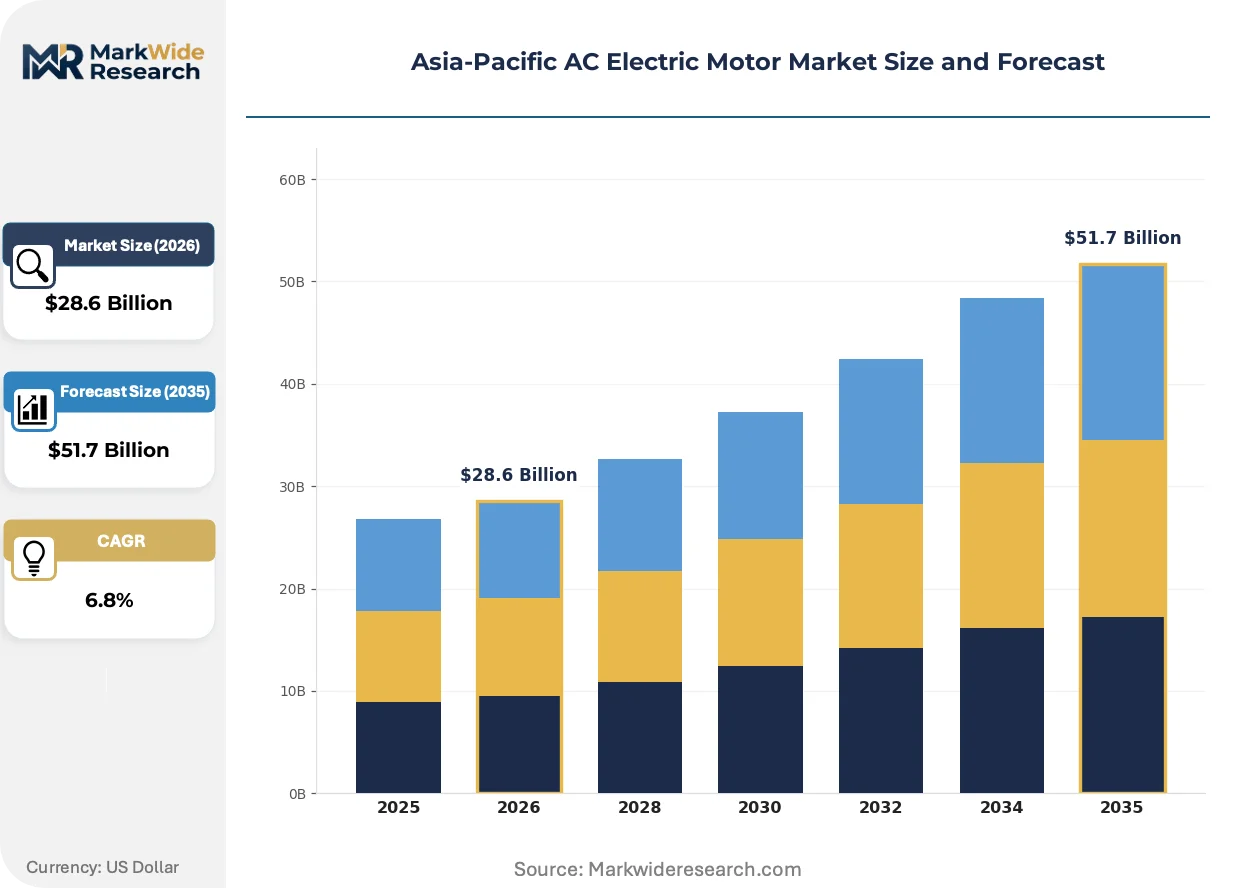
Market Dynamics
China's GB 18613 efficiency mandates are forcing a wholesale motor replacement cycle across Jiangsu and Zhejiang manufacturing clusters, compressing the installed base of IE2 equipment while accelerating IE3 and IE4 certification races among domestic suppliers.
Growth Catalysts
- EV Powertrain Electrification:Japanese and Korean automakers are expanding traction motor nominations for battery-electric platforms, pulling high-efficiency synchronous designs into mass production.
- India's BEE Standards:Tightening minimum energy performance standards across pump and compressor applications is compelling motor upgrades in Gujarat and Maharashtra industrial zones.
- Rare-Earth Magnet Integration:Permanent magnet rotor architectures are penetrating industrial automation lines where power density and thermal envelope constraints favor synchronous solutions over asynchronous alternatives.
Market Restraints
- Neodymium Price Volatility:Concentrated rare-earth processing in China's Baotou region creates input cost instability for permanent magnet motor manufacturers.
- IE3/IE4 Certification Burden:Extended testing protocols under IEC 60034 frameworks delay product launches and inflate R&D overhead for mid-tier suppliers.
- Copper Winding Cost Pressure:Electrification demand across grid infrastructure and EV charging is tightening copper supply, squeezing margin structures in the 1-5 HP segment.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Electronics assembly and textile automation in Bac Ninh and Hai Phong provinces remain underpenetrated for high-efficiency motor integration.
- India PLI Scheme:Production-linked incentives for advanced manufacturing are attracting motor capacity investments targeting domestic replacement and export markets.
- Digital Twin Integration:Predictive maintenance platforms converging with motor-drive systems are opening recurring revenue streams for condition-monitoring services.
Industry Challenges
- Magnet Thermal Management Expertise:Permanent magnet demagnetization risk at elevated temperatures requires scarce electromagnetic design talent, particularly for EV traction applications.
- Legacy Inverter Compatibility:Retrofitting IE4 motors into existing VFD-controlled systems demands harmonic mitigation engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific AC Electric Motor Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synchronous, Asynchronous, Brushless, Universal End User: Manufacturing, HVAC, Transportation, Consumer Electronics Power Rating: Below 1 HP, 1-5 HP, 6-10 HP, Above 10 HP Application: Industrial Equipment, Home Appliances, Electric Vehicles, Heating Systems |
| Companies Covered | Toshiba Corporation, Wolong Electric Group, ABB Ltd., Regal Beloit Corporation, TECO Electric & Machinery Co., Ltd., Nidec Corporation, WEG SA, Kirloskar Electric Co. Ltd., Siemens AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific AC Electric Motor Market Strategic Shifts
Electromagnetic design automation and materials science advances are compressing development cycles for next-generation motor platforms, while regulatory efficiency escalators and buyer procurement centralization reshape competitive positioning across the Asia-Pacific supply base.
Hairpin winding technology is automating stator coil formation for high-slot-fill configurations that boost power density in traction and servo applications. Korean battery production line builders are adopting these architectures at scale for robotic handling systems. The technology is automating labor-intensive winding processes that previously constrained output in the 10-100 HP range.
China's MIIT enforcement of GB 18613-2020 is phasing IE2 motors from industrial applications ahead of original timelines, forcing certificate renewals and production line requalifications. Domestic manufacturers in Ningbo and Changzhou are accelerating IE3 platform transitions to maintain state procurement eligibility. The regulation most heavily impacts pump and compressor OEMs supplying municipal water infrastructure.
Consolidated procurement by automotive tier-one suppliers is displacing fragmented distributor networks across Japanese and Korean EV supply chains. Direct sourcing agreements now govern permanent magnet motor nominations, compressing margin pools for traditional channel intermediaries. This concentration is most visible in South Korea's Gyeonggi-do cluster, where Hyundai-Kia suppliers negotiate multi-year volume contracts with Nidec and comparable specialists.
Asia-Pacific AC Electric Motor Market Segmentation
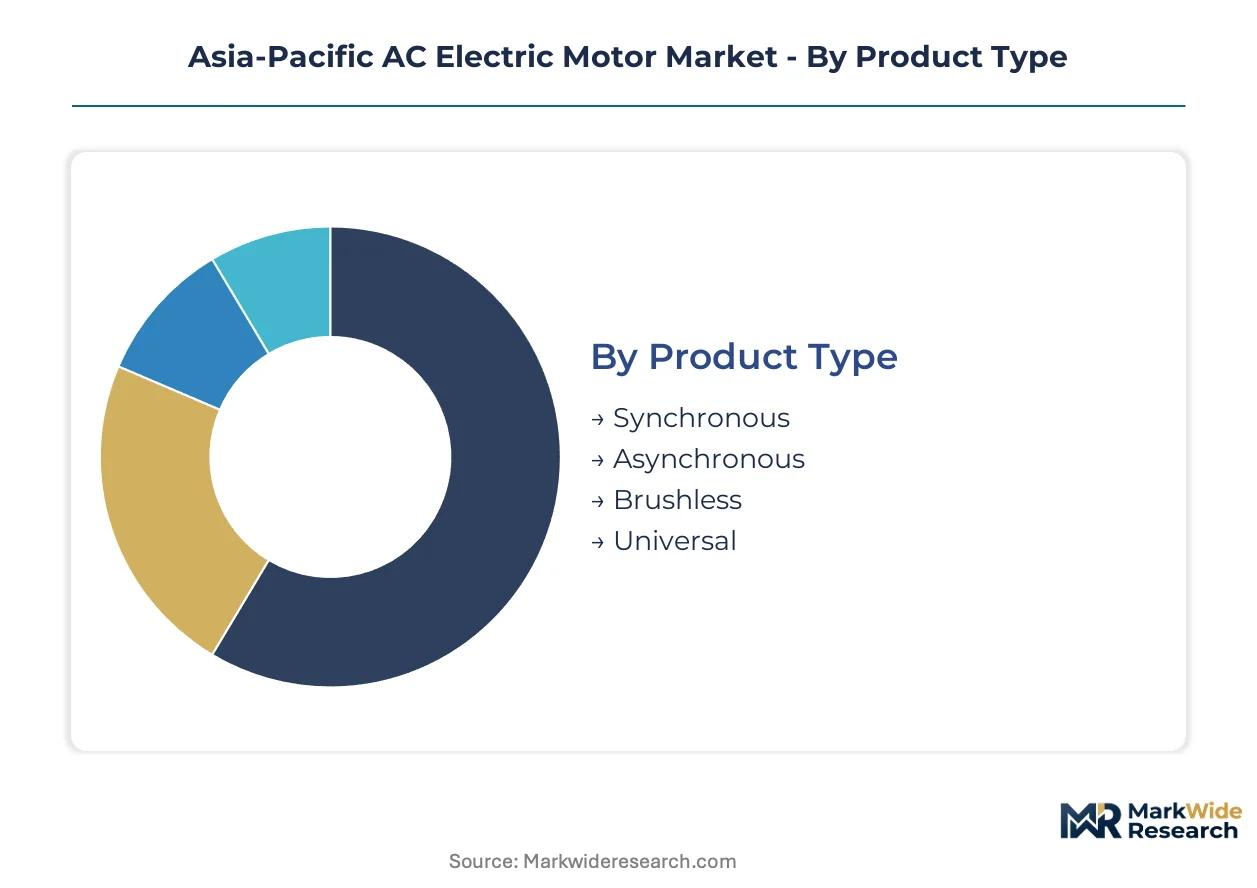
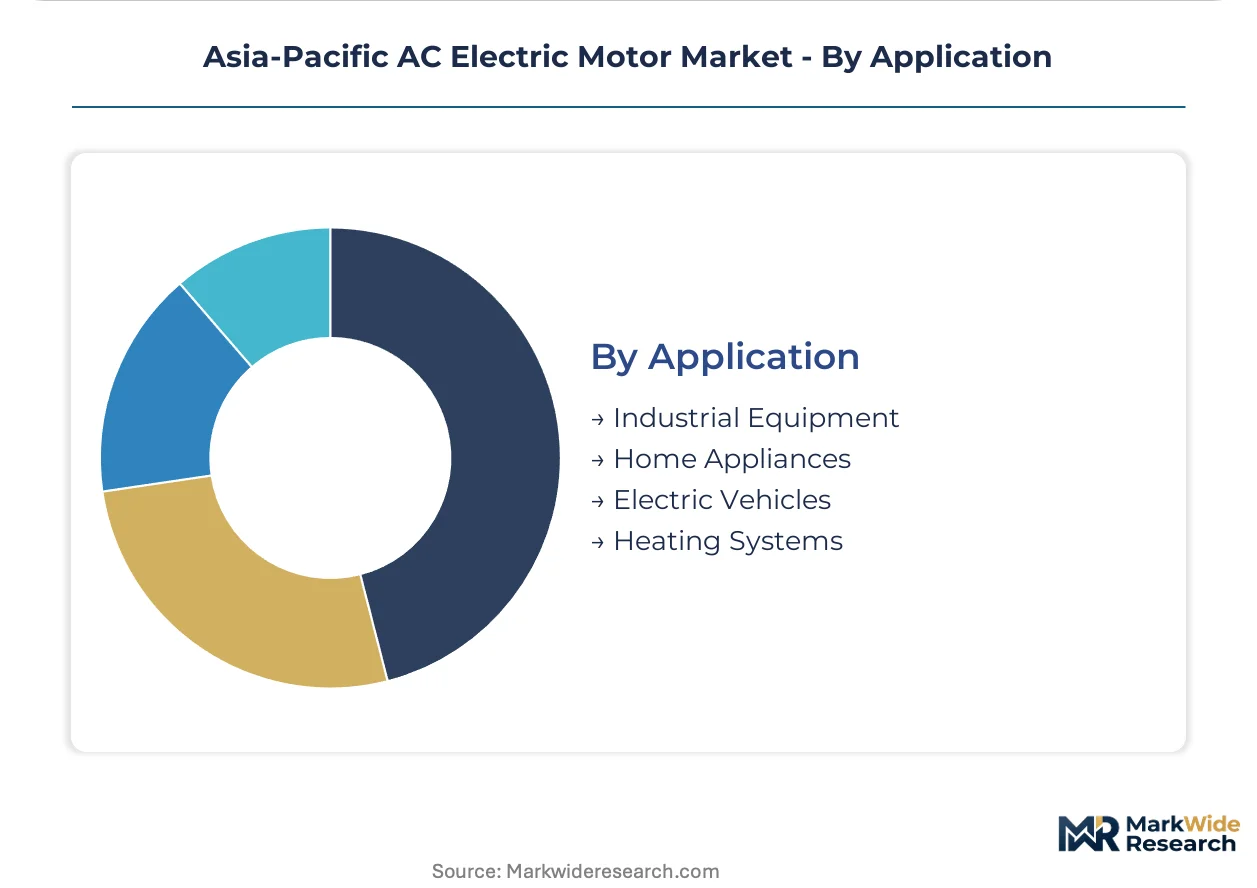
Segmentation in the Asia-Pacific AC electric motor market reveals how efficiency mandates and electrification priorities redistribute demand across motor architectures and power classes. Procurement patterns diverge sharply between industrial replacement cycles and EV platform nominations.
Product Type:
Integration depth varies substantially across motor architectures, with standalone industrial drives contrasting against embedded traction systems requiring thermal co-design with battery packs.
- Synchronous:Permanent magnet rotor designs achieve power densities exceeding 5 kW/kg through neodymium-iron-boron magnet arrays. Korean automakers in Gyeonggi-do province specify these for battery-electric traction, though magnet thermal demagnetization risks demand specialized cooling circuits.
- Asynchronous:Squirrel-cage induction construction dominates Jiangsu and Zhejiang manufacturing floors due to ruggedness and inverter compatibility. China's GB 18613-2020 efficiency mandates are accelerating IE3 transitions in this category, compressing replacement timelines for pump and compressor OEMs.
- Brushless:Electronically commutated architectures eliminate slip rings and brushes, reducing maintenance intervals for HVAC fan applications across Japanese commercial building retrofits.
- Universal:Series-wound designs with commutator assemblies persist in cost-sensitive home appliance niches where speed control via phase-angle trimming suffices.
Volume placements concentrate in Asynchronous; the faster expansion belongs to Synchronous.
End User:
Customer procurement maturity spans from centralized automotive tier-one negotiations to fragmented industrial distributor networks, reshaping margin capture across the value chain.
- Manufacturing:Industrial automation lines in Ningbo and Changzhou demand IE3-certified platforms for robotic handling and conveyor systems. China's MIIT enforcement is disqualifying IE2 equipment from state procurement, forcing certificate renewals.
- HVAC:Commercial heating and ventilation systems across Japan's METI Top Runner program specify inverter-duty motors with partial-load efficiency optimization. Chiller and air-handling unit OEMs in Osaka prefecture drive specification authority.
- Transportation:Railway traction and EV powertrain nominations pull high-efficiency synchronous designs into mass production, with direct sourcing agreements displacing traditional distribution channels.
- Consumer Electronics:White goods manufacturers in Vietnam's Bac Ninh electronics clusters specify compact induction motors for washing machines and refrigerators, prioritizing acoustic performance over peak efficiency.
Manufacturing commands the largest installed base; Transportation is climbing the fastest as electrification accelerates.
Power Rating:
Cost structures and copper intensity scale non-linearly across horsepower bands, with thermal management complexity escalating discontinuously above 10 HP thresholds.
- Below 1 HP:Fractional horsepower designs serve fan and pump auxiliaries in home appliances and small commercial equipment. India's BEE pump standards are tightening efficiency floors in this segment across Gujarat agricultural applications.
- 1-5 HP:Mid-range industrial workhorses power material handling and compressed air systems. Copper winding cost pressure from grid infrastructure electrification is squeezing margins in this high-volume band.
- 6-10 HP:Machine tool spindles and larger pump drives specify these platforms, with hairpin winding technology automating stator production for improved slot fill.
- Above 10 HP:Heavy industrial equipment and rail traction concentrate value here, requiring custom electromagnetic design and active thermal management that extends commissioning timelines.
The 1-5 HP band sustains broadest unit placements; Above 10 HP delivers steepest expansion trajectory as industrial automation and rail electrification advance.
Application:
Use-case thermal profiles and duty cycle requirements dictate motor architecture selection, with continuous-operation industrial loads contrasting against intermittent automotive traction demands.
- Industrial Equipment:Compressors, pumps, and conveyors in China's Jiangsu manufacturing belt specify IE3 and IE4 platforms under GB 18613 mandates. Continuous-duty thermal design prioritizes bearing life and winding insulation integrity.
- Home Appliances:Washing machines, refrigerators, and air conditioners across India and Southeast Asia specify cost-optimized induction designs with acoustic noise constraints driving stator slot geometry choices.
- Electric Vehicles:Battery-electric traction motors from Japanese and Korean OEMs demand power density and wide-speed-range efficiency that permanent magnet synchronous architectures uniquely deliver.
- Heating Systems:Boiler burners and heat pump compressors under Japan's METI efficiency programs specify inverter-compatible motors with partial-load optimization algorithms.
Industrial Equipment retains volume leadership; Electric Vehicles is gaining share fastest as platform nominations multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing in China's Baotou region anchors the Asia-Pacific AC electric motor supply base, concentrating permanent magnet feedstock for synchronous motor architectures across the region.
China
Industrial automation lines and EV battery production in Jiangsu and Zhejiang provinces drive synchronous motor demand. MIIT enforces GB 18613-2020 efficiency mandates that phase out IE2 motors from state procurement eligibility. Ningbo and Changzhou manufacturers accelerate IE3 platform certifications to retain municipal infrastructure contracts.
Japan
Automotive tier-one suppliers in Gyeonggi-do province nominate high-efficiency traction motors for battery-electric platforms. METI administers Top Runner standards compelling successive efficiency improvements across inverter-duty motor categories. Osaka prefecture chiller and air-handling unit OEMs drive specification authority for commercial HVAC applications.
India
Agricultural pump systems and manufacturing compressors in Gujarat and Maharashtra industrial zones require motor upgrades. BEE tightens minimum energy performance standards across pump and compressor applications. Domestic suppliers target PLI scheme incentives for advanced manufacturing capacity serving replacement and export markets.
South Korea
Hyundai-Kia suppliers negotiate multi-year volume contracts for EV traction motor nominations. Direct sourcing agreements displace traditional distribution channels across the Gyeonggi-do automotive cluster. Korean battery production line builders adopt hairpin winding architectures at scale for robotic handling systems.
Vietnam
Electronics assembly and textile automation in Bac Ninh and Hai Phong provinces remain underpenetrated for high-efficiency motor integration. White goods manufacturers specify compact induction motors prioritizing acoustic performance over peak efficiency. The electronics cluster offers expansion opportunity for IE3-certified platform suppliers.
Asia-Pacific AC Electric Motor Market Competitive Environment
Capacity expansion dominates the current landscape across the Asia-Pacific AC electric motor market. The supplier base organizes into three tiers: integrated conglomerates with captive rare-earth sourcing, mid-scale specialists focused on industrial automation, and regional fabricators serving replacement markets. Strategic archetypes include permanent magnet synchronous specialists, asynchronous induction generalists, and digital-integrated solution providers. M&A activity and backward integration into magnet supply chains constitute the dominant competitive moves reshaping positioning.
Among Japan-based specialists, Nidec Corporation occupies a position exemplifying ultra-high-efficiency brushless design concentration. Toshiba Corporation represents the integrated archetype through captive rare-earth sourcing partnerships. Wolong Electric Group anchors the Chinese tier through integrated manufacturing platforms serving industrial automation clients. These three entities collectively illustrate how geographic origin and structural integration determine competitive positioning across synchronous and asynchronous motor architectures.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Wolong Electric Group |
| ABB Ltd. |
| Regal Beloit Corporation |
| TECO Electric & Machinery Co., Ltd. |
| Nidec Corporation |
| WEG SA |
| Kirloskar Electric Co. Ltd. |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists across Ningbo and Changzhou anchor pricing discipline through captive stator lamination production, while their private-equity-rolled competitors unbundle after-sales service to recover margin on IE3 certification races. This ownership divergence concentrates supply-side bargaining power with magnet-integrated conglomerates, compressing price realization for distributors dependent on spot-market copper sourcing.
Pricing Analysis
Warranty and commissioning service bundles separate premium synchronous motor nominations from unbundled asynchronous replacements across Japanese automotive tier-one procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by efficiency class and magnet thermal management specification, with IE4-certified platforms commanding service-inclusive terms. Price erosion runs through the 1-5 HP segment as copper winding costs from grid infrastructure electrification squeeze fabricators lacking long-term cathode supply agreements. Small commercial HVAC contractors exhibit highest price sensitivity, while railway traction authorities prioritize lifecycle efficiency over first cost.
Supply Chain Analysis
GB 18613-2020 certification gates market access for imported and domestic platforms alike, conditioning procurement eligibility across China's municipal infrastructure sector. Rare-earth magnet processing concentrates in China's Baotou region and Malaysian separation facilities, with copper winding supply drawing from Chilean concentrate and Indonesian smelter output. Single-source vulnerability in neodymium-iron-boron magnet arrays threatens synchronous motor cost stability. Distribution runs through direct sourcing agreements with automotive tier-one suppliers, displacing fragmented industrial distributor networks across Japanese and Korean EV supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive magnet supply and hairpin winding automation determine cost position. Players pursuing backward integration into rare-earth separation or forward integration into digital-twin service platforms capture structural margin.
For Market Incumbents: To counter permanent magnet demagnetization risk at elevated temperatures, incumbents should deepen electromagnetic design talent pools through targeted acquisition of Korean traction motor specialists and expand hairpin winding capacity in Gyeonggi-do province to secure Hyundai-Kia nomination volume. Certification investment in IE4 platforms under China's GB 18613-2020 mandates preserves state procurement eligibility.
For New Entrants and Emerging Players: Vietnamese electronics assembly channel partners in Bac Ninh province offer the most penetrable white-space entry, as textile automation and white goods manufacturing remain underpenetrated for IE3-certified platform integration. Target India's PLI scheme beneficiaries in Gujarat pump applications for first volume placement, leveraging BEE standard tightening as a regulatory tailwind.
For Investors and Strategic Acquirers: Accelerated IE3 platform transitions by Ningbo manufacturers is the leading indicator that replacement cycle timing is compressing, signaling margin expansion opportunity for magnet-integrated specialists. Mid-scale asynchronous generalists with captive lamination capacity and established MIIT certification pathways represent optimal acquisition targets. A model refresh is warranted upon material change in China's dual carbon policy enforcement or neodymium price volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium sourcing insulates Nidec and Toshiba from Baotou price volatility. |
| Hairpin Winding Automation Deployment | Korean battery line builders adopt this architecture for robotic handling system density. |
| IE4 Certification Acceleration | MIIT enforcement of GB 18613-2020 disqualifies IE2 equipment from state contracts. |
| Digital Twin Platform Integration | Predictive maintenance services open recurring revenue streams for motor-drive systems. |
| Vietnam Manufacturing Footprint Expansion | Bac Ninh electronics clusters offer underpenetrated demand for IE3 platform suppliers. |
Study Parameters
Multi-period observation of MIIT enforcement timelines, BEE standard revision schedules, and neodymium price volatility anchored the trend analysis, supplemented by interviews with OEM procurement managers, tier-one supplier platform engineers, industrial maintenance directors, and aftermarket service heads. Primary fieldwork combined with secondary validation against IEC 60034 certification databases, Chinese customs trade data, Japanese METI efficiency program disclosures, and Indian PLI scheme beneficiary filings. Bottom-up segment sizing triangulated against top-down regional production capacity estimates.
Input-output matrices mapped motor architecture adoption across power rating bands and end-use applications, with volume and value outputs reflecting triangulated approaches across the projection horizon. Segmentation dimensions modeled include synchronous versus asynchronous versus brushless architectures, power rating tiers, and manufacturing versus transportation versus HVAC end-use categories. CAGRs derived from regression analysis of historical replacement cycles, regulatory phase-out schedules, and electrification platform nomination trajectories. Forecast inputs incorporated rare-earth magnet supply elasticity and copper winding cost pass-through assumptions.
Caveats apply where abrupt MIIT enforcement acceleration or neodymium supply disruption could materially shift the outlook beyond modeled trajectories. Forecasts reflect documented assumptions regarding regulatory timeline adherence and magnet thermal management technology diffusion. A model refresh is warranted upon material change in China's dual carbon policy stringency or Korean automotive platform electrification commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Vibrator Motor Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Fluid Conveyance Products Motors Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Voice Coil Motor Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market