
 Automotive Silicone Elastomer Market | 2026-2036
Automotive Silicone Elastomer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Silicone Elastomer Market Outlook
The gap between OEM direct procurement and aftermarket distribution is collapsing as vehicle electrification restructures supply relationships. Dow Inc. leverages its integrated silicone monomer-to-elastomer chain to secure long-term contracts with EV battery pack manufacturers. Wacker Chemie AG anchors its position through high-purity liquid silicone grades engineered for thermal management interfaces in power electronics. Shin-Etsu Chemical Co., Ltd. dominates Asian supply channels with vertically controlled methyl chlorosilane feedstock operations.
Automotive silicone elastomers are cross-linked polysiloxane polymers cured through platinum-catalyzed hydrosilylation or peroxide-initiated radical mechanisms, delivering continuous service temperatures from minus sixty to plus two hundred thirty degrees Celsius alongside dielectric stability and compression set resistance. Solid silicone compounds lead volume consumption in static sealing applications where durability under thermal cycling is paramount, while liquid silicone injection molding captures margin pools in complex geometric parts for sensor housings and connector seals. Extrusion technology sustains established positions in coolant hose and turbocharger ducting, though 3D printing of silicone prototypes is emerging as a tooling-cost reduction pathway for low-volume specialty vehicle programs.
EPA emission standards and NHTSA fuel economy regulations in the United States compel lighter material substitution in underhood applications, while REACH restrictions on phthalate plasticizers in Europe redirect formulation chemistry toward peroxide-cured silicone systems. China's GB standards for new energy vehicle safety specify flame-retardant elastomer performance thresholds that favor silicone over hydrocarbon alternatives in battery module assemblies. Stakeholders must monitor how evolving thermal interface material specifications across multiple regulatory jurisdictions reshape product development priorities and qualification timelines.
Market Dynamics
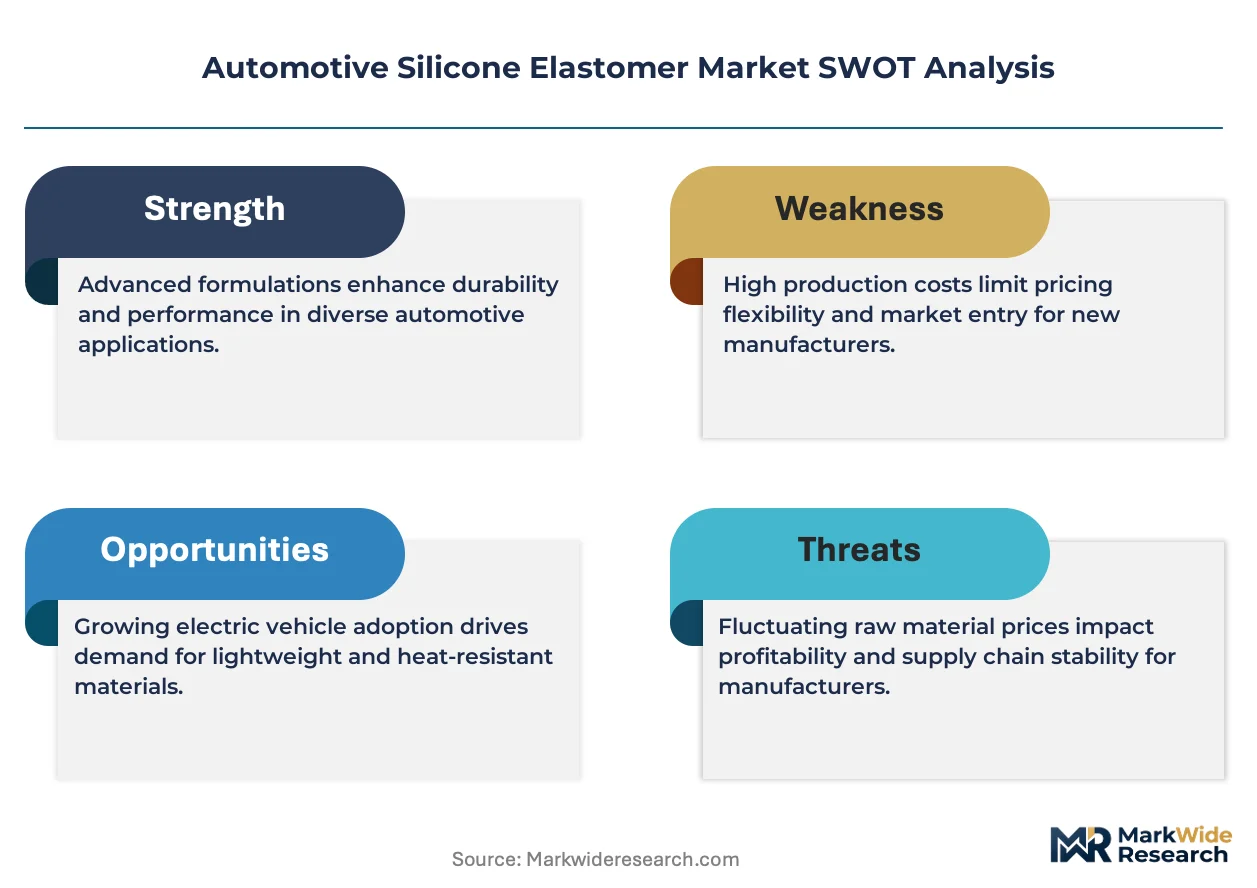
Vehicle electrification is collapsing the traditional boundary between powertrain sealing and thermal management, forcing silicone elastomer suppliers to requalify compounds for dual-function battery module applications under stricter thermal cycling protocols.
Growth Catalysts
- EU Green Deal material mandates:Brussels' sustainability requirements for recycled content in automotive components are accelerating silicone formulation redevelopment toward bio-based feedstocks and closed-loop manufacturing.
- Power electronics thermal interfaces:Silicon carbide inverter modules in electric drivetrains demand higher-purity liquid silicone grades for dielectric gap filling, creating specification premiums for qualified suppliers.
- Germany's manufacturing corridor concentration:OEM platform consolidation around Munich-Stuttgart engineering centers is compressing supplier qualification timelines and favoring regional compounders with rapid prototyping capabilities.
Market Restraints
- Methyl chlorosilane feedstock volatility:Silicon metal price swings and energy-intensive chlorosilane cracking operations expose compounders to margin compression when crude oil-linked hydrocarbon alternatives become cost-competitive.
- Asian monomer supply concentration:Captive production of silane precursors by integrated chemical conglomerates limits independent European and North American compounders' negotiating leverage on specialty grades.
- REACH authorization bottlenecks:ECHA's substance evaluation timelines for novel platinum catalyst systems delay new product introductions by eighteen to thirty-six months, freezing formulation innovation cycles.
Strategic Opportunities
- India's PLI scheme for electric mobility:Domestic component manufacturing incentives are attracting silicone molders to establish localized supply for two-wheeler and three-wheeler battery packs, bypassing import duty exposure.
- Autonomous vehicle sensor housings:Lidar and radar module sealing specifications favor optically clear liquid silicone grades with laser-weldable properties, opening design partnerships with Tier-1 electronics integrators.
- China's GB/T new energy vehicle safety standards:Mandatory flame-retardant performance thresholds above hydrocarbon elastomer capabilities are locking silicone into battery module intercell barriers and high-voltage connector seals.
Industry Challenges
- Platinum catalyst sourcing constraints:Automotive-grade hydrosilylation chemistry depends on consistent precious metal supply from South African and Russian mining operations, exposing compounders to geopolitical disruption and price spikes.
- Cross-regional qualification duplication:Separate OEM validation protocols for North American, European, and Asian battery pack designs force redundant testing campaigns that strain R&D budgets and extend program timelines.
- Legacy compression molding workforce gaps:Liquid silicone injection molding expertise remains scarce outside established medical device and consumer electronics supply bases, complicating automotive sector expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Silicone Elastomer Market |
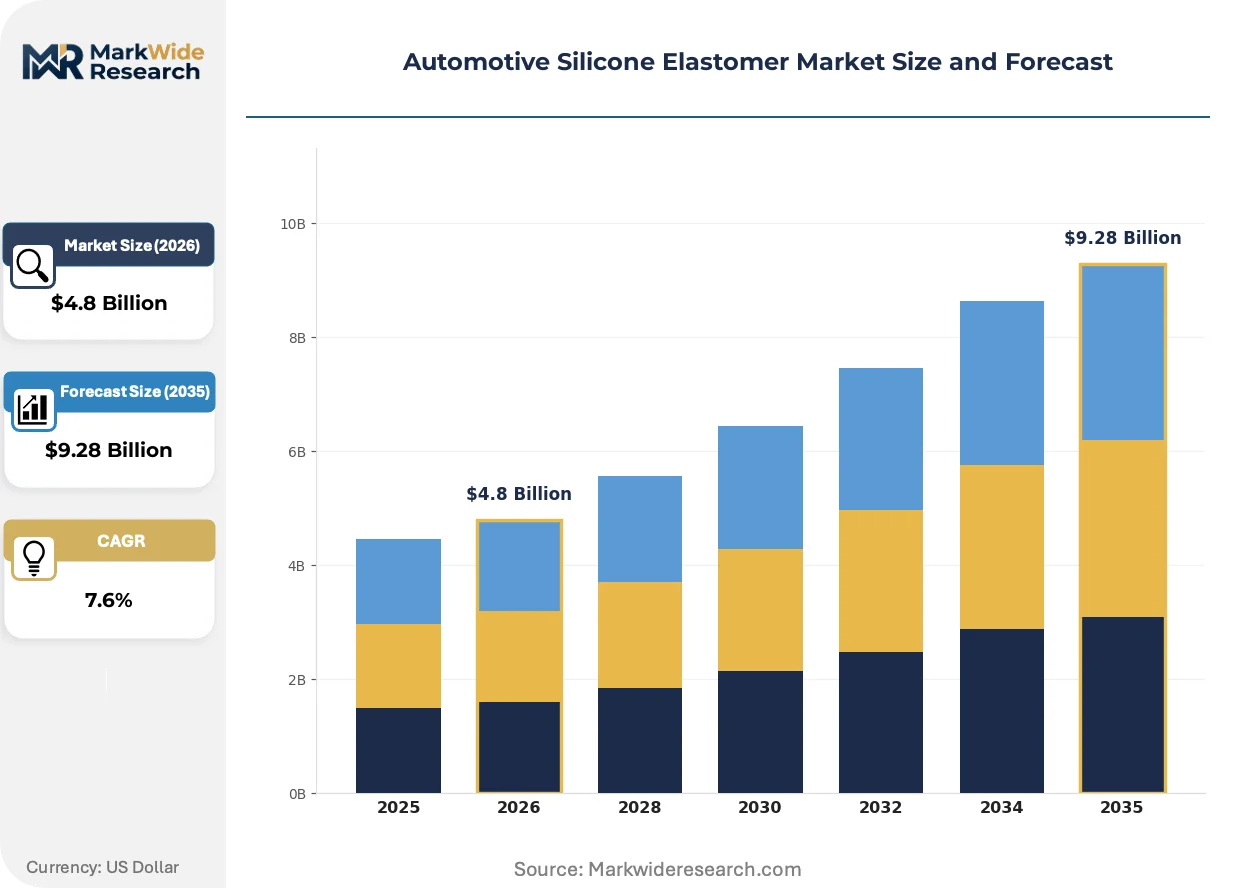
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Silicone, Liquid Silicone, Foam Silicone, Gels Application: Seals & Gaskets, Electrical Insulation, Vibration Dampening, Hoses End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Technology: Compression Molding, Injection Molding, Extrusion, 3D Printing |
| Companies Covered | Dow Inc., Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials Inc., Elkem ASA, Evonik Industries AG, Henkel AG & Co. KGaA, 3M Company, Gelest Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Silicone Elastomer Market Strategic Shifts
Silicone elastomer technology is bifurcating between commodity sealing compounds and engineered thermal interface materials, with processing methods and performance specifications diverging under pressure from electrification timelines.
Additive manufacturing of silicone prototypes is fragmenting traditional tooling economics for low-volume specialty vehicle programs. Tier-1 suppliers are adopting photopolymerizable silicone resins for rapid iteration of complex connector geometries. This capability is compressing development cycles from months to weeks for custom battery module seals.
REACH restrictions on phthalate plasticizers are redirecting European formulation chemistry toward peroxide-cured silicone systems. Compounders are reformulating solid rubber grades to eliminate platinum catalyst dependency where thermal stability requirements permit. German OEMs are qualifying these alternatives for underhood static seals to preempt regulatory liability.
Direct procurement contracts between EV battery pack manufacturers and silicone compounders are displacing traditional Tier-2 distribution channels. Automotive electronics integrators in South Korea and Japan are establishing dedicated supply agreements for high-purity thermal interface materials. This channel consolidation is squeezing independent distributors and forcing compounders to build application engineering capabilities in-house.
Automotive Silicone Elastomer Market Segmentation
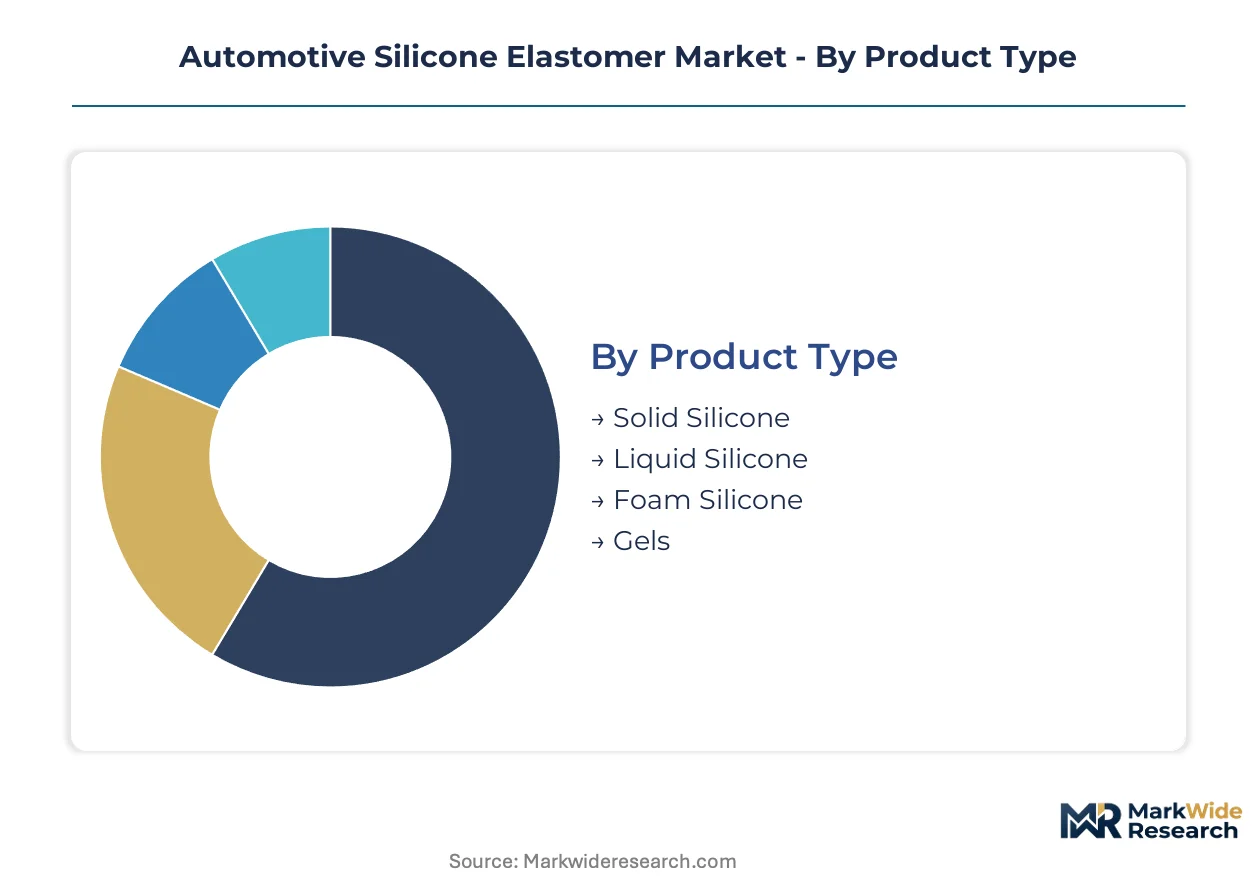
Segmentation in automotive silicone elastomers reveals how electrification is fragmenting traditional supply channels. Product specifications now diverge sharply between thermal management applications and legacy sealing functions, forcing compounders to maintain parallel qualification tracks for distinct customer tiers.
Product Type:
Solid silicone compounds flow primarily through Tier-1 distributors serving conventional powertrain programs, while liquid silicone grades increasingly move via direct procurement contracts with battery pack manufacturers seeking thermal interface specifications.
- Solid Silicone:Cross-linked polysiloxane rubber cured through peroxide or platinum-catalyzed mechanisms delivers compression set resistance for static sealing. Demand concentrates in Germany's automotive corridor for underhood gaskets and coolant system seals where thermal cycling durability is non-negotiable.
- Liquid Silicone:Low-viscosity two-part systems enable precision injection molding of complex geometries with tight tolerances. Battery module manufacturers in South Korea and Japan specify high-purity grades for dielectric gap filling in silicon carbide inverter assemblies.
- Foam Silicone:Cellular structures provide compressible sealing with reduced weight for NVH applications and gap filling in vehicle interiors.
- Gels:Soft, unfilled polysiloxane networks conform to irregular surfaces for potting and encapsulation of sensitive electronics.
By volume, solid silicone leads. By growth pace, liquid silicone is expanding most quickly.
Application:
Application segments stratify by margin structure: electrical insulation commands specification premiums, while hoses compete on throughput economics.
- Seals & Gaskets:Compression-molded or extruded profiles maintain fluid containment across temperature extremes from minus sixty to plus two hundred thirty degrees Celsius. OEM direct procurement is displacing Tier-2 distribution for EV battery module sealing as thermal cycling protocols tighten.
- Electrical Insulation:High-dielectric-strength silicone formulations isolate high-voltage busbars and connector terminals. China's GB standards for new energy vehicle safety mandate flame-retardant performance that hydrocarbon elastomers cannot achieve, locking silicone into intercell barriers.
- Vibration Dampening:Engine mounts and suspension bushings absorb mechanical energy while maintaining dimensional stability under load.
- Hoses:Extruded constructions with textile reinforcement convey coolant, charge air, and vacuum in turbocharged and electrified powertrains.
Seals and gaskets dominate volume throughput. Electrical insulation generates the steepest margin expansion.
End User:
Customer type determines contract structure: OEMs negotiate multi-year supply agreements, while aftermarket distributors stock standardized compounds.
- OEMs:Vehicle manufacturers specify compounds directly for platform-critical applications, bypassing traditional supply tiers. European OEMs consolidating engineering around Munich-Stuttgart corridors compress qualification timelines and demand rapid prototyping capabilities from compounders.
- Tier-1 Suppliers:Integrated electronics and thermal management specialists source high-purity grades for sensor housings and power module interfaces. South Korean automotive electronics integrators are establishing dedicated supply agreements for thermal interface materials.
- Aftermarket:Independent distributors serve replacement demand for legacy vehicle populations with standardized seal and hose specifications.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders procure silicone components for limited-production platforms.
OEMs anchor volume commitments. Tier-1 suppliers are gaining share fastest as electrification concentrates specification authority with electronics integrators.
Technology:
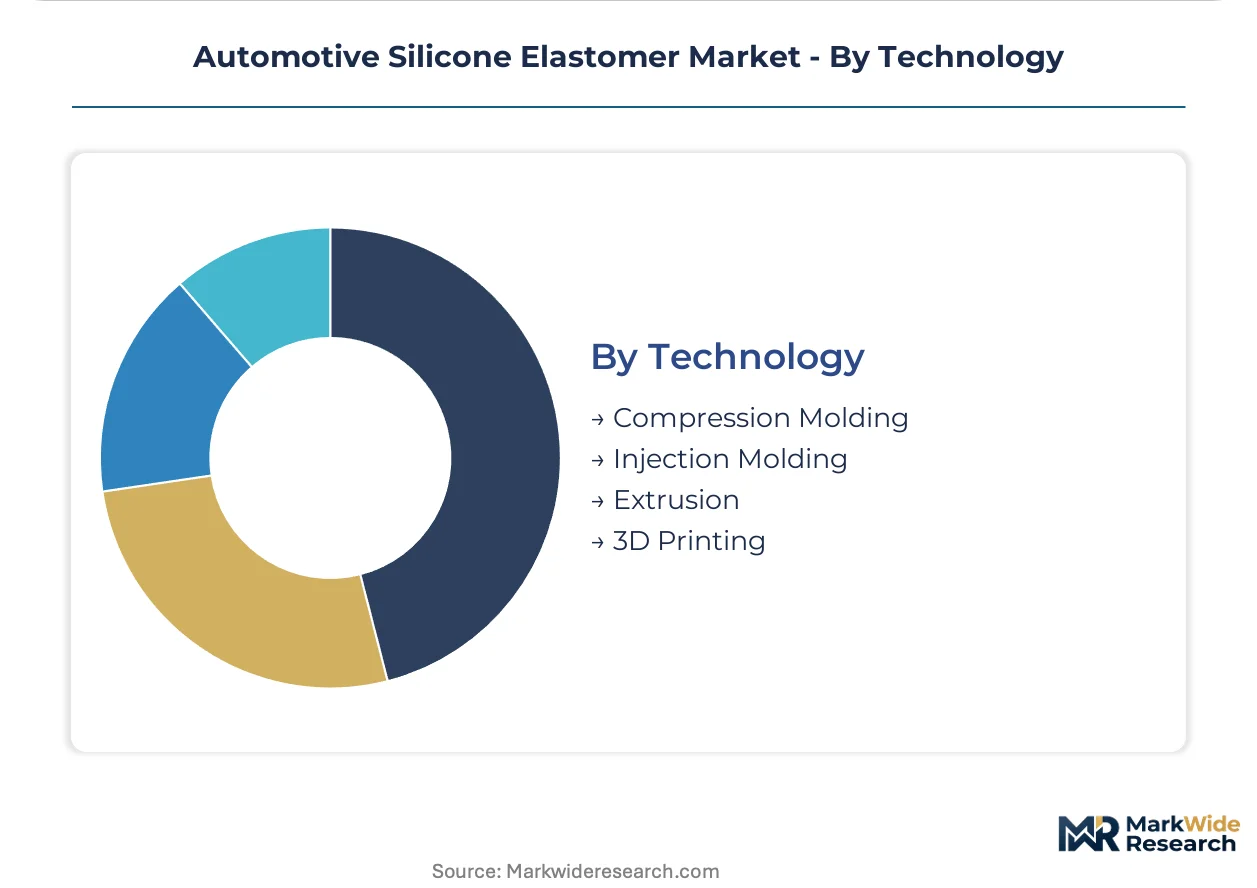
Processing method correlates with part complexity and volume economics, with injection molding capturing premium applications and extrusion sustaining commodity throughput.
- Injection Molding:Liquid silicone injection molding enables net-shape production of intricate geometries with flash-free precision. Medical device and consumer electronics supply bases retain scarce expertise, complicating automotive sector expansion for complex connector seals.
- Compression Molding:Solid silicone preforms cure under heat and pressure in multi-cavity tools for high-volume gasket production. Legacy workforce gaps in this technique are emerging as compounders struggle to staff production lines.
- Extrusion:Continuous profile production sustains established positions in coolant hose and turbocharger ducting with favorable throughput economics.
- 3D Printing:Photopolymerizable silicone resins enable rapid iteration of prototypes for low-volume specialty vehicle programs, compressing development cycles from months to weeks.
Compression molding leads by installed capacity. Injection molding climbs the fastest as electrification multiplies demand for precision-molded electrical components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's silicone elastomer logistics, channeling methyl chlorosilane feedstocks from upstream chemical complexes into automotive manufacturing corridors across Central Europe.
United States
NHTSA fuel economy regulations and EPA emission standards compel lighter material substitution in underhood applications. The Department of Energy's battery manufacturing grants under the Inflation Reduction Act subsidize domestic EV component supply chains. Detroit's engineering centers concentrate procurement authority for next-generation vehicle platforms, compressing supplier qualification timelines.
Germany
REACH authorization bottlenecks for novel platinum catalyst systems delay new product introductions by eighteen to thirty-six months. The EU Green Deal's material sustainability mandates accelerate silicone formulation redevelopment toward bio-based feedstocks. The Munich-Stuttgart manufacturing corridor concentrates OEM platform consolidation, favoring regional compounders with rapid prototyping capabilities.
China
GB standards for new energy vehicle safety specify flame-retardant elastomer performance thresholds that favor silicone over hydrocarbon alternatives. MIIT's dual carbon goals tighten energy efficiency requirements for silicone production facilities. The Yangtze River Delta hosts the densest concentration of battery pack manufacturers, driving thermal interface material demand.
Japan
METI's carbon neutrality roadmap pressures silicone compounders to decarbonize chlorosilane cracking operations. JIS standards for automotive electrical safety mandate dielectric stability in high-voltage connector applications. The Nagoya-Toyota industrial corridor anchors precision molding expertise for complex sensor housing geometries.
South Korea
MFDS-equivalent automotive safety regulations align with global EV battery standards, requiring flame-retardant sealing performance. The government's K-Battery strategy subsidizes domestic supply chain localization for thermal management components. Seoul's electronics integrators establish dedicated supply agreements for high-purity liquid silicone grades.
Automotive Silicone Elastomer Market Competitive Environment
Listed leaders compete with private specialists across integrated production capabilities, with publicly traded chemical conglomerates wielding capital access advantages while family-controlled firms retain formulation agility. Market structure consolidates around three to five vertically integrated monomer-to-elastomer producers, with mid-tier compounders occupying niche specification tiers. Strategic archetypes span captive feedstock operators, application engineering specialists, and regional toll compounders. Dominant competitive moves include backward integration into silicon metal refining and geographic expansion through qualified toll manufacturing partnerships.
Within the integrated chemical tier, Dow Inc., Wacker Chemie AG, and Shin-Etsu Chemical Co., Ltd. exemplify contrasting geographic anchoring strategies. The Michigan-based corporation represents North American supply security priorities. The Munich-headquartered Aktiengesellschaft occupies a position bridging European regulatory compliance with Asian market access. The Tokyo-based Kabushiki Kaisha anchors Asian monomer supply concentration through captive methyl chlorosilane operations. Each exemplifies how feedstock control shapes competitive positioning under volatile silicon metal pricing.
| Leading Market Players |
|---|
| Dow Inc. |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials Inc. |
| Elkem ASA |
| Evonik Industries AG |
| Henkel AG & Co. KGaA |
| 3M Company |
| Gelest Inc. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day methyl chlorosilane feedstock lead times concentrate pricing power with integrated monomer producers in Germany and Japan, while spot-market buyers absorb volatility through compressed compounder margins. Battery pack manufacturers negotiating direct procurement contracts extract volume concessions that reshape traditional distributor economics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates platinum-catalyzed liquid silicone grades for silicon carbide inverters from peroxide-cured solid compounds for static seals. Price differentiation hinges on certification tier (automotive-grade IATF 16949 vs industrial ISO 9001) and volume scale. Cost compression in standard-grade solid silicone intensifies because Asian monomer supply concentration exposes European compounders to margin squeeze when hydrocarbon alternatives become cost-competitive. Aftermarket distributors exhibit highest price sensitivity; OEM direct buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of silicon metal and platinum catalyst prevails among German and Japanese compounders confronting South African and Russian supply concentration, while just-in-time resin delivery dominates liquid silicone injection molders serving South Korean battery integrators. Feedstock sourcing draws from China, Germany, and the United States for methyl chlorosilane precursors. Supply chain risk centers on single-source vulnerability in platinum group metal refining. Distribution runs through captive logistics networks from monomer complexes to automotive manufacturing corridors, bypassing independent chemical distributors for thermal interface material grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive silicone elastomers sit in early-cycle expansion as EV battery thermal management specifications multiply addressable application scope beyond legacy powertrain sealing.
For Market Incumbents: Shield formulation portfolios from REACH authorization delays by accelerating peroxide-cured alternatives through German OEM qualification pipelines. Deepen backward integration into silicon metal refining to offset methyl chlorosilane feedstock volatility. Prioritize captive platinum catalyst inventory positions against South African supply disruption. For New Entrants and Emerging Players: Rapid prototyping services for Munich-Stuttgart OEM engineering centers represent the most penetrable service-layer gap, as incumbent compounders struggle to compress eighteen-month qualification timelines. Target India's PLI-subsidized two-wheeler battery pack segment with localized toll manufacturing partnerships. Lead with application engineering capabilities rather than commodity compound supply. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-monetized automotive silicone divisions lacking direct EV battery pack relationships. Five-to-ten-year viability hinges on thermal interface material specification authority migrating from Tier-1 distributors to compounders. Watch for silicon carbide inverter adoption rates crossing mass-production thresholds as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Captive refining secures margin stability against volatile ferrosilicon pricing from Norwegian and Icelandic smelters. |
| Platinum Catalyst Inventory Pre-positioning | Strategic metal stockpiling buffers German compounders from ECHA authorization bottlenecks and Russian supply disruption. |
| Application Engineering Center Expansion | Munich and Stuttgart proximity accelerates OEM qualification timelines for next-generation battery module sealing. |
| India Toll Manufacturing Partnership | Localized compounding bypasses import duty exposure under PLI scheme for electric two-wheeler battery packs. |
| Peroxide-Cured Formulation Redevelopment | Eliminating platinum dependency preempts REACH liability while maintaining thermal stability for underhood static seals. |
Study Parameters
A standing panel of OEM platform engineers, Tier-1 supplier procurement leads, silicone compounding plant managers, and thermal interface material R&D directors provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K chemical segment disclosures, and vehicle production databases. Bottom-up volume modeling triangulated against top-down market sizing from raw material consumption trends.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product grade tier, propulsion architecture, application function, and regional production cluster. CAGRs derived from year-over-year growth rate progression analysis incorporating silicon carbide inverter adoption curves, battery pack production forecasts, and REACH regulatory implementation timelines.
Forecasts assume regulatory continuity in EU REACH, China GB standards, and US EPA emission regimes; material policy shifts would require re-modeling. Revision becomes warranted when platinum group metal supply disruption or silicon carbide inverter mass-production acceleration crosses threshold magnitudes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automotive Sunroof Glass Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Active Suspension Damper Actuator Systems Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
Automobile Accessories Market
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Brackets Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Automotive Tie Rod Market