
 Towing Ropes Market | 2026-2036
Towing Ropes Market Size, Share, and Industry Trends Forecast 2026-2036
Towing Ropes Market Analytics
Skilled polymer engineering talent is rotating from maritime rigging into synthetic rope manufacturing, easing capacity bottlenecks for advanced fiber products. Samson Rope Technologies leverages its proprietary Double-Braid construction to dominate premium marine towing applications. WireCo WorldGroup sustains global distribution density through integrated wire-rope foundries across multiple continents. TEUFELBERGER specializes in heat-resistant aramid blends that serve industrial heat-exposure environments.
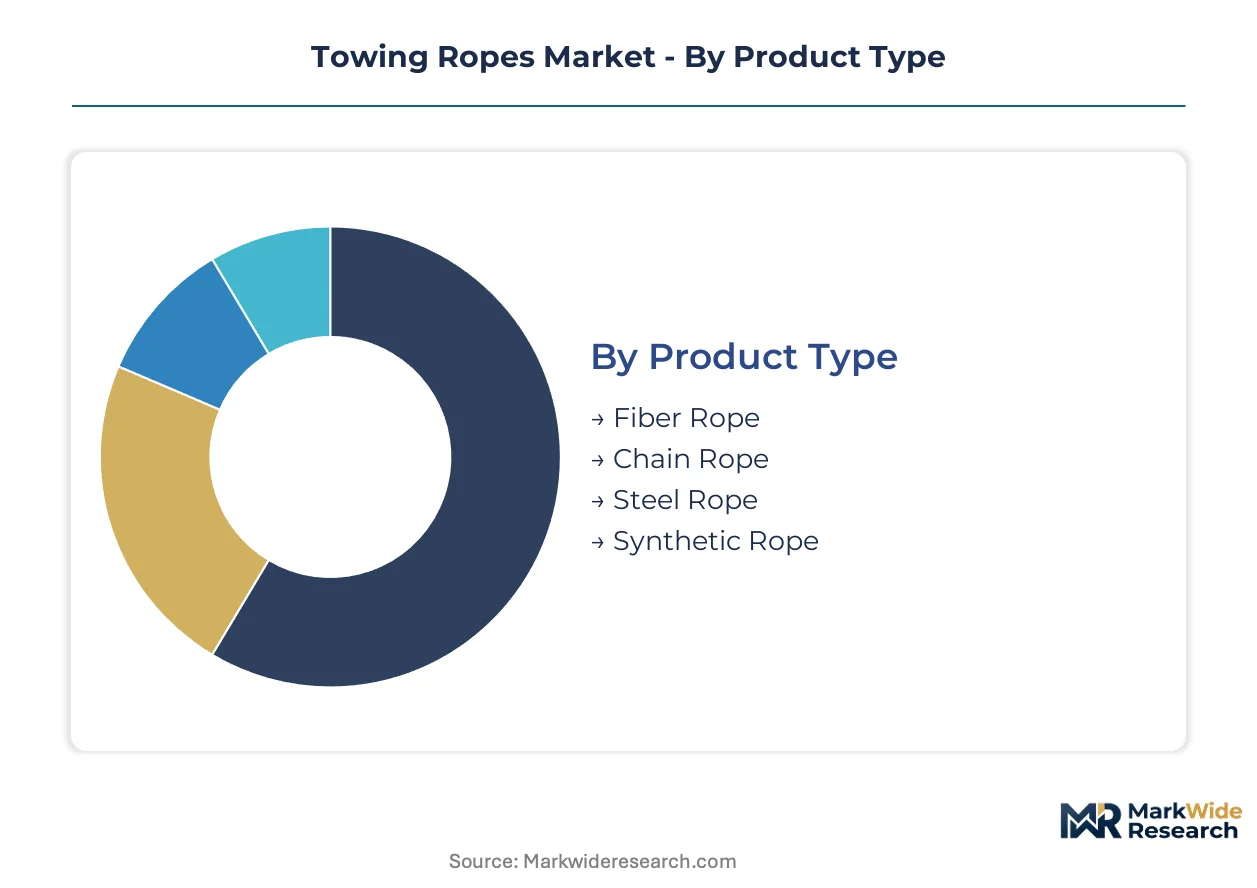
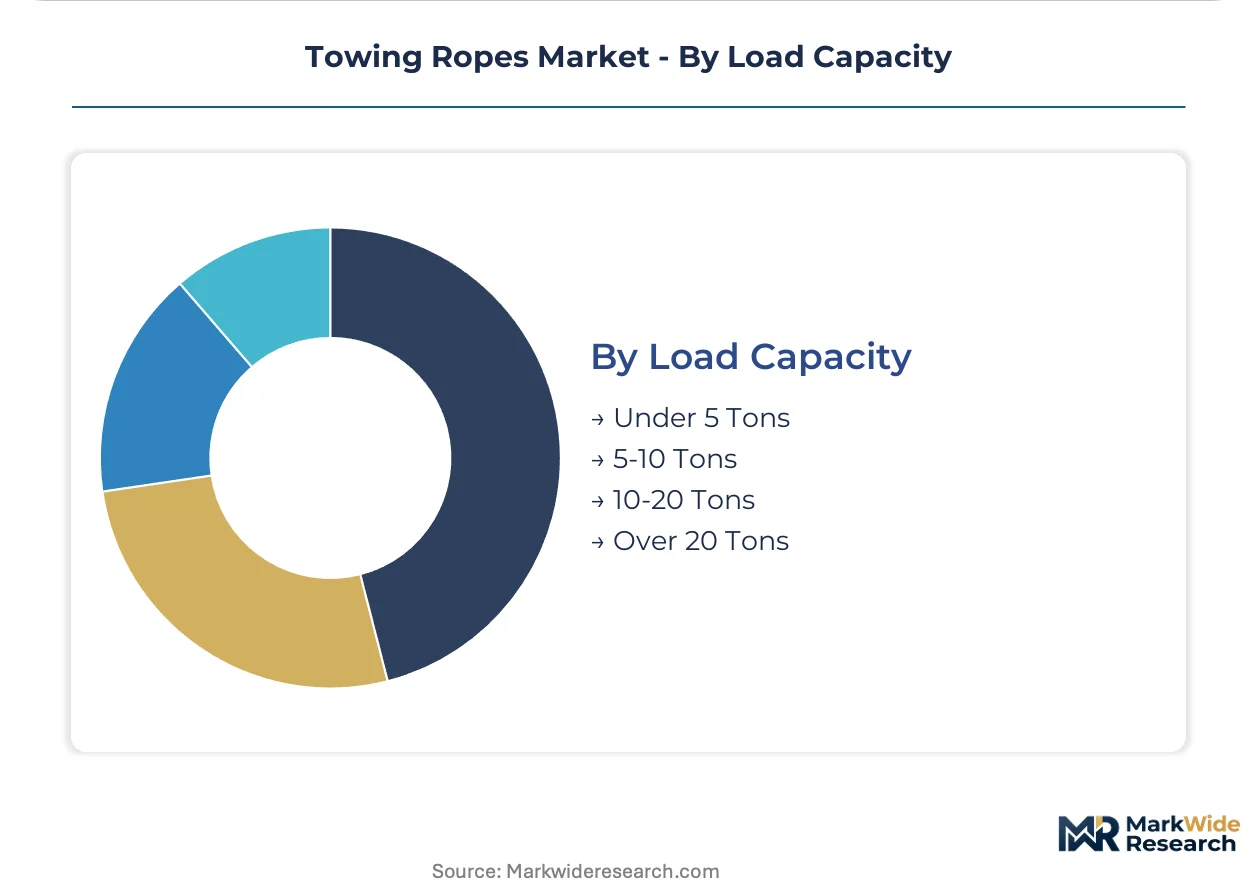
Towing ropes are load-bearing tensile members manufactured from twisted or braided fibers, wire strands, or chain links, engineered to transmit pulling force between a powered vehicle and a trailing or immobilized load. Synthetic variants typically incorporate ultra-high molecular weight polyethylene (UHMWPE) or aramid cores with protective polyester jackets to achieve strength-to-weight ratios exceeding steel by factors of seven to fifteen. Fiber rope commands the largest volume share due to versatility across agriculture and marine settings, while synthetic rope captures the fastest expansion as fleet operators replace wire assemblies to reduce handling injuries and corrosion maintenance. Chain rope retains entrenched positions in mining and heavy construction where abrasion resistance outweighs weight penalties. Load capacity segmentation shows 10-20 ton ratings generating disproportionate margin contribution, as these specifications require certified testing regimes that smaller suppliers struggle to fund.
FAA guidelines for airport ground support equipment impose dynamic load testing on aircraft tow ropes, while OSHA regulations mandate working load limits and inspection intervals for industrial lifting and pulling operations. ISO 9554 and ASTM D4268 establish baseline breaking strength and elongation criteria that determine market access for certified suppliers. Stakeholders must monitor evolving standards for bio-based fiber alternatives and recycled content mandates that could reshape raw material qualification pathways.
Market Dynamics
The Towing Ropes Market is experiencing structural compression as fleet operators accelerate wire-to-synthetic conversion cycles, driven by OSHA-mandated injury reduction targets and corrosion maintenance cost accumulation across coastal and chemical exposure environments.
Growth Catalysts
- EU Machinery Directive enforcement:Updated tensile testing protocols for load-bearing cordage are disqualifying uncertified suppliers, consolidating procurement toward ISO 9554-compliant manufacturers in marine and industrial verticals.
- Off-road vehicle recovery services:Expanded procurement of high-strength synthetic ropes is creating dedicated specification tiers for UHMWPE-core assemblies in Texas and California fleet networks.
- Skilled polymer engineering migration:Talent rotation from maritime rigging into synthetic rope manufacturing is easing capacity bottlenecks for advanced fiber products serving heat-exposure industrial environments.
Market Restraints
- Aramid fiber input cost volatility:Heat-resistant blend formulations depend on petroleum-derived precursor supply chains concentrated in Gulf Coast petrochemical corridors.
- Wire rope foundry concentration:Integrated steel-cord production capacity clusters in East Asian and European metallurgical basins, creating geographic single-source exposure for legacy fleet maintenance.
- Chain rope substitution ceiling:Mining and heavy construction segments retain entrenched positions where abrasion resistance outweighs synthetic weight advantages, capping displacement velocity.
Strategic Opportunities
- Airport ground support equipment:FAA dynamic load testing requirements for aircraft tow ropes are creating certified-supplier moats with limited qualified competitors.
- Bio-based fiber qualification pathways:Evolving ISO standards for recycled content mandates are reshaping raw material sourcing strategies ahead of regulatory codification.
- Double-braid construction licensing:Proprietary marine towing architectures are generating technology transfer revenue streams from rigging specialists entering adjacent industrial segments.
Industry Challenges
- Certified testing regime capital intensity:10-20 ton load capacity ratings require funded validation infrastructure that smaller suppliers cannot access, creating tier-lockout effects.
- Multi-standard compliance synchronization:Simultaneous adherence to ASTM D4268 elongation criteria and EU Machinery Directive tensile protocols demands dedicated quality engineering functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Towing Ropes Market |
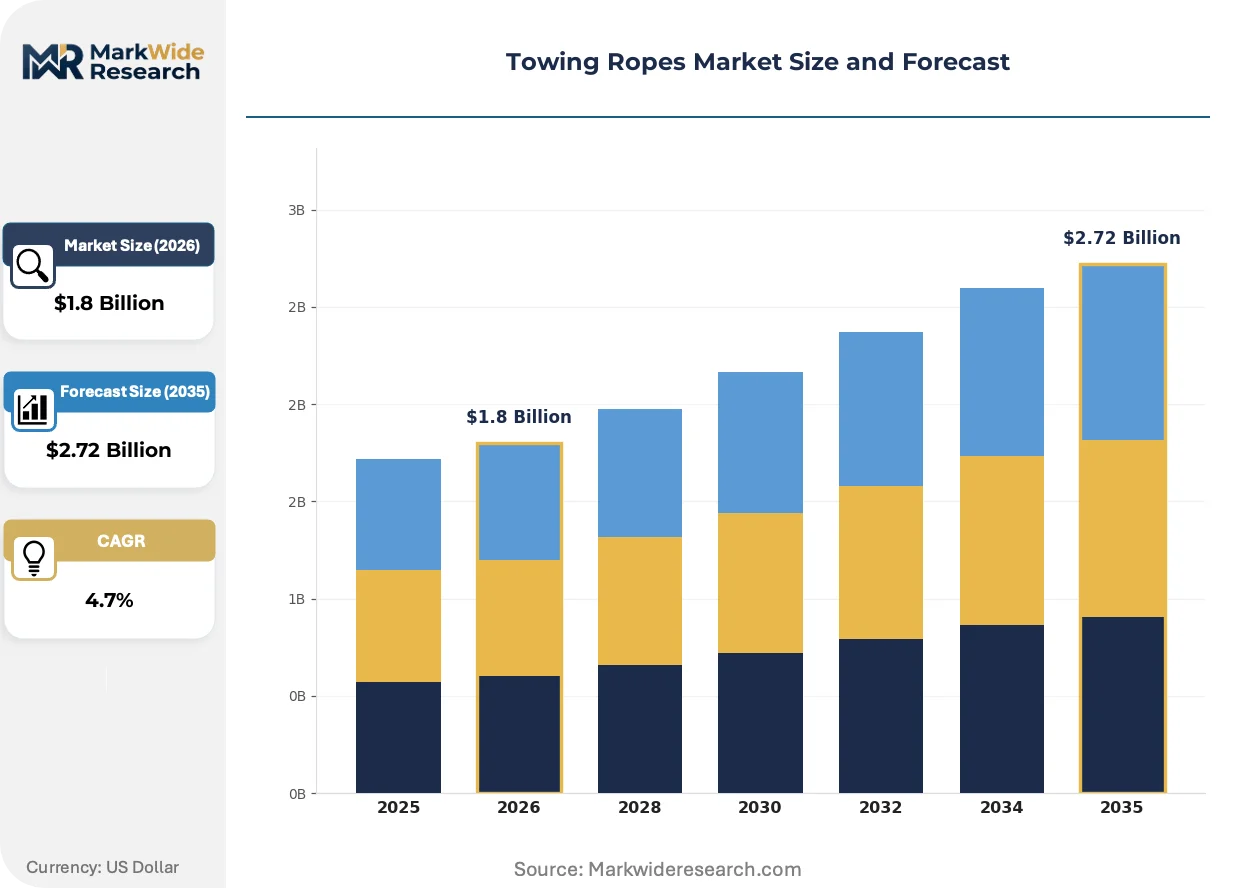
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Rope, Chain Rope, Steel Rope, Synthetic Rope End User: Agriculture, Transportation, Marine, Industrial Application: Towing, Recovery, Lifting, Hauling Load Capacity: Under 5 Tons, 5-10 Tons, 10-20 Tons, Over 20 Tons |
| Companies Covered | Samson Rope Technologies, Cortland Limited, WireCo WorldGroup, TEUFELBERGER, Bridon-Bekaert, Yale Cordage, Bekaert, Bubba Rope, Rhino USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Towing Ropes Market Evolving Landscape
Synthetic fiber architectures are compressing traditional material hierarchies across marine, industrial, and automotive towing applications, with regulatory pressure and operator safety economics converging to accelerate specification turnover.
Ultra-high molecular weight polyethylene core assemblies with protective polyester jackets are achieving strength-to-weight ratios exceeding steel by factors of seven to fifteen. Fleet operators in Texas and California are specifying these configurations for corrosion-prone environments. This material transition is miniaturizing handling crews and reducing rigging injury incident rates below OSHA-reportable thresholds.
The EU Machinery Directive's updated tensile testing protocols are forcing recertification of all load-bearing cordage sold within member states. Industrial rope manufacturers must now maintain dual-validated quality systems for ISO 9554 and ASTM D4268 compliance. Marine towing segments are responding fastest, with premium double-braid constructions capturing specification preference in North Sea and Mediterranean port authorities.
Buyer concentration among fleet operator networks is compressing vendor qualification cycles and unbundling after-sales inspection services from original equipment supply. Large-scale logistics operators in the United States are establishing captive rope inspection intervals independent of manufacturer recommendations. This pattern is most visible in California agricultural towing cooperatives and Texas oilfield service fleets.
Towing Ropes Market Segmentation
Towing rope procurement channels diverge sharply by material type and end-use certification requirements. Fleet operators route high-volume synthetic orders through integrated distributors, while specialized industrial buyers engage manufacturers directly for certified load-rated assemblies.
Product Type:
Fiber rope moves through agricultural supply cooperatives and marine chandleries in high volumes with minimal technical consultation. Synthetic rope commands premium positioning through industrial distributors serving OSHA-regulated fleet networks.
- Fiber Rope:Twisted or braided natural and synthetic fiber constructions dominate agricultural towing and general marine applications. Demand concentrates in United States agricultural cooperatives across California's Central Valley, driven by cost-sensitive procurement patterns and established supplier relationships with regional farm equipment distributors.
- Synthetic Rope:Ultra-high molecular weight polyethylene and aramid-core assemblies with protective jackets achieve strength-to-weight ratios exceeding steel by factors of seven to fifteen. Fleet operators in Texas oilfield services and California transportation networks are specifying these configurations to reduce rigging injuries and eliminate corrosion maintenance cycles.
- Steel Rope:Wire strand constructions retain entrenched positions in mining and heavy infrastructure where abrasion resistance outweighs handling penalties.
- Chain Rope:Welded link assemblies serve extreme-load mining and construction environments where synthetic displacement faces technical ceilings.
By volume, fiber rope leads. By growth pace, synthetic rope is climbing the fastest.
End User:
Cost tier stratification separates commodity agriculture from certified industrial and marine segments requiring funded testing infrastructure.
- Transportation:Fleet operator networks in Texas and California specify ISO 9554-compliant synthetic assemblies for heavy-duty vehicle recovery and terminal operations. These buyers prioritize working load limit documentation and inspection interval protocols mandated by OSHA regulations.
- Marine:Port authorities and offshore operators procure double-braid constructions meeting EU Machinery Directive tensile testing protocols. North Sea and Mediterranean terminals are consolidating procurement toward certified suppliers with dual-validated quality systems.
- Industrial:Heat-exposure environments specify aramid blends from manufacturers with polymer engineering capabilities.
- Agriculture:California cooperatives and Midwest farm operations drive fiber rope volume through price-sensitive distributor channels.
Transportation commands the highest margin tier. Marine is gaining share fastest through regulatory consolidation.
Application:
Volume distribution skews toward towing, while recovery applications concentrate the most demanding technical specifications.
- Towing:Standard load transmission between powered vehicles and trailers or immobilized equipment represents the baseline application across all material types. Agricultural and transportation fleets in the United States generate the bulk of demand through routine operational replacement cycles.
- Recovery:Off-road vehicle extraction and emergency response operations require high-strength synthetic ropes with documented dynamic load characteristics. Texas and California fleet networks are establishing dedicated specification tiers for UHMWPE-core assemblies in extreme terrain environments.
- Lifting:Vertical load operations demand certified breaking strength documentation under ASTM D4268 protocols.
- Hauling:Sustained tension applications in logging and construction favor steel and chain constructions.
Towing generates the largest unit volume. Recovery shows the steepest specification upgrade trajectory.
Load Capacity:
Margin concentration sits in mid-range ratings where certified testing creates supplier tier lockout effects.
- 10-20 Tons:These ratings require funded validation infrastructure and documented quality systems that disqualify smaller suppliers. Industrial fleet operators and marine contractors in the United States concentrate procurement in this band, generating disproportionate margin contribution for ISO 9554-compliant manufacturers.
- 5-10 Tons:Light industrial and commercial vehicle applications cluster here, with California agricultural cooperatives and Texas service fleets driving volume through distributor networks.
- Under 5 Tons:Consumer and light commercial applications favor fiber rope through retail and cooperative channels.
- Over 20 Tons:Mining and heavy construction retain chain and steel rope dominance where synthetic displacement faces abrasion resistance constraints.
By revenue contribution, 10-20 ton ratings lead. By volume expansion, 5-10 ton ratings are advancing most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States fleet operators favor synthetic UHMWPE assemblies for corrosion resistance, while German industrial buyers prioritize EU Machinery Directive certification, and Chinese mining corridors retain steel-wire dominance for abrasion-critical haulage.
United States
Texas oilfield service fleets and California agricultural cooperatives drive synthetic rope procurement for off-road recovery and transportation applications. OSHA working load limit regulations mandate documented inspection intervals for fleet operators. Dallas-Fort Worth distribution networks concentrate procurement for 10-20 ton rated assemblies serving heavy-duty vehicle recovery.
Germany
North Sea port authorities and industrial manufacturers prioritize ISO 9554-compliant double-braid constructions for marine towing. EU Machinery Directive tensile testing protocols disqualify uncertified suppliers from member state procurement. Hamburg and Bremen harbor terminals consolidate sourcing toward dual-validated quality system providers.
China
Domestic mining operations and heavy infrastructure projects sustain wire rope demand where synthetic displacement faces technical ceilings. GB standards and MIIT industrial safety regulations govern load-bearing cordage certification. Shanxi Province coal corridors and Yangtze River Delta construction zones anchor steel-cord consumption.
Japan
Maritime rigging specialists and polymer engineering talent rotate into advanced fiber manufacturing for heat-exposure industrial environments. METI industrial standards and JIS certification requirements shape supplier qualification. Nagoya industrial belt and Osaka Bay port clusters concentrate aramid-blend specification.
Australia
Mining sector procurement favors chain rope for extreme-load environments where abrasion resistance outweighs weight considerations. National workplace safety regulations mandate documented breaking strength validation for lifting and pulling operations. Western Australia Pilbara iron ore districts and Queensland coal basins retain entrenched steel and chain assemblies.
Towing Ropes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with global wire-rope foundries and proprietary fiber manufacturers occupying distinct competitive positions. The market structure concentrates certified testing capacity among ISO 9554-compliant suppliers, while smaller fabricators serve price-sensitive agricultural channels. Three archetypes dominate: integrated metallurgical producers with captive steel-cord capacity, polymer engineering specialists with proprietary braid architectures, and regional distributors with fleet operator relationships. Competitive moves center on technology licensing for double-braid constructions and backward integration into UHMWPE fiber production.
Among North American specialists, Samson Rope Technologies and Yale Cordage exemplify the premium marine and industrial tier, while WireCo WorldGroup represents the integrated metallurgical archetype with global foundry networks. TEUFELBERGER anchors the European heat-resistant fiber segment. These three occupy positions that reflect divergent strategic bets on synthetic displacement versus steel-wire retention across regional demand clusters.
| Leading Market Players |
|---|
| Samson Rope Technologies |
| Cortland Limited |
| WireCo WorldGroup |
| TEUFELBERGER |
| Bridon-Bekaert |
| Yale Cordage |
| Bekaert |
| Bubba Rope |
| Rhino USA |
| Others |
Value Network & Pricing Analysis
ISO 9554 certification requirements simultaneously gate supplier qualification and stratify price tiers, forcing uncertified manufacturers toward commodity fiber rope segments while accredited producers capture premium positioning in 10-20 ton rated assemblies. This dual filtering mechanism concentrates pricing power among dual-validated quality system holders serving OSHA-regulated fleet networks.
Pricing Analysis
Long-term offtake contracts dominate procurement for 10-20 ton rated synthetic assemblies, with spot purchasing limited to agricultural fiber rope through cooperative distributors. Price differentiation stems from ISO 9554 certification tier and volume scale, with certified marine and industrial buyers showing low sensitivity compared to California agricultural cooperatives. Cost compression in standard fiber constructions intensifies as Texas and California fleet operators consolidate toward fewer approved vendors.
Supply Chain Analysis
Inventory lead times for UHMWPE-core assemblies stretch when Gulf Coast petrochemical corridors experience aramid precursor disruptions, while wire rope foundries in Germany and Japan maintain steadier availability. Raw material sourcing draws from petroleum-derived fiber precursors, steel-cord metallurgical basins, and polyester jacket polymers. Single-source vulnerability concentrates in heat-resistant aramid blend formulations. Distribution runs through integrated industrial distributors serving certified fleet operator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator wire-to-synthetic conversion cycles are accelerating penetration in corrosion-prone environments, positioning the market for early-cycle expansion as OSHA injury reduction mandates harden procurement specifications.
For Market Incumbents: Secure backward integration into UHMWPE fiber production to defend margin position against polymer input volatility. Fortify dual-validated quality systems for simultaneous ASTM D4268 and EU Machinery Directive compliance, creating tier-lockout effects against uncertified challengers in 10-20 ton rated segments.
For New Entrants and Emerging Players: Anchor in California agricultural cooperative channels where price-sensitive fiber rope procurement tolerates new supplier qualification. Target 5-10 ton light commercial ratings through distributor partnerships, leveraging lower certification capital intensity than industrial tier requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across certified testing infrastructure as ISO 9554 and FAA dynamic load validation requirements proliferate. Acquisition targets should display captive polymer engineering capabilities and established port authority relationships. Monitor EU Machinery Directive enforcement velocity as inflection indicator for regulatory consolidation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into UHMWPE Fiber Production | Captive supply of ultra-high molecular weight polyethylene cores reduces Gulf Coast petrochemical corridor exposure for synthetic rope manufacturers. |
| Dual-Validation Quality System Investment | Simultaneous ISO 9554 and ASTM D4268 compliance creates procurement moats in OSHA-regulated Texas and California fleet networks. |
| Double-Braid Construction Licensing | Technology transfer revenue from proprietary marine architectures expands addressable market into adjacent industrial heat-exposure segments. |
| Airport Ground Support Equipment Certification | FAA dynamic load testing qualification limits qualified competitors in aircraft tow rope specifications. |
| Bio-Based Fiber Qualification Pathway Development | Early positioning for evolving ISO recycled content mandates ahead of regulatory codification secures future raw material access. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operator procurement directors, marine port authority engineers, polymer R&D specialists, and industrial distributor category managers and refined through secondary validation. Sources included customs trade data for steel-cord and synthetic fiber imports, SEC filings from integrated wire-rope manufacturers, FAA certification databases for aircraft tow rope approvals, and EU Machinery Directive implementation guidance. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Variance decomposition across material type, load capacity tier, end-use vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level penetration curves and replacement cycle analysis. Industry-specific inputs incorporated OSHA inspection interval compliance rates, EU port authority procurement consolidation patterns, and aramid fiber precursor supply elasticity assumptions.
Decision-makers should treat outputs as directional under sustained wire-to-synthetic conversion velocity and stable petrochemical input pricing; material deviation in fleet operator replacement cycles or Gulf Coast supply disruptions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Thrust Bearings Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Automotive Wheel Speed Sensor Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Steering Column Module Market
Vehicle Components
Motor Monitoring Market