
 Online Car Buying Market | 2026-2036
Online Car Buying Market Size, Share, and Industry Trends Forecast 2026-2036
Online Car Buying Market Intelligence
Artificial intelligence-powered vehicle valuation and automated financing underwriting is reshaping how automobiles are sourced and sold through digital channels. Carvana leverages proprietary logistics infrastructure to control end-to-end fulfillment across major metropolitan zones. CarGurus anchors its marketplace model on price transparency tools that aggregate inventory from franchise and independent sources. Amazon Autos competes by extending its e-commerce fulfillment expertise into automotive retail, integrating search, financing, and delivery within its existing platform architecture.
Online car buying encompasses the complete digital transaction of vehicle acquisition, from search and configuration through financing, trade-in valuation, and final delivery or pickup, typically supported by AI-driven pricing engines, digital document execution, and integrated logistics coordination. The used cars segment sustains the largest transaction volume due to price sensitivity and shorter replacement cycles among private buyers. Fleet buyers represent the fastest-growing customer type as commercial enterprises centralize procurement through online platforms to reduce acquisition overhead and standardize vehicle specifications across distributed operations. Financing dominates the payment method landscape because integrated lending marketplaces streamline credit decisioning and rate comparison within the purchase workflow.
The Federal Trade Commission's Combating Auto Retail Scams rule shapes disclosure requirements for digital dealers operating in the United States, while the EU AI Act imposes algorithmic accountability standards on automated credit scoring and vehicle pricing systems deployed across European markets. China's SAMR enforces data localization and consumer protection rules that govern how domestic platforms handle buyer financial information and transaction records. Stakeholders must monitor how divergent regulatory timelines for AI governance and consumer finance disclosure create compliance complexity for platforms operating across multiple jurisdictions.
Market Dynamics
AI-driven valuation engines and integrated logistics networks are compressing transaction timelines while fragmenting traditional dealer networks across major metropolitan corridors. The FTC's Combating Auto Retail Scams rule and the EU AI Act are forcing platforms to re-engineer disclosure workflows and algorithmic accountability mechanisms.
Growth Catalysts
- EU AI Act compliance frameworks:Mandated algorithmic transparency for automated credit scoring is accelerating platform investment in explainable AI systems across European markets.
- Fleet procurement centralization:Commercial enterprises are consolidating vehicle acquisition through digital channels to standardize specifications and reduce overhead across distributed operations.
- Integrated financing marketplaces:Embedded lending comparison tools streamline credit decisioning within purchase workflows, reducing abandonment rates at checkout.
Market Restraints
- Last-mile delivery cost structures:Single-vehicle transport economics constrain profitability in low-density postal codes outside major urban clusters.
- Data localization mandates:China's SAMR requirements for domestic storage of buyer financial information fragment platform architecture and increase compliance overhead.
- Physical inspection substitution limits:Remote condition assessment technologies face trust deficits for high-value transactions among risk-averse buyer segments.
Strategic Opportunities
- German market penetration gaps:Independent dealer digitalization lags behind franchise networks, creating white space for platform-enabled inventory aggregation.
- Subscription-to-purchase conversion:Flexible tenure models are bridging short-term mobility services with long-term ownership commitments among urban millennials.
- Blockchain title verification:Distributed ledger integration with state DMV systems is compressing lien-release and ownership-transfer timelines.
Industry Challenges
- Automotive technician recruitment:Reconditioning center staffing shortages delay vehicle readiness and extend delivery windows.
- Multi-jurisdiction disclosure alignment:Divergent FTC, EU AI Act, and SAMR timelines create compliance complexity for cross-border platform operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Car Buying Market |
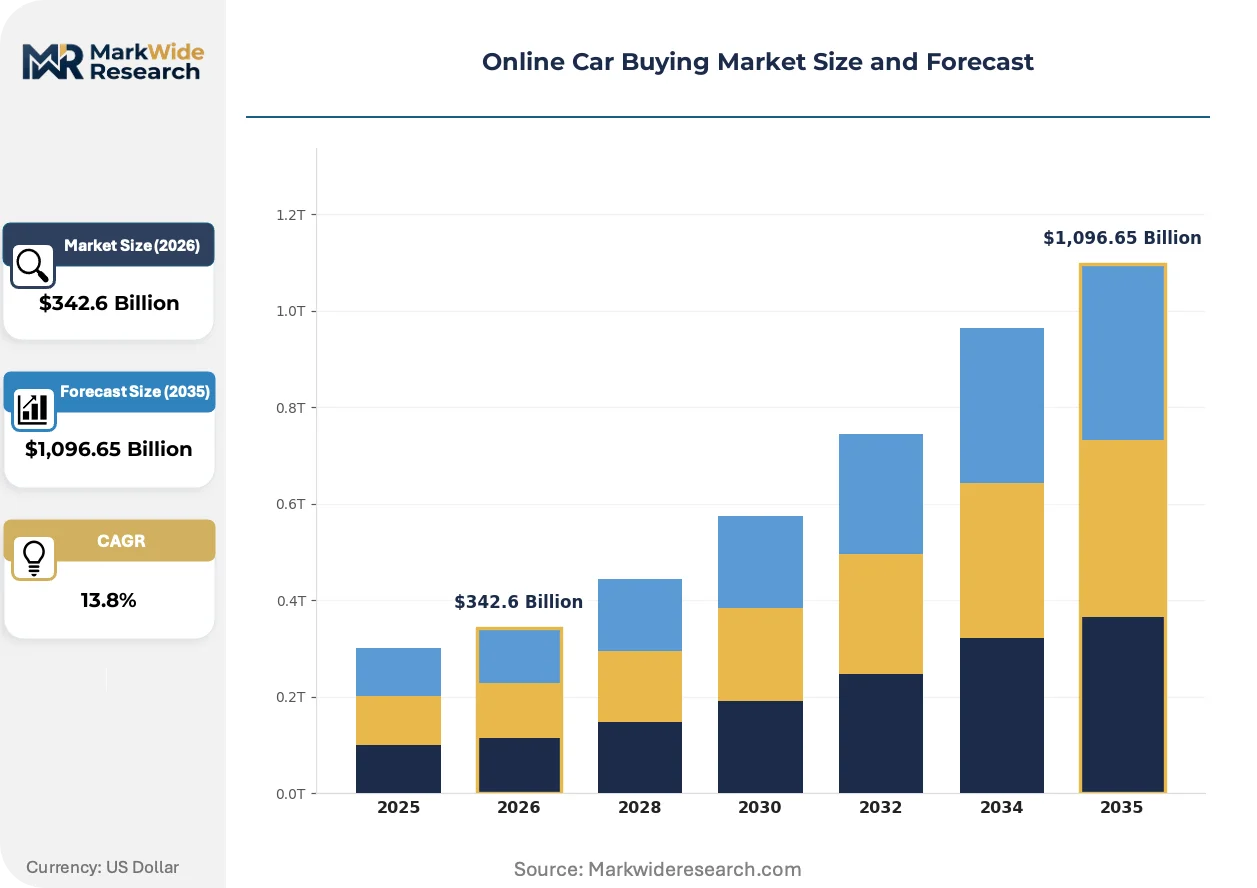
| Market Size in 2026 | $342.6 Billion |
| Market Size in 2035 | $1,096.65 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transaction Type: New Cars, Used Cars, Certified Pre-Owned, Auction Cars Payment Method: Financing, Cash Purchase, Trade-In, Lease Dealer Model: Franchise Dealerships, Independent Dealers, Online-Only Platforms, Auctions Customer Type: Private Buyers, Fleet Buyers, Commercial Enterprises, Educators |
| Companies Covered | Autotrader, CarGurus, Carvana, Edmunds, Kelley Blue Book, CarMax, Cars.com, Amazon Autos, TrueCar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Car Buying Market Strategic Shifts & Innovations
Digital infrastructure investments are compressing the traditional vehicle acquisition funnel from search through fulfillment. Three concurrent developments are reconfiguring competitive positioning and buyer expectations.
Computer vision-based damage detection is digitizing condition assessment workflows previously requiring physical inspection. Fleet buyers and high-volume remarketers are deploying these tools at scale to accelerate wholesale acquisition decisions. The technology is digitizing trust formation between remote sellers and distant buyers, reducing transaction friction in cross-state commerce.
The EU AI Act's algorithmic accountability requirements are mandating audit trails for automated pricing and credit decisioning systems. European platforms must now document training data provenance and model performance metrics for regulatory examination. Used vehicle marketplaces with integrated lending functions face the steepest compliance burden, driving consolidation toward better-capitalized operators.
Fleet procurement departments are consolidating vendor relationships around platforms offering standardized specification management and centralized billing. Multi-location enterprises are abandoning fragmented local dealer networks for national contracts with digital-native suppliers. This concentration is most visible in the United States, where telematics-enabled fleet management integration creates switching costs for incumbent platforms.
Online Car Buying Market Segmentation
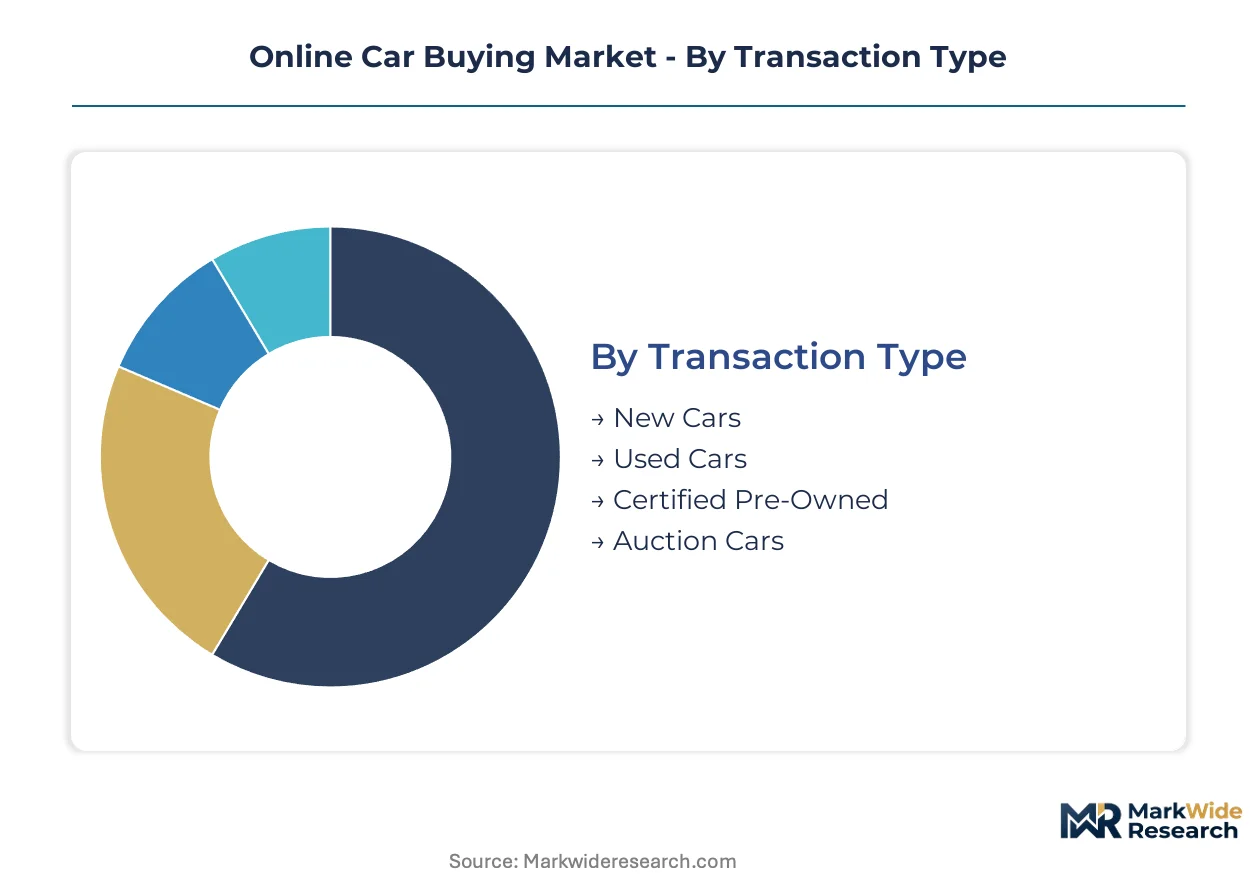
Transaction complexity in digital automotive retail demands precise segmentation to align platform capabilities with distinct buyer workflows. Each dimension—vehicle condition, payment structure, sales channel, and purchaser category—carries unique fulfillment requirements and regulatory exposure.
Transaction Type:
Vehicle condition tiers span the depreciation curve from factory-fresh inventory to distressed assets.
- Used Cars:Vehicles with prior ownership history dominate transaction volume through price accessibility and shorter replacement cycles. Demand concentrates among private buyers in the United States seeking value retention, constrained by trust deficits in remote condition assessment for high-mileage units.
- New Cars:Factory-authorized inventory with full manufacturer warranty coverage. Configuration tools and transparent pricing attract digitally native buyers in Germany, though franchise agreements limit direct-to-consumer distribution in many jurisdictions.
- Certified Pre-Owned:Manufacturer-backed used vehicles with extended warranty and inspection protocols. Appeals to risk-averse segments seeking middle-ground assurance between new and uncertified used.
- Auction Cars:Wholesale inventory including fleet returns, lease maturities, and salvage titles. Trades primarily between commercial remarketers and dealers, with condition disclosure standards varying by auction platform.
Established volume favors used cars; emerging adoption favors certified pre-owned.
Payment Method:
Capital structure preferences determine platform integration depth with financial services infrastructure.
- Financing:Embedded lending marketplaces streamline credit decisioning within purchase workflows. Integrated rate comparison reduces abandonment at checkout, particularly among prime-credit buyers in the United States where the FTC's disclosure rules govern digital execution.
- Cash Purchase:Full upfront settlement eliminates underwriting friction and accelerates fulfillment timelines. Concentrates among high-net-worth individuals and repeat buyers with established platform relationships.
- Trade-In:Equity transfer from existing vehicle ownership reduces net cash outflow. Valuation accuracy and title-handling speed determine conversion rates, with AI-powered appraisal tools compressing quote-to-offer intervals.
- Lease:Structured monthly payments with residual value risk retention by lessor. Digital lease origination requires residual forecasting models and captive finance integration, limiting platform participation to manufacturer-affiliated channels.
Transaction velocity favors financing; margin compression favors cash purchase.
Dealer Model:
Channel architecture determines inventory access, pricing transparency, and regulatory compliance burden.
- Franchise Dealerships:Manufacturer-authorized retailers with exclusive territory rights and facility standards. Digital integration lags in Germany's independent sector, creating aggregation opportunities for platform intermediaries.
- Independent Dealers:Non-affiliated retailers sourcing inventory through wholesale auctions and trade-ins. Price competition and lower overhead enable aggressive digital positioning, though warranty limitations constrain premium positioning.
- Online-Only Platforms:Digital-native operators controlling end-to-end fulfillment through proprietary logistics. Capital intensity and last-mile delivery economics favor metropolitan corridor concentration over rural penetration.
- Auctions:Wholesale exchange infrastructure connecting institutional sellers with dealer buyers. Physical auction migration to digital timed sales accelerates, with condition disclosure and arbitration protocols determining platform differentiation.
Scale concentration favors franchise dealerships; expansion velocity favors online-only platforms.
Customer Type:
Procurement sophistication spans individual convenience-seekers to enterprise fleet managers with specification standardization requirements.
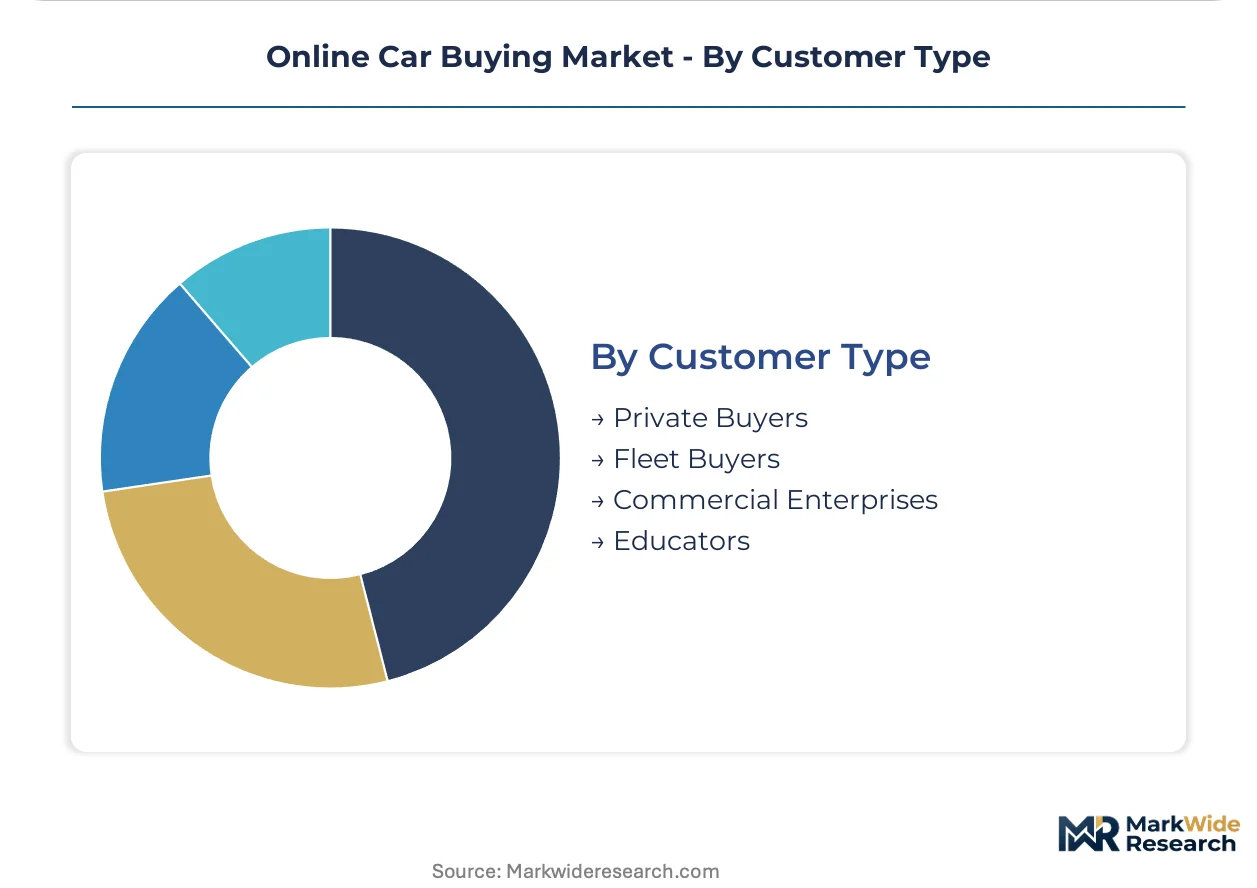
- Fleet Buyers:Commercial enterprises centralizing vehicle acquisition through digital channels to reduce overhead and standardize specifications across distributed operations. Telematics integration creates switching costs in the United States market.
- Private Buyers:Individual consumers seeking personal transportation with flexible payment and delivery preferences. Price sensitivity and trust formation around remote condition assessment dominate purchase friction.
- Commercial Enterprises:Non-fleet business purchasers acquiring vehicles for executive use or operational support. Smaller scale than fleet buyers, with less standardized specification requirements and shorter replacement cycles.
- Educators:Institutional purchasers including universities and school districts with specialized vehicle needs and public procurement compliance obligations. Budget constraints and competitive bidding requirements extend sales cycles.
Transaction volume favors private buyers; steepest expansion trajectory favors fleet buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers concentrate procurement in the United States, Germany, and China, where digital infrastructure and regulatory clarity enable platform adoption. Private buyers in these markets drive transaction volume through price-sensitive used vehicle acquisition.
United States
Telematics-enabled fleet management integration creates switching costs for incumbent platforms serving commercial enterprises. The FTC's Combating Auto Retail Scams rule mandates disclosure workflows for digital dealers operating across state lines. Dallas-Fort Worth and Atlanta anchor major reconditioning center networks where vehicle readiness timelines compress delivery windows.
Germany
Independent dealer digitalization lags behind franchise networks, creating white space for platform-enabled inventory aggregation. The EU AI Act imposes algorithmic accountability standards on automated credit scoring and vehicle pricing systems deployed nationwide. Bavaria's automotive engineering corridor hosts captive finance integration hubs connecting manufacturer-affiliated channels with lease origination platforms.
China
Domestic platforms handle massive transaction volumes through integrated super-app architectures combining search, financing, and logistics. SAMR enforces data localization requirements for buyer financial information and transaction records. Shanghai's Yangtze River Delta cluster concentrates proprietary logistics infrastructure controlling end-to-end fulfillment across major metropolitan zones.
United Kingdom
Price transparency tools attract digitally native buyers seeking configuration flexibility across new and certified pre-owned segments. GDPR compliance frameworks govern consumer data handling in integrated financing marketplaces. London's Southeast corridor aggregates inventory from franchise and independent sources through marketplace intermediaries.
Japan
Residual value forecasting models enable digital lease origination through captive finance integration. METI guidelines shape platform disclosure standards for automated valuation engines. Kanto's Tokyo metropolitan zone concentrates reconditioning expertise supporting cross-state commerce through computer vision-based damage detection workflows.
Online Car Buying Market Key Industry Players
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single operator commands dominant share. Digital-native platforms with proprietary logistics infrastructure vie against marketplace intermediaries aggregating third-party inventory. Two strategic archetypes define competitive positioning: end-to-end fulfillment operators and price-transparent aggregation platforms. Consolidation through strategic partnerships and geographic corridor concentration represent dominant competitive moves reshaping market structure.
Within the digital-native fulfillment tier, Carvana exemplifies channel-controlling architecture through metropolitan logistics networks, while CarGurus occupies a position exemplifying price-transparent marketplace aggregation. Amazon Autos anchors the e-commerce extension archetype, leveraging existing platform infrastructure to integrate search, financing, and delivery workflows. These three operators represent divergent strategic bets on whether buyers prioritize fulfillment control, price discovery, or ecosystem convenience.
| Leading Market Players |
|---|
| Autotrader |
| CarGurus |
| Carvana |
| Edmunds |
| Kelley Blue Book |
| CarMax |
| Cars.com |
| Amazon Autos |
| TrueCar |
| Others |
Cost & Logistics Intelligence
Metropolitan logistics corridors connecting Dallas-Fort Worth and Atlanta reconditioning centers concentrate vehicle readiness costs, compressing delivery timelines for premium-tier fulfillment while amplifying price spreads between urban-cluster and low-density postal code service levels. This geographic cost stratification feeds directly into platform pricing architecture, where integrated operators extract margin advantages through proprietary last-mile networks that independent aggregators cannot replicate.
Pricing Analysis
Cost-plus contracts with fuel indexation dominate fleet procurement agreements, embedding diesel price volatility into long-term service pricing. Three-tier pricing structure across premium, standard, and economy levels separates white-glove delivery with reconditioning guarantees from basic transport-only fulfillment. Cost compression in the economy tier is intensifying because single-vehicle transport economics deteriorate outside major metropolitan zones. Fleet buyers exhibit lowest price sensitivity due to telematics integration switching costs, while private buyers in rural markets face the highest sensitivity to delivery surcharges.
Supply Chain Analysis
Upstream feedstock for digital automotive retail draws from wholesale auction pipelines, captive lease returns, and institutional fleet remarketers concentrated in the United States, Germany, and China. Vehicle transport capacity, reconditioning labor pools, and title documentation services constitute critical input dependencies. Single-source vulnerability in automotive technician recruitment delays vehicle readiness and extends delivery windows. Distribution runs through hub-and-spoke reconditioning networks anchored by proprietary logistics infrastructure in major metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic accountability mandates constitute a regulatory inflection accelerating platform consolidation toward better-capitalized operators capable of explainable AI investment. This disruption creates asymmetric opportunity across stakeholder positions.
For Market Incumbents: Insulate market position by deepening captive logistics infrastructure in the United States metropolitan corridors where telematics integration creates switching costs for fleet buyers. Accelerate compliance architecture for EU AI Act audit trails before regulatory examination timelines harden. Prioritize reconditioning center staffing pipelines to compress vehicle readiness delays threatening delivery commitments. For New Entrants and Emerging Players: German independent dealer digitalization gaps offer immediate white-space penetration through platform-enabled inventory aggregation partnerships. Target certified pre-owned segments where manufacturer-backed warranty protocols reduce trust deficits that constrain uncertified used vehicle conversion. Deploy computer vision-based damage detection as differentiated trust-formation technology for cross-state commerce. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy dealership groups seeking digital capability acquisition without organic buildout timelines. Long-term viability centers on platforms controlling end-to-end fulfillment rather than marketplace intermediaries exposed to margin compression. Monitor FTC disclosure rule enforcement intensity as signal for compliance cost escalation favoring scaled operators.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Logistics Network Expansion | Metropolitan corridor concentration enables delivery timeline compression that independent aggregators cannot match. |
| Explainable AI System Investment | EU AI Act compliance creates audit trail differentiation against undercapitalized competitors facing regulatory examination. |
| Fleet Telematics Integration | Embedded switching costs in United States commercial procurement reduce customer churn and stabilize contract renewal rates. |
| Blockchain Title Verification Partnership | DMV system integration compresses lien-release timelines and accelerates ownership transfer velocity. |
| Reconditioning Center Automation | Computer vision damage detection reduces technician labor dependency and extends operational throughput per facility. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with digital platform executives, fleet procurement directors, and captive finance integration specialists, combined with secondary validation against SEC filings, vehicle registration databases, and EU regulatory disclosure repositories. Primary fieldwork captured operational metrics on reconditioning throughput, delivery cost structures, and algorithmic pricing system architecture. Bottom-up transaction volume estimates triangulated against top-down market sizing from production and registration data.
Forecast inputs incorporated vehicle class segmentation, payment method preference evolution, and dealer model channel shifts across the projection horizon. CAGRs derived from regression analysis of historical digital adoption curves applied to fleet procurement centralization trends and private buyer financing integration rates. Model sensitivity tested algorithmic accountability compliance cost scenarios and last-mile delivery economics variation by population density cluster.
Practitioners should monitor FTC enforcement intensity, EU AI Act examination timelines, and SAMR data localization implementation for early signals requiring forecast revision. Cross-checking against IHS Markit vehicle registration data and auction volume disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
North America Used Truck Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
UAE Used Cars Industry Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
Canada Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Hong Kong Used Car Market