
 Global Automotive Braking System Market | 2026-2036
Global Automotive Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Braking System Market Intelligence
Aftermarket distribution for replacement brake pads and rotors is fragmenting as e-commerce platforms and direct-to-garage channels erode traditional wholesaler networks. Robert Bosch GmbH leverages its captive sensor portfolio to bundle brake-by-wire modules with ESP controllers. Continental AG anchors European OEM supply through integrated electromechanical caliper production. Aisin Corporation specializes in compact drum brake assemblies for Asian compact vehicle platforms.
An automotive braking system integrates friction components, actuation mechanisms, and electronic control units to decelerate or immobilize a vehicle, with disc brakes typically employing cast iron or carbon-ceramic rotors paired with organic, semi-metallic, or ceramic friction formulations rated for specific temperature thresholds exceeding 300°C under sustained load. Its primary commercial purpose is to satisfy mandatory stopping-distance regulations while preserving driver control stability across variable road conditions. Disc brake configurations dominate value pools in passenger and performance segments due to thermal capacity requirements, while regenerative brake technology captures the fastest growth trajectory as battery-electric platforms expand. Hydraulic technology still occupies the majority of installed base, though electromechanical actuation is displacing vacuum-assisted systems in premium electric architectures.
The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 135, which mandates maximum stopping distances and fade resistance for service and emergency braking. Europe's ECE R90 and REACH regulations govern friction material composition and aftermarket replacement part homologation, while China's GB 7258 vehicle safety standard sets equivalent brake performance thresholds for domestic type approval. Stakeholders must monitor how brake-by-wire liability frameworks evolve alongside software-defined vehicle architectures.
Market Dynamics
Electromechanical brake-by-wire architectures are collapsing the century-old hydraulic vacuum-boost paradigm as battery-electric vehicle platforms eliminate engine-driven vacuum sources and demand software-defined deceleration control.
Growth Catalysts
- Regenerative braking integration:Battery-electric platforms from passenger cars to commercial vans now blend friction and regenerative deceleration, expanding module value per vehicle and requiring new thermal management architectures.
- ECE R90 homologation expansion:Europe's aftermarket brake lining certification now covers copper-free formulations, accelerating material transitions across supplier portfolios serving EU-27 type-approval markets.
- China's GB 7258 enforcement tightening:Domestic OEMs and joint-venture partners face stepped-up brake performance audits for new energy vehicle registrations, elevating qualification barriers for friction material suppliers.
Market Restraints
- Neodymium and copper supply concentration:Rare-earth magnet dependencies for electromechanical caliper motors concentrate in Chinese processing facilities, exposing European and North American module assemblers to export control volatility.
- Carbon-ceramic rotor cost floor:Chemical vapor infiltration cycles exceeding 200 hours per rotor set constrain cost-down trajectories for performance EV applications below premium price tiers.
- REACH substance restriction timeline uncertainty:ECHA's pending copper and antimony friction material limits create formulation lock-in risks for suppliers with multi-year homologation cycles.
Strategic Opportunities
- India's PLI scheme for automotive components:Localized brake module production for domestic OEMs and export markets gains fiscal support through the government's production-linked incentive framework.
- Software-defined vehicle liability frameworks:Emerging brake-by-wire certification standards create first-mover advantages for suppliers with embedded functional safety competencies.
- Direct-to-garage e-commerce channels:Independent repair networks in Germany and the United States are bypassing traditional wholesale distributors for certified aftermarket pad and rotor procurement.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D brake control system development requires embedded software and systems engineering talent pools concentrated in automotive electronics hubs.
- Legacy hydraulic-electromechanical integration complexity:Transitional vehicle architectures must maintain dual actuation systems during multi-year platform migration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Braking System Market |
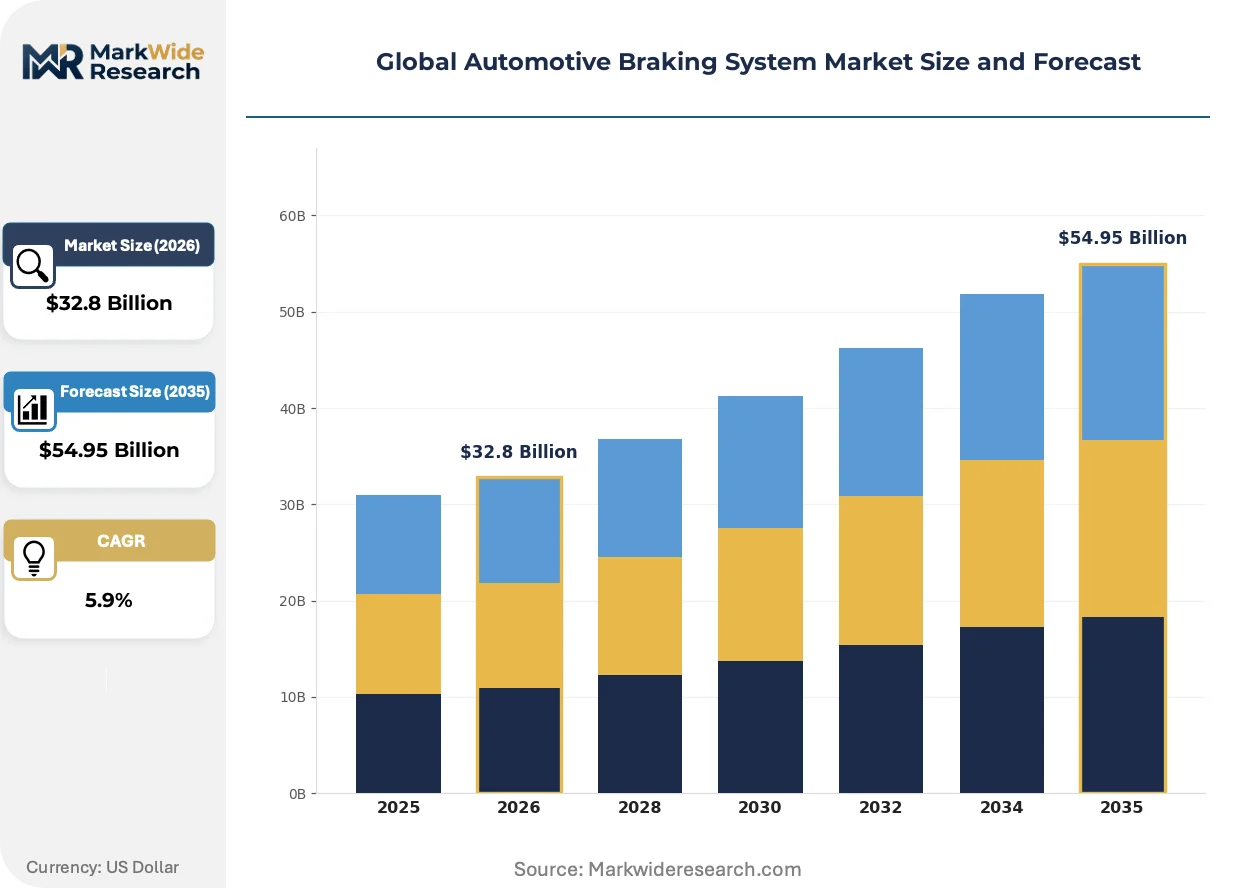
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.95 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brake, Drum Brake, Anti-lock Braking System, Electronic Brake-force Distribution, Brake Booster, Regenerative Brake Technology: Hydraulic, Pneumatic, Electric, Electromechanical, Vacuum, Vacuum-assisted Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-road Vehicles, Special Purpose Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Retailers, Vehicle Assemblers |
| Companies Covered | Brembo S.p.A, Hitachi Astemo Ltd., Robert Bosch GmbH, Mando Corporation, Aisin Corporation, Continental AG, Akebono Brake Industry Co. Ltd, Knorr-Bremse AG, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Braking System Market Strategic Shifts & Innovations
Brake system architectures are fragmenting into three parallel development tracks: friction materials optimized for regenerative blending, electromechanical actuation replacing hydraulic circuits, and embedded sensing enabling predictive maintenance.
Electromechanical brake-by-wire is collapsing the boundary between chassis control and powertrain management. Integrated motor-generator units now handle routine deceleration while friction brakes activate only for final stopping or emergency intervention. German premium OEMs are deploying this architecture across dedicated EV platforms, compressing supplier tier structures as caliper and controller functions merge into single-source modules.
REACH substance restrictions are forcing copper elimination from friction formulations ahead of 2025 enforcement windows. ECHA's candidate list expansion targets brake dust emissions for urban air quality compliance. European aftermarket suppliers are accelerating ceramic and organic matrix validation to maintain ECE R90 certification, while Asian export-oriented manufacturers face reformulation investments to retain EU market access.
Service contract unbundling is fragmenting traditional fleet procurement relationships. Commercial vehicle operators in the United States now source brake wear components through usage-based subscription models rather than bundled maintenance agreements. Independent telematics providers capture brake condition data, disintermediating OEM dealer networks for scheduled replacement scheduling and compressing supplier-direct channel development timelines.
Global Automotive Braking System Market Segmentation
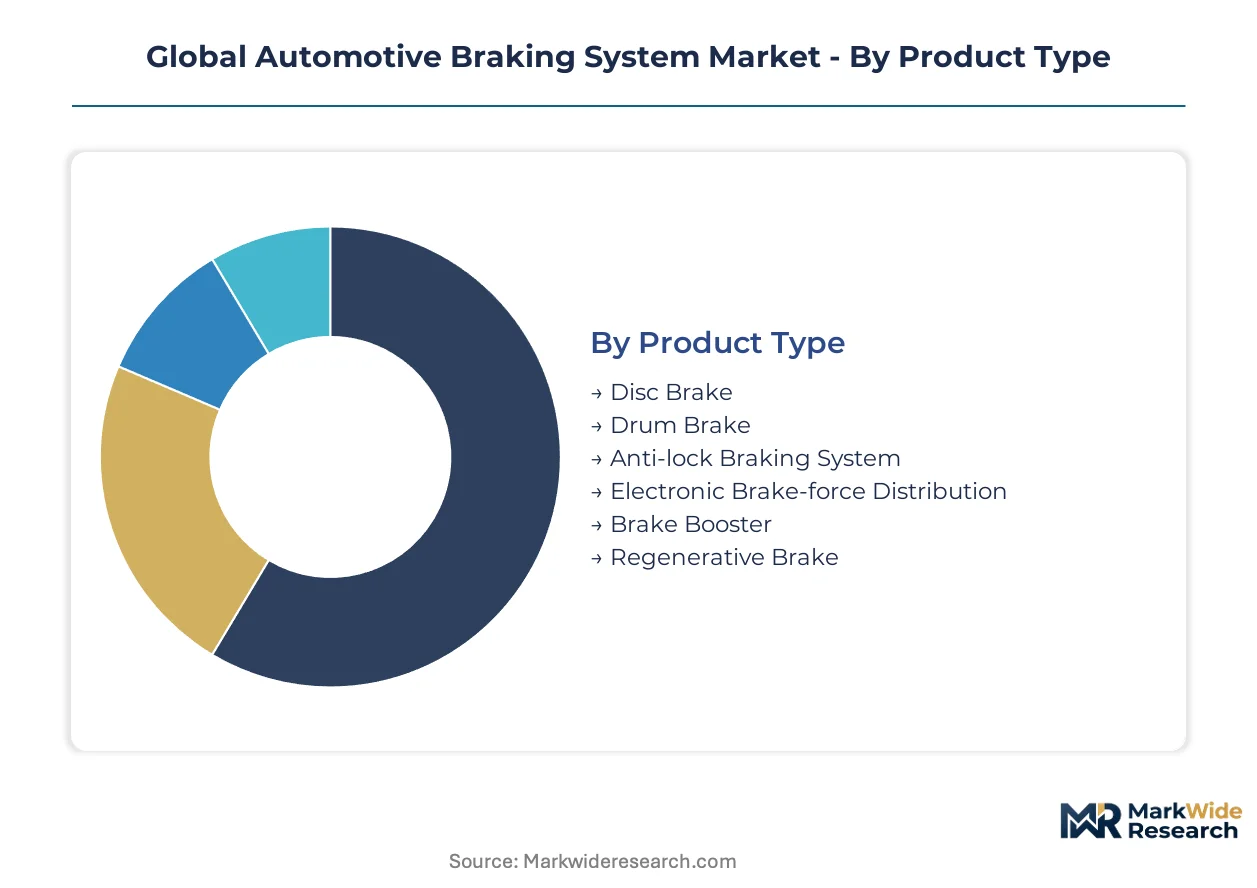
Brake system segmentation reveals divergent technology investment cycles across vehicle electrification trajectories. Product architecture choices determine thermal management requirements, actuation complexity, and supplier margin structures throughout the value chain.
Product Type:
Cost tier stratification separates commodity friction components from integrated electromechanical modules commanding premium positioning.
- Disc Brake:Cast iron or carbon-ceramic rotors paired with organic, semi-metallic, or ceramic friction formulations rated for sustained temperatures exceeding 300°C. Passenger and performance segments in Germany and the United States concentrate demand as thermal capacity requirements escalate with vehicle mass and speed ratings.
- Regenerative Brake:Integrated motor-generator units blending friction and electromagnetic deceleration through software-defined torque distribution. Battery-electric platforms from Chinese and German OEMs drive module value expansion per vehicle, requiring new thermal management architectures for blended braking scenarios.
- Drum Brake:Compact assemblies dominate Asian compact vehicle platforms where cost sensitivity outweighs thermal performance requirements.
- Anti-lock Braking System:Wheel-speed sensor networks preventing lock-up during emergency deceleration across all vehicle classes.
- Electronic Brake-force Distribution:Dynamic front-rear torque allocation optimizing stopping stability under variable load conditions.
- Brake Booster:Vacuum-assisted or electromechanical amplification reducing pedal effort requirements for driver ergonomics.
Disc brake architectures command the established base across passenger and commercial fleets. The steepest expansion runs through regenerative brake integration as electric platform volumes accelerate.
Technology:
Application context determines actuation method selection, with powertrain architecture eliminating legacy vacuum sources on dedicated EV platforms.
- Hydraulic:Pressurized fluid circuits transmitting pedal force to caliper pistons through master cylinder and ABS modulator valves. Global installed base concentration persists in internal combustion and transitional hybrid architectures where proven reliability offsets efficiency limitations.
- Electromechanical:Motor-driven caliper actuation eliminating hydraulic lines and enabling software-defined deceleration profiles. German premium OEM deployments on dedicated EV platforms compress supplier tier structures as caliper and controller functions merge.
- Electric:Solid-state motor control for brake-by-wire architectures with embedded functional safety to ISO 26262 ASIL-D standards.
- Pneumatic:Compressed air systems retaining dominance in heavy commercial vehicle categories requiring high-force actuation.
- Vacuum:Engine-driven aspiration systems facing obsolescence as battery-electric platforms eliminate intake manifold vacuum sources.
- Vacuum-assisted:Hybrid configurations bridging legacy infrastructure during multi-year platform migration cycles.
Hydraulic technology retains the volume base through transitional fleet turnover. The fastest technology transition occurs through electromechanical displacement as brake-by-wire certification standards mature.
Application:
Customer type segmentation aligns brake specification with duty cycle intensity, regulatory exposure, and total cost of ownership optimization priorities.
- Passenger Vehicles:Disc-dominant configurations with escalating copper-free friction material requirements under ECHA REACH substance restrictions. European and Chinese OEMs face stepped-up performance audits for new energy vehicle registrations, elevating qualification barriers for suppliers.
- Commercial Vehicles:Drum-pneumatic combinations in heavy-duty categories with emerging usage-based subscription procurement models displacing bundled maintenance agreements. United States fleet operators now source wear components through telematics-enabled direct channels.
- Two-Wheelers:Compact drum and single-disc architectures optimized for emerging market cost structures and urban maneuverability requirements.
- Off-road Vehicles:Sealed hydraulic systems engineered for contamination resistance in construction and agricultural duty cycles.
- Special Purpose Vehicles:Custom actuation configurations for emergency services, military, and industrial applications requiring non-standard performance envelopes.
Passenger vehicle demand anchors module production volumes. Commercial vehicle procurement transformation is gaining share fastest through service contract unbundling and telematics integration.
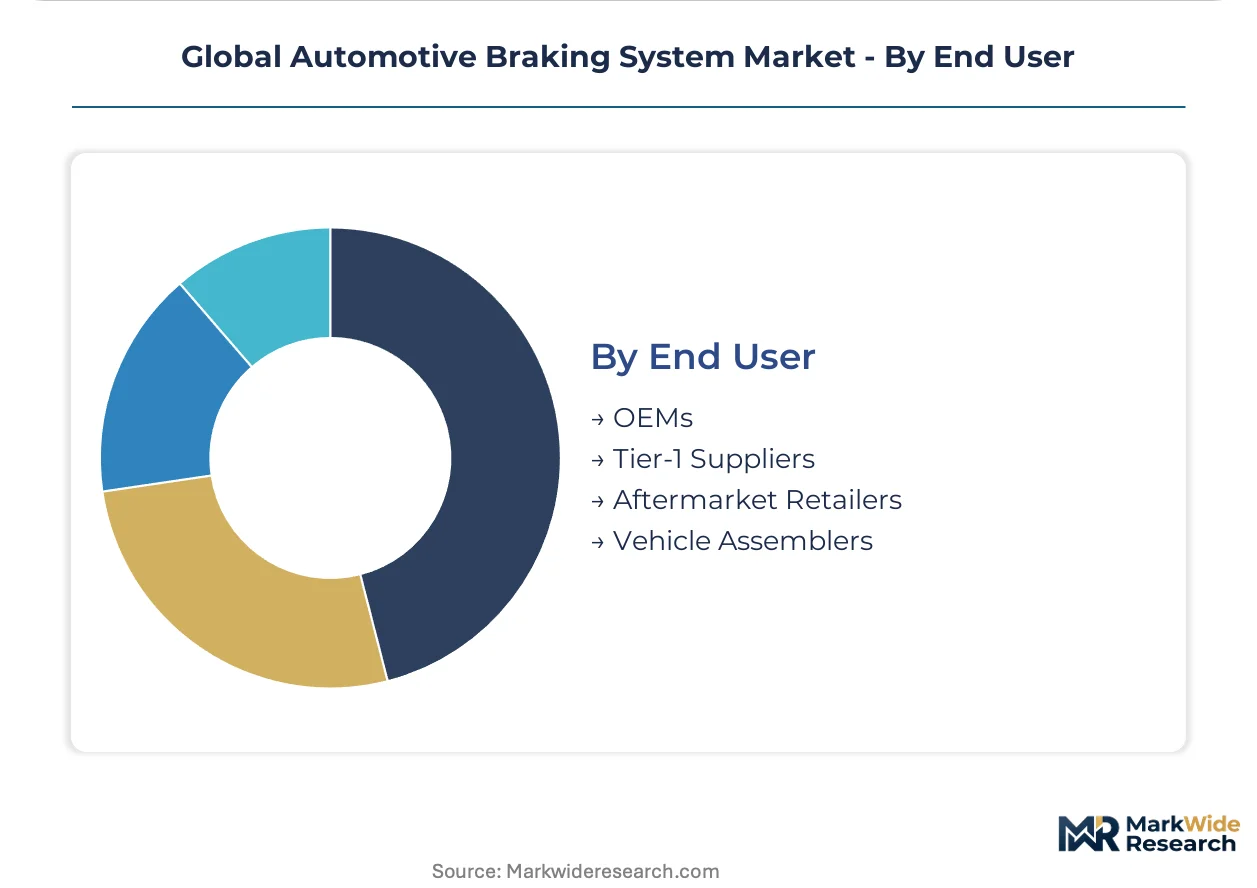
End User:
Supply concentration patterns differ sharply between captive OEM supply, tier-1 module integration, and fragmented aftermarket distribution channels.
- OEMs:Vehicle manufacturers specifying brake system architectures and qualifying suppliers against platform-specific thermal and functional safety requirements. German and Chinese OEMs consolidate sourcing around integrated electromechanical caliper-controller modules.
- Aftermarket Retailers:E-commerce platforms and direct-to-garage channels eroding traditional wholesaler networks in Germany and the United States. ECE R90 homologation expansion to copper-free formulations accelerates material transitions across supplier portfolios.
- Tier-1 Suppliers:Module assemblers managing rare-earth magnet dependencies for electromechanical caliper motors concentrated in Chinese processing facilities.
- Vehicle Assemblers:Contract manufacturing operations integrating qualified brake modules into final assembly sequences under OEM technical direction.
OEM qualification programs command the established supply relationships. Aftermarket channel restructuring is expanding most quickly through digital procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German electromechanical module supply while Chinese friction material exports compete on reformulation speed. Japanese sensor-caliper integration commands premium positioning in hybrid architectures. India's PLI subsidization is compressing landed costs for export-bound drum brake assemblies.
United States
Commercial fleet telematics adoption and NHTSA FMVSS 135 enforcement drive demand for fade-resistant disc configurations. The EPA's emerging brake dust particulate scrutiny shapes copper-free formulation roadmaps. Detroit-area module integration clusters concentrate electromechanical caliper-controller development for domestic OEM electrification platforms.
Germany
Premium EV platform volumes and KBA type-approval stringency elevate integrated brake-by-wire specifications. ECE R90 homologation expansion to copper-free formulations accelerates material portfolio transitions. Stuttgart and Munich engineering corridors concentrate functional safety talent for ISO 26262 ASIL-D system development.
China
Domestic NEV registration volumes and MIIT GB 7258 enforcement tightening reshape supplier qualification barriers. SAMR market access protocols for friction materials intensify homologation investments. Yangtze River Delta manufacturing clusters anchor electromechanical caliper motor production despite rare-earth processing concentration risks.
Japan
Hybrid powertrain brake blending requirements and METI carbon-neutrality roadmaps sustain regenerative architecture investment. JIS standard harmonization with UN regulations streamlines export certification pathways. Nagoya-area supplier networks specialize in compact sensor-integrated caliper modules for Asian compact vehicle platforms.
India
Domestic OEM localization mandates and PLI scheme fiscal support accelerate brake module manufacturing investments. BIS certification alignment with ECE R90 protocols enables export market access for friction material suppliers. Tamil Nadu and Gujarat automotive corridors concentrate drum brake assembly production for cost-sensitive compact segments.
Global Automotive Braking System Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in friction and sensor supply. The vendor base stratifies between captive OEM-aligned module assemblers and independent aftermarket distributors. Three archetypes dominate: integrated electromechanical system suppliers, friction material formulators, and sensor-electronics hybrid players. Competitive moves concentrate on backward integration into rare-earth magnet supply and functional safety engineering acquisition.
Within the integrated system tier, Robert Bosch GmbH and Continental AG exemplify platform-scale positioning through captive controller-caliper bundling. Aisin Corporation occupies a specialist position in compact drum brake architectures for Asian cost-optimized platforms. Brembo S.p.A anchors the performance-EV segment through carbon-ceramic thermal capacity leadership.
| Leading Market Players |
|---|
| Brembo S.p.A |
| Hitachi Astemo Ltd. |
| Robert Bosch GmbH |
| Mando Corporation |
| Aisin Corporation |
| Continental AG |
| Akebono Brake Industry Co. Ltd |
| Knorr-Bremse AG |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
Rare-earth magnet concentration in Chinese processing facilities determines both electromechanical module premium spreads and supplier geographic diversification imperatives. Neodymium dependency creates asymmetric pricing power where European and North American assemblers absorb volatility while Asian integrated producers capture margin.
Pricing Analysis
Configured-to-order pricing for brake-by-wire modules commands substantial premiums over standard hydraulic configurations. Three-tier pricing structure across premium, standard, and economy levels separates carbon-ceramic performance EV specifications from cast iron mass-market discs and compact drum assemblies. Price differentiation rests on ISO 26262 ASIL-D certification grade and thermal capacity ratings. Cost compression in copper-free friction formulations is intensifying because ECHA REACH enforcement accelerates reformulation investments. Aftermarket retailers exhibit highest price sensitivity; German premium OEMs show lowest sensitivity for integrated electromechanical sourcing.
Supply Chain Analysis
Extended payment terms from German and Chinese OEMs strain tier-2 magnet and copper alloy suppliers. Geographic supply concentration centers on China for rare-earth processing, Germany for electromechanical module assembly, and Japan for sensor-integrated caliper production. Raw material dependencies draw from neodymium-iron-boron magnets, copper-free friction substrates, and carbon-ceramic preforms. Single-source vulnerability in Chinese rare-earth refining exposes European module assemblers to export control volatility. Distribution runs through captive OEM supply chains for original equipment, with e-commerce platforms fragmenting aftermarket channels in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brake-by-wire electrification represents a high-growth disruption justified by ECE R90 copper-free homologation mandates collapsing legacy formulation portfolios. The technology transition compresses supplier tiers while elevating functional safety engineering premiums.
For Market Incumbents: Harden rare-earth magnet supply security through backward integration into alternative processing geographies or long-term offtake agreements with Australian and Vietnamese concentrate sources. Accelerate ISO 26262 ASIL-D certification investments to defend module integration positions against emerging electromechanical specialists threatening tier-1 relationships. For New Entrants and Emerging Players: Pursue India's PLI-subsidized manufacturing corridors for drum brake and friction material export production serving cost-sensitive Asian compact platforms. Target direct-to-garage e-commerce channels in Germany and the United States where traditional wholesale networks are disintermediating fastest, using ECE R90 copper-free certification as the go-to-market credential. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors functional safety engineering boutiques with embedded software competencies and rare-earth magnet trading positions. Long-term viability across the projection horizon rests on brake-by-wire liability framework clarity and OEM platform standardization decisions. Acquisition target archetype: electromechanical caliper specialists with captive controller development and existing German OEM qualification. Signal to watch: ECHA REACH substance restriction finalization dates for copper and antimony limits.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Standardization | Consolidates supplier tiers as German OEMs merge caliper and controller sourcing. |
| Rare-Earth Magnet Supply Agreement | Secures neodymium-iron-boron feedstock outside Chinese processing concentration. |
| Copper-Free Friction Certification | Maintains ECE R90 homologation access across EU-27 type-approval markets. |
| Direct-to-Garage Channel Development | Bypasses eroding wholesale networks in German and United States aftermarket. |
| Functional Safety Engineering Acquisition | Captures scarce ISO 26262 ASIL-D talent pools concentrated in Stuttgart and Munich. |
Research Approach
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and dealership operations anchored the qualitative base. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS 135 enforcement records, and ECHA REACH substance restriction filings. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand indicators.
Scenario-bracketing around technology adoption curves and regulatory enforcement timelines shaped the analytical framework. Segmentation dimensions modeled include vehicle propulsion architecture, brake system technology type, content per vehicle, OEM tier positioning, and regional production cluster. CAGRs derived from installed base turnover rates and electric platform penetration assumptions. Industry-specific forecast inputs incorporated GB 7258 enforcement intensity and ECE R90 homologation expansion scope.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, rare-earth export policy, or REACH enforcement timing would shift the trajectory. Forecasts reflect documented assumptions about technology substitution rates and regulatory implementation schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Safety Restraint Systems Market