
 Automotive Thermal Management Systems for Electric Vehicles Market | 2026-2036
Automotive Thermal Management Systems for Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Thermal Management Systems for Electric Vehicles Market Insights
Modular thermal packaging is expanding as OEMs shift from discrete component procurement to integrated battery-cabin-powertrain modules. Denso Corporation leverages its semiconductor-thermal integration expertise to dominate Japanese OEM supply chains. Valeo anchors European demand through its vertically controlled compressor and heat pump assembly lines. MAHLE GmbH competes with refrigerant-agnostic architectures that accommodate both R-1234yf and CO2 loops.
Automotive thermal management systems for electric vehicles comprise pumps, valves, heat exchangers, coolant loops, and control electronics engineered to maintain battery cells within 15-45°C operating windows while conditioning cabin air and cooling power electronics. Active systems lead installed value due to electric compressor and smart valve content, while phase change materials represent the fastest-growing technology segment as cell-to-pack architectures demand passive buffering against thermal runaway. Battery cooling commands the largest application share because lithium-ion degradation rates double for every 10°C excursion above optimal range.
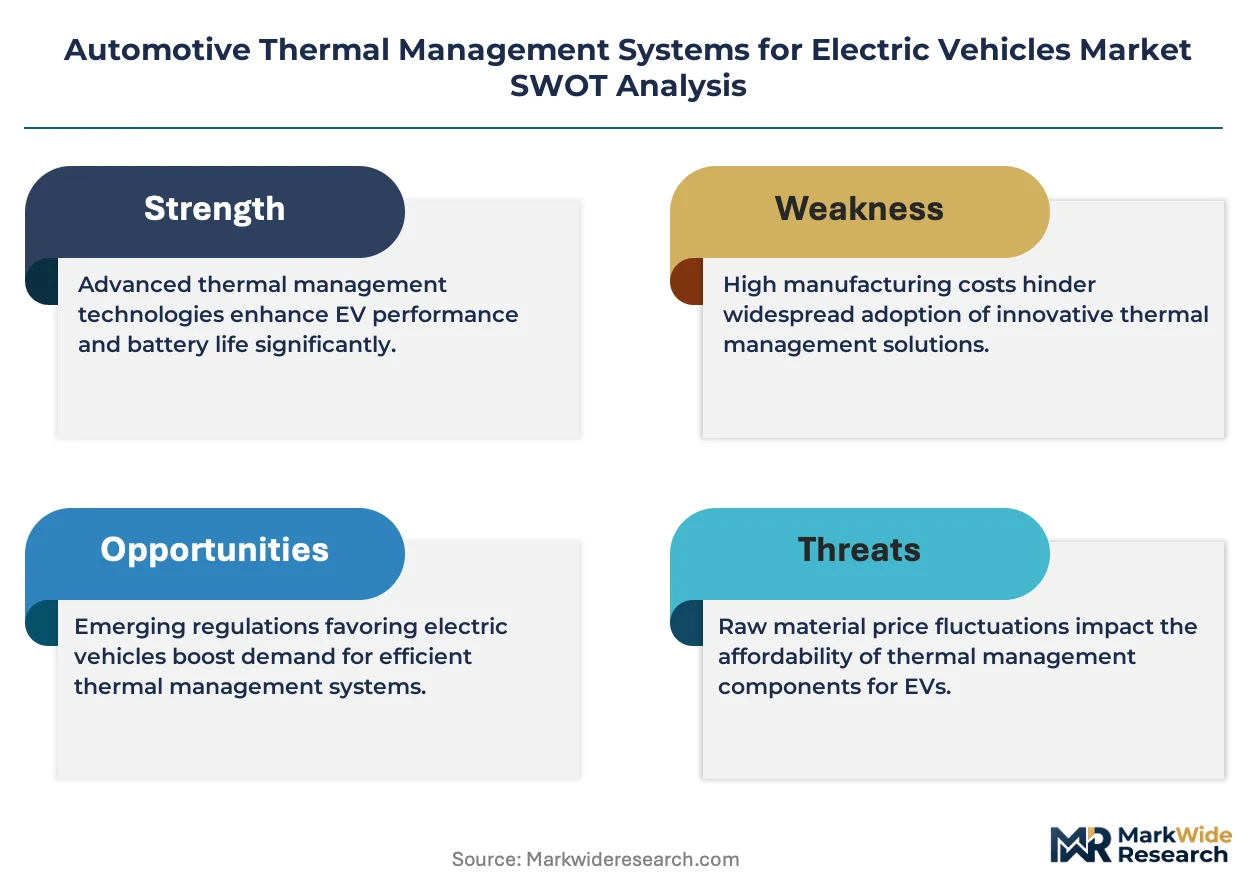
EPA tailpipe-equivalent rules and NHTSA safety standards shape US product specifications by mandating thermal runaway propagation containment, while EU F-Gas Regulation and REACH chemical restrictions force refrigerant transitions across European supply chains. China's GB standards and dual carbon goals establish domestic efficiency benchmarks that export-oriented suppliers must match. Stakeholders should monitor refrigerant chemistry transitions and solid-state battery thermal profiles as the next architecture inflection points.
Market Dynamics
Battery energy density trajectories above 300 Wh/kg are forcing thermal architectures toward cell-to-pack integration, compressing the design window for passive and active cooling systems simultaneously.
Growth Catalysts
- Cell-to-Pack Architectures:OEMs consolidating battery housings into structural elements require integrated thermal modules that combine cooling plates, phase change materials, and sensor arrays in single assemblies.
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants mandates CO2 heat pump adoption across European EV platforms, accelerating supplier retooling toward transcritical loop expertise.
- China's Dual Carbon Goals:Domestic efficiency benchmarks under GB standards are pushing NEV manufacturers toward intelligent thermal management with predictive battery conditioning algorithms.
Market Restraints
- Copper and Aluminum Price Volatility:Heat exchanger and busbar materials face commodity swings that compress module margins before long-term supply agreements stabilize input costs.
- Compressor Supply Concentration:Electric compressor manufacturing clusters in Japan and South Korea create geographic vulnerability for European and North American OEMs seeking dual-source strategies.
- Refrigerant Transition Friction:The technical gap between R-1234yf infrastructure and CO2 system requirements forces parallel engineering tracks that dilute R&D efficiency.
Strategic Opportunities
- Solid-State Battery Thermal Profiles:Next-generation chemistries with reduced cooling loads will enable simplified loop architectures and lighter packaging for premium EV segments.
- India's PLI Scheme for Auto Components:Localized thermal module production incentives are opening supplier establishment pathways in Chennai and Pune manufacturing corridors.
- Vehicle-to-Grid Integration:Bidirectional charging infrastructure creates demand for thermal systems capable of managing battery heat during extended discharge cycles in stationary applications.
Industry Challenges
- Systems Integration Engineering Gap:The shortage of engineers fluent in both thermal physics and battery electrochemistry delays development cycles for integrated module suppliers.
- Multi-Refrigerant Certification Burden:Suppliers must maintain parallel validation protocols for R-1234yf, CO2, and emerging low-GWP blends across overlapping regional regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Thermal Management Systems for Electric Vehicles Market |
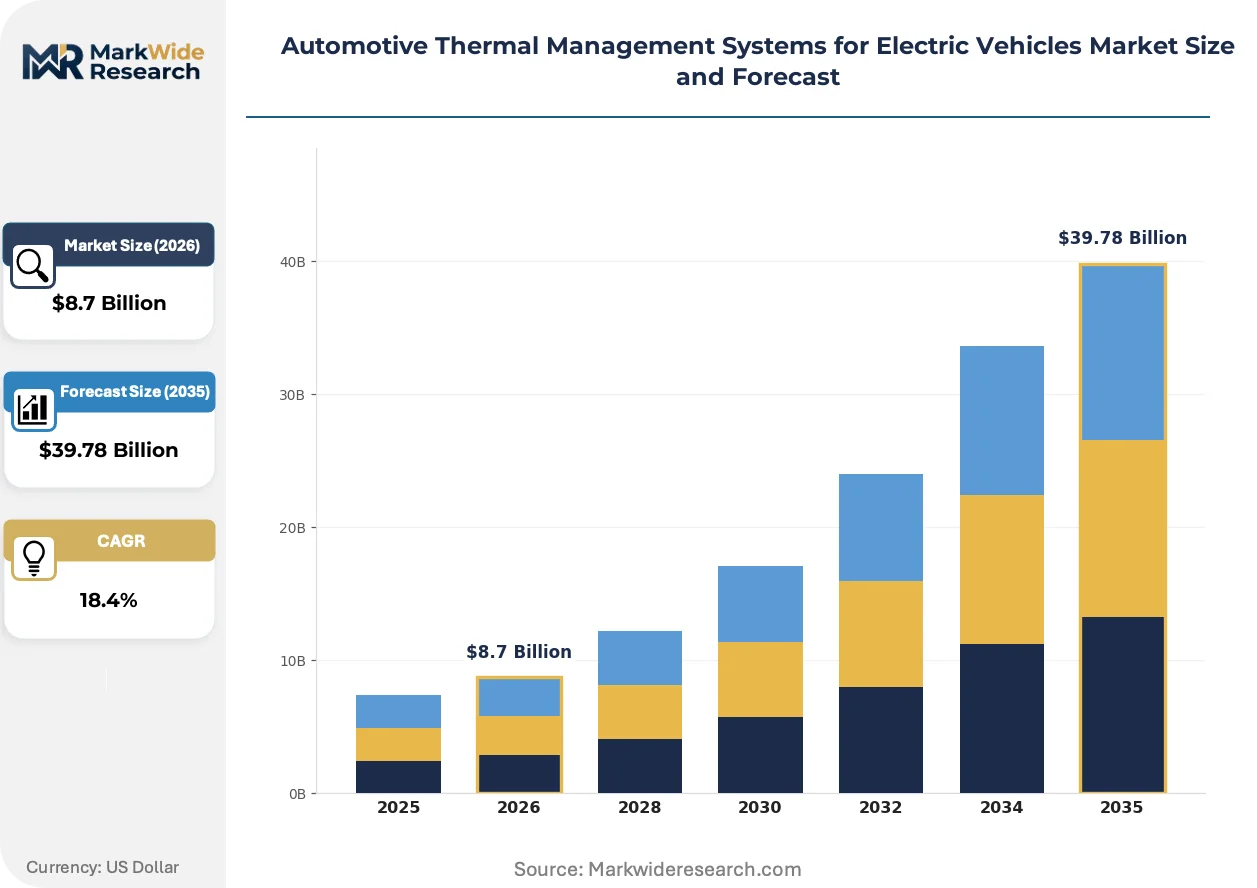
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Hybrid Systems, Heat Exchangers Technology: Phase Change Materials, Electric Heaters, Refrigerant Systems, Thermal Oil Application: Battery Cooling, Cabin Heating, Power Electronics Cooling, Drive Unit Cooling End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions |
| Companies Covered | Denso Corporation, Valeo, MAHLE GmbH, Continental AG, BorgWarner Inc., Hanon Systems, Gentherm Incorporated, Modine Manufacturing Company, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Thermal Management Systems for Electric Vehicles Market Trends and Innovations
Smart thermal architectures are absorbing functions from discrete controllers into domain-consolidated electronics, compressing component counts while enabling predictive battery conditioning based on route and charging data.
Phase change material composites are absorbing latent heat spikes during fast-charging events, enabling 350 kW charge rates without active cooling oversizing. Cell-to-pack battery designs from Korean and Chinese OEMs are embedding paraffin-graphite matrices between cell layers. This absorption of thermal buffering into structural elements is displacing separate cold plate assemblies in next-generation platforms.
The EU F-Gas Regulation's 2030 phase-down targets for fluorinated gases are forcing refrigerant infrastructure conversions across European supplier parks. Component manufacturers in Stuttgart and Munich are retooling compressor lines for transcritical CO2 operation. Passenger EV heat pumps face the steepest compliance burden, as mobile air conditioning systems must demonstrate GWP below 150 under certified test cycles.
Fleet operators are consolidating thermal system procurement under total-cost-of-ownership frameworks rather than upfront component pricing. Leasing companies and ride-hail platforms in Germany and California now specify battery degradation guarantees tied to thermal management performance. This contractual shift is compressing supplier margins on initial sales while extending revenue capture through service and monitoring subscriptions.
Automotive Thermal Management Systems for Electric Vehicles Market Segmentation
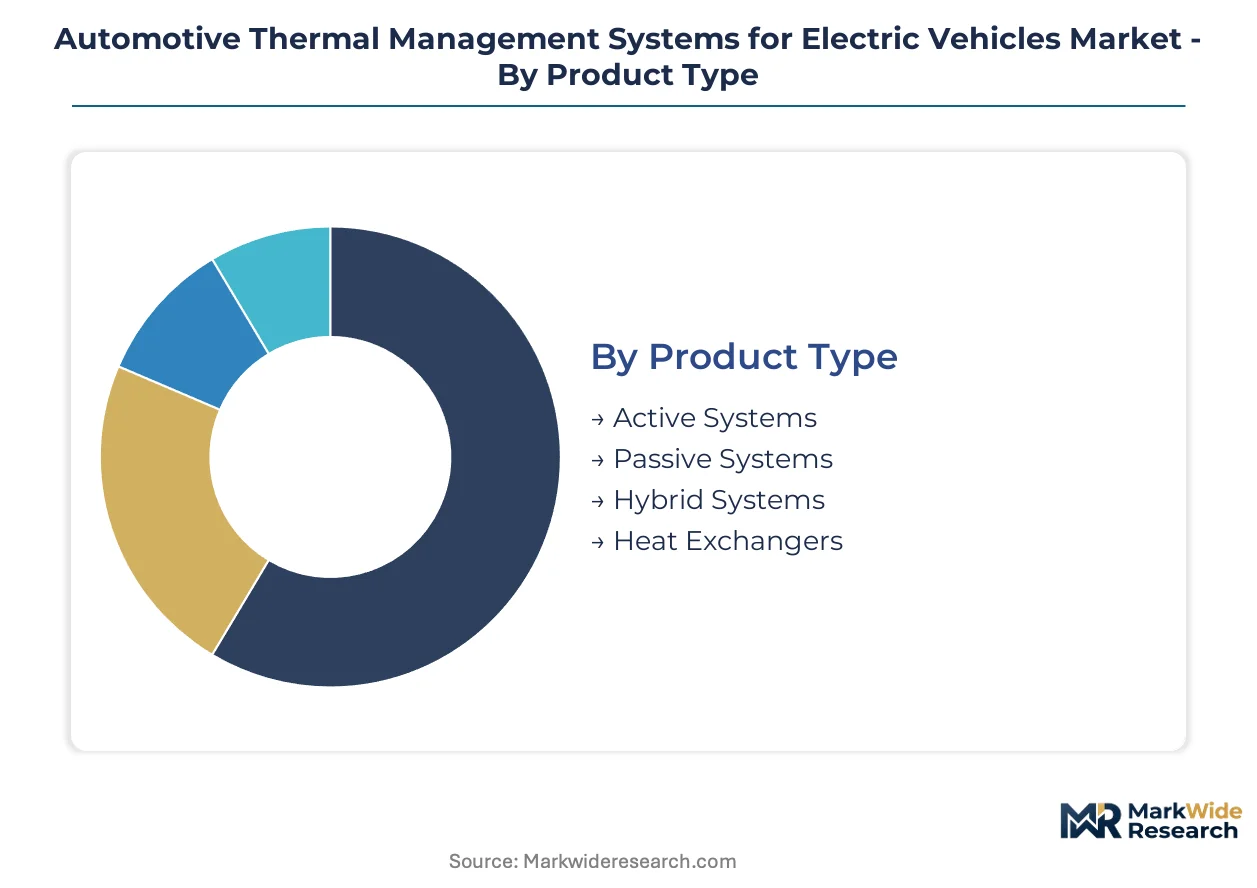
Thermal management procurement splits across engineering specifications, refrigerant chemistry, and vehicle integration depth. Buyers in premium passenger EVs prioritize integrated modules with predictive algorithms, while commercial fleet operators emphasize serviceability and total-cost guarantees.
Product Type:
OEMs differentiate procurement strategies based on the balance between energy efficiency and manufacturing complexity.
- Active Systems:Electric compressors, smart valves, and pump assemblies deliver precise temperature control through software-driven coolant routing. Battery cooling for 800V architectures in Germany's Stuttgart engineering corridor demands these systems for fast-charge thermal stability.
- Passive Systems:Phase change materials and thermal mass elements absorb heat spikes without energy consumption. Cell-to-pack designs from Korean OEMs embed paraffin-graphite matrices, displacing separate cold plates in next-generation platforms.
- Hybrid Systems:Combine active pumping with passive buffering for load-peak shaving.
- Heat Exchangers:Aluminum-brazed plate-and-fin assemblies transfer thermal energy between loops.
Volume sits with Active Systems; growth tilts toward Hybrid Systems.
Technology:
Material selection tracks battery chemistry evolution and regional refrigerant regulations.
- Phase Change Materials:Latent heat absorption during 350 kW fast-charging events enables thinner cooling packaging. Chinese cell-to-pack architectures under GB standards embed these composites between cell layers.
- Electric Heaters:High-voltage PTC and heat pump elements condition cabin air in cold climates. Nordic EV platforms specify these for sub-zero range preservation.
- Refrigerant Systems:R-1234yf and CO2 transcritical loops face EU F-Gas Regulation phase-down deadlines.
- Thermal Oil:Dielectric fluids cool power electronics in sealed immersion configurations.
Revenue concentrates in Refrigerant Systems; steepest expansion trajectory belongs to Phase Change Materials.
Application:
Integration depth varies by the thermal sensitivity of protected subsystems.
- Battery Cooling:Maintains lithium-ion cells within 15-45°C windows to prevent degradation doubling per 10°C excursion. Munich-based OEMs specify combined cooling plate and sensor arrays for structural battery housings.
- Cabin Heating:Heat pump systems extract thermal energy from ambient air and powertrain waste heat. EU CO2 heat pump mandates are accelerating transcritical loop adoption across European platforms.
- Power Electronics Cooling:IGBT and SiC inverter modules require dielectric fluid or two-phase immersion.
- Drive Unit Cooling:Motor and gearbox lubricant thermal management extends bearing life.
Deployment volume favors Battery Cooling; technology investment flows toward Cabin Heating.
End User:
Contract structures and specification authority differ sharply across buyer categories.
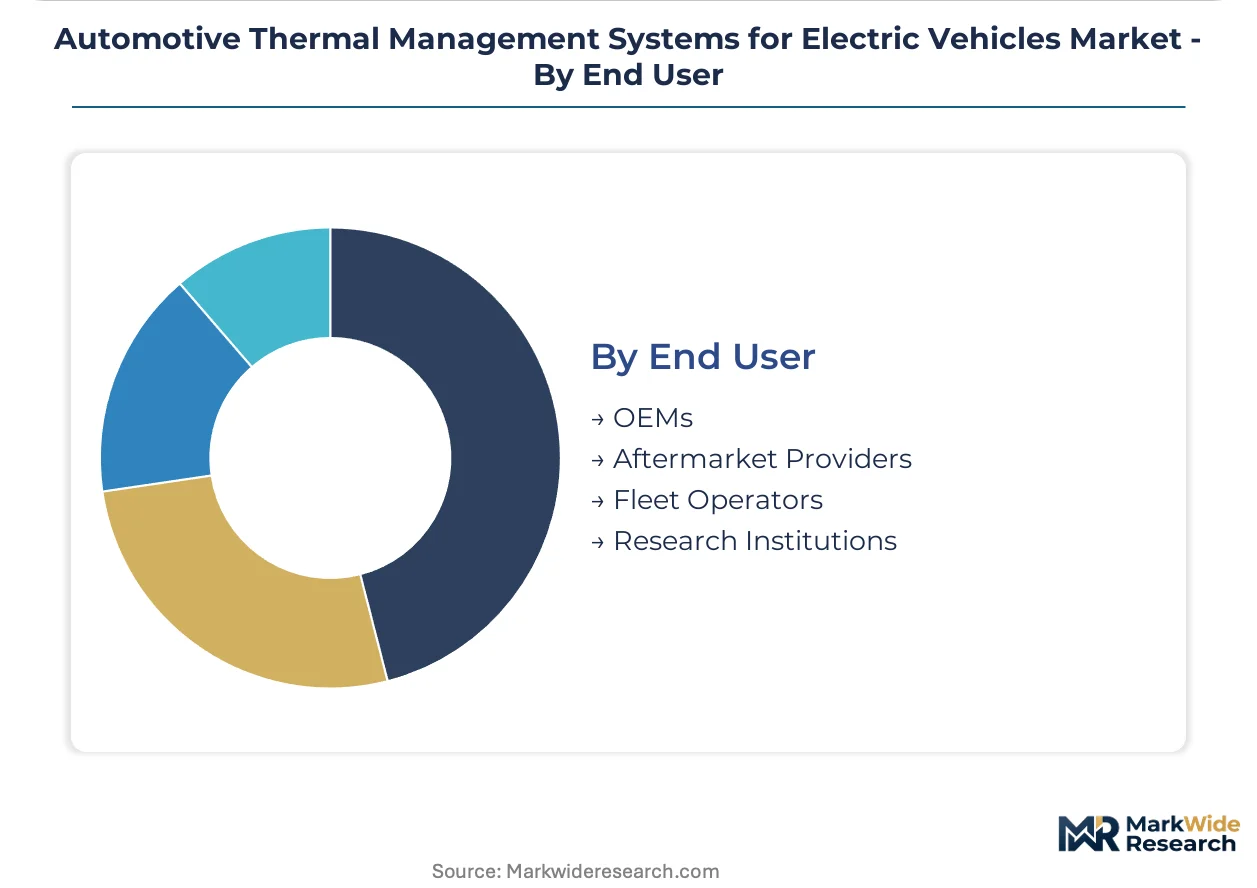
- OEMs:Integrated thermal module procurement combines cooling plates, sensors, and control electronics in single assemblies. Premium passenger EV manufacturers in Germany and China are consolidating suppliers for cell-to-pack architectures.
- Fleet Operators:Total-cost-of-ownership frameworks now tie battery degradation guarantees to thermal performance. German and California ride-hail platforms specify monitoring subscriptions alongside hardware.
- Aftermarket Providers:Service replacement of pumps, valves, and compressors in out-of-warranty vehicles.
- Research Institutions:Validation testing for next-generation solid-state battery thermal profiles.
Specification authority rests with OEMs; contract innovation emerges from Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of automotive thermal management systems clusters in manufacturing corridors serving major EV assembly regions, while consumption patterns track battery plant investments and fleet electrification mandates across distinct national markets.
China
NEV manufacturers under GB standards are embedding phase change materials into cell-to-pack architectures, with procurement concentrated around Shanghai and Shenzhen engineering centers. SAMR efficiency certifications are tightening subsystem requirements. The Yangtze River Delta hosts integrated thermal module production serving domestic OEMs and export markets.
Germany
Stuttgart and Munich anchor European demand for 800V battery cooling systems, with OEMs specifying combined cooling plate and sensor arrays. The EU F-Gas Regulation mandates CO2 heat pump adoption by 2030. Supplier parks around Wolfsburg and Ingolstadt are retooling compressor lines for transcritical loop operation.
United States
EPA tailpipe-equivalent rules and NHTSA thermal runaway containment standards shape product specifications for Detroit Three platforms. Michigan-based engineering centers specify predictive battery conditioning algorithms. The Southeast manufacturing corridor is attracting thermal module assembly investments to serve regional battery plants.
South Korea
Cell-to-pack designs from domestic OEMs embed paraffin-graphite matrices, displacing separate cold plate assemblies. MFDS-aligned safety protocols influence thermal architecture validation. The Busan-Ulsan industrial belt concentrates electric compressor manufacturing for export to European and North American OEMs.
Japan
METI-supported R&D programs advance semiconductor-thermal integration for next-generation power electronics. Domestic OEMs procure integrated modules combining coolant routing with domain-consolidated controllers. The Nagoya manufacturing hub maintains specialized capacity for high-voltage heat pump assemblies.
Automotive Thermal Management Systems for Electric Vehicles Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base organizes around three strategic archetypes: integrated system suppliers controlling compressor and heat pump assembly lines, component specialists mastering refrigerant-agnostic architectures, and semiconductor-thermal integrators leveraging electronics expertise. Dominant competitive moves include backward integration into heat exchanger manufacturing and technology licensing partnerships for CO2 transcritical systems.
Within the integrated system tier, Denso Corporation and Valeo occupy anchor positions exemplifying divergent geographic strategies. Denso represents Japanese OEM supply chain dominance through semiconductor-thermal integration capabilities. Valeo anchors European demand through vertically controlled manufacturing footprints. MAHLE GmbH sits within the refrigerant-agnostic specialist archetype, accommodating multiple chemistry loops without platform lock-in.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo |
| MAHLE GmbH |
| Continental AG |
| BorgWarner Inc. |
| Hanon Systems |
| Gentherm Incorporated |
| Modine Manufacturing Company |
| Robert Bosch GmbH |
| Others |
Pricing and Supply Chain Analysis
Performance-tier bifurcation between 800V active cooling systems and commodity 400V modules manifests in divergent margin structures and supplier footprints across the automotive thermal management landscape. Premium integrated thermal modules command value-based pricing through predictive algorithm content and structural battery integration, while standard-tier suppliers compete on aluminum cold plate unit economics with thinner engineering margins and geographically dispersed stamping operations.
Pricing Analysis
Cost-down pressure on standard-tier heat exchanger assemblies accelerates because Chinese cell-to-pack architectures are consolidating procurement volumes under long-term offtake agreements with embedded phase change material suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under GB standards and EU F-Gas Regulation compliance timelines, with fleet operators in Germany and California exhibiting highest price sensitivity through total-cost-of-ownership frameworks that discount upfront hardware against degradation guarantees.
Supply Chain Analysis
Engineering workforce availability constraints in Stuttgart, Munich, and Nagoya manufacturing corridors are compressing development cycle timelines for integrated thermal module suppliers competing on CO2 transcritical loop expertise. Component sourcing draws from South Korean electric compressor clusters, Chinese aluminum brazing facilities, and Japanese semiconductor-thermal integration specialists, with single-source vulnerability around high-voltage heat pump controllers creating geographic concentration risk. Distribution runs through Tier 1 supplier parks co-located with OEM battery assembly plants in the Yangtze River Delta and Southeast US manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive thermal management sector sits in a refrigerant-transition phase, with CO2 transcritical loops displacing R-1234yf infrastructure across European supply chains and forcing parallel engineering investments.
For Market Incumbents: Cement compressor and heat pump assembly line dominance through backward integration into aluminum heat exchanger manufacturing and captive sensor array production. Denso Corporation and Valeo anchor positions face emerging threat from refrigerant-agnostic specialists like MAHLE GmbH that accommodate multiple chemistry loops without platform lock-in; priority lever rests on CO2 system certification investment ahead of EU F-Gas Regulation deadlines. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels offer white-space access around battery degradation guarantee contracts and thermal performance monitoring subscriptions. India's PLI scheme for auto components presents the most penetrable geography, with localized module production incentives in Chennai and Pune manufacturing corridors enabling cost-competitive entry through predictive conditioning algorithm licensing rather than hardware manufacturing. For Investors and Strategic Acquirers: Re-rating potential sits with refrigerant-agnostic component specialists given EU F-Gas Regulation phase-down acceleration and multi-refrigerant certification burden concentration. Long-term viability favors suppliers with transcritical CO2 loop validation capabilities and solid-state battery thermal profile development pipelines; signal to watch is OEM platform standardization announcements that consolidate thermal module procurement under single-source integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Loop Certification | EU F-Gas Regulation compliance unlocks European OEM platform access ahead of 2030 deadlines. |
| Cell-to-Pack Thermal Integration | Korean and Chinese OEM architectures embed cooling plates directly into structural battery housings. |
| Predictive Algorithm Development | Route and charging data enable battery conditioning that extends cell life under GB standard efficiency benchmarks. |
| Phase Change Material Manufacturing Scale-Up | Paraffin-graphite matrix production capacity determines fast-charge thermal buffering market share. |
| Semiconductor-Thermal Domain Consolidation | Controller integration into coolant routing modules reduces component counts for Japanese OEM supply chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and thermal systems R&D directors with bottom-up and top-down triangulation. Secondary validation drew from NHTSA safety standard documentation, EU F-Gas Regulation implementation reports, SAMR efficiency certification databases, and vehicle production registration data across the analysis window.
Segment-level modeling tracked propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster dimensions throughout the forecast period. CAGRs derived from installed base growth, replacement cycle timing, and technology transition curves across active, passive, and hybrid thermal system categories. Industry-specific inputs included battery energy density trajectories, refrigerant chemistry adoption rates, and cell-to-pack architecture penetration by OEM geography.
The model holds under stable copper and aluminum commodity conditions and consistent regulatory phase-down timelines; deviation in raw material price volatility or refrigerant transition acceleration would shift supplier margin and technology investment trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Washer System Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Brake Pad Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
China Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Global Automotive Muffler Tip Market