
 Automotive Lifts Market | 2026-2036
Automotive Lifts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lifts Market Insights
China is narrowing its cost advantage in automotive lift manufacturing as domestic labor rates rise and environmental compliance costs mount. BendPak leverages vertical integration across its California and Alabama facilities to control steel fabrication and hydraulic component sourcing. Rotary Lift sustains technology leadership through proprietary spotting technology integrated into its inground and above-ground lift portfolios. Hunter Engineering competes on precision alignment integration, bundling lift systems with diagnostic and calibration equipment for dealership service bays.
Automotive lifts are electro-hydraulic or mechanically actuated elevation platforms designed to raise vehicles for inspection, maintenance, repair, or storage, typically rated by lifting capacity measured in pounds or tons and governed by safety standards for structural integrity and locking mechanism reliability. Two-post lifts dominate independent automotive shops due to their footprint efficiency and direct wheel access, while four-post lifts anchor higher-margin segments serving storage and alignment applications where stability under load is paramount. Scissor lifts are gaining traction among fleet service providers servicing electric commercial vehicles, as their low-profile collapsed height accommodates battery-heavy chassis geometries without pit excavation.
OSHA and ANSI standards in the United States mandate periodic inspection and load-testing protocols that accelerate replacement cycles for aging lift installations. The EU Machinery Directive and CE marking requirements enforce design safety assessments that filter out non-compliant imports from European distribution channels. Stakeholders must monitor how evolving electric vehicle platform weights and battery placement geometries reshape capacity and clearance specifications across lift portfolios.
Market Dynamics
Electric vehicle platform weights are forcing capacity recalibration across lift portfolios, as battery-heavy chassis geometries exceed legacy rating thresholds and demand reinforced structural members.
Growth Catalysts
- Fleet electrification mandates:Commercial vehicle operators in California and Germany are retrofitting service bays to accommodate electric bus and truck maintenance, driving scissor lift demand for low-profile battery access.
- OSHA inspection protocols:Mandatory load-testing cycles for above-ground equipment are compressing replacement timelines and sustaining aftermarket revenue streams for certified service providers.
- Workshop modernization in Germany:Aging independent automotive facilities are replacing hydraulic systems with electro-hydraulic platforms to meet EU Machinery Directive safety assessments.
Market Restraints
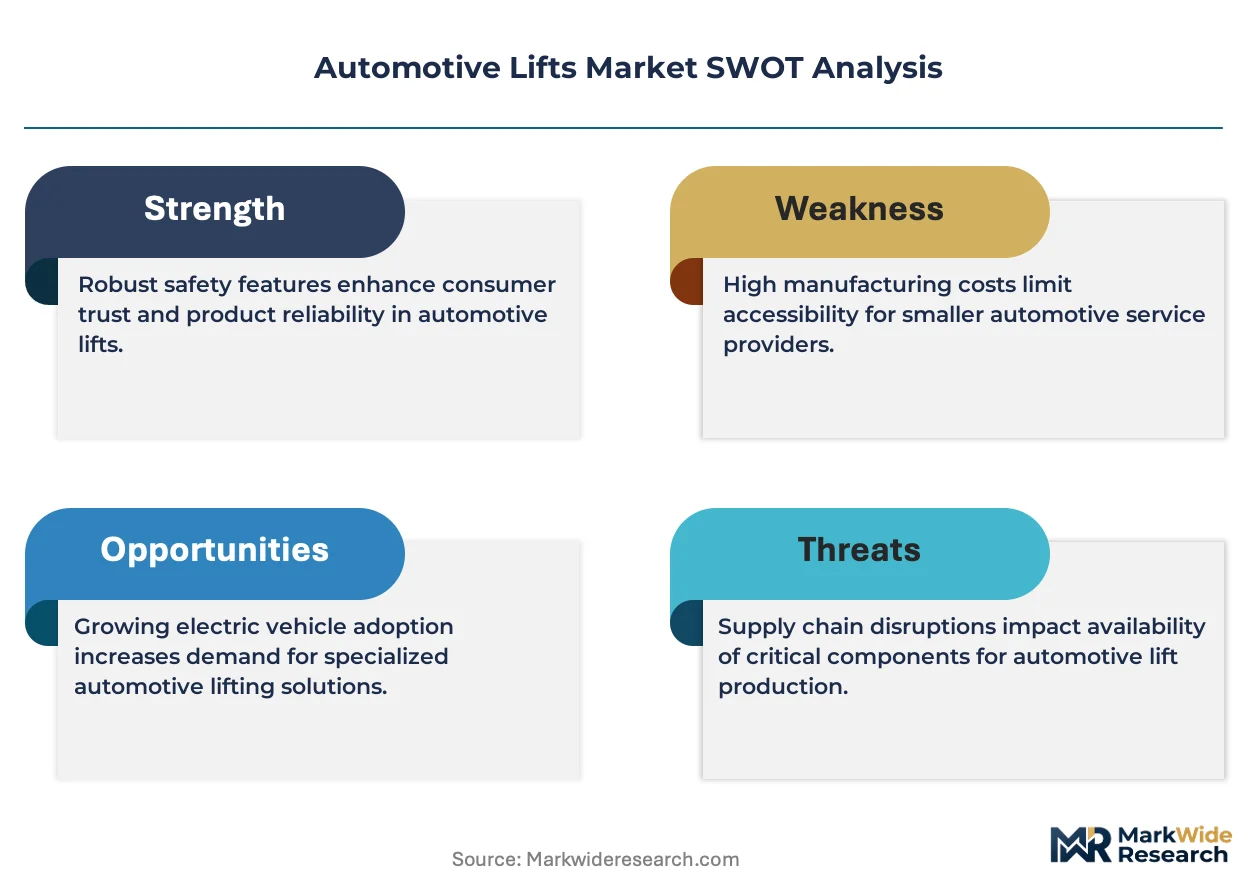
- Steel price volatility:Structural steel and hydraulic cylinder inputs face fluctuating commodity costs that compress margin predictability for fabricators without captive supply arrangements.
- Supply concentration in China:Hydraulic component sourcing clusters in Zhejiang and Jiangsu provinces create vulnerability to export documentation delays and environmental compliance enforcement.
- Substitution by mobile column lifts:Heavy-duty fleet operators are adopting portable lift configurations for irregular maintenance schedules, displacing fixed installation demand in certain commercial segments.
Strategic Opportunities
- India aftermarket expansion:Organized multi-brand service chains in Maharashtra and Karnataka are standardizing on four-post alignment lifts as vehicle parc ages and dealership networks extend.
- ISO 9001 convergence with predictive maintenance:Sensor-integrated lift systems that feed diagnostic data into workshop management platforms are capturing premium positioning in German and Japanese markets.
- Direct-to-workshop distribution:E-commerce procurement channels are disintermediating traditional equipment distributors for standardized two-post configurations in North American independent shops.
Industry Challenges
- Certified technician scarcity:Hydraulic system diagnostics and ANSI-compliant installation protocols require specialized training that outpaces vocational program output in several manufacturing regions.
- Legacy pit infrastructure:Inground lift replacement in established facilities demands concrete excavation and structural reinforcement that extends project timelines and customer decision cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lifts Market |
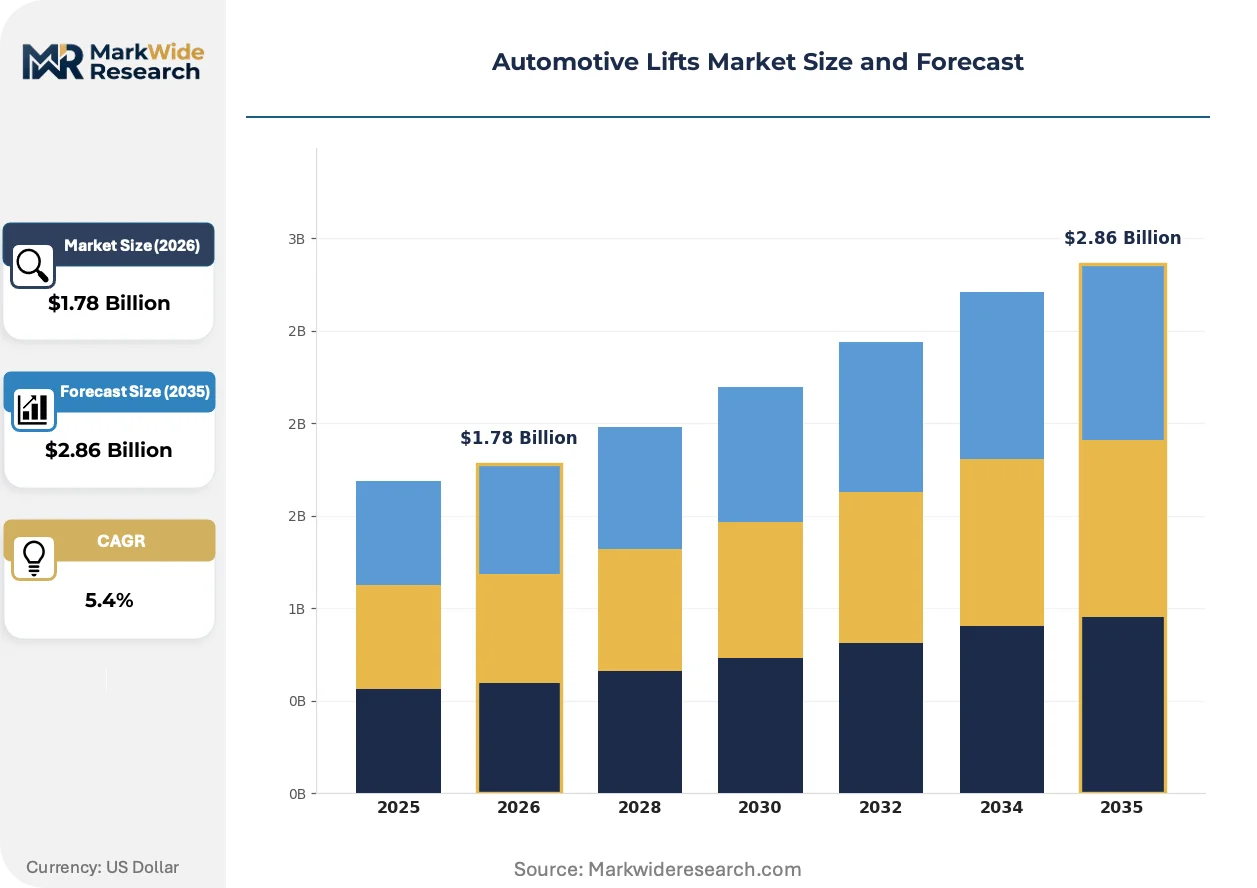
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Post Lifts, Four-Post Lifts, Scissor Lifts, In-Ground Lifts End User: Automotive Shops, Car Dealerships, Fleet Service Providers, Home Garage Owners Technology: Hydraulic, Electric, Pneumatic, Mechanical Capacity: Light-Duty, Medium-Duty, Heavy-Duty, Specialty |
| Companies Covered | BendPak, Rotary Lift, Hunter Engineering, Stertil-Koni, Nussbaum, Mohawk Lifts, Challenger Lifts, ARI-HETRA, MAHA Maschinenbau Haldenwang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lifts Market Trends and Innovations
Lift technology is converging with vehicle diagnostic systems and workshop software platforms, transforming standalone elevation equipment into integrated service nodes that capture operational data and enable predictive maintenance workflows.
Electro-hydraulic actuation is hybridizing with mechanical locking systems to combine precision height control with failsafe redundancy for electric vehicle battery servicing. Fleet operators in Germany and California are specifying these configurations for commercial electric van maintenance. The technology is hybridizing procurement criteria by merging traditional capacity ratings with connectivity and data-export capabilities.
EU Machinery Directive enforcement through CE marking requirements is filtering non-compliant imports from European distribution channels and elevating documentation burdens for Asian manufacturers. Third-party notified body assessments now extend to software safety functions in sensor-integrated platforms. German commercial workshops are responding by consolidating supplier relationships with established European brands possessing existing conformity infrastructure.
Certification-driven purchasing is compressing evaluation cycles as workshop operators prioritize ANSI and OSHA documentation over price differentiation. Independent automotive shops in the United States are unbundling installation and inspection services from equipment procurement, creating specialized regional service providers. This pattern is most visible in Texas and Florida where rapid facility expansion outpaces manufacturer direct service capacity.
Automotive Lifts Market Segmentation
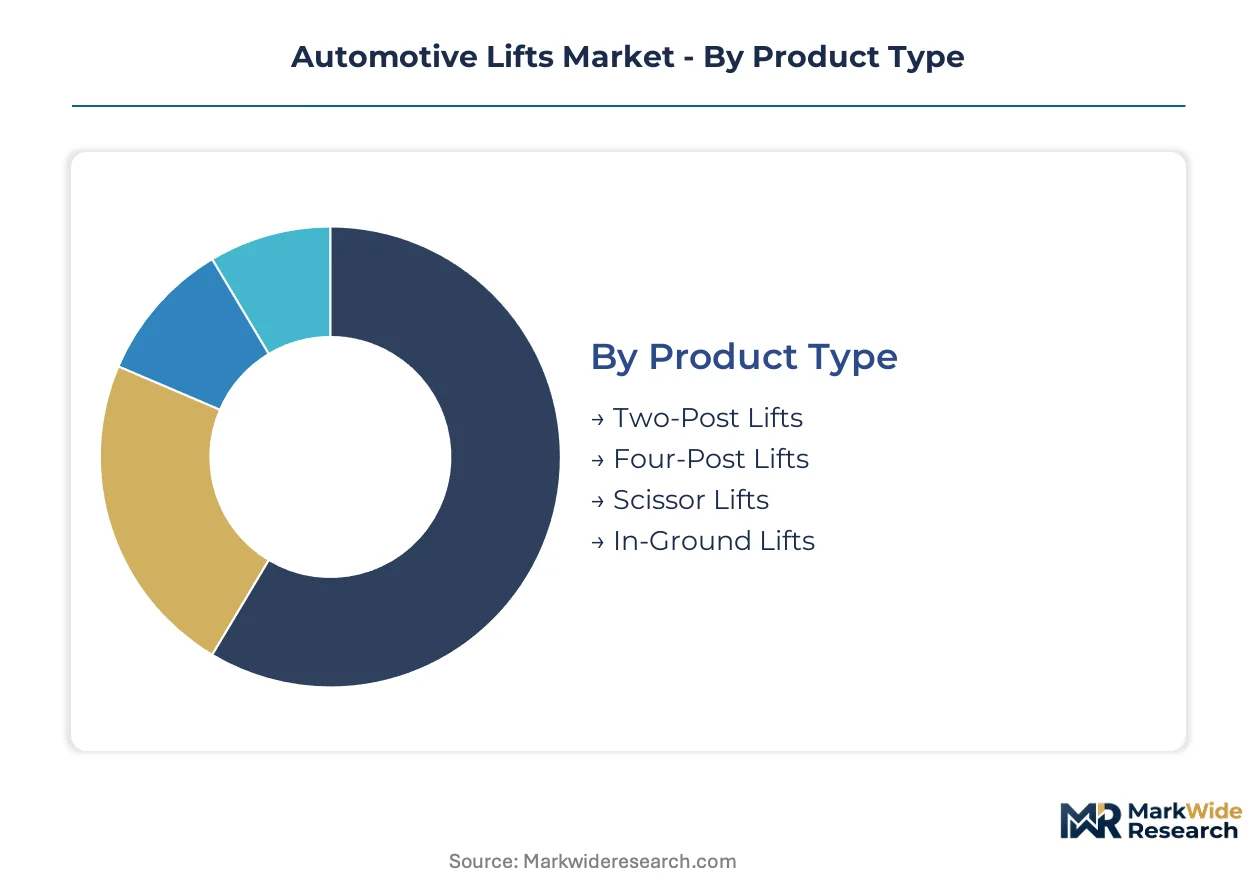
Segmentation in automotive lifts reveals how workshop configuration, vehicle fleet composition, and regulatory compliance reshape procurement patterns across distinct customer profiles. Product architecture, powertrain technology, and rated capacity each create divergent margin structures and replacement cycles that vendors must navigate.
Product Type:
Cost tier differentiation across lift architectures separates footprint-efficient independent shop solutions from stability-optimized commercial installations.
- Two-Post Lifts:Cantilevered frame design with direct wheel access dominates independent automotive shops in Texas and Florida where bay space constraints limit equipment footprint. Demand concentrates among multi-bay operators modernizing above-ground installations to meet OSHA inspection protocols.
- Four-Post Lifts:Runway configurations with integrated alignment racks anchor higher-margin dealership service bays in Germany and California. Fleet operators specify these for electric commercial vehicle storage and wheel alignment where load stability under battery-heavy chassis is paramount.
- Scissor Lifts:Low-profile collapsed height accommodates battery-heavy electric vehicle geometries without pit excavation.
- In-Ground Lifts:Flush-mount designs require concrete excavation and structural reinforcement that extends replacement timelines in established facilities.
Two-Post Lifts holds installed capacity. Scissor Lifts is rotating up the share rankings.
End User:
Customer type determines specification complexity, with commercial operators demanding integrated diagnostics and residential buyers prioritizing footprint efficiency.
- Automotive Shops:Independent multi-bay operators in Maharashtra and Karnataka standardize on four-post alignment lifts as vehicle parc ages. These facilities unbundle installation from procurement, creating specialized regional service providers.
- Car Dealerships:OEM-affiliated service bays bundle lift systems with Hunter Engineering precision alignment and diagnostic calibration equipment. Procurement prioritizes ANSI documentation and sensor-integrated platforms feeding workshop management software.
- Fleet Service Providers:Commercial operators in California and Germany retrofit service bays for electric bus and truck maintenance, driving scissor lift demand.
- Home Garage Owners:Residential segment concentrates e-commerce procurement of standardized two-post configurations through direct-to-workshop distribution channels.
Automotive Shops maintains volume leadership. Fleet Service Providers is climbing the fastest on electrification mandates.
Technology:
Power source selection reflects trade-offs between precision control, maintenance burden, and failsafe redundancy for electric vehicle battery servicing.
- Hydraulic:Fluid-actuated systems with mechanical locking dominate legacy installed base but face replacement pressure from electro-hydraulic hybrid configurations.
- Electric:Motor-driven screw or chain mechanisms enable precise height control with reduced maintenance intervals.
- Pneumatic:Compressed air systems find niche application in facilities with existing shop air infrastructure.
- Mechanical:Pure mechanical locking provides failsafe redundancy when hybridized with electro-hydraulic actuation for commercial electric van maintenance in Germany.
Hydraulic retains legacy dominance. Electric is gaining share fastest on predictive maintenance integration.
Capacity:
Rated load thresholds segment procurement between passenger vehicle service and commercial fleet infrastructure.
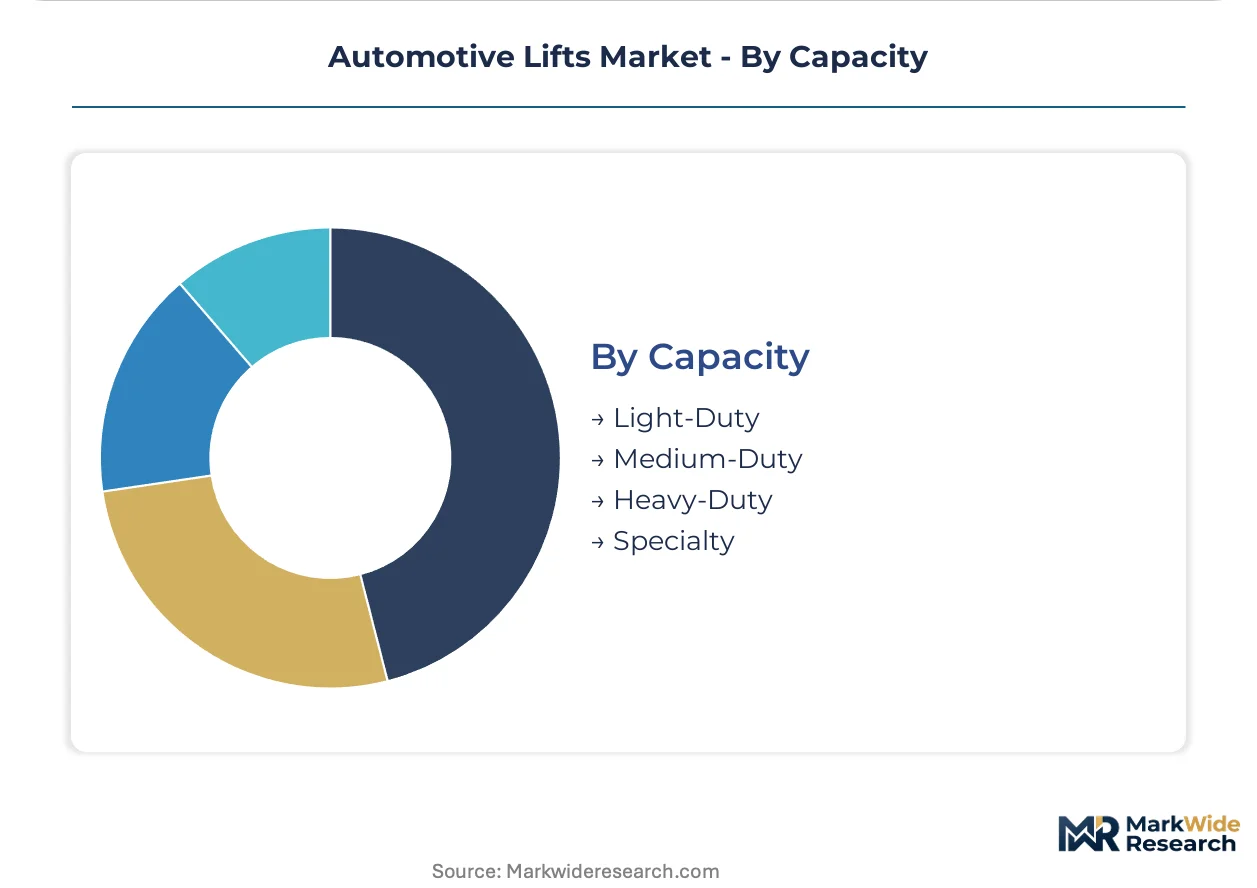
- Light-Duty:Passenger vehicle ratings up to 7,000 pounds serve independent shops and residential installations.
- Medium-Duty:Commercial van and light truck ratings address fleet service provider requirements in California.
- Heavy-Duty:Bus and truck ratings exceed 30,000 pounds, forcing structural steel recalibration as battery-electric commercial vehicle platform weights climb.
- Specialty:Custom ratings for motorcycle, ATV, and wheelchair-accessible vehicle applications occupy niche positioning.
Medium-Duty anchors current revenue. Heavy-Duty is expanding most quickly on fleet electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's intermodal freight corridors channel steel and hydraulic components into Central European lift fabrication, while the Rhine-Ruhr industrial belt distributes finished equipment across continental workshop networks.
United States
OSHA inspection protocols and ANSI load-testing mandates compress replacement cycles for aging above-ground installations. Fleet electrification requirements in California drive bay retrofitting for electric commercial vehicle maintenance. Houston and Dallas-Fort Worth anchor independent shop expansion, with regional service providers unbundling installation from equipment procurement.
Germany
Commercial automotive workshops modernize aging hydraulic infrastructure to meet EU Machinery Directive safety assessments and CE marking requirements. KBA vehicle inspection standards elevate documentation burdens for non-compliant imports. The Rhine-Main cluster around Frankfurt concentrates distribution of electro-hydraulic platforms serving independent multi-bay operators.
China
Rising domestic labor rates and environmental compliance costs narrow historical cost advantages in lift manufacturing. MIIT industrial standards and GB certification requirements filter export capacity. Zhejiang and Jiangsu provinces maintain hydraulic component sourcing clusters despite vulnerability to environmental enforcement actions.
India
Organized multi-brand service chains in Maharashtra and Karnataka standardize on four-post alignment lifts as vehicle parc ages and dealership networks extend. BIS equipment safety standards shape procurement criteria for commercial installations. The Pune-Aurangabad industrial corridor anchors fabrication capacity serving western Indian aftermarket expansion.
Japan
Sensor-integrated lift systems feeding workshop management platforms capture premium positioning through METI-supported smart factory initiatives. JIS structural integrity standards govern locking mechanism reliability for electric vehicle battery servicing applications. The Nagoya-Toyota industrial zone concentrates precision alignment integration demand from OEM-affiliated service bays.
Automotive Lifts Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in steel fabrication and hydraulic cylinder supply. The vendor base stratifies between vertically integrated full-line manufacturers and regional fabricators serving price-sensitive independent shops. Three archetypes dominate: premium-tier OEM-affiliated integrators, mid-market full-line suppliers, and regional specialists in standardized two-post configurations. Consolidation pressure operates through M&A targeting sensor-integrated platform capabilities, while capacity expansion concentrates in captive steel processing and electro-hydraulic actuator assembly.
Among North American full-line manufacturers, BendPak, Rotary Lift, and Hunter Engineering exemplify the premium-tier archetype through control over upstream fabrication and diagnostic integration. Stertil-Koni and Nussbaum occupy positions within the European specialist tier, anchoring conformity infrastructure for Machinery Directive compliance. Mohawk Lifts, Challenger Lifts, ARI-HETRA, and MAHA Maschinenbau Haldenwang represent regional fabrication strength across distinct geographic footprints, with naming conventions signaling American and German industrial origins respectively.
| Leading Market Players |
|---|
| BendPak |
| Rotary Lift |
| Hunter Engineering |
| Stertil-Koni |
| Nussbaum |
| Mohawk Lifts |
| Challenger Lifts |
| ARI-HETRA |
| MAHA Maschinenbau Haldenwang |
| Others |
Pricing and Supply Chain Analysis
Steel price volatility in structural members and hydraulic cylinders compresses margin predictability across fabrication tiers while simultaneously forcing tiered pricing stratification between captive-supply integrated manufacturers and import-dependent regional fabricators.
Pricing Analysis
Volume-discount tiering separates OEM-affiliated dealership procurement from independent shop spot purchasing, with certification-grade differentiation widening spreads between ANSI-documented premium platforms and non-certified economy imports. Price differentiation hinges on CE marking compliance costs and after-sales service bundling, with pricing pressure intensifying as e-commerce channels disintermediate traditional distributor markups. Fleet service providers exhibit lowest price sensitivity due to electrification mandate deadlines, while residential home garage buyers concentrate entirely in economy tiers.
Supply Chain Analysis
Upstream structural steel feedstock draws from integrated mills in the United States, Germany, and Japan, with hydraulic cylinder components anchored in Zhejiang and Jiangsu provinces of China. Raw material dependencies encompass high-tensile steel plate, precision-machined cylinder rods, and electro-hydraulic actuator assemblies. Single-source vulnerability concentrates in Chinese hydraulic component clusters facing environmental compliance enforcement. Distribution runs through captive OEM service networks for premium tiers and regional equipment distributors for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile column lift substitution threatens fixed installation incumbents as fleet operators prioritize portable configurations for irregular maintenance schedules, forcing established manufacturers to defend core positioning through structural differentiation.
For Market Incumbents: Insulate core above-ground lift portfolios by deepening backward integration into steel fabrication and electro-hydraulic actuator assembly in Alabama and California facilities. Accelerate sensor-integrated platform development to merge predictive maintenance capabilities with ANSI-compliant documentation, creating switching costs that mobile column alternatives cannot replicate.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka aftermarket expansion offers underpenetrated white space as organized multi-brand service chains standardize equipment procurement. Target four-post alignment lift demand in aging vehicle parc markets through direct-to-workshop e-commerce channels, bypassing established distributor relationships that incumbent full-line manufacturers dominate.
For Investors and Strategic Acquirers: The market sits at a certification-convergence phase that favors vertically integrated manufacturers possessing captive conformity infrastructure. Long-term viability centers on sensor-integrated platform capabilities feeding workshop management software. Watch for inflection when mobile column lift adoption rates in heavy-duty fleet segments exceed replacement thresholds for fixed scissor configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Platform Development | Captures premium positioning in German and Japanese markets through METI-supported smart factory alignment. |
| Backward Integration into Steel Fabrication | Insulates margin structures from commodity volatility affecting import-dependent regional competitors. |
| Direct-to-Workshop Distribution Channel | Disintermediates traditional equipment distributors for standardized two-post configurations in North America. |
| CE Marking Conformity Infrastructure Investment | Filters non-compliant Asian imports from European distribution channels under Machinery Directive enforcement. |
| Predictive Maintenance Software Integration | Transforms standalone elevation equipment into data-capturing service nodes for fleet operators. |
Research Methodology
Initial hypotheses were tested against primary input from fleet maintenance directors, automotive workshop owners, OEM procurement specialists, and aftermarket equipment distributors and refined through secondary validation across SEC filings, customs trade records, OSHA inspection databases, and vehicle production statistics. Bottom-up demand modeling triangulated with top-down market sizing across product type, end user, technology, and capacity segmentation dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling spanning lift architecture, powertrain service requirements, rated load thresholds, and regional regulatory clusters. CAGRs were derived from replacement cycle compression analysis and fleet electrification penetration curves, incorporating electric vehicle platform weight trajectories and battery placement geometries as structural capacity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese hydraulic component specialists or accelerated mobile column lift adoption by heavy-duty fleet operators would shift outcomes. Cross-checking against OSHA inspection protocol enforcement rates and EU Machinery Directive third-party assessment volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Air Springs Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Thermostat Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Electromagnetic Clutch System Market