
 Automotive Central Lubrication System Market | 2026-2036
Automotive Central Lubrication System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Central Lubrication System Market Analysis
Electromechanical engineering talent scarcity in precision fluid dynamics is reorganizing how suppliers allocate R&D resources across Europe and Asia. SKF Group leverages its bearing-lubrication integration expertise to dominate system architecture decisions at major commercial vehicle platforms. Groeneveld-BEKA sustains market presence through its dense service network covering fleet operators across Nordic and Benelux corridors. Cenlub Systems anchors its position in cost-sensitive segments with localized manufacturing and aftermarket spare parts availability.
An automotive central lubrication system distributes metered lubricant through fixed piping networks to multiple friction points using pumps, progressive dividers, and control units, typically operating at pressures between 150-300 bar for chassis applications and timed injection cycles measured in cubic millimeters per stroke. Its primary purpose is eliminating manual greasing intervals, extending component life in wheel bearings, kingpins, and fifth wheels while reducing labor hours and contamination exposure in commercial vehicle operations. Electric system architectures are capturing specification share fastest as fleets demand programmable dosing tied to telematics platforms, while pneumatic systems retain dominance in heavy machinery applications where compressed air infrastructure already exists. OEM channel access concentrates margin pools at the top, with fleet operators representing the fastest-growing end-user category as total-cost-of-ownership calculators reshape procurement criteria away from upfront price toward lifecycle maintenance economics.
The EPA's greenhouse gas Phase 3 standards for heavy-duty vehicles and the EU's F-Gas Regulation on fluorinated lubricant alternatives are reshaping material specifications and system sealing requirements across North American and European supply chains. NHTSA's enhanced braking system reliability guidelines indirectly elevate lubrication system performance thresholds as wheel-end thermal management becomes critical to compliance. Stakeholders must monitor how China's MIIT new-energy commercial vehicle mandates alter lubrication architectures for electric axle and thermal management integration before specification lock-in at next-generation platforms.
Market Dynamics
Commercial vehicle fleet operators are consolidating procurement authority toward lifecycle cost calculators, compressing specification cycles and forcing lubrication system suppliers to prove total-cost-of-ownership superiority over upfront hardware pricing. This demand-side concentration is accelerating R&D prioritization toward predictive maintenance integration and sealed-for-life architectures that eliminate service intervals.
Growth Catalysts
- EPA Phase 3 Standards:Tightened greenhouse gas regulations for heavy-duty engines are mandating precision thermal management, elevating automated lubrication from convenience to compliance infrastructure.
- Telematics Convergence:Fleet management platforms are absorbing lubrication system data streams, creating specification pull for programmable electric pumps with CAN-bus connectivity.
- German Manufacturing Clusters:Dense Tier-1 supplier networks around Stuttgart and Munich are concentrating design-in decisions, accelerating technology transfer from commercial vehicle OEMs to system architects.
Market Restraints
- Electromechanical Talent Scarcity:Precision fluid dynamics engineering expertise concentrates in aging workforces across Central Europe, constraining supplier scaling capacity.
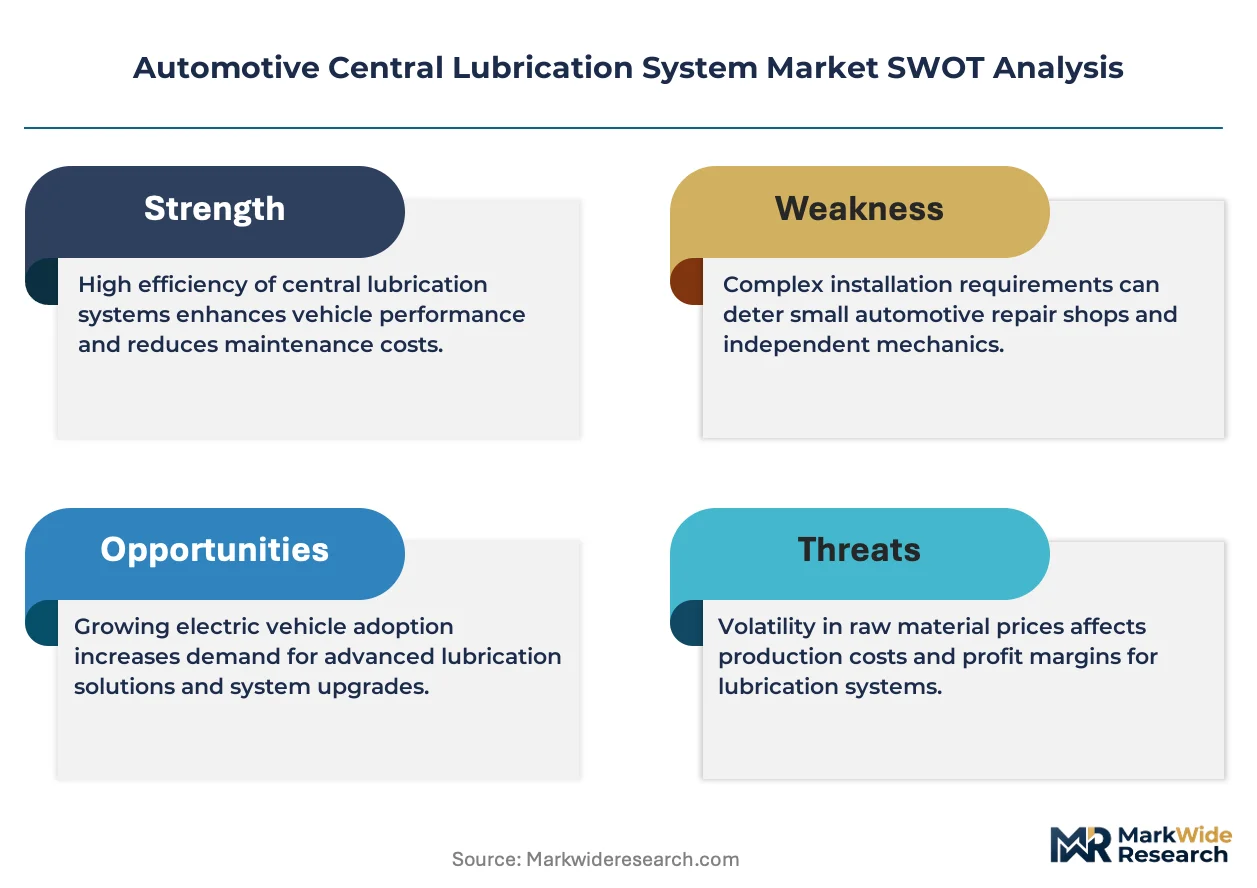
- Specialized Polymer Costs:High-pressure sealing materials resistant to biodegradable lubricant chemistries face volatile pricing tied to fluoropolymer feedstock availability.
- Pneumatic Infrastructure Lock-In:Heavy machinery operators with sunk capital in compressed air systems resist electric architecture migration despite superior dosing precision.
Strategic Opportunities
- Electric Axle Thermal Management:New-energy commercial vehicle platforms in China are creating specification voids for integrated cooling-lubrication modules at e-axle and hub motor interfaces.
- EU F-Gas Regulation:Phase-down of fluorinated lubricant alternatives is accelerating demand for reformulated biodegradable greases compatible with next-generation sealing elastomers.
- Direct Fleet Channel Development:Bypassing OEM specification gates through certified retrofit programs targets owner-operator segments with compressed payback period requirements.
Industry Challenges
- Precision Metrology Skill Gaps:Metering pump calibration to cubic-millimeter tolerances requires specialized technicians scarce in aftermarket service networks.
- Legacy Pneumatic Integration:Electric system retrofits into existing chassis architectures demand custom manifold design extending engineering-to-delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Central Lubrication System Market |
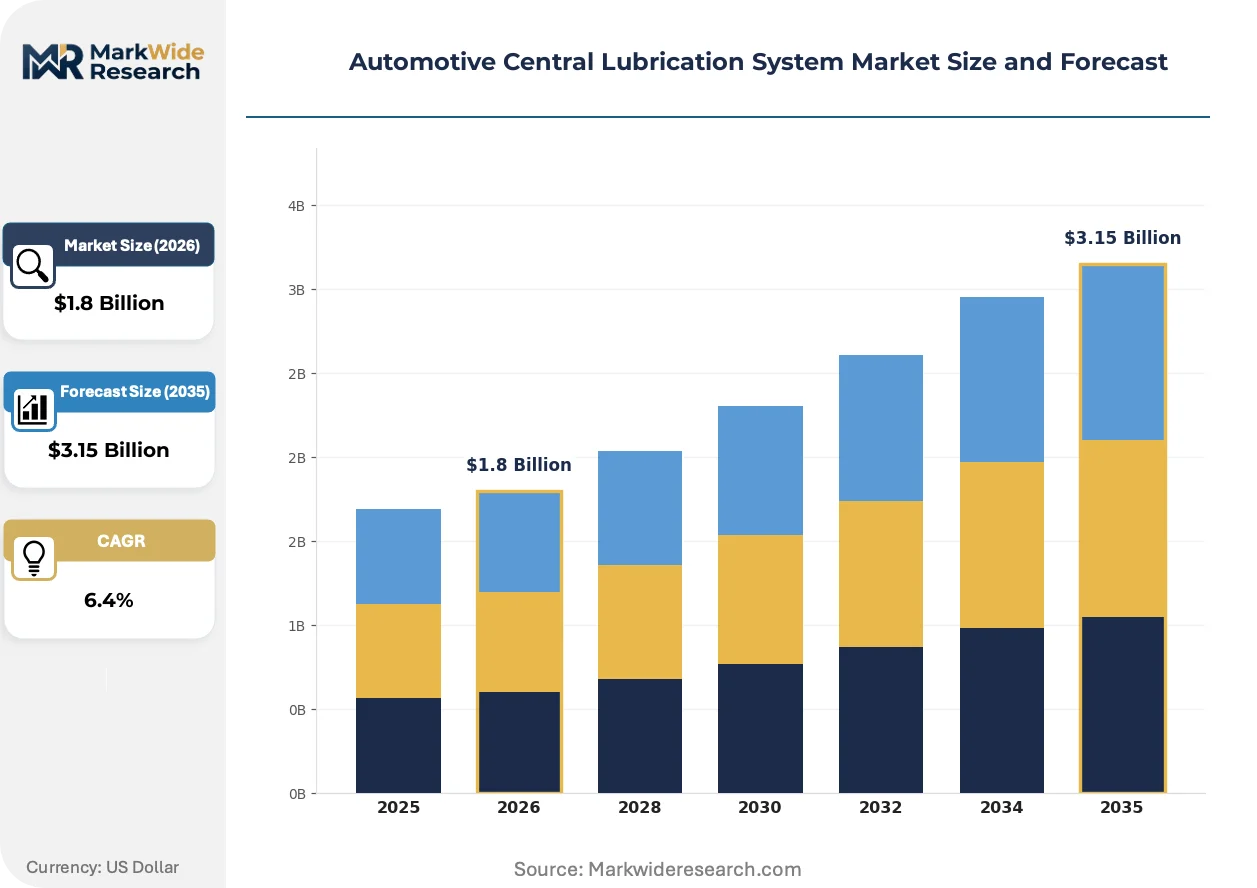
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Greasing Systems, Manual Greasing Systems, Oil Injection Systems, Centralized Lubrication Systems End User: Manufacturers, Repair Shops, Fleet Operators, OEMs Technology: Pneumatic Systems, Electric Systems, Mechanical Systems, Hydraulic Systems Application: Heavy Machinery, Automotive Equipment, Industrial Equipment, Others |
| Companies Covered | SKF Group, Graco Inc., Timken Company, Bijur Delimon International, Groeneveld-BEKA, Cenlub Systems, Raasm, DropsA, Lincoln Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Central Lubrication System Market Emerging Trajectories
System architectures are splitting into two distinct optimization paths: sealed-for-life precision dosing for electric commercial vehicles versus ruggedized high-volume delivery for legacy diesel fleets. This technical divergence is forcing suppliers to place parallel bets on incompatible R&D portfolios.
Electric pump technology is bifurcating market specifications. Programmable brushless DC pumps with integrated flow sensors enable telematics-linked dosing algorithms for fleet operators demanding predictive maintenance data. Tier-1 suppliers are capturing design-in decisions at major commercial vehicle platforms by bundling bearing-lubrication integration expertise. The technology is compressing margins for pneumatic system incumbents while creating premium pricing tiers for connected architectures.
The EU F-Gas Regulation is mandating fluorinated lubricant phase-downs across European supply chains. Biodegradable grease formulations with modified thickener chemistries are displacing conventional lithium-complex products in progressive divider systems. German commercial vehicle OEMs are accelerating qualification timelines for alternative sealing elastomers compatible with these reformulated lubricants, compressing material validation cycles.
Fleet procurement authority is consolidating toward total-cost-of-ownership calculators. Owner-operators and mid-size logistics providers are bypassing traditional OEM specification channels through certified retrofit programs with compressed payback period guarantees. Nordic corridor operators are driving this behavioral shift most visibly, demanding outcome-based service contracts that unbundle hardware from preventive maintenance labor.
Automotive Central Lubrication System Market Segmentation
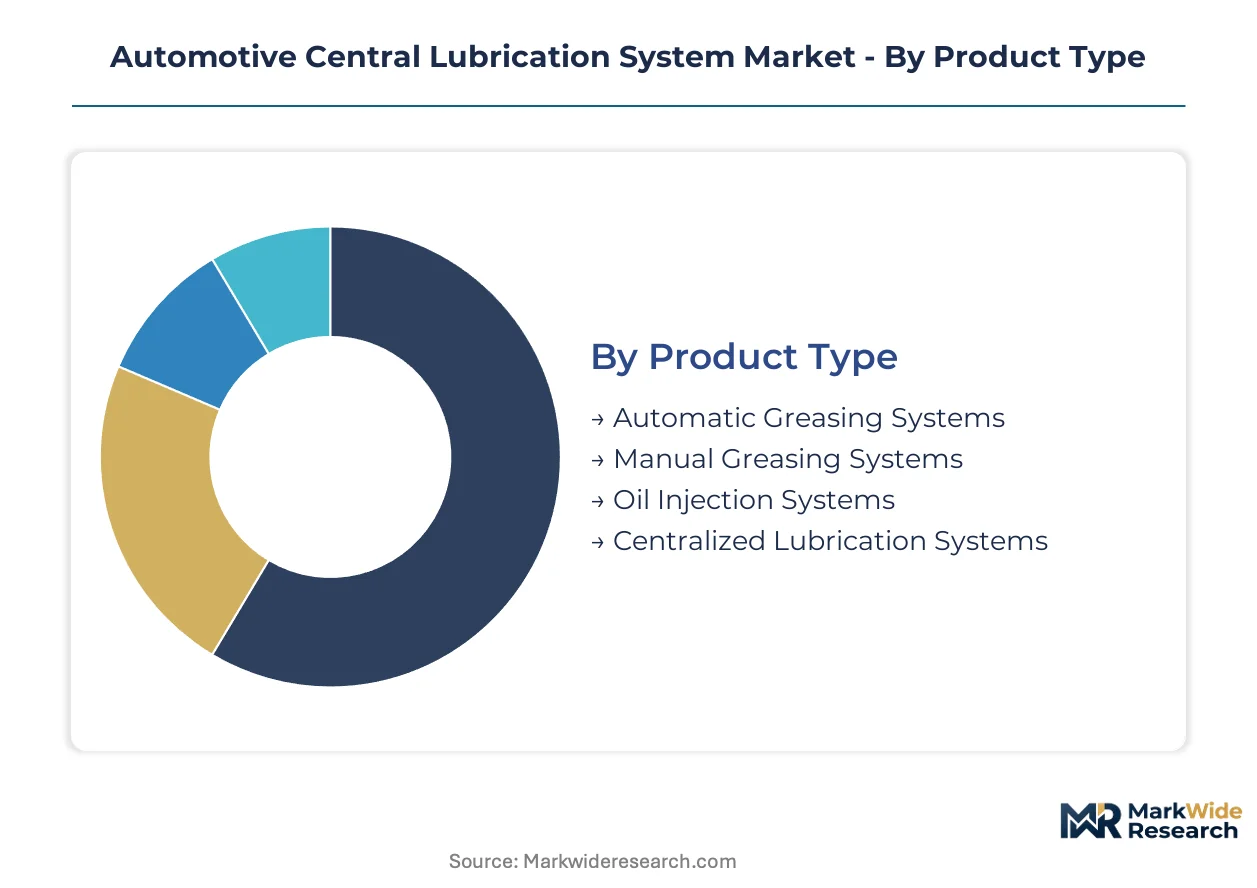
Segmentation in automotive central lubrication systems reveals how regulatory pressure and fleet economics split procurement decisions across incompatible technical architectures. Each dimension exposes where specification power concentrates and where retrofit opportunities bypass traditional OEM channels.
Product Type:
EPA Phase 3 greenhouse gas standards and EU F-Gas fluorinated lubricant phase-downs are segmenting product portfolios by sealing compatibility and precision dosing requirements.
- Automatic Greasing Systems:Electromechanical pump architectures with programmable CAN-bus interfaces deliver cubic-millimeter precision dosing synchronized to vehicle telematics. German commercial vehicle OEMs specify these for next-generation platforms requiring thermal management compliance.
- Centralized Lubrication Systems:Fixed piping networks with progressive dividers operating at 150-300 bar pressure serve chassis applications across heavy-duty fleets. Fleet operators in Nordic corridors favor these for sealed-for-life architectures that eliminate service intervals and labor exposure.
- Manual Greasing Systems:Hand-operated grease guns and portable lubricators persist in owner-operator segments with minimal compressed air or electrical infrastructure.
- Oil Injection Systems:Metered oil delivery for high-speed bearings and precision gearboxes in industrial equipment applications.
Centralized lubrication systems handle the majority of throughput; automatic greasing systems are gaining share fastest as telematics integration reshapes fleet procurement.
End User:
Customer type determines whether suppliers capture margin through OEM design-in authority or aftermarket retrofit volume with compressed payback guarantees.
- Fleet Operators:Consolidating procurement authority toward total-cost-of-ownership calculators, these buyers demand predictive maintenance integration and sealed-for-life architectures. Nordic and Benelux logistics providers drive specification pull for connected electric pump systems.
- OEMs:Commercial vehicle manufacturers around Stuttgart and Munich concentrate design-in decisions, bundling lubrication architecture with bearing systems at platform conception. SKF Group leverages this channel through integrated bearing-lubrication expertise.
- Repair Shops:Aftermarket service networks require precision metrology capabilities for metering pump calibration that remain scarce in distributed maintenance infrastructure.
- Manufacturers:Tier-1 suppliers and system integrators specifying components for upstream assembly into complete vehicle platforms.
OEMs dominate specification authority; fleet operators represent the steepest expansion trajectory as procurement bypasses traditional channels.
Technology:
Capital sunk into compressed air infrastructure versus telematics connectivity requirements splits adoption between legacy pneumatic and emerging electric architectures.
- Electric Systems:Brushless DC pumps with integrated flow sensors enable programmable dosing algorithms and predictive maintenance data streams. These systems capture specification share fastest where fleets demand CAN-bus connectivity and precision thermal management.
- Pneumatic Systems:Compressed air-driven pumps retain dominance in heavy machinery applications with existing infrastructure. Heavy machinery operators resist migration despite electric dosing precision due to sunk capital in air compression systems.
- Hydraulic Systems:High-pressure fluid power architectures for extreme-duty mining and construction equipment requiring ruggedized delivery.
- Mechanical Systems:Simple cam-driven or linkage-actuated pumps for cost-sensitive applications with minimal automation requirements.
Pneumatic systems retain installed base dominance; electric systems are expanding most quickly as programmable dosing aligns with fleet telematics convergence.
Application:
Equipment duty cycle and operating environment determine whether specifications prioritize precision sealing or high-volume ruggedized delivery.
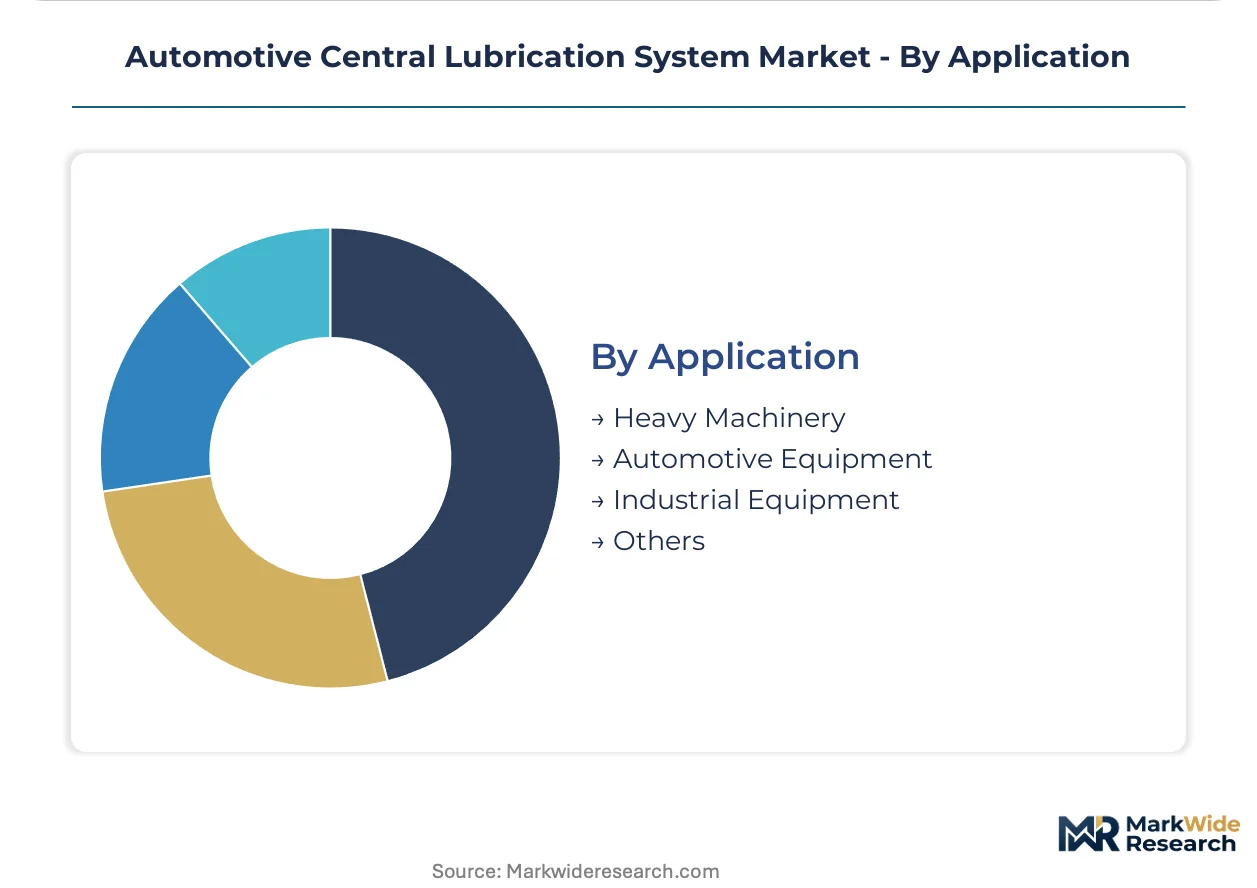
- Heavy Machinery:Mining, construction, and agricultural equipment demand high-pressure delivery and contamination resistance. Pneumatic systems dominate where compressed air infrastructure exists; electric retrofits face custom manifold design barriers.
- Automotive Equipment:Commercial vehicle chassis applications concentrate demand in Germany, with wheel bearings, kingpins, and fifth wheels requiring automated greasing to extend component life and reduce downtime.
- Industrial Equipment:Manufacturing machinery and material handling systems with scheduled maintenance windows and controlled operating environments.
- Others:Marine, rail, and specialty vehicle applications with customized lubrication architectures.
Automotive equipment commands the largest volume share; heavy machinery is climbing the fastest as fleet operators consolidate lifecycle cost accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 standards for heavy-duty engines are concentrating specification authority in Germany, while China's MIIT mandates for new-energy commercial vehicles are reshaping lubrication architectures across Asia-Pacific manufacturing corridors.
Germany
Commercial vehicle OEMs around Stuttgart and Munich are driving demand for precision thermal management systems that comply with EU F-Gas fluorinated lubricant phase-downs. The KBA enforces stringent braking system reliability guidelines that elevate wheel-end lubrication performance thresholds. Dense Tier-1 supplier networks in Baden-Württemberg concentrate design-in decisions for integrated bearing-lubrication modules.
United States
Fleet operators across the Midwest and Southeast corridors are consolidating procurement toward total-cost-of-ownership calculators that favor predictive maintenance integration. EPA greenhouse gas Phase 3 standards mandate precision thermal management infrastructure for heavy-duty engines. Manufacturing clusters in Michigan and Ohio anchor specification pull for sealed-for-life architectures that reduce service intervals.
China
New-energy commercial vehicle mandates from MIIT are creating specification voids for integrated cooling-lubrication modules at e-axle interfaces. The country's dual carbon goals accelerate demand for electric pump architectures with telematics connectivity. Manufacturing corridors in the Yangtze River Delta and Pearl River Delta concentrate R&D investment toward thermal management integration for electric axle platforms.
Sweden
Nordic logistics providers are driving behavioral shifts toward outcome-based service contracts that unbundle hardware from preventive maintenance labor. The EU F-Gas Regulation mandates fluorinated lubricant alternatives phase-down across commercial vehicle supply chains. Industrial clusters around Gothenburg concentrate fleet operator demand for connected electric pump systems with CAN-bus interfaces.
India
Cost-sensitive fleet segments are expanding adoption of localized manufacturing and aftermarket spare parts availability to compress payback periods. The PLI scheme for automotive components incentivizes domestic production of precision fluid dynamics systems. Manufacturing hubs in Maharashtra and Gujarat anchor demand for centralized lubrication systems serving heavy-duty chassis applications.
Automotive Central Lubrication System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with bearing-lubrication bundlers capturing OEM design-in authority while regional fabricators defend aftermarket retrofit volume. The structure concentrates margin pools at specification gates where telematics integration and precision dosing capabilities differentiate premium positioning from commodity hardware. Three archetypes dominate: integrated bearing-lubrication bundlers, electromechanical pump specialists, and dense-service-network operators. Competitive moves center on backward integration into sealing elastomer production and technology licensing agreements that accelerate qualification timelines for biodegradable grease compatibility.
Within the integrated bundler tier, SKF Group exemplifies the bearing-lubrication convergence archetype that dominates commercial vehicle platform decisions. Groeneveld-BEKA occupies a position anchored by dense service networks across Nordic and Benelux corridors, while Cenlub Systems represents the cost-optimized fabricator archetype serving price-sensitive segments through localized production.
| Leading Market Players |
|---|
| SKF Group |
| Graco Inc. |
| Timken Company |
| Bijur Delimon International |
| Groeneveld-BEKA |
| Cenlub Systems |
| Raasm |
| DropsA |
| Lincoln Industrial |
| Others |
Supply Flow & Price Mechanics
Biodegradable grease formulations replacing fluorinated lubricants under EU F-Gas phase-downs are simultaneously shifting procurement geography toward German sealing elastomer suppliers and compressing margin structures for legacy pneumatic system incumbents. This substitution dynamic concentrates pricing power with electromechanical pump architects while fragmenting supply options for fleet operators locked into conventional chemistries.
Pricing Analysis
German-manufactured electric pump systems command substantial premiums over Chinese and Indian alternatives, with price spreads reflecting CAN-bus integration depth and precision dosing certification tiers. Three-tier pricing structure across premium connected architectures, standard programmable systems, and economy pneumatic alternatives stratifies the market. Cost compression in the mid-tier is intensifying because fleet procurement consolidation demands telematics bundling at compressed hardware margins. Owner-operator segments exhibit highest price sensitivity, while Nordic logistics providers prioritize lifecycle cost calculators over upfront expenditure.
Supply Chain Analysis
Inventory cycles for high-pressure sealing polymers now stretch 16-22 weeks, forcing Tier-1 suppliers to pre-position stock ahead of EU F-Gas compliance deadlines. Manufacturing concentrates in Germany, China, and India, with precision pump assembly anchored in Baden-Württemberg clusters and cost-optimized fabrication in Maharashtra and Gujarat. The supply chain draws from fluoropolymer feedstocks, brushless DC motor components, and progressive divider castings. Single-source vulnerability around specialized elastomer grades poses structural risk. Distribution runs through OEM specification channels for new platforms and certified retrofit networks for aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement cyclicality tied to commercial vehicle production schedules positions the market for recovery as EPA Phase 3 compliance deadlines approach and deferred maintenance backlogs release pent-up specification demand.
For Market Incumbents: Fortify bearing-lubrication integration expertise to defend OEM design-in authority against emerging electromechanical specialists. Deepen backward integration into sealing elastomer production to capture margin pools from F-Gas-driven material transitions. Prioritize captive supply of biodegradable-compatible polymer formulations. For New Entrants and Emerging Players: CE marking fast-track for electric pump architectures with integrated flow sensors unlocks specification access at German commercial vehicle platforms. Target the Indian aftermarket retrofit segment where localized manufacturing and compressed payback guarantees penetrate cost-sensitive fleet operators. Pursue technology licensing agreements with established sealing material suppliers to accelerate qualification timelines. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors electromechanical pump specialists with telematics integration capabilities over legacy pneumatic incumbents. Long-term viability hinges on positioning for electric commercial vehicle platform specification windows. Target acquisition archetypes include precision fluid dynamics engineering teams and connected system software stacks. Watch for MIIT mandate acceleration in China as inflection indicator for integrated cooling-lubrication module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealing Elastomers | Captures margin pools from EU F-Gas material transitions and reduces fluoropolymer feedstock exposure. |
| Telematics Platform Partnership | Enables predictive maintenance data monetization at Nordic fleet operators consolidating procurement authority. |
| Electric Axle Thermal Module Development | Addresses specification voids created by China's MIIT new-energy commercial vehicle mandates. |
| Certified Retrofit Program Expansion | Bypasses OEM specification gates to capture owner-operator segments with compressed payback requirements. |
| Precision Metrology Service Network | Resolves aftermarket calibration skill gaps that constrain electric system penetration in distributed maintenance infrastructure. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, fleet maintenance directors, and aftermarket distributors; and secondary validation through vehicle production databases, EPA regulatory filings, EU F-Gas implementation tracking, and commercial vehicle registration statistics. Bottom-up triangulation against top-down market sizing ensured dimensional consistency across product type, technology architecture, and end-user segmentation.
Across the projection horizon, the analytical framework modeled volume and value outputs through vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from production forecast linkages and specification penetration curves. Industry-specific inputs included EPA Phase 3 compliance timelines, EU F-Gas phase-down schedules, and MIIT new-energy mandate implementation tracking.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement and fleet procurement consolidation; material deviation in commercial vehicle production schedules or lubricant chemistry substitution rates would warrant model refresh. Revision becomes warranted when electric commercial vehicle platform specification lock-in crosses critical mass thresholds in Chinese or German manufacturing corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Singapore Automotive Engine Oils Market
Automotive Parts
Brake Pad Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Air Lift Jack Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Automotive Washer System Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market