
 Argentina Automotive Actuators Market | 2026-2036
Argentina Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Automotive Actuators Market Outlook
Market Context
Argentina's Tier-1 supplier base is hardening around electromechanical actuator production for the Mercosur automotive corridor. Robert Bosch GmbH leverages its Campana facility to sustain module assembly capacity serving both domestic OEMs and Brazilian export programs. Continental AG anchors regional brake actuator supply through localized manufacturing, while Denso Corporation competes on thermal management actuator integration for engine control applications. BorgWarner Inc differentiates via its clutch actuator specialization for dual-clutch transmission programs supplied to Volkswagen Group Argentina.
Technical Definition and Segment Structure
Automotive actuators are electromechanical or electrohydraulic devices that convert control signals into precise mechanical motion to regulate vehicle subsystems such as throttle position, valve timing, braking force, or steering assist torque, typically operating across voltage ranges from 12V to 48V in passenger and commercial vehicle architectures. Rotary actuators dominate engine control and transmission applications where angular positioning precision governs fuel efficiency compliance, while electric actuators displace hydraulic alternatives in brake control systems as OEMs pursue weight reduction and simplified maintenance cycles. Linear actuators retain stronghold in power steering column adjustments and seat positioning modules where straight-line force transmission optimizes packaging constraints.
Regulatory Environment and Outlook
Argentina's IRAM standards body enforces electromagnetic compatibility and functional safety protocols for automotive actuators, while the country's national automotive regulator aligns type-approval processes with Mercosur's evolving safety harmonization framework. The Córdoba industrial corridor faces intensifying scrutiny on component traceability as Brazil's INMETRO certification requirements cascade across cross-border supplier contracts. Stakeholders must monitor how Mercosur's pending unified cybersecurity standards for connected vehicle systems reshape actuator firmware validation requirements and supplier qualification timelines.
Market Dynamics
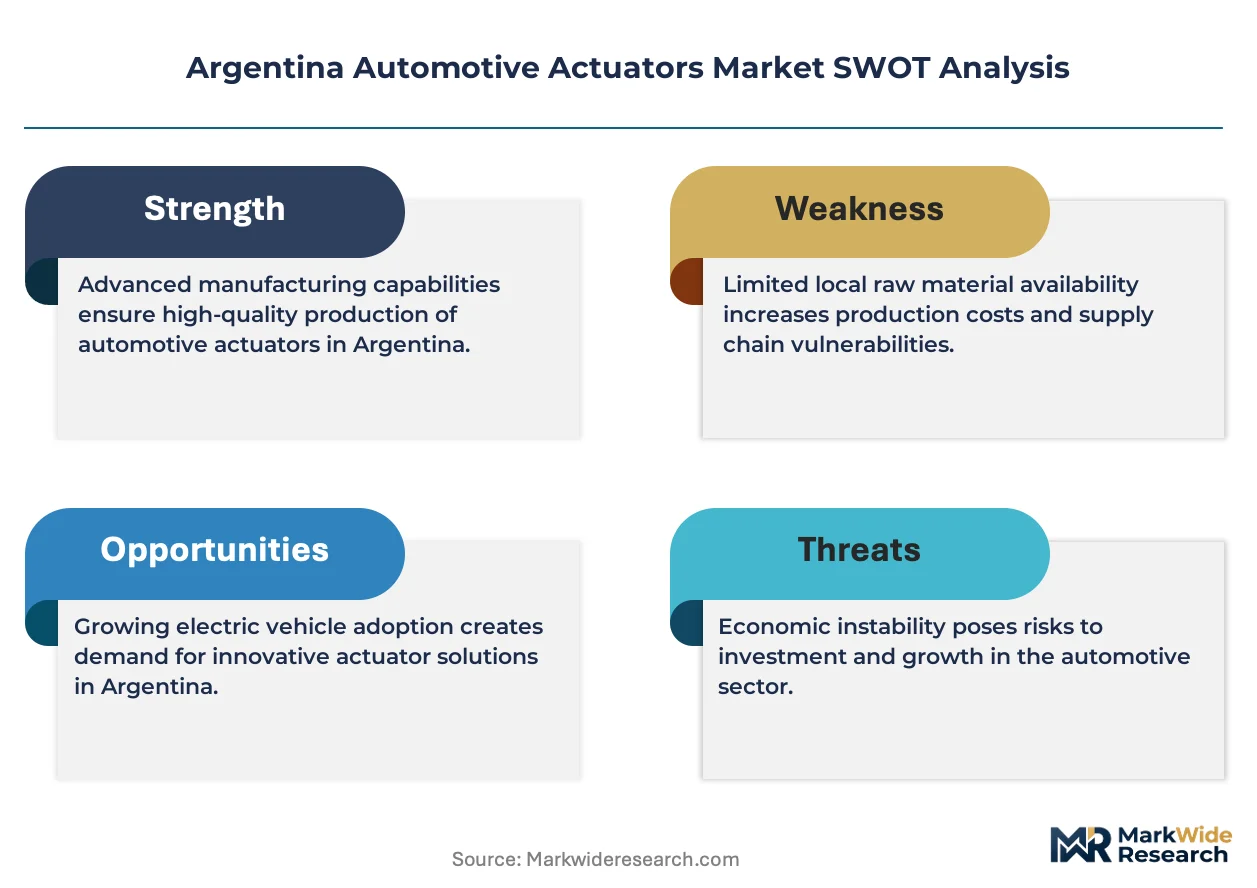
Electrification of vehicle subsystems is compressing supplier margins while forcing legacy hydraulic actuator manufacturers to retool for electromechanical architectures. The Córdoba industrial corridor's concentration of powertrain component suppliers faces acute pressure from Brazilian OEMs demanding localized 48V actuator sourcing.
Growth Catalysts
- IRAM Safety Certification Tightening:Argentina's national standards body is mandating enhanced functional safety protocols for brake control actuators, compelling Tier-1 suppliers to upgrade electromagnetic compatibility testing infrastructure.
- Light Commercial Vehicle Electrification:Córdoba Province manufacturers are expanding electric power steering actuator procurement to meet Mercosur fleet efficiency benchmarks.
- Buenos Aires Supplier Cluster Density:The province's concentration of vehicle assemblers and Tier-1 parks generates procurement economies that attract specialized actuator module producers.
Market Restraints
- Import Dependency for Rare Earth Magnets:Argentina lacks domestic neodymium processing capacity, exposing electric actuator manufacturers to Chinese supply chain volatility and currency fluctuation risks.
- Mercosur Regulatory Misalignment:Divergent type-approval timelines between Argentina's national automotive regulator and Brazil's INMETRO create cross-border certification friction that delays product launches.
- Hydraulic Actuator Obsolescence Risk:Remaining electrohydraulic brake actuator installations face premature replacement cycles as OEMs standardize on fully electric architectures.
Strategic Opportunities
- Patagonia Logistics Vehicle Retrofit Market:Mining and agricultural fleet operators in southern Argentina present aftermarket demand for heavy-duty actuator replacements with extended temperature tolerance specifications.
- Mercosur Unified Cybersecurity Standards:Pending connected vehicle firmware mandates will create validation service opportunities for actuator suppliers with embedded security certification capabilities.
- Thermal Management Integration:Convergence of engine cooling valve actuators with battery thermal control systems opens cross-platform module supply contracts for diversified component manufacturers.
Industry Challenges
- Embedded Software Competency Gap:Argentine actuator suppliers face acute shortages of functional safety engineers capable of delivering ASIL-D certified control algorithms required by modern brake and steering systems.
- IRAM Certification Timeline Compression:Accelerated type-approval cycles for electromechanical safety components are straining testing laboratory capacity and extending supplier qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Automotive Actuators Market |
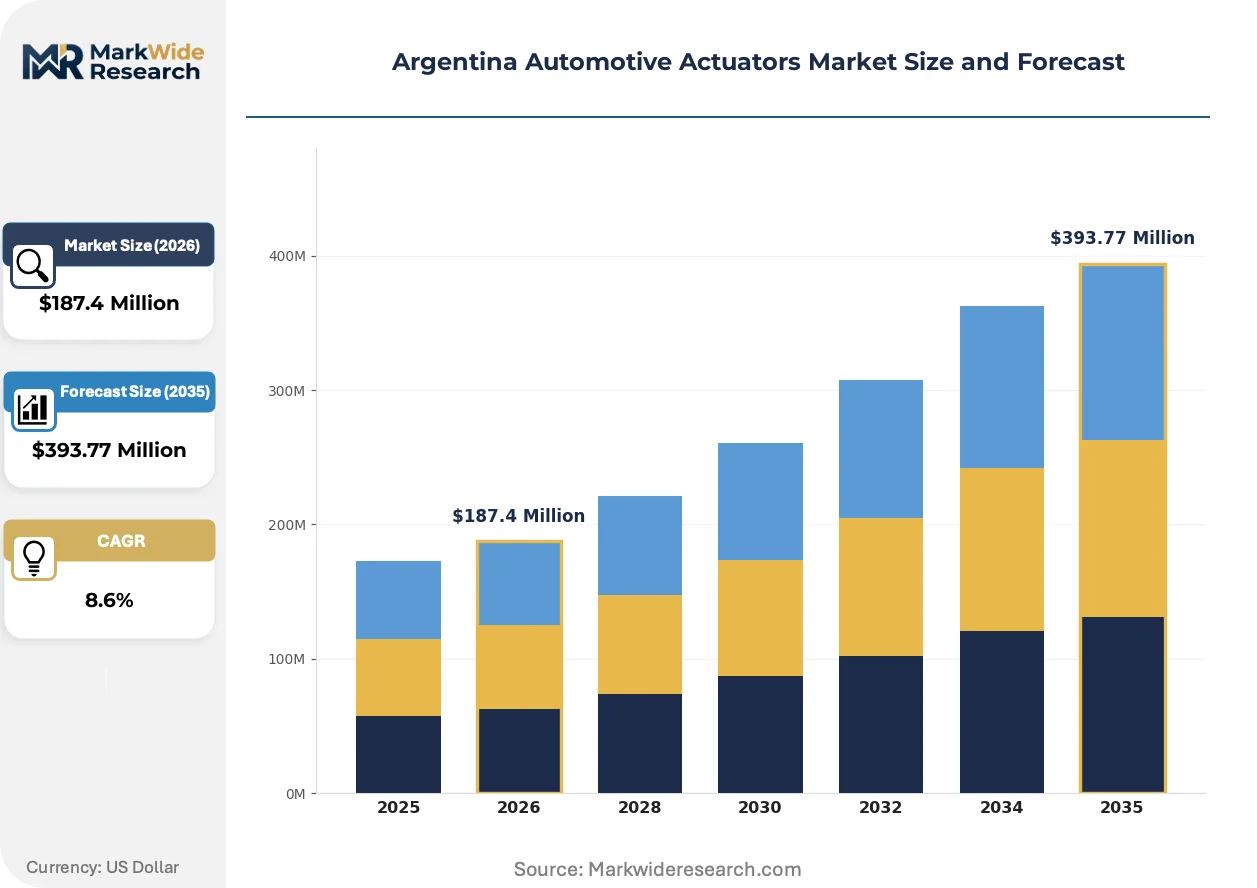
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Electric Actuators, Hydraulic Actuators End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Power Steering, Engine Control, Transmission Control, Brake Control Installation: Integrated, Standalone, Embedded, Retrofit |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Johnson Electric, BorgWarner Inc, Wabco Holdings Inc, Hella KGaA Hueck & Co, CTS Corporation, Sonceboz SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Automotive Actuators Market Strategic Shifts
Actuator architectures are bifurcating between high-voltage electric platforms for new vehicle programs and cost-optimized electromechanical retrofits serving existing Mercosur fleets. This technological divergence is reshaping supplier R&D allocation and manufacturing footprint decisions across Argentina's automotive corridor.
Brushless DC motor technology is consolidating position in power steering and brake control applications where torque precision and thermal efficiency determine system performance. Volkswagen Group Argentina and domestic commercial vehicle assemblers are specifying integrated motor-controller modules that eliminate separate ECU packaging. This integration is consolidating supplier tiers as electromechanical specialists absorb electronic control competencies previously held by separate semiconductor distributors.
Argentina's national automotive regulator is aligning type-approval processes with Brazil's INMETRO electromagnetic compatibility requirements, forcing component suppliers to dual-certify actuator designs for cross-border acceptance. The industrial consequence is standardized test protocol adoption that reduces regulatory arbitrage between Mercosur members. Brake control system manufacturers face the most acute compliance pressure, as safety-critical actuator firmware must demonstrate fault tolerance under harmonized validation frameworks.
Fleet procurement departments are consolidating supplier relationships around full-system integrators capable of delivering actuator-controller-calibration bundles rather than discrete mechanical components. Tier-1 distributors serving Buenos Aires Province vehicle assemblers are displacing specialized actuator traders with module-level supply contracts. This concentration is most visible in light commercial vehicle manufacturing, where single-source power steering system awards now span mechanical, electronic, and software deliverables.
Argentina Automotive Actuators Market Segmentation
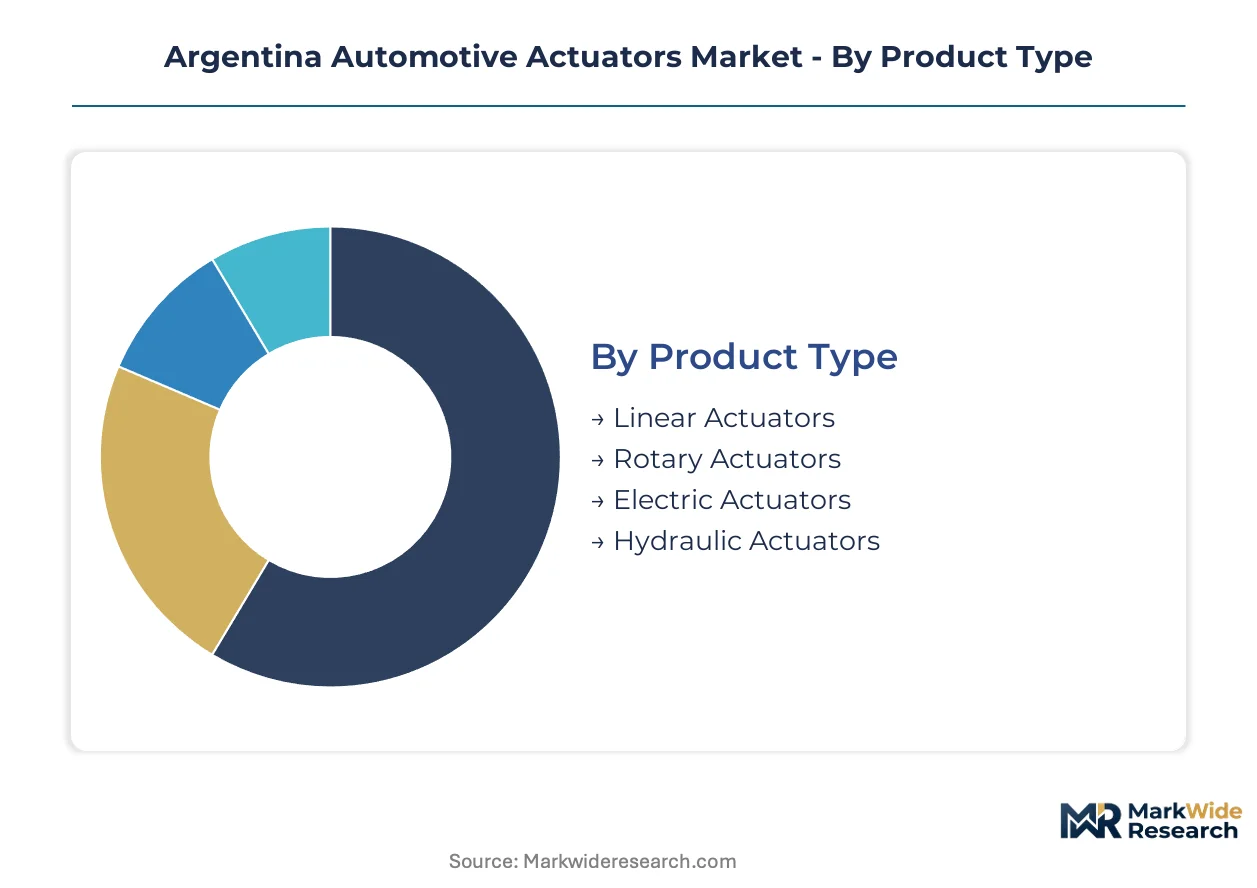
Actuator segmentation in Argentina reflects the tension between legacy hydraulic architectures and electromechanical upgrades demanded by Mercosur fleet efficiency mandates. Supplier qualification timelines and IRAM certification pathways vary sharply across product categories, forcing procurement strategies to align with specific upgrade cycle positions.
Product Type:
Replacement cycles favor electromechanical platforms as OEMs retire hydraulic systems ahead of regulatory deadlines.
- Linear Actuators:These devices generate straight-line force through screw or belt-drive mechanisms, typically operating at 12V with position feedback via Hall-effect sensors. Demand concentrates in power steering column adjustments and seat positioning modules across Buenos Aires Province vehicle assemblers, where packaging constraints prioritize compact linear force transmission over rotary alternatives.
- Rotary Actuators:Angular positioning systems employing brushless DC motors with encoder feedback achieve precision within 0.1 degrees for cam phasing and throttle control. Córdoba Province powertrain suppliers specify these for engine control applications where fuel efficiency compliance depends on valve timing accuracy under Mercosur emission benchmarks.
- Electric Actuators:Solid-state electromechanical units replacing hydraulic circuits in brake and steering systems, eliminating fluid maintenance and reducing weight by 30-40% versus legacy designs.
- Hydraulic Actuators:Electrohydraulic systems retaining installed base in heavy commercial vehicles and mining equipment, though facing accelerated obsolescence as OEMs standardize electric architectures.
Electric actuators sit at the top of the volume ranking, with rotary actuators climbing the fastest.
End User:
Margin structures diverge sharply between captive OEM supply and fragmented aftermarket channels.
- OEMs:Original equipment manufacturers in Buenos Aires Province specify actuator-controller-calibration bundles through single-source contracts, consolidating procurement around full-system integrators capable of delivering IRAM-certified modules with embedded firmware.
- Tier-1 Suppliers:Module assemblers such as Robert Bosch GmbH's Campana facility and Continental AG's brake actuator plants serve as intermediaries between component manufacturers and vehicle assemblers, absorbing electromagnetic compatibility testing costs for cross-border Mercosur supply.
- Aftermarket Providers:Independent distributors serving Patagonia mining fleets and agricultural operators focus on heavy-duty actuator replacements with extended temperature tolerance specifications.
- Vehicle Assemblers:Final assembly plants in Córdoba Province and Buenos Aires Province integrate actuators into powertrain, chassis, and body systems, with procurement departments consolidating relationships around suppliers offering localized technical support.
Tier-1 suppliers capture the dominant revenue share, while aftermarket providers expand most quickly in southern Argentina's extractive sectors.
Application:
Functional safety requirements stratify actuator specifications across vehicle subsystems.
- Power Steering:Electric power steering actuators deliver torque assist through brushless DC motors integrated with rack-and-pinion or column-mounted mechanisms. Córdoba light commercial vehicle manufacturers are expanding procurement of these units to meet Mercosur fleet efficiency benchmarks, with IRAM mandating enhanced electromagnetic compatibility protocols for safety-critical steering components.
- Engine Control:Throttle body actuators and variable valve timing actuators regulate air intake and exhaust flow with millisecond response times. Buenos Aires Province engine plants specify these for compliance with tightening emission standards, with rotary actuator precision directly determining fuel consumption performance.
- Transmission Control:Clutch and shift actuators enable automated manual and dual-clutch transmission operation, with BorgWarner Inc specializing in this segment for Volkswagen Group Argentina supply programs.
- Brake Control:Brake-by-wire actuators replace hydraulic master cylinders with electromechanical force generation, facing the most stringent IRAM functional safety certification requirements and fault-tolerance validation.
Power steering commands the largest installed base, with brake control gaining share fastest as electric architectures displace hydraulic systems.
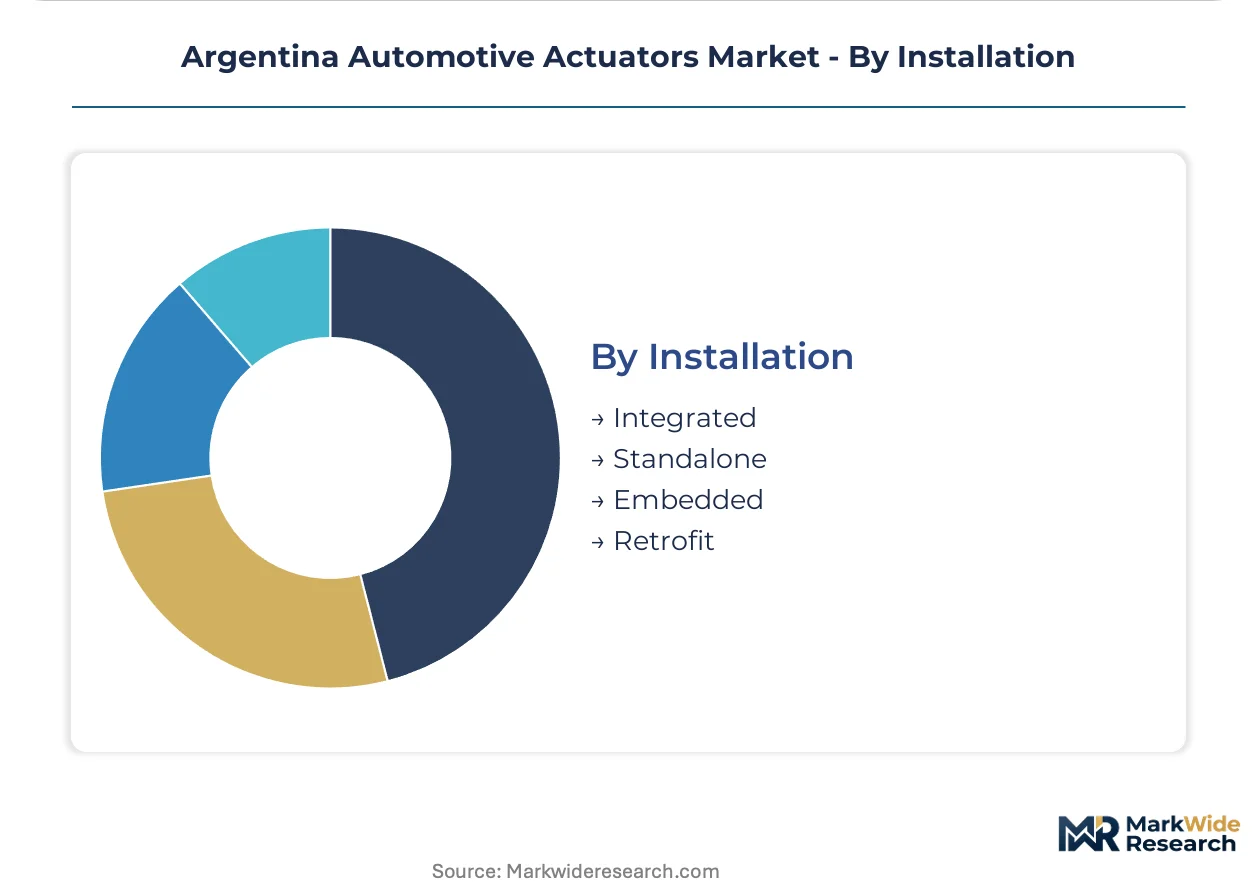
Installation:
Integration depth determines supplier tier positioning and software competency requirements.
- Integrated:Actuator-motor-controller modules eliminate separate ECU packaging, with Volkswagen Group Argentina and domestic commercial vehicle assemblers specifying these consolidated units to reduce wiring complexity and assembly cost.
- Standalone:Discrete mechanical actuators with separate electronic control units persist in legacy vehicle platforms and cost-sensitive commercial vehicle segments where full integration economics do not justify redesign investment.
- Embedded:Firmware-intensive actuators with ASIL-D certified control algorithms for brake and steering applications, requiring suppliers to absorb functional safety engineering competencies previously held by semiconductor distributors.
- Retrofit:Aftermarket actuator replacements for Patagonia mining and agricultural fleets, specified with extended temperature ranges and simplified calibration procedures for field installation.
Integrated installations lead by volume, with embedded configurations expanding most steeply as safety-critical firmware mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where IRAM certification costs undercut Brazilian INMETRO equivalents, concentrating electromechanical actuator assembly in Argentina's lower-cost industrial corridors while cross-border regulatory misalignment persists.
Buenos Aires Province
Vehicle assemblers and Tier-1 supplier parks generate procurement economies that attract specialized actuator module producers. IRAM electromagnetic compatibility protocols tighten functional safety thresholds for brake control systems manufactured in this corridor. The Greater Buenos Aires industrial belt hosts concentrated module assembly operations serving both domestic OEMs and Mercosur export programs.
Córdoba Province
Light commercial vehicle manufacturers expand electric power steering actuator procurement to meet fleet efficiency benchmarks. The province's powertrain component suppliers face pressure from Brazilian OEMs demanding localized 48V actuator sourcing. Córdoba's automotive cluster anchors regional transmission control actuator production for Volkswagen Group Argentina supply programs.
Santa Fe Province
Agricultural machinery manufacturers generate aftermarket demand for heavy-duty hydraulic actuator replacements with extended temperature tolerance. The Rosario industrial corridor processes soy export revenues into capital equipment procurement, indirectly sustaining actuator demand from associated logistics vehicle fleets. Local distributors serve Patagonia mining retrofit markets through specialized temperature-rated inventory.
Mendoza Province
Wine industry logistics fleets create niche demand for brake actuator retrofits in heavy commercial vehicles traversing Andean mountain routes. Provincial transport regulators enforce maintenance cycles that accelerate replacement part turnover. The Mendoza-Valparaíso corridor's cross-border trucking volume sustains aftermarket actuator distribution channels.
Patagonia Region
Mining and extractive operations in southern Argentina present aftermarket demand for actuator replacements specified to extreme temperature ranges. Remote fleet operators prioritize simplified calibration procedures for field installation over integrated module complexity. Regional procurement bypasses Buenos Aires-based distribution, creating direct supplier relationships with specialized temperature-rated component manufacturers.
Argentina Automotive Actuators Market Competitive Environment
German producers anchor one tier; Japanese and American specialists hold differentiated positions in electromechanical subsystems. The supplier base consolidates around full-system integrators capable of delivering actuator-controller-calibration bundles rather than discrete mechanical components. Two strategic archetypes dominate: diversified automotive conglomerates with module-level integration capabilities, and focused electromechanical specialists competing on thermal management or transmission control niches. Competitive moves center on absorbing functional safety engineering competencies previously held by semiconductor distributors, and consolidating procurement relationships through single-source power steering system awards.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify integrated module assembly capacity serving cross-border Mercosur supply. Denso Corporation occupies a position among thermal management actuator specialists competing on engine control integration. BorgWarner Inc represents the transmission-focused archetype, anchoring clutch actuator supply for dual-clutch programs. These three companies illustrate how supplier tiers compress as electromechanical specialists absorb electronic control competencies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Johnson Electric |
| BorgWarner Inc |
| Wabco Holdings Inc |
| Hella KGaA Hueck & Co |
| CTS Corporation |
| Sonceboz SA |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap electromechanical specialists in Córdoba Province anchor Argentina's actuator supply base, their conservative capital allocation limiting capacity expansion and sustaining pricing discipline even as Brazilian OEMs demand localized 48V sourcing. This ownership pattern concentrates supply-side bargaining power among a handful of generational producers who prioritize margin preservation over market share capture.
Pricing Analysis
Distributor margins for aftermarket actuators in Patagonia mining corridors run 35-45 points above direct-to-OEM contract pricing for integrated power steering modules. Pricing stratifies across IRAM-certified premium tiers for brake control systems, standard electromagnetic compatibility grades for engine applications, and economy linear actuators serving agricultural retrofit demand. Cost compression in hydraulic-to-electric conversion programs is intensifying because Tier-1 suppliers absorb firmware development costs previously externalized to semiconductor partners. Aftermarket providers serving remote mining fleets exhibit highest price sensitivity, while OEMs in Buenos Aires Province prioritize single-source system integration over unit cost minimization.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese neodymium processing capacity, Japanese specialty magnet alloy producers, and limited German recycling operations. Argentine actuator manufacturers draw from Taiwanese brushless DC motor controllers, South Korean Hall-effect sensor suppliers, and domestic aluminum die-casting foundries in Santa Fe Province. Single-source vulnerability concentrates in neodymium supply, where currency fluctuation against the yuan transmits directly to electric actuator bill-of-materials. Distribution runs through Buenos Aires-based Tier-1 module assemblers who consolidate component procurement for cross-border Mercosur supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's automotive actuator market reads as a late-cycle quality story, with fleet electrification mandates and IRAM safety certification tightening driving demand-shift toward ASIL-D certified embedded systems. Procurement departments now specify actuator-controller-calibration bundles that reward suppliers with integrated functional safety competencies.
For Market Incumbents: Deepen backward integration into brushless DC motor production to defend margin position against Chinese actuator imports penetrating through Brazilian OEM supply contracts. Prioritize IRAM certification investment for brake control firmware to maintain qualification status as electromagnetic compatibility protocols tighten. Consolidate channel control by absorbing aftermarket distribution relationships previously held by independent traders in Patagonia mining corridors. For New Entrants and Emerging Players: The premium-economy price gap in power steering actuators creates entry space for mid-tier electromechanical specialists offering IRAM-compliant standard grades without full system integration burden. Target Córdoba Province light commercial vehicle manufacturers seeking second-source electric power steering supply to reduce single-source dependency on Robert Bosch GmbH. Pursue go-to-market positioning as firmware-agnostic mechanical actuator suppliers, enabling Tier-1 integrators to embed proprietary control algorithms. For Investors and Strategic Acquirers: Valuations sit cheapest among Argentine family-owned actuator component manufacturers lacking ASIL-D certification capabilities but possessing established IRAM testing relationships and Córdoba industrial corridor real estate. Long-term viability over the projection horizon hinges on electromechanical architecture conversion completion and Mercosur regulatory harmonization progress. Watch for Brazilian INMETRO-IRAM type-approval timeline convergence as the inflection signal triggering consolidation premiums for dual-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| IRAM Certification Investment | Dual electromagnetic compatibility and functional safety certification opens cross-border Mercosur supply to Brazilian OEMs. |
| Backward Integration into Motor Production | In-house brushless DC manufacturing reduces neodymium magnet cost exposure and shortens lead times for Córdoba assemblers. |
| Firmware-Mechanical Separation | Unbundling control algorithms from mechanical actuators enables Tier-1 integrators to customize without redesigning hardware platforms. |
| Patagonia Distribution Direct Relationships | Bypassing Buenos Aires-based distributors captures aftermarket margin in mining and agricultural retrofit segments. |
| 48V Architecture Conversion | Localizing high-voltage electric actuator supply satisfies Brazilian OEM demands and qualifies for Mercosur origin requirements. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down Tier-1 supplier capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 procurement directors, aftermarket distributors in Buenos Aires Province, IRAM certification laboratory managers, and Córdoba industrial corridor plant operators combined with secondary validation against vehicle registration databases, customs import records for rare earth magnets, and SEC filings of multinational actuator manufacturers. Triangulation between production volume estimates and component bill-of-materials analysis calibrated market sizing across the projection horizon.
Input-output matrices mapped actuator demand by vehicle class, propulsion architecture, content per vehicle, OEM tier positioning, and regional production cluster. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion, with electromechanical conversion timelines and IRAM regulatory implementation schedules serving as key forecast inputs. Model outputs stress-tested against alternative scenarios for Mercosur regulatory harmonization pace and Chinese rare earth export policy shifts.
Caveats apply where neodymium supply disruption, Brazilian-Argentine regulatory misalignment extension, or accelerated hydraulic actuator obsolescence could materially shift the outlook. Forecasts reflect assumptions on IRAM certification timeline compression and Tier-1 supplier consolidation trajectories. A small set of triggers—Mercosur cybersecurity standard finalization, Chinese magnet export quota adjustments, and Volkswagen Group Argentina platform allocation decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Singapore Passenger Vehicles Lubricants Market
Automotive Parts
Wheel Arch Liner Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
South America Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Nitrous Oxide System Market