
 India Brake Pads Market | 2026-2036
India Brake Pads Market Size, Share, and Industry Trends Forecast 2026-2036
India Brake Pads Market Insights
Buyer concentration among commercial fleet operators is restructuring procurement patterns across India's brake pad value chain. ASK Automotive Pvt. Ltd. leverages vertically integrated friction material production to serve domestic OEM contracts. Brakes India Private Limited anchors its position through captive foundry capacity and long-standing supply relationships with domestic vehicle assemblers. Brembo Brake India Pvt. Ltd. differentiates via high-performance ceramic formulations targeted at premium passenger vehicle platforms.
Brake pads are friction components engineered from bonded asbestos-free formulations—typically incorporating ceramic fibers, steel wool, and phenolic resin matrices—designed to convert kinetic energy into thermal energy through controlled surface abrasion against rotating brake rotors or drums. Manufacturing involves pre-forming, hot pressing at 150-200°C, and thermal curing to achieve specified friction coefficients and wear rates for automotive braking systems. Semi-metallic formulations dominate volume production for commercial vehicles due to thermal durability under sustained load cycles, while ceramic segments command margin premiums in passenger vehicle OEM channels where noise and dust reduction carry weight. Aftermarket distribution for two-wheelers represents the fastest-growing application channel as India's motorcycle parc expands and independent repair networks penetrate tier-2 and tier-3 cities.
BIS mandates friction material certification under IS 11852, while the Automotive Research Association of India enforces brake performance testing protocols aligned with Central Motor Vehicle Rules. The Ministry of Road Transport and Highways periodically revises braking distance standards, forcing formulation upgrades across domestic suppliers. Stakeholders must monitor alignment between state-level vehicle scrappage incentives and replacement part demand cycles.
Market Dynamics
Commercial fleet operators across Maharashtra and Gujarat are compressing replacement cycles, forcing suppliers to reconfigure inventory positioning and service networks around concentrated demand nodes.
Growth Catalysts
- IS 11852 Certification Mandate:BIS friction material standards are eliminating substandard suppliers and consolidating procurement toward certified domestic manufacturers serving OEM channels.
- Two-Wheeler Aftermarket Expansion:Independent repair networks penetrating tier-2 and tier-3 cities are creating new distribution endpoints for replacement brake pads.
- Delhi-Mumbai Industrial Corridor Concentration:Passenger vehicle assembly clusters are pulling friction material suppliers into proximity for just-in-sequence delivery contracts.
Market Restraints
- Phenolic Resin Cost Volatility:Petrochemical feedstock price swings compress margin buffers for semi-metallic formulation producers serving volume commercial vehicle contracts.
- Captive Foundry Supply Concentration:Domestic brake rotor casting capacity concentrates among vertically integrated assemblers, limiting independent pad suppliers' backward integration options.
- Ceramic Fiber Import Dependency:High-performance friction material substrates rely on controlled foreign supply chains subject to DGFT licensing delays.
Strategic Opportunities
- Tamil Nadu Electric Vehicle Hub:Chennai-Bengaluru manufacturing corridor development is attracting regenerative braking-integrated friction suppliers for emerging EV platforms.
- Central Motor Vehicle Rules Alignment:Revised braking distance standards under Ministry of Road Transport and Highways mandates are forcing formulation upgrades that favor technical specialists.
- E-Commerce Spare Parts Platforms:Digital aftermarket channels are disintermediating traditional distributor tiers for independent motorcycle service shops.
Industry Challenges
- Thermal Curing Process Engineering Talent:Specialized technicians capable of optimizing hot-press cycles at 150-200°C for specified friction coefficients remain scarce outside established manufacturing belts.
- Automotive Research Association of India Testing Queues:Brake performance validation bottlenecks extend product qualification timelines for new formulation launches.
- Legacy Drum Brake System Integration:Commercial vehicle parc retention of older architectures forces parallel production lines for disc and drum friction configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Brake Pads Market |
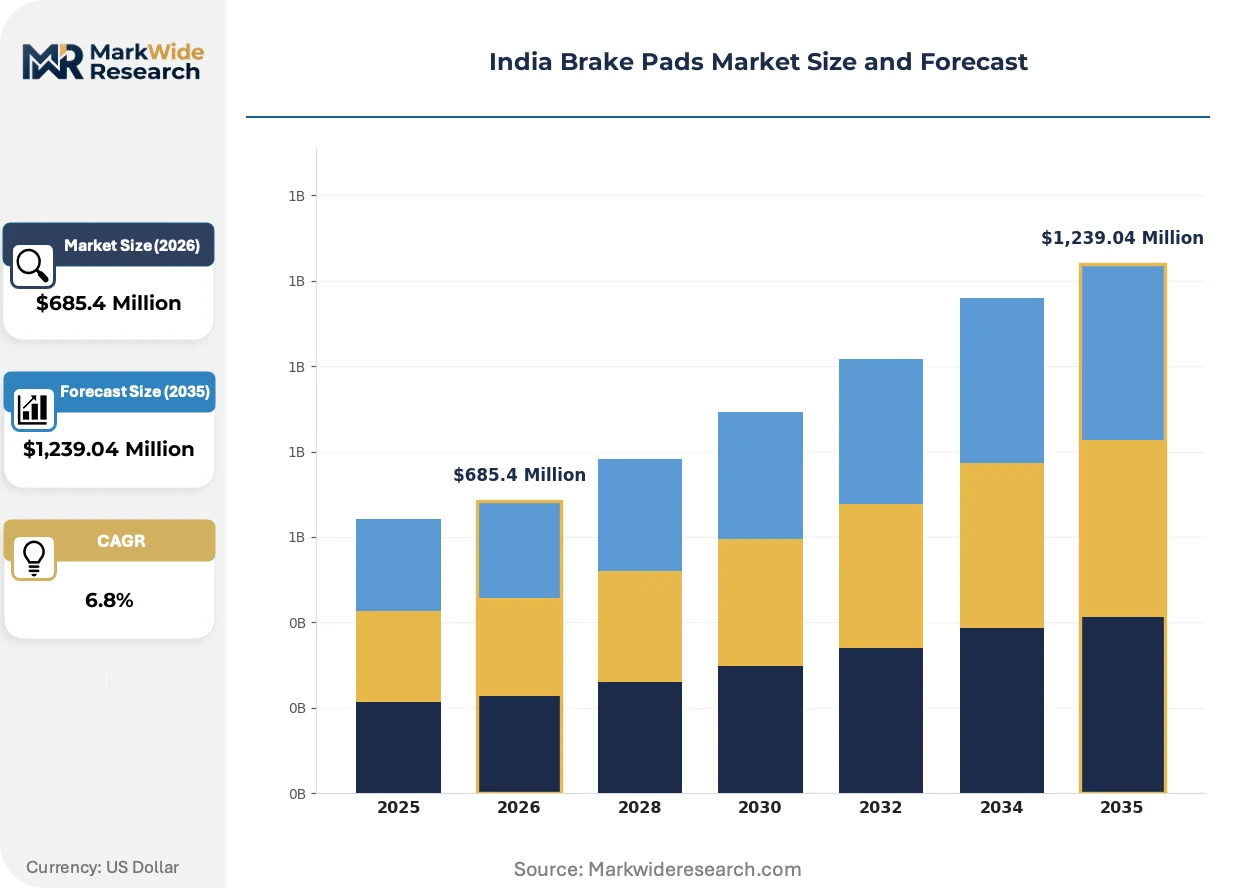
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Semi-Metallic, Ceramic, Metallic End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Application: OEM, Aftermarket, Racing, Industrial Material: Rubber, Composite, Steel, Fiber |
| Companies Covered | ASK Automotive Pvt. Ltd., Makino Auto Industries Pvt. Ltd., Brakes India Private Limited, Allied Nippon Private Limited, Masu Brake Pads Pvt. Ltd., Rane Holdings Limited, Brembo Brake India Pvt. Ltd., Sagestics Brakes, Endurance Technologies Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Brake Pads Market Trends and Innovations
Ceramic fiber matrix technologies are compressing the performance gap between commercial durability requirements and passenger comfort expectations, reshaping supplier R&D allocation.
Ceramic-steel hybrid formulations are unifying thermal stability with noise suppression in single-layer architectures. Premium passenger vehicle OEMs in the Delhi-Mumbai corridor are adopting these at accelerated qualification paces. This unification is compressing the traditional segmentation between fleet-grade semi-metallics and luxury ceramic grades.
BIS IS 11852 certification protocols under the Ministry of Road Transport and Highways are tightening asbestos-free verification requirements. Domestic friction material producers are restructuring quality assurance departments to meet documented traceability mandates. Semi-metallic suppliers serving commercial vehicle channels face the steepest compliance cost absorption.
Fleet procurement departments are consolidating brake pad purchasing under national maintenance contracts with specified performance metrics. Large commercial operators in Gujarat and Maharashtra are displacing decentralized branch-level buying with centralized category management. This concentration is visible most acutely in long-haul logistics verticals operating interstate corridors.
India Brake Pads Market Segmentation
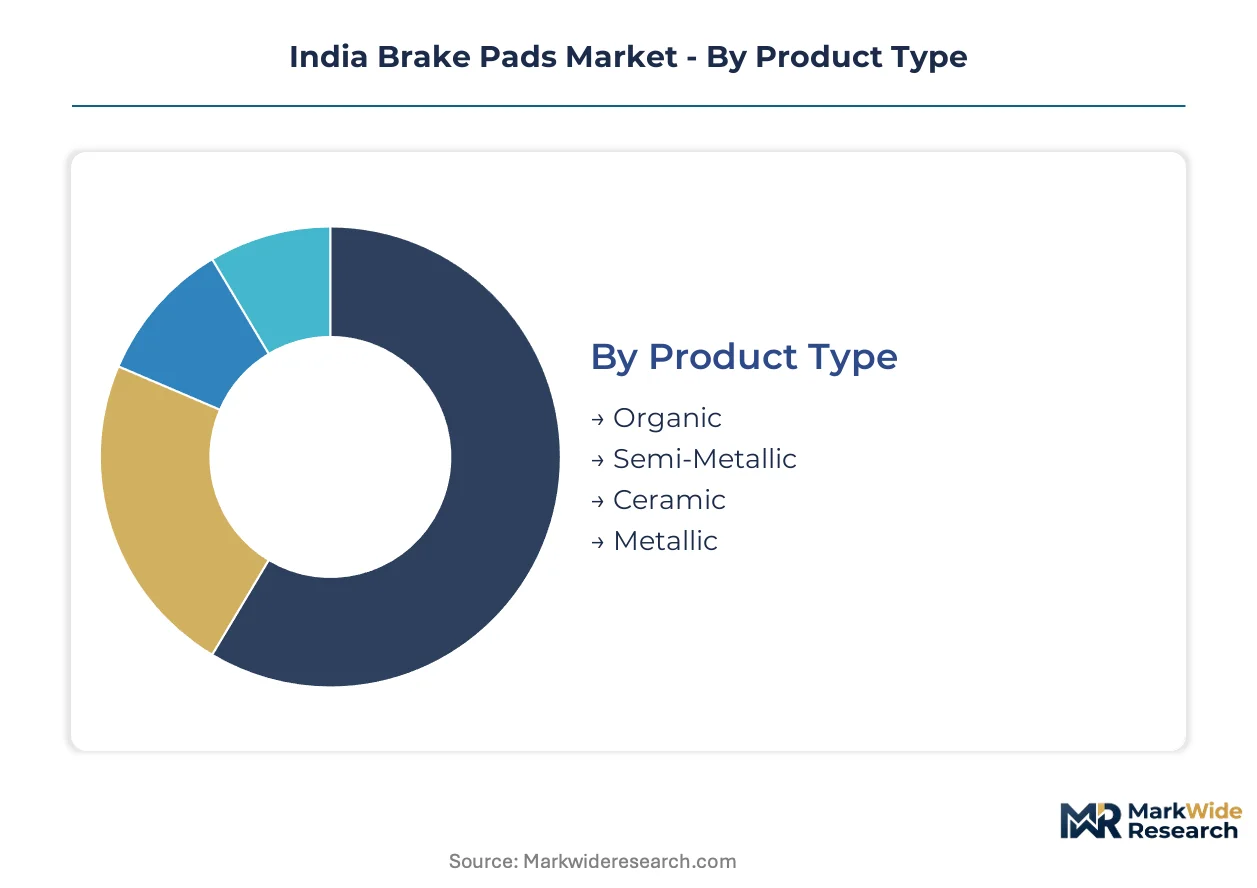
Friction material suppliers in India configure production lines around distinct thermal performance envelopes and customer procurement rhythms. Segment boundaries reflect divergent certification requirements, margin structures, and geographic demand clustering across the country's automotive manufacturing belts.
Product Type:
Supply concentration for raw friction substrates shapes competitive positioning across formulation categories, with phenolic resin availability and ceramic fiber import licensing creating divergent cost structures.
- Semi-Metallic:Steel wool and copper fiber matrices bonded with phenolic resins deliver thermal durability under sustained load cycles. Fleet operators across Maharashtra and Gujarat specify these formulations for long-haul commercial contracts where brake fade resistance outweighs noise considerations.
- Ceramic:Silicate fiber and non-ferrous filler architectures suppress dust generation and NVH characteristics. Delhi-Mumbai corridor passenger vehicle OEMs specify ceramic grades for premium platform fitments where consumer comfort metrics drive supplier selection.
- Organic:Glass, rubber, and Kevlar fiber blends in organic resin matrices serve cost-sensitive replacement channels. Two-wheeler aftermarket distributors in tier-2 cities stock organic formulations for price-driven motorcycle service intervals.
- Metallic:Sintered metal powder compacts withstand extreme thermal loads in specialized applications. Racing circuit suppliers and heavy-duty mining equipment operators procure metallic pads for non-automotive friction requirements.
Semi-metallic formulations absorb the bulk of installed capacity; ceramic segments are expanding most quickly.
End User:
Customer procurement scale and technical specification authority fragment the value chain, with centralized fleet purchasing diverging from decentralized two-wheeler service channel buying.
- Commercial Vehicles:Interstate logistics operators and intracity freight fleets specify friction materials through national maintenance contracts with documented wear-rate guarantees. Gujarat-based cement and petroleum product transporters compress replacement cycles below OEM recommendations to minimize downtime liability.
- Passenger Vehicles:Maruti Suzuki, Hyundai, and Tata Motors assembly plants in Haryana and Maharashtra drive just-in-sequence supply requirements. OEM friction contracts demand IS 11852 certification with batch-level traceability documentation.
- Two-Wheelers:Hero MotoCorp and TVS Motor production volumes anchor OEM demand, while independent repair networks in Tamil Nadu and Karnataka states generate replacement pull through distributor-stocked inventory.
- Heavy-Duty Trucks:Mining and construction equipment operators in Odisha and Chhattisgarh specify severe-duty formulations for drum brake architectures retained in off-highway applications.
Commercial vehicle channels dominate production allocation; two-wheeler aftermarket segments are climbing the fastest.
Application:
Certification burden and warranty liability differentiate channel economics, with OEM supply requiring full type approval versus aftermarket distribution operating under component-level compliance.
- OEM:Direct supply contracts to vehicle assemblers mandate ARAI brake performance testing and BIS friction material certification. Supplier qualification timelines extend production planning horizons and concentrate procurement among certified domestic manufacturers.
- Aftermarket:Replacement demand flows through multi-tier distribution networks serving independent garages and authorized service centers. E-commerce spare parts platforms are disintermediating traditional distributor tiers for motorcycle service shops in tier-2 and tier-3 cities.
- Racing:Motorsport sanctioning bodies specify non-homologated friction compounds outside standard certification protocols. Track-day operators and circuit racing teams procure through specialized performance parts importers.
- Industrial:Crane, hoist, and material handling equipment manufacturers specify friction materials for non-automotive braking systems. These applications operate outside automotive regulatory frameworks and follow machinery safety standards.
OEM channels absorb the bulk of certified production capacity; aftermarket distribution is gaining share fastest.
Material:
Input cost volatility and import dependency structure supplier margin profiles, with domestic steel wool availability contrasting against ceramic fiber licensing requirements.
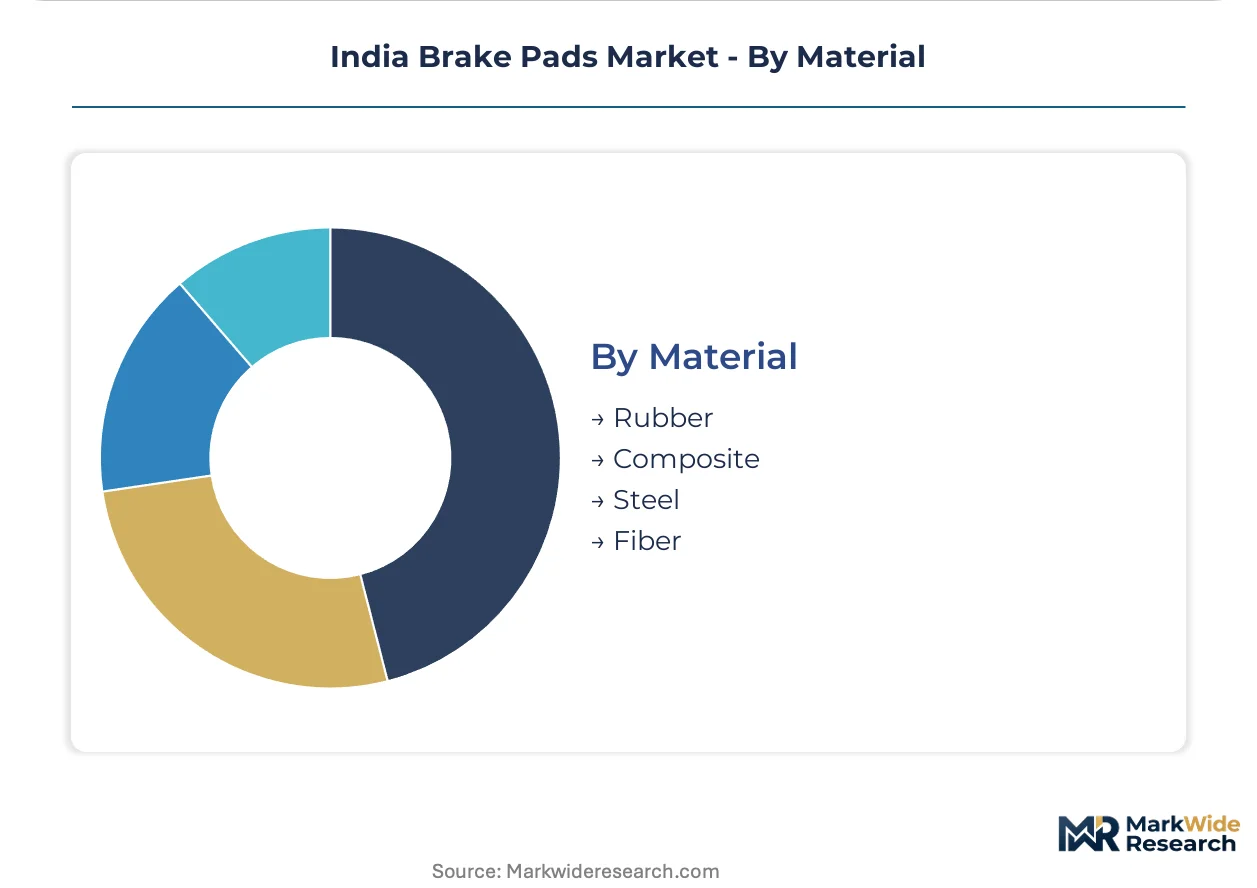
- Steel:Domestic foundry and wire drawing capacity supports semi-metallic formulation production without foreign exchange exposure. Scrap steel recycling networks in Punjab and Gujarat feed friction material fiber production.
- Composite:Engineered blends of aramid, glass, and mineral fibers balance thermal properties across mid-tier price points. Composite formulations serve standard passenger vehicle replacement channels where performance and cost tradeoffs converge.
- Fiber:Ceramic and basalt fiber substrates enable high-temperature performance in premium applications. DGFT import licensing for ceramic fiber creates supply planning complexity for specialized friction manufacturers.
- Rubber:Nitrile and SBR rubber components provide compressibility and noise damping in organic formulations. Domestic petrochemical derivatives supply rubber friction modifiers at stable cost structures.
Steel-based formulations absorb the bulk of volume production; composite materials are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vehicle fleet density concentrates brake pad procurement power across western and southern manufacturing belts. State-level vehicle scrappage policies and industrial corridor development reshape replacement demand geography.
Maharashtra
Mumbai-Pune logistics corridors generate concentrated fleet maintenance demand from cement and petroleum transporters. The state transport department enforces enhanced braking distance standards under Central Motor Vehicle Rules alignment. Nashik-Aurangabad industrial zones host passenger vehicle assembly plants pulling just-in-sequence friction material supply.
Gujarat
Port-centric freight operators compress replacement cycles below OEM specifications to minimize interstate downtime liability. BIS certification requirements for automotive friction materials eliminate substandard suppliers from procurement pools. Vadodara-Surat manufacturing belts anchor foundry capacity serving captive brake rotor casting for integrated assemblers.
Tamil Nadu
Chennai-Bengaluru electric vehicle hub development attracts regenerative braking-integrated friction suppliers. State industrial policy incentives under PLI scheme provisions support component localization for emerging EV platforms. Sriperumbudur-Oragadam auto clusters concentrate two-wheeler OEM demand from Hero MotoCorp and TVS Motor production lines.
Haryana
Maruti Suzuki and Hyundai assembly plants in Gurgaon-Manesar drive specification-grade friction material contracts. BIS IS 11852 certification mandates enforce batch-level traceability documentation for direct supply relationships. Faridabad component supplier density creates backward integration opportunities for steel wool fiber sourcing.
Karnataka
Bengaluru-Tumakuru industrial corridor expansion pulls friction material suppliers into proximity for premium passenger vehicle platforms. DGFT ceramic fiber import licensing delays create supply planning complexity for high-performance formulation producers. Independent repair networks in tier-2 cities generate aftermarket pull through distributor-stocked organic formulations.
India Brake Pads Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized performance niches and digital aftermarket channels. The supplier base concentrates among vertically integrated domestic manufacturers and technology-licensed foreign entrants. Three archetypes dominate: captive foundry operators, ceramic formulation specialists, and independent aftermarket distributors. Capacity expansion and certification-driven consolidation constitute the primary competitive vectors reshaping procurement relationships.
Among domestic friction material specialists, ASK Automotive Pvt. Ltd., Brakes India Private Limited, and Brembo Brake India Pvt. Ltd. occupy positions exemplifying distinct strategic archetypes. ASK Automotive represents vertically integrated production serving standard OEM contracts. Brakes India anchors its market presence through long-standing supply relationships with domestic vehicle assemblers. Brembo Brake India exemplifies technology-licensed premium positioning targeting high-performance platform specifications. These three entities collectively illustrate the tiered competitive structure separating volume commercial vehicle supply from passenger vehicle comfort-grade procurement.
| Leading Market Players |
|---|
| ASK Automotive Pvt. Ltd. |
| Makino Auto Industries Pvt. Ltd. |
| Brakes India Private Limited |
| Allied Nippon Private Limited |
| Masu Brake Pads Pvt. Ltd. |
| Rane Holdings Limited |
| Brembo Brake India Pvt. Ltd. |
| Sagestics Brakes |
| Endurance Technologies Limited |
| Others |
Pricing and Supply Chain Analysis
Phenolic resin spot pricing on Indian petrochemical exchanges cascades through brake pad manufacturing into three distinct procurement tiers serving fleet operators, OEM assemblers, and aftermarket distributors. Cost pass-through elasticity varies sharply across these segments, with commercial vehicle contracts absorbing feedstock volatility through annual renegotiation clauses while premium passenger vehicle platforms maintain margin buffers via ceramic formulation premiums.
Pricing Analysis
Volume-mass commercial vehicle channels trade margin for fleet scale, while ceramic OEM grades capture premium positioning through noise-suppression performance guarantees. Price differentiation hinges on BIS IS 11852 certification tier and thermal durability specifications under Central Motor Vehicle Rules braking distance mandates. Cost compression in semi-metallic formulations is intensifying because phenolic resin feedstock volatility erodes producer buffers on long-haul fleet contracts. Independent repair networks in tier-2 cities exhibit highest price sensitivity, whereas Delhi-Mumbai corridor OEMs prioritize batch traceability over unit cost.
Supply Chain Analysis
Ceramic fiber supply rests on DGFT-licensed imports from Japan and Germany, constraining high-performance formulation capacity expansion for domestic friction specialists. Raw material portfolios center on phenolic resins, steel wool from Punjab foundries, and aramid fiber composites. Single-source vulnerability concentrates in ceramic substrate licensing delays that extend qualification timelines for premium platform suppliers. Distribution runs through captive OEM supply chains, authorized service networks, and emergent e-commerce spare parts platforms disintermediating traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's brake pad sector sits at a technology-transition inflection where regenerative braking integration in Tamil Nadu electric vehicle hubs is displacing conventional friction architectures. Ceramic-steel hybrid formulations are capturing platform engineering mindshare previously reserved for legacy semi-metallic specifications.
For Market Incumbents: Anchor certification leadership through accelerated BIS IS 11852 compliance investment ahead of Ministry of Road Transport and Highways enforcement tightening. Deepen captive foundry relationships in Gujarat and Maharashtra to secure rotor casting capacity against independent pad supplier encroachment. Backward integration into phenolic resin compounding buffers margin erosion from petrochemical feedstock volatility threatening volume commercial contracts. For New Entrants and Emerging Players: PLI scheme provisions in Tamil Nadu open a window for regenerative braking-integrated friction suppliers targeting emerging EV platform qualification. White-space concentration sits in tier-3 two-wheeler aftermarket penetration via e-commerce spare parts platforms disintermediating legacy distributor hierarchies. Go-to-market positioning should emphasize DGFT ceramic fiber import license navigation as a technical services wrapper around formulation supply. For Investors and Strategic Acquirers: The window for entry favors domestic specialists with captive BIS certification and established OEM supply relationships over technology-licensed foreign entrants facing qualification timeline disadvantages. Long-term viability hinges on electric vehicle friction architecture transition execution across the Chennai-Bengaluru corridor. Watch state-level vehicle scrappage incentive alignment with replacement part demand cycles as the inflection signal for aftermarket volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| BIS IS 11852 Certification Acceleration | Compliance investment ahead of Ministry of Road Transport enforcement tightening secures OEM contract eligibility. |
| Ceramic Fiber Import License Navigation | DGFT licensing expertise creates service differentiation for high-performance formulation producers. |
| Regenerative Braking Integration R&D | Tamil Nadu EV hub development attracts friction suppliers for emerging electric platform specifications. |
| E-Commerce Aftermarket Channel Development | Digital spare parts platforms disintermediate traditional tiers for tier-2 and tier-3 motorcycle service shops. |
| Captive Foundry Capacity Securement | Backward integration into Gujarat-Maharashtra rotor casting limits independent pad supplier options. |
Research Methodology
Document review covered BIS certification registries, ARAI brake performance test protocols, and Ministry of Road Transport regulatory filings, complemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and commercial fleet maintenance directors. Secondary validation drew from vehicle production databases, customs friction material import records, and state industrial policy incentive disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation anchored market estimates.
Segment-level outputs across product type, end user, application, and material category were generated through the analytical framework over the projection horizon. Modeled dimensions included thermal performance envelope, certification tier, and regional production cluster concentration. CAGRs were derived from regression analysis against vehicle parc expansion, replacement cycle compression, and formulation mix shift assumptions. Forecast inputs incorporated phenolic resin price index trajectories and DGFT ceramic fiber licensing queue dynamics.
Caveats apply where Central Motor Vehicle Rules braking distance standard revisions or state-level scrappage incentive misalignment could materially shift replacement demand timing. Forecasts reflect documented assumptions regarding EV platform penetration and fleet operator procurement centralization. A small set of triggers—BIS enforcement intensity, ceramic fiber import license processing velocity, and Tamil Nadu EV hub localization pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Apron Bus Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Tappet Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Heavy Duty Engines Market
Automotive Parts
Transfer Case Market