
 Global Automotive Flywheel Market | 2026-2036
Global Automotive Flywheel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Flywheel Market Intelligence
The material science gap between lightweight composite flywheels for motorsports applications and conventional single-mass steel units for economy passenger cars is broadening. This divergence creates distinct value chains and engineering requirements. Schaeffler AG specializes in advanced dual-mass flywheel systems to dampen vibrations in modern engines. ZF Friedrichshafen AG competes with integrated powertrain solutions, while Valeo SA leverages its expertise in clutch systems to offer complete transmission components.
An automotive flywheel is a heavy rotating disc, typically made from cast iron or billet steel, engineered to store kinetic energy. Its primary function is smoothing power pulses from an engine's pistons, ensuring consistent rotational speed. Dual-mass flywheel products command the premium passenger vehicle segment due to superior noise and vibration reduction. The more durable single-mass flywheel remains the standard for most commercial truck applications.
Emissions standards from the US Environmental Protection Agency (EPA) and vehicle noise regulations from Germany's Kraftfahrt-Bundesamt (KBA) influence flywheel design toward more efficient and quieter systems. In parallel, China's GB standards for vehicle components mandate specific material and performance criteria for market access. Component manufacturers must now decide whether to invest in composite materials for hybrid applications or optimize legacy designs for the global aftermarket.
Market Dynamics
The primary structural force shaping the automotive flywheel market is the bifurcation of material science and design philosophy. This divergence is driven by parallel demands for lightweight composite units in hybrid systems and durable, cost-effective steel designs for conventional powertrains.
Growth Catalysts
- EU Green Deal:This policy framework accelerates powertrain efficiency research, creating demand for innovative lightweight flywheel materials that improve fuel economy and reduce emissions in hybrid vehicles.
- Heavy-Duty Truck Segment:Sustained expansion in logistics and construction drives volume for robust, single-mass steel flywheels, which are essential for the durability required in heavy-duty commercial trucks.
- OEM Manufacturing Clusters:The concentration of automotive production in geographies like China and Mexico creates localized, high-volume demand for OEM flywheel components, simplifying supply chains for manufacturers with a local presence.
Market Restraints
- Input Cost Volatility:The high and fluctuating cost of carbon fiber and other composite materials creates a significant price barrier, limiting their adoption to high-performance and premium vehicle segments.
- Substitution by BEVs:The long-term transition to pure battery electric vehicles, which do not utilize a conventional flywheel, presents an existential threat to the entire product category.
- Technical Limitations:Composite flywheels face durability and heat dissipation challenges in high-torque applications, making them unsuitable for many commercial and heavy-duty vehicle platforms currently dominated by steel.
Strategic Opportunities
- Hybrid Material Systems:Developing flywheels that combine composite and metal elements offers a pathway to balance weight reduction with the cost and durability requirements of mass-market hybrid passenger cars.
- Aftermarket Performance Niche:A dedicated market exists for specialized billet steel and composite flywheels designed for motorsports and enthusiast vehicle modifications, representing a high-margin opportunity.
- Service and Replacement Parts:Targeting the aftermarket in regions with older vehicle fleets provides a stable revenue stream for standard single-mass and dual-mass replacement units.
Industry Challenges
- Divergent Regulatory Compliance:Manufacturers must invest significant resources to meet conflicting or unique performance mandates, such as China's GB standards, Germany's KBA noise rules, and US EPA emissions targets.
- System Integration Complexity:Integrating advanced dual-mass flywheels with sophisticated multi-speed transmissions and hybrid powertrains requires deep engineering expertise and extensive validation testing to manage vibrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Flywheel Market |
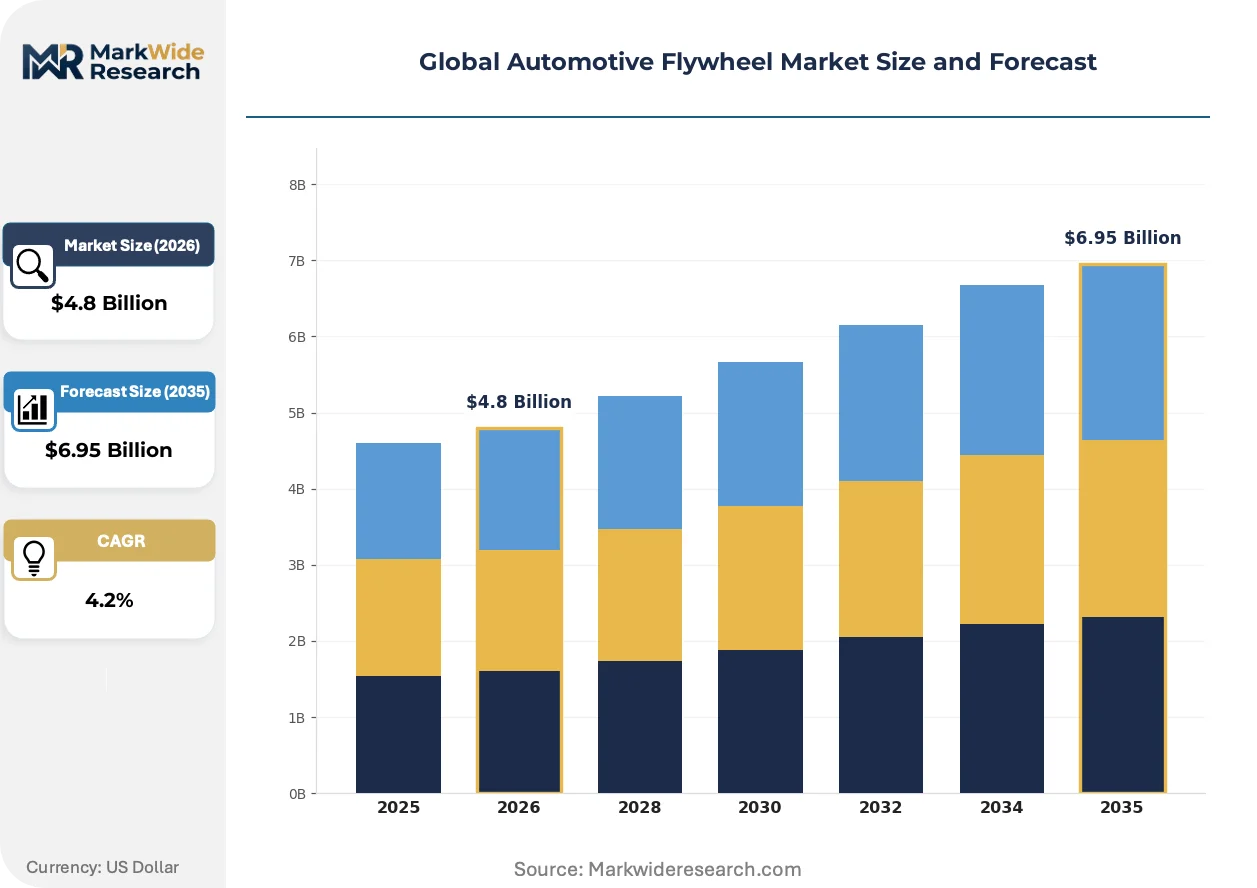
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Mass, Dual Mass, Composite, Multi-Plate Technology: Mechanical, Electromagnetic, Hydraulic, Hybrid Application: Passenger Vehicles, Commercial Trucks, Off-Road Vehicles, Motorsports End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Schaeffler AG, ZF Friedrichshafen AG, Valeo SA, Aisin Corporation, BorgWarner Inc., EXEDY Corporation, Linamar Corporation, Magna International Inc., Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Flywheel Market Strategic Shifts & Innovations
Powertrain diversification is fundamentally redefining the flywheel from a passive inertial damper into an active component of energy management systems. This evolution forces manufacturers to choose between optimizing legacy designs for cost or investing in new materials for hybrid-specific functions.
Lightweight composite materials are enabling new flywheel designs for high-performance applications. The motorsport and premium hybrid segments are the primary adopters of this technology, valuing its ability to improve engine response and store kinetic energy. This advanced flywheel is absorbing the function of a short-term mechanical battery, reducing the performance gap between a simple rotating mass and an electrical energy storage system.
Germany's Kraftfahrt-Bundesamt (KBA) vehicle noise regulations impose strict limits on powertrain sound and vibration. This directly impacts flywheel design by increasing the technical requirements for noise, vibration, and harshness (NVH) suppression. The premium passenger vehicle segment is most affected, leading to the widespread adoption of complex dual-mass flywheel systems to meet these stringent acoustic standards.
A behavioral shift in the aftermarket is seeing some vehicle owners opt for performance-oriented flywheel upgrades over standard OEM-spec replacements. This disrupts the traditional like-for-like repair model, particularly within the independent automotive service channel. This trend is most visible in North American and European markets where a strong car enthusiast and modification culture exists for specific vehicle platforms.
Global Automotive Flywheel Market Segmentation
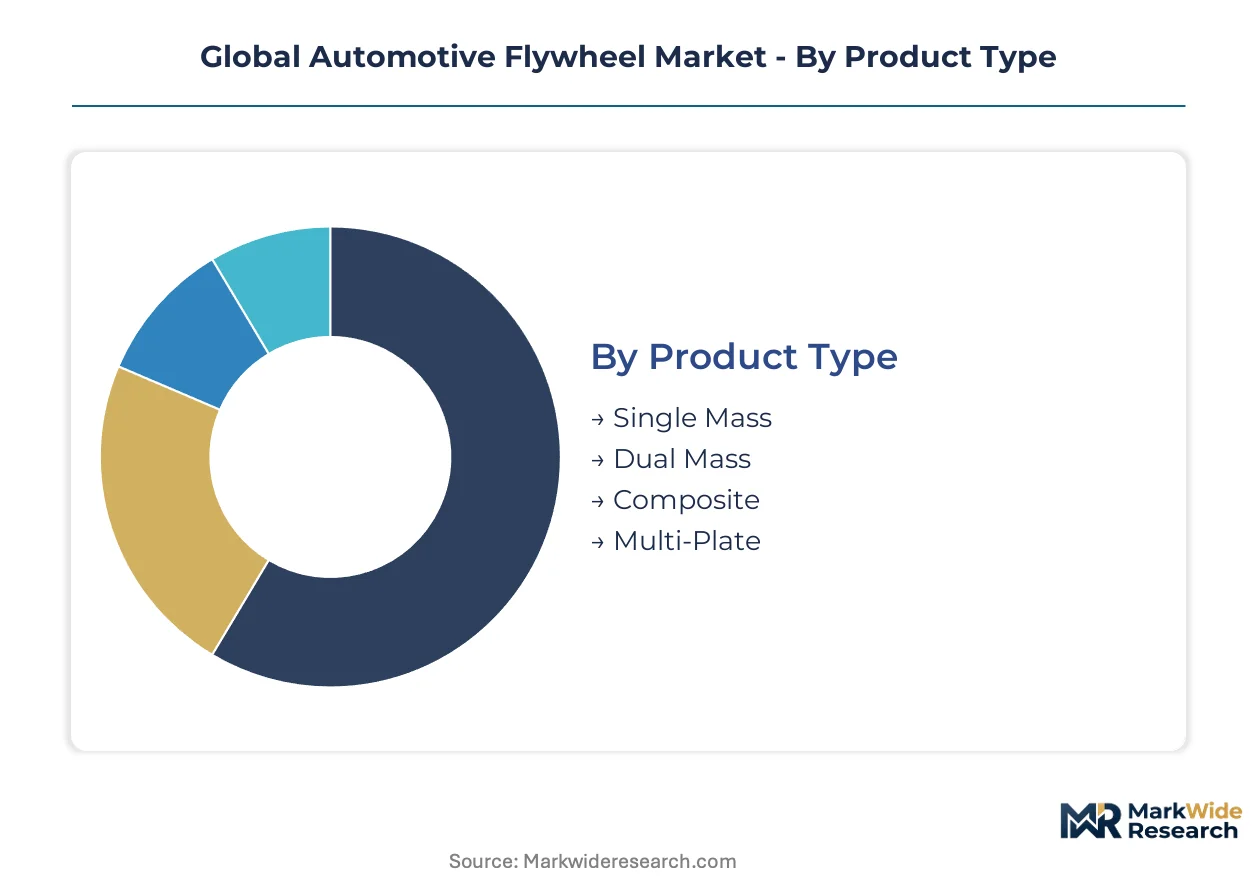
The automotive flywheel market's diverse requirements necessitate a granular understanding of its segmentation. Different vehicle types, performance needs, and cost considerations drive distinct product and technology preferences. This detailed analysis clarifies where value is created across the various market dimensions.
Product Type:
The upgrade and replacement cycle for automotive flywheels often dictates the choice between traditional and advanced designs.
- Single Mass:This robust and cost-effective flywheel, typically made from cast iron or billet steel, provides basic engine smoothing and power transmission. Demand remains consistent for conventional powertrains in commercial truck applications due to its durability.
- Dual Mass:Engineered with two separate masses connected by a spring-damper system, this type significantly reduces torsional vibrations and noise, enhancing driving comfort. Premium passenger vehicle segments in Germany and Japan increasingly adopt dual-mass units for superior NVH characteristics.
- Composite:Utilizing lightweight materials such as carbon fiber, composite flywheels offer reduced inertia and improved engine response, making them ideal for high-performance and hybrid applications. Motorsports and specialized hybrid systems in Europe are primary adopters, valuing their energy storage capabilities.
- Multi-Plate:These flywheels feature multiple friction surfaces, allowing for higher torque capacity and more precise engagement, often found in high-performance or heavy-duty industrial applications.
Volume placements concentrate in Single Mass; the faster expansion belongs to Composite.
Technology:
Cost tiering significantly influences the adoption of various flywheel technologies, balancing performance with manufacturing expense.
- Mechanical:This traditional technology relies on the flywheel's rotational inertia to smooth engine power pulses and store kinetic energy. Mechanical systems remain the standard for most internal combustion engine vehicles due to their proven reliability and manufacturing simplicity.
- Electromagnetic:Leveraging magnetic forces for energy transfer and damping, electromagnetic flywheels offer precise control over rotational speed and vibration, often integrated into advanced powertrain systems. Demand for these systems is emerging in specialized industrial machinery.
- Hydraulic:Hydraulic flywheels use fluid dynamics to absorb and release energy, providing effective vibration damping in specific heavy-duty industrial and off-road equipment. These systems offer robust performance under extreme conditions.
- Hybrid:Integrating mechanical and electrical components, hybrid flywheels function as advanced energy storage devices, contributing to fuel efficiency and emissions reduction in hybrid electric vehicles. Powertrain diversification in China and the US drives demand for hybrid flywheel solutions.
Application focus drives differentiation across these technological offerings.
Application:
Volume demand for automotive flywheels is heavily skewed towards specific vehicle applications, reflecting production scale.
- Passenger Vehicles:This segment includes a broad range of cars, from economy models using single-mass flywheels to luxury vehicles adopting advanced dual-mass systems for enhanced comfort. Regulatory pushes for powertrain efficiency in Europe accelerate innovation within this segment.
- Commercial Trucks:Heavy-duty commercial trucks require robust and durable flywheels, primarily single-mass steel units, to withstand high torque loads and continuous operation. Sustained expansion in logistics and construction drives consistent demand across North America and Asia.
- Off-Road Vehicles:Flywheels for off-road vehicles must endure harsh operating conditions, including extreme temperatures and vibrations, necessitating durable and reliable designs. Agricultural machinery and construction equipment represent key end-uses.
- Motorsports:High-performance composite flywheels are crucial for motorsports, offering rapid engine response and significant weight reduction, critical for competitive racing applications.
Market maturity varies significantly across these application segments.
End User Industry:
Supply concentration within the automotive value chain shapes the purchasing dynamics for flywheel components.
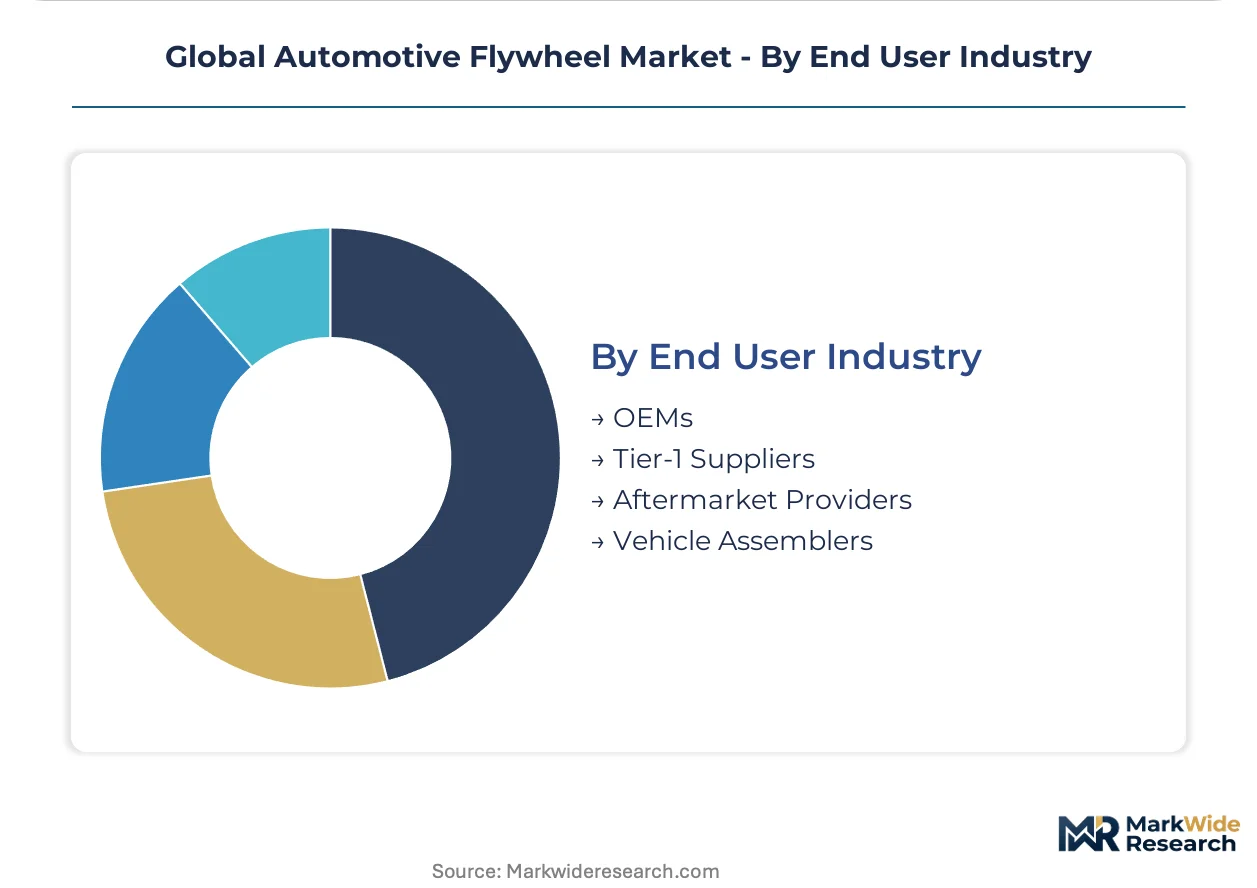
- OEMs:Original Equipment Manufacturers integrate flywheels directly into new vehicle production lines, demanding high-volume supply, stringent quality control, and adherence to specific design specifications. Automotive manufacturing clusters in Mexico and China are major OEM demand centers.
- Tier-1 Suppliers:These companies provide complete sub-assemblies and systems, including flywheels, directly to OEMs, often collaborating on design and engineering. Tier-1 suppliers maintain complex relationships with both raw material providers and vehicle manufacturers.
- Aftermarket Providers:This segment supplies replacement flywheels for vehicle repair and maintenance, catering to both independent garages and authorized service centers. Aftermarket demand in regions with older vehicle fleets, such as parts of North America, provides stable revenue streams.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, sourcing components from various suppliers, including flywheels, to meet production targets.
Strategic partnerships are critical for navigating the complexities of each end-user industry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturing hubs like those within China's Yangtze River Delta drive significant demand for flywheel components. These localized production clusters, alongside others in Mexico and Germany, concentrate OEM procurement activities. Policy frameworks and local market dynamics heavily influence product preferences across these key regions.
China
China's vast automotive production volume creates substantial demand for both single-mass and hybrid flywheel solutions. The country's GB standards for vehicle components mandate specific material and performance criteria for market access. Manufacturing centers in Shanghai and Guangzhou are particularly active, focusing on high-volume production for domestic and export markets.
Germany
Germany's robust premium vehicle segment demands advanced dual-mass flywheels for superior noise and vibration reduction. The Kraftfahrt-Bundesamt (KBA) regulations impose stringent vehicle noise limits, directly impacting flywheel design. Stuttgart's automotive cluster, home to major luxury brands, prioritizes these sophisticated systems for enhanced driving comfort.
Mexico
Mexico's strategic position as a North American automotive manufacturing hub drives consistent demand for OEM flywheel components. The country's favorable trade agreements and established supply chains attract major vehicle producers. Production facilities in cities like Puebla and Monterrey serve as critical supply points for the North American market.
United States
The United States market exhibits bifurcated demand for durable single-mass units in commercial trucks and advanced flywheels for hybrid passenger vehicles. US Environmental Protection Agency (EPA) emissions standards influence design toward greater efficiency. Automotive centers in Michigan, particularly around Detroit, remain central to component development and vehicle assembly.
Japan
Japan's mature automotive industry emphasizes precision engineering and lightweight solutions for fuel efficiency. The Ministry of Economy, Trade and Industry (METI) promotes innovation in advanced materials for vehicle components. Nagoya's Chubu region, a major automotive production base, focuses on integrating new flywheel technologies into hybrid and conventional powertrains.
Global Automotive Flywheel Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in the automotive flywheel sector. The market exhibits a tiered structure, with established manufacturers dominating high-volume OEM supply chains and specialized firms targeting premium aftermarket niches. Strategic archetypes include integrated powertrain solution providers, advanced material developers, and conventional component specialists. Companies pursue portfolio diversification into hybrid systems and strategic partnerships to navigate evolving powertrain technologies.
Specialists in advanced transmission components and vibration damping systems include Schaeffler AG, a German-based company known for dual-mass flywheel systems. ZF Friedrichshafen AG, another German corporation, represents integrated powertrain solution providers. Valeo SA, a French automotive supplier, exemplifies expertise in clutch systems and complete transmission components.
| Leading Market Players |
|---|
| Schaeffler AG |
| ZF Friedrichshafen AG |
| Valeo SA |
| Aisin Corporation |
| BorgWarner Inc. |
| EXEDY Corporation |
| Linamar Corporation |
| Magna International Inc. |
| Eaton Corporation |
| Others |
Cost & Logistics Intelligence
Original Equipment Manufacturers' concentrated purchasing power heavily influences flywheel component pricing, often dictating long-term contract models over spot market transactions. This buyer-side concentration fosters a competitive environment for suppliers, particularly for high-volume standard units.
Pricing Analysis
Value-based pricing anchors premium dual-mass and composite flywheels to their enhanced performance attributes, such as superior noise and vibration reduction. Price differentiation stems from material composition, with carbon fiber composites commanding higher values, and the level of engineering customization required for specific powertrain integrations. Pricing pressure stems from the high cost volatility of raw materials like steel and carbon fiber, impacting manufacturers' margins. Commercial truck operators, prioritizing durability and cost-effectiveness, represent the most price-sensitive segment, while luxury vehicle OEMs are less sensitive to component cost for advanced systems.
Supply Chain Analysis
Logistics and freight costs significantly impact the delivered price of flywheels, particularly for heavy steel units shipped globally. Geographic supply concentration for automotive components centers on China, Mexico, and Germany, where major manufacturing clusters exist. The supply chain relies heavily on raw materials like cast iron, billet steel, and specialized composite fibers. Single-source vulnerability for advanced composite materials represents a structural supply chain risk. Downstream distribution runs through a mix of direct OEM supply channels and a fragmented aftermarket network of distributors and independent garages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with composite flywheels gradually replacing traditional steel units in specific high-performance and hybrid applications.
For Market Incumbents: Acquire advanced material science capabilities or partner with composite specialists to secure a competitive edge in hybrid flywheel development. Consolidate production lines for single-mass steel units in high-volume regions like China and Mexico to leverage economies of scale against cost pressures. The long-term threat from Battery Electric Vehicles (BEVs) necessitates diversification into integrated powertrain solutions beyond traditional flywheel components.
For New Entrants and Emerging Players: Specialized aftermarket distributors offer an accessible channel to introduce high-performance billet steel or composite flywheels for enthusiast vehicle modifications. Target the North American and European performance aftermarket, focusing on specific vehicle platforms with strong modification cultures. A go-to-market angle emphasizing superior power delivery and weight reduction will resonate with this niche. Underpenetration in specialized industrial applications also presents an opportunity.
For Investors and Strategic Acquirers: The window for entry favors patient investors targeting companies with robust intellectual property in hybrid flywheel systems or unique composite manufacturing processes. Focus on mid-sized firms offering proprietary vibration damping technologies or lightweight material expertise. A signal to watch is the increasing investment by Tier-1 suppliers into dedicated hybrid powertrain component divisions, indicating a shift in strategic focus and potential acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Composite Flywheel R&D | Develop lighter, more efficient flywheels for hybrid and performance vehicle segments, meeting evolving emissions standards. |
| Expand Dual-Mass Production Capacity | Cater to the growing demand for superior NVH reduction in premium passenger vehicles, particularly in Europe. |
| Form Strategic Partnerships with OEMs | Ensure early integration of new flywheel designs into next-generation vehicle platforms, securing long-term supply contracts. |
| Optimize Steel Flywheel Manufacturing | Maintain cost competitiveness and durability for high-volume commercial truck and economy passenger vehicle applications. |
| Develop Aftermarket Performance Kits | Capture high-margin revenue from vehicle enthusiasts seeking specialized upgrades in North America and Europe. |
Research Approach
Document review covered automotive industry reports, regulatory filings from the US EPA and Germany's KBA, and technical specifications from leading manufacturers, complemented by interviews with OEM procurement managers, Tier-1 engineering leads, and aftermarket distributors. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Bottom-up and top-down triangulation reconciled disparate data points.
Market volume and value projections were developed through an analytical framework that modeled demand across the analysis window. Segmentation dimensions included product type, technology, application, and end-user industry, alongside regional production clusters. Compound annual growth rates were derived from historical data trends and projected shifts in vehicle electrification and regulatory mandates. Key forecast inputs included vehicle production forecasts and material cost trajectories.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or radical breakthroughs in battery technology that could accelerate BEV adoption beyond current projections. The forecasts reflect assumptions documented regarding technological evolution and regulatory stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Dynamic Chassis Control System Market
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Automotive Canister Market