
 Global Automotive Timing Belt Market | 2026-2036
Global Automotive Timing Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Timing Belt Market Analysis
Aftermarket providers is rotating toward a larger share of total demand as aging vehicle fleets in North America and Europe extend replacement cycles beyond traditional intervals. Mitsuboshi Belting Ltd. leverages its rubber compounding expertise to dominate replacement channels across Asia-Pacific. Gates Corporation sustains technology leadership in aramid-reinforced synchronous belt architectures for high-load commercial applications. Continental AG anchors European OEM supply relationships through integrated powertrain system partnerships.
An automotive timing belt is a toothed drive belt fabricated from reinforced rubber compounds, polyurethane, or steel-cord composites, engineered to synchronize crankshaft and camshaft rotation within precise tolerance windows of one to two degrees. Its primary commercial purpose is to prevent valve-to-piston interference in interference engines while transmitting power to auxiliary components such as water pumps and oil pumps. Rubber belts occupy the mature volume tier in passenger vehicle OEM fitments, while polyurethane belts capture margin pools in performance and extended-life aftermarket segments. Synchronous belts lead technology migration as engine downsourcing and turbocharging intensify load requirements across OEM and industrial equipment applications.
The US EPA, the European Commission through Euro 7 frameworks, and China's MEE enforce progressively tighter emission and fuel-efficiency mandates that compel manufacturers to tighten valve timing precision and accelerate belt replacement specifications. REACH and RoHS constraints in Europe further restrict phthalate plasticizers and heavy-metal additives in rubber formulations, reshaping material sourcing for suppliers serving EU-registered vehicles. Stakeholders must monitor regulatory divergence between emission regimes and material compliance standards when configuring regional product portfolios and replacement service networks.
Market Dynamics
Engine downsizing and forced induction are compressing belt load cycles while EPA and Euro 7 mandates tighten tolerance windows, forcing synchronous belt architectures to absorb higher thermal and mechanical stress without extending replacement intervals.
Growth Catalysts
- Euro 7 emission frameworks:Tighter valve timing precision mandates in the European Union are accelerating specification upgrades across OEM supply chains for high-performance synchronous belts.
- Hybrid powertrain expansion:Belt-driven starter-generator systems in 48V mild-hybrid architectures are creating incremental belt positions per vehicle platform.
- China:Domestic OEM capacity expansion for internal combustion and hybrid vehicle production is concentrating demand for rubber timing belts in tier-one supplier networks.
Market Restraints
- Aramid fiber cost volatility:Petroleum-derived synthetic fiber pricing swings compress margin pools for reinforced belt manufacturers serving commercial vehicle segments.
- Chain substitution in high-performance engines:Timing chain architectures are capturing share in premium displacement engines above 2.0 liters where durability requirements exceed belt capabilities.
- REACH compliance friction:ECHA restrictions on phthalate plasticizers and heavy-metal additives force reformulation cycles that extend new product qualification timelines by 12-18 months.
Strategic Opportunities
- India aftermarket penetration:Aging vehicle parc and service network expansion in tier-two and tier-three cities create replacement volume growth outside organized dealer channels.
- Polyurethane material convergence:Extended-life belt compounds are capturing margin pools in performance aftermarket segments where replacement intervals stretch beyond 150,000 kilometers.
- Amazon and Alibaba digital distribution:E-commerce platforms are disintermediating traditional parts distributors for DIY replacement purchases in North America and Asia-Pacific.
Industry Challenges
- Compound formulation expertise scarcity:Rubber chemists with synchronous belt-specific knowledge are concentrating at incumbent suppliers, constraining new entrant technical staffing.
- OEM qualification timeline compression:Accelerated platform development cycles force belt suppliers to compress validation testing without compromising durability certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Timing Belt Market |
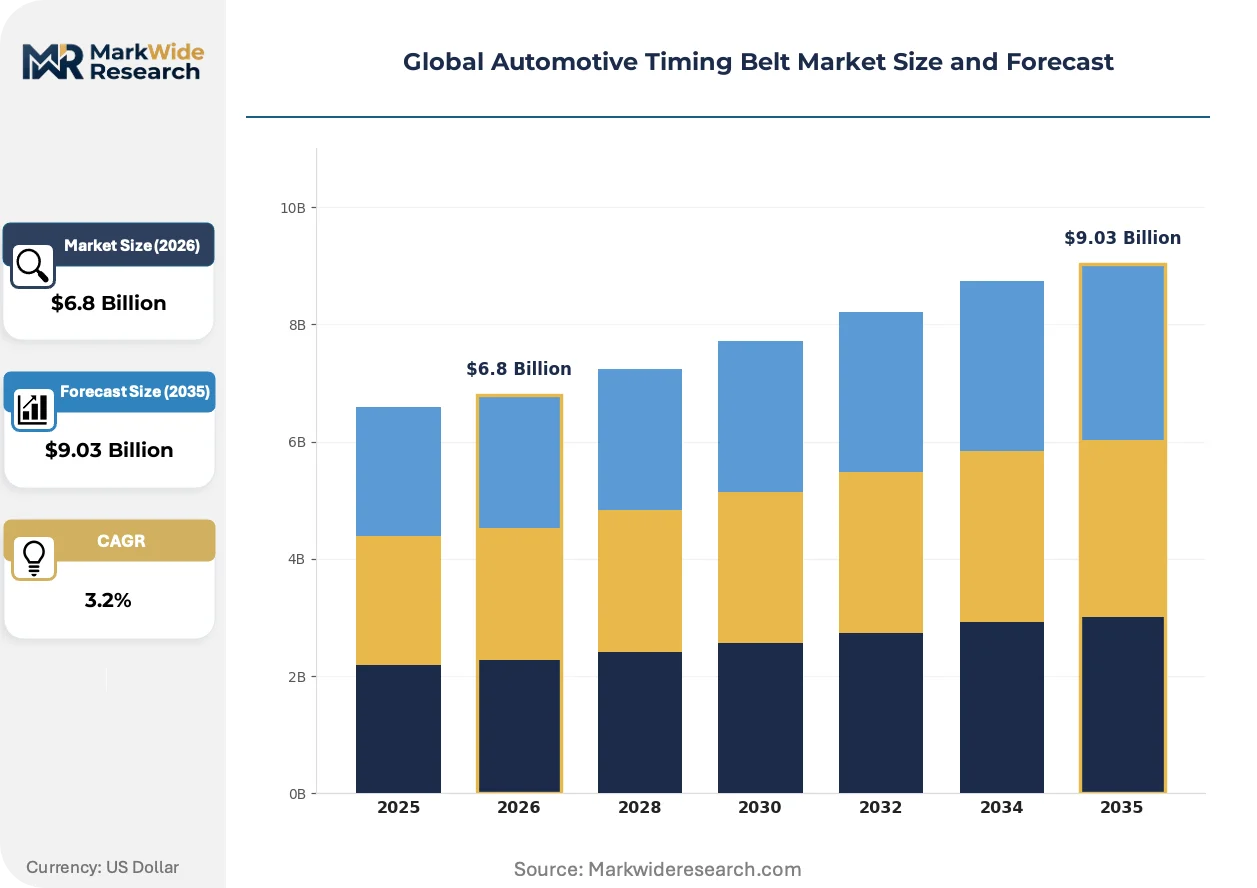
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.03 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Belts, Polyurethane Belts, Steel Belts, Synchronous Belts End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Maintenance Services Application: Passenger Vehicles, Commercial Vehicles, Industrial Equipment, Recreational Vehicles Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Mitsuboshi Belting Ltd., Optibelt GmbH, Gates Corporation, Tsubakimoto Chain Co., Megadyne Group, Continental AG, Bando Chemical Industries Ltd., Schaeffler AG, Dayco Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Timing Belt Market Emerging Trajectories
Material science advances and regulatory precision mandates are bifurcating the synchronous belt landscape into extended-life premium tiers and cost-optimized standard tiers, with distinct supply chain configurations serving each trajectory.
Aramid-reinforced rubber compounds are bifurcating the high-load belt segment. Commercial vehicle OEMs in North America and heavy-duty applications in Germany are specifying these materials for turbocharged diesel platforms. The technology is bifurcating supplier capabilities between compound specialists and commodity converters.
REACH and RoHS constraints in Europe are reshaping rubber formulation sourcing. ECHA enforcement of phthalate restrictions and heavy-metal limits is forcing compounders to qualify bio-based plasticizers and alternative cure systems. Belt suppliers serving EU-registered vehicles are absorbing reformulation costs while maintaining price positions in export markets with divergent material standards.
Aftermarket service unbundling is compressing replacement cycle timing. Independent repair shops and mobile technicians in the United States and United Kingdom are capturing share from dealer networks by offering timing belt replacement as standalone services rather than bundled maintenance packages. This pattern is most visible in vehicle populations aged 8-12 years where warranty expiration eliminates dealer capture.
Global Automotive Timing Belt Market Segmentation
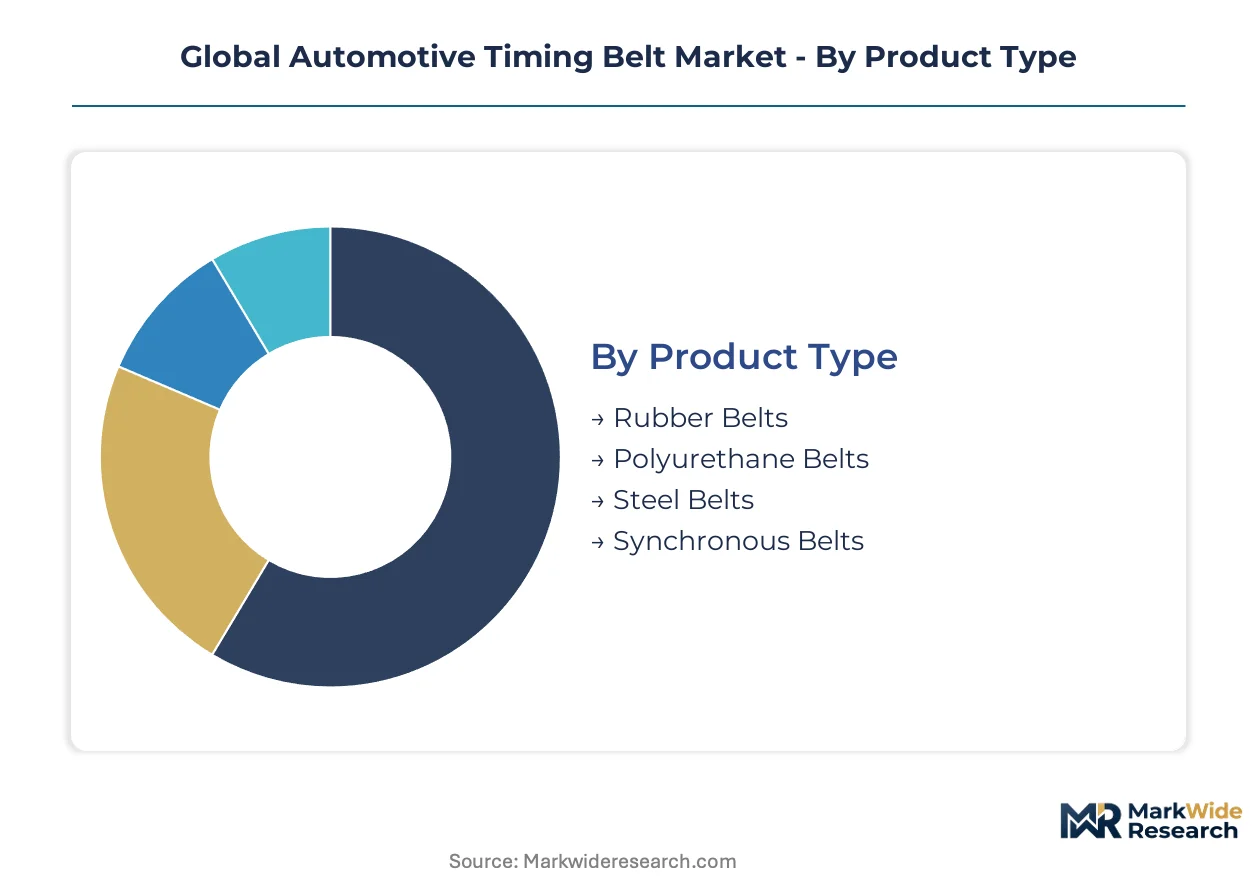
Timing belt segmentation reveals how material science and channel economics partition value capture across the supply chain. Product type stratification determines margin pools, while end-user concentration shapes replacement cycle timing and qualification requirements.
Product Type:
Rubber compounds face the most acute substitution pressure from polyurethane and aramid-reinforced alternatives as load requirements intensify across downsized engine architectures.
- Rubber Belts:Fabricated from neoprene or HNBR compounds with fiberglass tensile cords, these belts dominate passenger vehicle OEM fitments where cost optimization outweighs extended-life requirements. Demand concentrates in China as domestic OEMs expand internal combustion and hybrid production capacity for mass-market vehicle platforms.
- Synchronous Belts:Engineered with precision-molded tooth profiles and aramid or carbon fiber reinforcement, these belts transmit higher loads across variable valve timing systems and belt-driven starter-generator architectures. Euro 7 tolerance mandates are accelerating specification upgrades across European OEM supply chains for high-performance synchronous belt architectures.
- Polyurethane Belts:Cast thermoplastic elastomer compounds deliver extended service intervals exceeding 150,000 kilometers in performance aftermarket applications.
- Steel Belts:Steel-cord composite constructions serve niche industrial equipment and heavy-duty commercial segments where thermal stability exceeds rubber operational limits.
Rubber Belts anchors the volume base while Synchronous Belts gains share at the steepest rate.
End User:
Channel economics bifurcate sharply between captive OEM supply relationships and fragmented aftermarket service networks with divergent margin structures.
- Aftermarket Providers:Independent repair shops, mobile technicians, and digital platforms capture replacement demand as vehicle parc ages beyond warranty coverage in North America and Europe. Unbundled timing belt replacement services are compressing cycle timing versus bundled dealer maintenance packages for vehicle populations aged 8-12 years.
- OEMs:Original equipment manufacturers specify belt architectures during powertrain development cycles with qualification timelines spanning 24-36 months. EPA and Euro 7 emission mandates are tightening valve timing precision requirements and accelerating replacement interval specifications across OEM supply chains.
- Vehicle Assemblers:Contract manufacturing partners integrate timing belts into complete powertrain modules for domestic OEMs in China and India.
- Maintenance Services:Fleet operators and dealership service departments manage scheduled replacement programs for commercial vehicle populations.
Aftermarket Providers command the expanding profit pool while OEMs retain the highest technical barrier to entry.
Application:
Load cycle intensity and replacement accessibility create divergent material specifications across vehicle duty cycles.
- Passenger Vehicles:Mass-market sedans, crossovers, and light trucks specify rubber or entry-synchronous belts where 100,000-kilometer replacement intervals align with consumer maintenance expectations. Belt-driven starter-generator systems in 48V mild-hybrid architectures are creating incremental belt positions per vehicle platform across German and Japanese OEM lineups.
- Commercial Vehicles:Heavy-duty diesel platforms and turbocharged delivery vans demand aramid-reinforced synchronous belts to absorb higher thermal and mechanical stress without interval extension. North American fleet operators are specifying these materials for turbocharged diesel platforms with compressed maintenance windows.
- Industrial Equipment:Stationary engines and material handling systems utilize steel-cord or heavy-duty synchronous constructions.
- Recreational Vehicles:Marine and powersports applications require specialized corrosion-resistant compounds.
Passenger Vehicles generates the largest absolute volume while Commercial Vehicles delivers the highest per-unit margin contribution.
Distribution Channel:
Digital disintermediation is restructuring parts procurement patterns across DIY and professional installer segments.
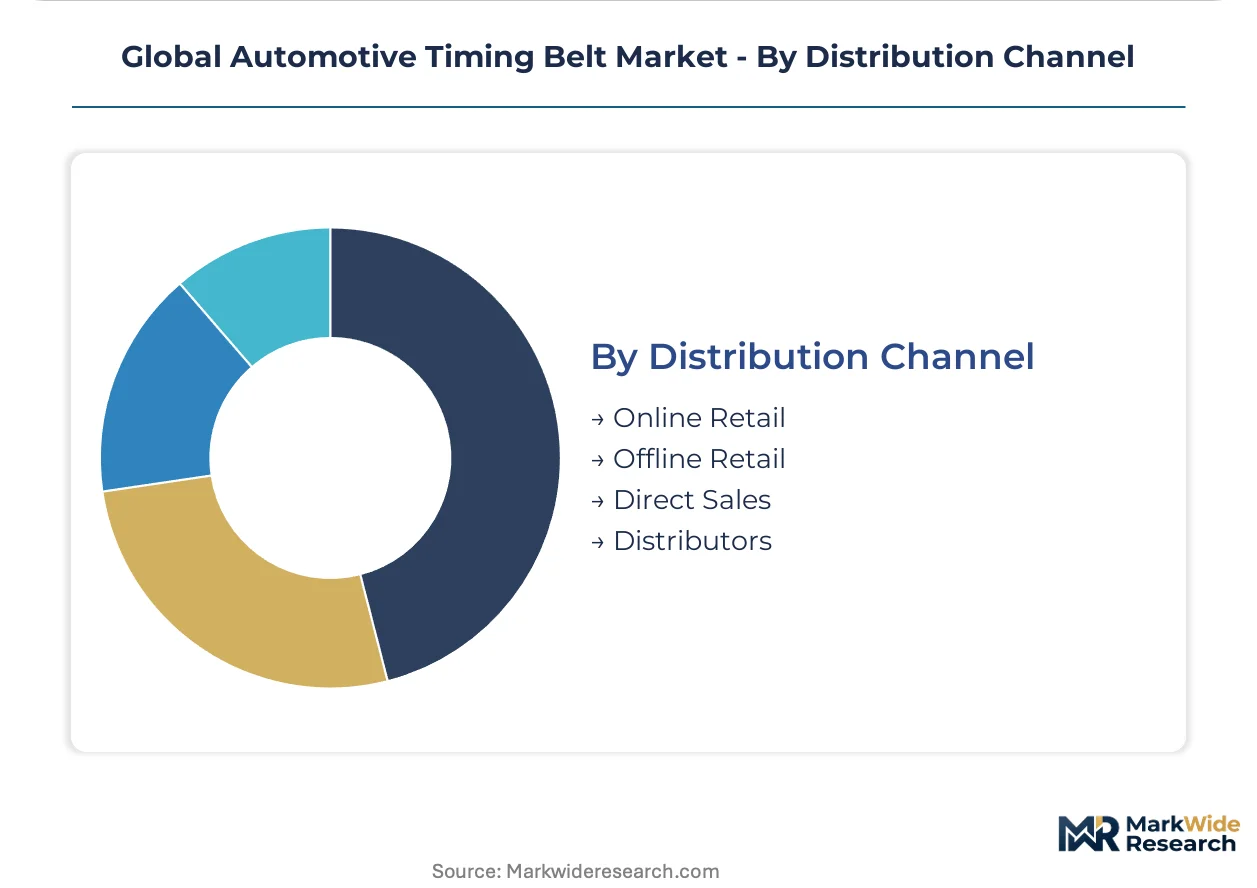
- Online Retail:Amazon, Alibaba, and specialized automotive platforms are capturing share from traditional distributors for DIY replacement purchases in North America and Asia-Pacific. E-commerce penetration is accelerating as vehicle owners research specifications and compare pricing across regional supplier networks.
- Distributors:National and regional parts wholesalers maintain inventory depth and technical support for professional repair shops. These intermediaries absorb working capital requirements while providing same-day availability for emergency replacement scenarios.
- Offline Retail:Brick-and-mortar auto parts chains serve immediate-need purchases and specification verification.
- Direct Sales:Tier-one suppliers contract directly with OEMs and large fleet operators for volume supply agreements.
Distributors retain the professional installer relationship while Online Retail expands most quickly in consumer-direct segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered synchronous belt systems to Chinese OEMs and North American commercial vehicle manufacturers. Trade corridors between Stuttgart industrial clusters and Shanghai assembly plants concentrate high-value belt architectures. Cross-border supply chains route through Rotterdam port infrastructure for REACH-compliant compound distribution.
China
Domestic OEM capacity expansion for internal combustion and hybrid platforms concentrates demand in Yangtze River Delta manufacturing corridors. MEE emission enforcement tightens valve timing precision requirements for vehicles registered in Beijing and Shanghai metropolitan zones. Tier-one supplier networks in Jiangsu and Zhejiang provinces qualify synchronous belt specifications for export-bound production lines.
Germany
Commercial vehicle OEMs specify aramid-reinforced architectures for turbocharged diesel platforms serving compressed maintenance windows. KBA type-approval processes enforce Euro 7 tolerance mandates that accelerate belt replacement interval specifications. Industrial clusters in Stuttgart and Munich anchor development partnerships between belt suppliers and powertrain engineering centers.
United States
Aftermarket service unbundling compresses replacement cycle timing for vehicle populations aged 8-12 years in Texas and California metropolitan markets. EPA emission standards tighten tolerance windows for valve timing precision across light-duty truck platforms. Detroit-area engineering centers coordinate qualification timelines with belt suppliers for next-generation powertrain architectures.
India
Aging vehicle parc in tier-two and tier-three cities creates replacement volume growth outside organized dealer channels. BIS certification requirements shape material sourcing for suppliers serving domestic OEM assembly operations. Manufacturing corridors in Maharashtra and Tamil Nadu concentrate belt fabrication capacity for export and domestic fitment.
Japan
48V mild-hybrid architectures create incremental belt positions per vehicle platform across domestic OEM lineups. METI energy efficiency mandates accelerate specification upgrades for belt-driven starter-generator systems. Industrial clusters in Aichi Prefecture coordinate synchronous belt integration with variable valve timing system development.
Global Automotive Timing Belt Market Vendor Landscape
Listed leaders compete with private specialists across compound formulation capabilities and OEM qualification access. The supplier base organizes into three tiers: integrated rubber compounders with captive polymer science, regional fabricators serving aftermarket channels, and diversified industrial conglomerates with powertrain system partnerships. Consolidation pressure intensifies as OEMs compress platform development cycles. Strategic moves center on backward integration into aramid fiber supply and geographic expansion into Chinese tier-one supplier networks.
Within the integrated compounder tier, Mitsuboshi Belting Ltd. and Gates Corporation exemplify archetypes spanning Asian replacement channel dominance and North American commercial vehicle specification leadership. Continental AG occupies a position bridging European OEM system partnerships with aftermarket distribution scale. Among specialized fabricators, Optibelt GmbH and Tsubakimoto Chain Co. represent German and Japanese engineering traditions in precision synchronous belt architectures.
| Leading Market Players |
|---|
| Mitsuboshi Belting Ltd. |
| Optibelt GmbH |
| Gates Corporation |
| Tsubakimoto Chain Co. |
| Megadyne Group |
| Continental AG |
| Bando Chemical Industries Ltd. |
| Schaeffler AG |
| Dayco Products LLC |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between aramid fiber suppliers and tier-one belt manufacturers lock in both raw material access and cost visibility across the analysis window, insulating compounders from petroleum-derived synthetic fiber volatility while anchoring price positions for synchronous belt architectures serving Euro 7-compliant European OEMs and North American commercial vehicle platforms.
Pricing Analysis
Next-generation aramid-reinforced synchronous belts command 40-60% price premiums over standard rubber compounds, while prior-generation neoprene constructions face accelerated erosion in mass-market passenger fitments. Three-tier pricing structure across premium, standard, and economy levels separates compound specialists from commodity converters, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard rubber tiers is intensifying because Chinese domestic OEMs are consolidating supplier panels around Yangtze River Delta manufacturing corridors. Fleet operators and commercial vehicle buyers exhibit lowest price sensitivity due to total cost-of-ownership calculations, while independent repair shops in India aftermarket channels remain most price-sensitive.
Supply Chain Analysis
Strategic stockpile preferences dominate aramid fiber procurement given petroleum price volatility, while just-in-time inventory management governs rubber compound flows to tier-one fabricators. Manufacturing gravity centers on China, Germany, and Japan, with Jiangsu province, Stuttgart industrial clusters, and Aichi Prefecture anchoring synchronous belt fabrication capacity. Raw material sourcing draws from Saudi aramid fiber production, Malaysian natural rubber plantations, and German specialty chemical additives. Single-source vulnerability concentrates in aramid fiber supply chains where three global producers control capacity. Distribution runs through Rotterdam port infrastructure for REACH-compliant compound distribution to European OEMs, while Alibaba and Amazon disintermediate traditional distributors for aftermarket channels in Asia-Pacific and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against timing chain architectures capturing share in premium displacement engines above 2.0 liters, where durability requirements exceed belt capabilities and threaten margin pools in the highest-value OEM segments.
For Market Incumbents: Compound formulation expertise scarcity by acquiring regional rubber chemist teams in Asia-Pacific, while backward integration into aramid fiber supply secures cost positions against petroleum volatility. OEM qualification timeline compression threatens technical staffing retention; defend by embedding compound scientists within Detroit-area and Stuttgart engineering centers during platform development cycles. For New Entrants and Emerging Players: Mobile technician service layers in India tier-two and tier-three cities present white-space where organized dealer networks under-serve aging vehicle parc. Target polyurethane extended-life aftermarket segments where replacement intervals exceed 150,000 kilometers and margin pools detach from commodity rubber competition. Deploy digital-first go-to-market through Amazon and Alibaba platforms to bypass entrenched distributor relationships in North America and Asia-Pacific. For Investors and Strategic Acquirers: Regional fabricators with captive OEM qualification access in Chinese tier-one supplier networks represent acquisition targets with defensive moats against consolidation pressure. Long-term viability hinges on compound science differentiation surviving electrification transition windows. Watch hybrid powertrain platform announcements from German and Japanese OEMs as inflection indicators for incremental belt position creation in 48V mild-hybrid architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Supply | Secures cost visibility against petroleum volatility for Continental AG and Gates Corporation serving commercial vehicle platforms. |
| REACH-Compliant Compound Reformulation | Accelerates ECHA qualification timelines by 12-18 months for suppliers serving EU-registered vehicle populations. |
| Digital Platform Distribution Partnership | Disintermediates traditional parts distributors through Amazon and Alibaba for DIY replacement purchases in North America. |
| Mobile Service Network Expansion | Captures unbundled timing belt replacement demand from aging vehicle parc in India tier-two and tier-three cities. |
| Hybrid Powertrain System Integration | Creates incremental belt positions per vehicle platform across Japanese and German OEM 48V mild-hybrid architectures. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from listed automotive suppliers, with bottom-up triangulation across OEM platform engineering directors, tier-one supplier procurement leads, aftermarket distributor operations heads, and independent repair shop owners in North America, Europe, and Asia-Pacific.
Segmentation dimensions modeled span product type stratification across rubber, synchronous, polyurethane, and steel-cord constructions; end-user concentration between OEM captive relationships and aftermarket service networks; application intensity across passenger vehicle, commercial vehicle, and industrial equipment duty cycles; and distribution channel evolution through digital platforms versus traditional wholesale intermediaries. CAGRs were derived from production volume trajectories, content-per-vehicle assumptions for belt-driven starter-generator systems, and replacement cycle compression factors across aging vehicle parc in key regional markets.
Underlying assumptions cover sustained internal combustion and hybrid platform production in China, Euro 7 enforcement timelines across European Union member states, and aramid fiber supply stability from Saudi and domestic Japanese producers, with deviation risk concentrated in accelerated timing chain substitution in premium engine displacements and REACH reformulation cost absorption capacity among mid-tier compounders. Practitioners should keep alternative scenarios live as electrification transition pace and hybrid architecture penetration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Automotive Surface Coated Brake Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
South Africa Electric Power Steering Market
Automotive Parts
Automotive Antifreeze Market