

Resin Silencer Market Size, Share, and Industry Trends Forecast 2026-2036
Resin Silencer Market Insights
Buyer concentration among manufacturing equipment OEMs is recalibrating procurement leverage across the supply base. SMC Corporation leverages captive injection molding capacity to control cost position in acoustic resin silencers. Festo anchors European specification standards through its embedded design engineering relationships with machinery builders. Parker Hannifin competes on geographic reach, extending distribution density across North American industrial corridors.
Resin silencers are engineered polymer components that attenuate pneumatic exhaust noise through tuned internal chambers and porous resin matrices, typically rated for operating pressures up to 1.0 MPa and temperature ranges from -5°C to 60°C depending on base resin formulation. Their primary purpose is to bring compressed air systems into compliance with workplace noise exposure limits while preventing particulate contamination of exhaust streams. Acoustic resin silencers dominate unit volume due to universal fitment across standard pneumatic valves, while multi-layer resin silencers command margin premiums in semiconductor and food processing environments where dual attenuation and filtration functions consolidate component count. Injection molding technology leads throughput economics at scale, though 3D printing is gaining traction in aftermarket and legacy equipment retrofit programs where tooling amortization proves prohibitive.
OSHA workplace noise regulations in the United States, the EU Machinery Directive with its CE marking requirements, and Japan's METI industrial safety standards collectively shape product certification burdens and specification minimums for cross-border equipment sales. EPA and REACH frameworks additionally constrain base resin chemistry selection, favoring suppliers with polymer science depth and regulatory affairs infrastructure. Stakeholders must monitor evolving decibel thresholds and material restriction lists to anticipate redesign cycles and qualification timelines.
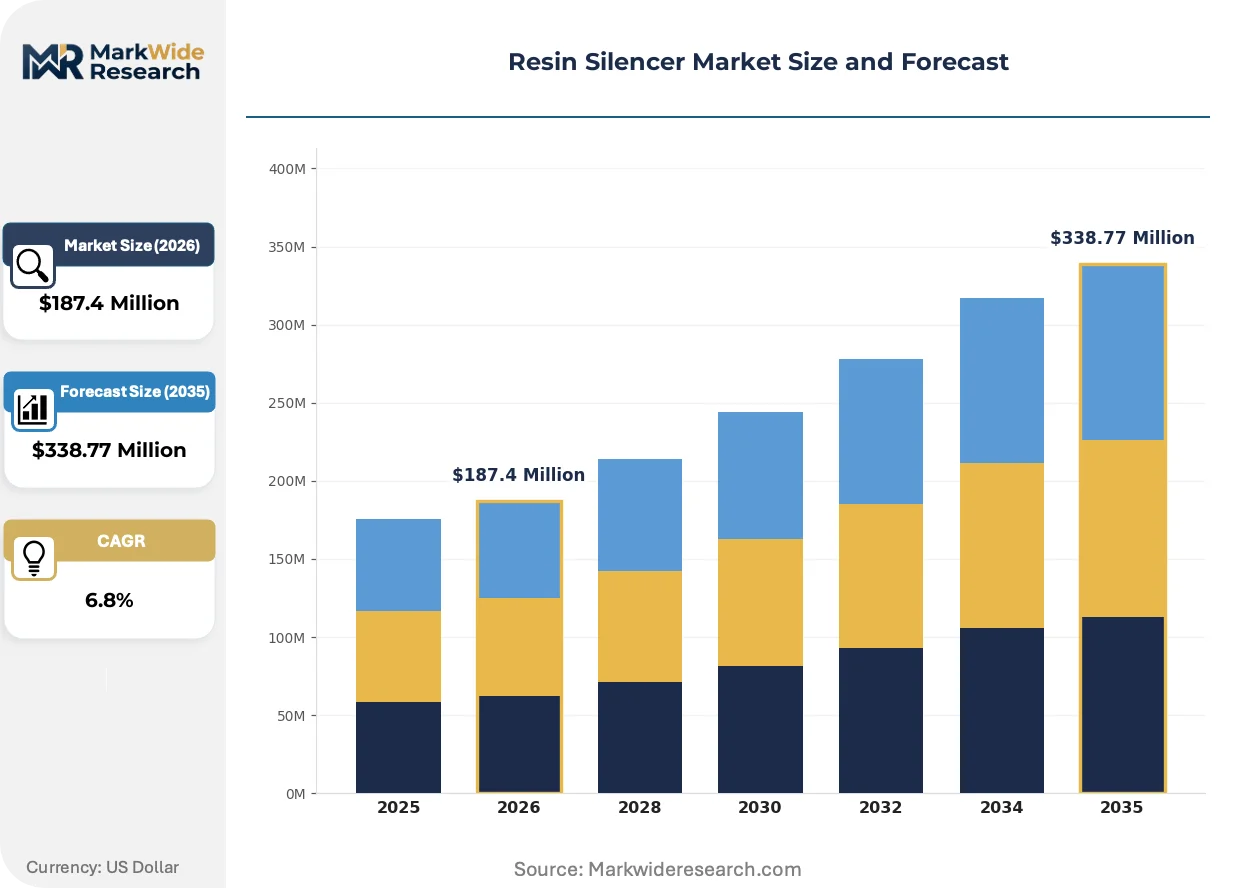
Market Dynamics
Compression molding technology is displacing legacy fabrication across high-volume pneumatic programs, concentrating production economics among equipment operators with captive polymer processing capabilities. Factory noise ordinances in industrial clusters are tightening procurement specifications and accelerating qualification timelines for acoustic attenuation components.
Growth Catalysts
- OSHA workplace noise regulations:United States manufacturing facilities face stricter decibel exposure limits, forcing compressed air system upgrades and resin silencer retrofit programs across automotive and electronics assembly plants.
- Semiconductor cleanroom expansion:Multi-layer resin silencers with integrated filtration functions consolidate component count in wafer fabrication environments where particulate control and acoustic attenuation share specification priority.
- Food processing automation:Pneumatic OEMs in Germany and Japan specify resin silencers for washdown-compatible machinery, linking hygiene-grade polymer formulations to equipment export eligibility.
Market Restraints
- Base resin cost volatility:Engineering polymer feedstock prices fluctuate with crude oil derivatives and specialty additive supply, compressing margin buffers for injection molding-dependent producers.
- REACH substance restrictions:ECHA candidate list expansions constrain flame-retardant and plasticizer chemistries, triggering reformulation cycles and requalification costs for European market access.
- Metallic silencer substitution:Stainless steel alternatives persist in high-temperature pneumatic applications above 60°C, limiting resin penetration in heavy machinery exhaust systems.
Strategic Opportunities
- India industrial corridor buildout:PLI scheme incentives for manufacturing equipment OEMs create specification pull for cost-optimized acoustic resin silencers in Pune and Chennai industrial zones.
- 3D-printed aftermarket channels:Legacy equipment retrofit programs bypass tooling amortization barriers through additive manufacturing, opening service revenue streams for obsolete pneumatic valve formats.
- EU Green Deal circularity mandates:Design-for-recycling requirements favor mono-material resin constructions over multi-layer assemblies, rewarding polymer science capabilities in next-generation product development.
Industry Challenges
- Acoustic engineering talent scarcity:Tuned chamber design and porous matrix optimization require specialized simulation expertise that concentrates among Tier-1 pneumatic OEMs and their captive engineering partners.
- Cross-border certification timelines:CE marking under the EU Machinery Directive, METI industrial safety approvals in Japan, and OSHA compliance documentation create staggered product launch windows that fragment inventory planning.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resin Silencer Market Trends and Innovations
Resin silencer engineering is pivoting toward configurable platform architectures that reduce SKU proliferation while accommodating divergent regional noise regulations. Material science advances and digital manufacturing methods are compressing the traditional trade-off between acoustic performance and production economics.
Multi-cavity injection mold designs with interchangeable core inserts are modularizing product families around shared base geometries. Pneumatic OEMs in Germany and the United States specify these platforms to cover decibel rating variants without dedicated tooling for each configuration. The approach collapses qualification overhead and enables faster regional specification responses.
REACH framework expansions are constraining halogenated flame retardants in acoustic resin formulations, forcing suppliers toward phosphorus-based and mineral filler alternatives. ECHA regulatory pressure is most acute for semiconductor and food processing applications where material safety documentation faces downstream customer audit. Japanese METI standards are converging with EU restrictions, creating harmonized chemistry constraints across major export markets.
Equipment operators are consolidating vendor relationships around pneumatic system integrators who bundle acoustic components with valve and actuator procurement. Machinery builders in Japan and Germany now specify resin silencers through embedded design engineering contracts rather than discrete component sourcing. The pattern concentrates specification influence with Festo, SMC Corporation, and Parker Hannifin while marginalizing standalone acoustic component distributors.
Resin Silencer Market Segmentation
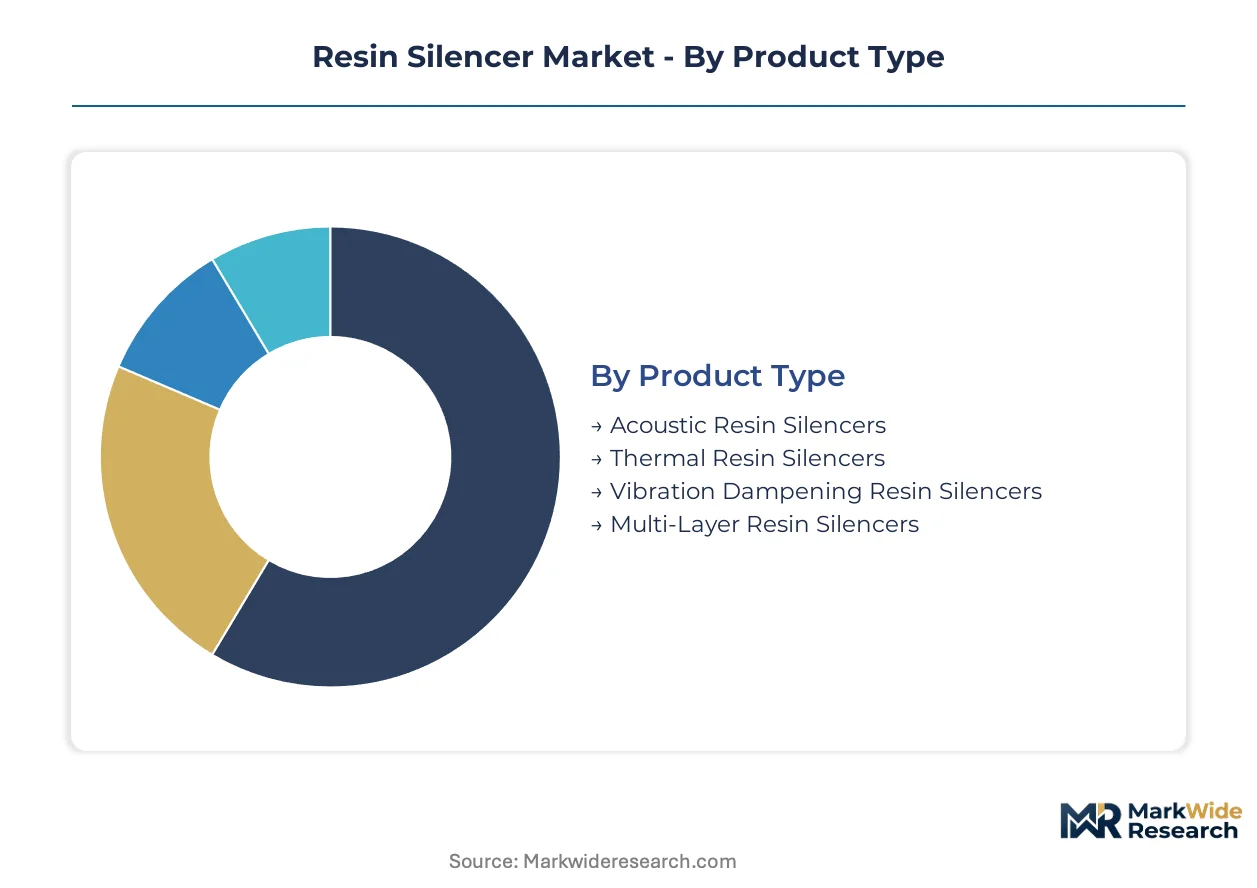
Resin silencer procurement patterns diverge sharply across product architectures and fabrication methods. Upgrade cycles in factory automation and tightening noise ordinances are fragmenting specification requirements, forcing suppliers to maintain parallel product lines across acoustic performance tiers and regulatory compliance levels.
Product Type:
Replacement demand in compressed air systems is accelerating as legacy metallic silencers age out of service life, creating upgrade pathways that favor polymer alternatives with lower mass and integrated filtration.
- Acoustic Resin Silencers:Engineered with tuned internal chambers and porous resin matrices to attenuate pneumatic exhaust noise. Demand concentrates in Germany, Japan, and the United States where pneumatic OEMs anchor specification standards for manufacturing equipment. OSHA workplace noise regulations are forcing retrofit programs across automotive and electronics assembly plants.
- Multi-Layer Resin Silencers:Combine dual attenuation and filtration functions through stratified resin constructions. Semiconductor cleanroom expansion in Japan and Germany drives specification pull where particulate control shares priority with acoustic performance. REACH substance restrictions constrain halogenated flame retardants in these formulations.
- Thermal Resin Silencers:Engineered for heat dissipation in exhaust streams with elevated operating temperatures.
- Vibration Dampening Resin Silencers:Integrate elastomeric layers to isolate mechanical resonance in heavy machinery mounting points.
Acoustic Resin Silencers sits at the top of the volume ranking, with Multi-Layer Resin Silencers climbing the fastest.
Technology:
Cost tier differentiation in fabrication economics is concentrating procurement leverage among equipment operators with captive polymer processing capabilities.
- Injection Molding:Delivers throughput leadership at scale through multi-cavity mold designs with interchangeable core inserts. SMC Corporation leverages captive capacity to control cost position in high-volume pneumatic programs.
- Compression Molding:Displacing legacy fabrication across high-volume programs with lower tooling complexity for thick-walled acoustic components.
- Resin Casting:Serves low-volume specialty applications requiring complex internal geometries impractical for mold-based methods.
- 3D Printing:Gaining traction in aftermarket and legacy equipment retrofit programs where tooling amortization proves prohibitive for obsolete pneumatic valve formats.
Injection Molding commands the volume base, while 3D Printing is expanding most quickly in service revenue channels.
Application:
Customer type segmentation reveals divergent specification authority between machinery builders and end-user facilities.
- Manufacturing Equipment:Factory noise ordinances in industrial clusters are tightening procurement specifications. Festo anchors European specification standards through embedded design engineering relationships with machinery builders.
- Industrial Machinery:Heavy equipment OEMs specify resin silencers for washdown-compatible machinery in food processing automation.
- HVAC Systems:Building automation integrators source acoustic attenuation for centralized air handling units.
- Agricultural Machinery:Equipment manufacturers face less stringent noise regulation, limiting specification premium capture.
Manufacturing Equipment holds the installed base, with Industrial Machinery gaining share fastest in export-oriented machinery programs.
End User Industry:
Geography-driven demand concentration is shaping regional specification standards and certification requirements.
- Construction Equipment Providers:Specifying acoustic resin silencers for compact machinery operating in urban noise-restricted zones. Parker Hannifin competes on geographic reach across North American industrial corridors serving this segment.
- Aircraft Component Makers:Requiring lightweight polymer solutions where mass reduction offsets acoustic performance trade-offs.
- Marine Equipment Suppliers:Face salt corrosion constraints that limit resin penetration relative to stainless steel alternatives.
- Mining Operations:High-temperature pneumatic applications above 60°C sustain metallic silencer preference, capping resin adoption.
Construction Equipment Providers dominate current procurement volume, with Aircraft Component Makers showing the steepest expansion trajectory on weight-driven specification shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pneumatic OEMs set acoustic specification benchmarks that Japanese machinery builders increasingly reference, while the United States drives retrofit demand through enforcement of stricter workplace noise limits.
United States
Automotive and electronics assembly plants are accelerating compressed air system upgrades. OSHA workplace noise regulations are forcing resin silencer retrofit programs across industrial facilities. The Midwest industrial corridor spanning Michigan and Ohio sees concentrated procurement activity among tier-one manufacturing equipment operators.
Germany
Food processing automation and semiconductor equipment exports are driving specification pull for washdown-compatible polymer formulations. EU Machinery Directive CE marking requirements shape product certification minimums for cross-border machinery sales. The Baden-Württemberg and Bavaria industrial clusters host embedded design engineering relationships between Festo and machinery builders.
Japan
Wafer fabrication cleanroom expansion is propelling multi-layer resin silencer demand where particulate control shares priority with acoustic attenuation. METI industrial safety standards are converging with EU REACH restrictions on halogenated flame retardants. The Chubu region around Nagoya anchors pneumatic OEM specification authority for export-oriented machinery programs.
India
Manufacturing equipment OEMs are expanding procurement of cost-optimized acoustic components under PLI scheme incentives. Central government production-linked incentive schemes are creating specification pull for industrial automation components. The Pune and Chennai industrial zones are emerging as concentrated demand centers for pneumatic system upgrades.
China
Factory automation upgrade cycles are tightening noise ordinance enforcement across coastal industrial clusters. GB standards and MIIT industrial safety frameworks are elevating product certification requirements for domestic and export equipment sales. The Yangtze River Delta region around Shanghai sees accelerated qualification timelines for acoustic attenuation components in automotive assembly applications.
Resin Silencer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated pneumatic system providers with captive polymer processing, standalone acoustic component specialists serving aftermarket channels, and diversified industrial conglomerates leveraging geographic distribution density. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players prioritizing embedded design engineering relationships over discrete component sourcing.
Among Japan-based integrated providers, SMC Corporation exemplifies the captive manufacturing archetype through controlled injection molding capacity. Festo GmbH represents the European specification authority model, anchoring design engineering relationships with machinery builders. Parker Hannifin Corporation occupies the geographic reach position, extending distribution density across North American industrial corridors.
| Leading Market Players |
|---|
| SMC Corporation |
| Festo |
| Parker Hannifin |
| IMI |
| NORGREN |
| Metal Work Pneumatic |
| PISCO |
| AIRTAC International Group |
| Humphrey Products |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap polymer processors in Germany and Japan anchor supply discipline through generational capital allocation patterns that resist cyclical price-cutting. Their conservative balance sheet management sustains pricing floors even when injection molding capacity utilization fluctuates, while embedded design engineering contracts with Festo and SMC Corporation lock in volume commitments that buffer spot-market volatility. This ownership structure concentrates bargaining power with machinery builders who bundle acoustic components into pneumatic system procurement.
Pricing Analysis
Capacity additions in China's Yangtze River Delta industrial cluster are reshaping price floors for standard acoustic resin silencers. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked semiconductor-grade formulations from general manufacturing equipment specifications. Price differentiation hinges on REACH compliance documentation and multi-cavity mold economies of scale. Cost compression in economy-tier acoustic silencers is intensifying because 3D-printed aftermarket channels bypass traditional tooling amortization. Construction equipment providers exhibit the highest price sensitivity due to project-based procurement cycles, while semiconductor cleanroom operators absorb premium pricing for particulate-control-integrated multi-layer constructions.
Supply Chain Analysis
Single-source vulnerability sits with Japanese engineering polymer compounders who dominate halogenated flame-retardant alternatives for REACH-constrained formulations. Manufacturing concentration centers on Germany, Japan, and the United States where pneumatic OEMs anchor captive injection molding capacity. Raw material dependencies draw from crude oil derivatives for base resins, phosphorus-based flame retardants, and mineral fillers for acoustic matrix optimization. Tariff exposure on Chinese-molded components threatens cost-optimized supply routes for European machinery exports. Distribution runs through embedded design engineering contracts rather than discrete component channels, concentrating specification authority with integrated pneumatic system providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story where specification authority migrates toward embedded design engineering relationships and away from spot procurement. Demand is tilting toward premium multi-layer resin silencers in semiconductor and food processing environments where dual attenuation and filtration functions consolidate component count.
For Market Incumbents: Anticipate margin compression from 3D-printed aftermarket channels by deepening captive polymer processing capabilities and accelerating REACH-compliant formulation transitions. Backward integration into specialty additive compounding secures supply continuity as ECHA substance restrictions expand. Defensive consolidation of embedded design engineering contracts with German and Japanese machinery builders protects specification authority against geographic expansion plays by North American distributors. For New Entrants and Emerging Players: Capture white-space opportunity in India's Pune and Chennai industrial corridors where PLI scheme incentives for manufacturing equipment OEMs create specification pull for cost-optimized acoustic components. Aftermarket retrofit programs for obsolete pneumatic valve formats offer the most penetrable entry vector given prohibitive tooling economics for legacy equipment formats. Go-to-market execution should prioritize 3D printing service partnerships that bypass capital-intensive mold fabrication. For Investors and Strategic Acquirers: Pneumatic system integrators with captive polymer processing capabilities are the most active acquirer in this space, seeking to consolidate specification influence through vertical manufacturing control. Long-term viability over a multi-year horizon rests on regulatory compliance infrastructure depth rather than pure manufacturing scale. Acquisition targets should display polymer science R&D capabilities alongside embedded customer relationships. The signal to watch is ECHA candidate list expansion velocity, which triggers reformulation investment cycles that favor well-capitalized incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Additive Compounding | ECHA REACH restrictions on halogenated flame retardants force chemistry control. |
| Embedded Design Engineering Contract Expansion | Festo's machinery builder relationships demonstrate specification authority concentration. |
| 3D-Printed Aftermarket Service Launch | Legacy equipment retrofit bypasses tooling amortization barriers for obsolete formats. |
| Multi-Cavity Mold Platform Investment | Interchangeable core inserts collapse SKU proliferation across regional decibel variants. |
| REACH-Compliant Formulation Qualification | Semiconductor and food processing customers audit material safety documentation downstream. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both procurement volume patterns and specification authority dynamics. Primary fieldwork engaged pneumatic OEM procurement directors, plant engineers at automotive assembly facilities, aftermarket service managers, and regulatory affairs specialists at polymer compounders. Secondary validation drew from SEC filings of diversified industrial conglomerates, ECHA substance restriction announcements, OSHA workplace noise enforcement data, and customs records of engineering polymer trade flows. Bottom-up demand modeling triangulated against top-down pneumatic equipment production forecasts.
Segment-weighting distributed volume and value estimates across product type, fabrication technology, application category, and end-user industry dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical pneumatic equipment shipments against noise ordinance enforcement intensity. Modeled inputs included injection molding capacity utilization rates, REACH candidate list expansion schedules, and semiconductor cleanroom construction permits.
Base resin cost volatility, ECHA regulatory timeline acceleration, and metallic silencer substitution in high-temperature applications are the dominant revision risks that could compress or extend projected trajectories. Forecasts reflect documented assumptions about regional noise ordinance enforcement consistency and polymer processing technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.