
 Automotive Axle and Propeller Shaft Market | 2026-2036
Automotive Axle and Propeller Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Axle and Propeller Shaft Market Intelligence
The IATF 16949 quality management system certification is collapsing the supplier base into tiers of certified and non-certified manufacturers. Dana Holding Corporation leverages its global manufacturing footprint to serve OEMs across multiple continents. American Axle & Manufacturing Inc. specializes in driveline systems for light trucks and SUVs. ZF Friedrichshafen AG competes with a broad portfolio that includes advanced axle and transmission technologies.
Automotive axles are structural components that support vehicle weight and transfer power to the driving wheels. Propeller shafts are mechanical components designed to transmit torque and rotation, often fabricated from high-tensile steel or aluminum alloys to manage high rotational speeds. Rear axles remain the dominant product type, particularly for commercial vehicles. The adoption of carbon fiber shafts, while still a niche, represents the fastest-growing material segment due to its superior strength-to-weight ratio.
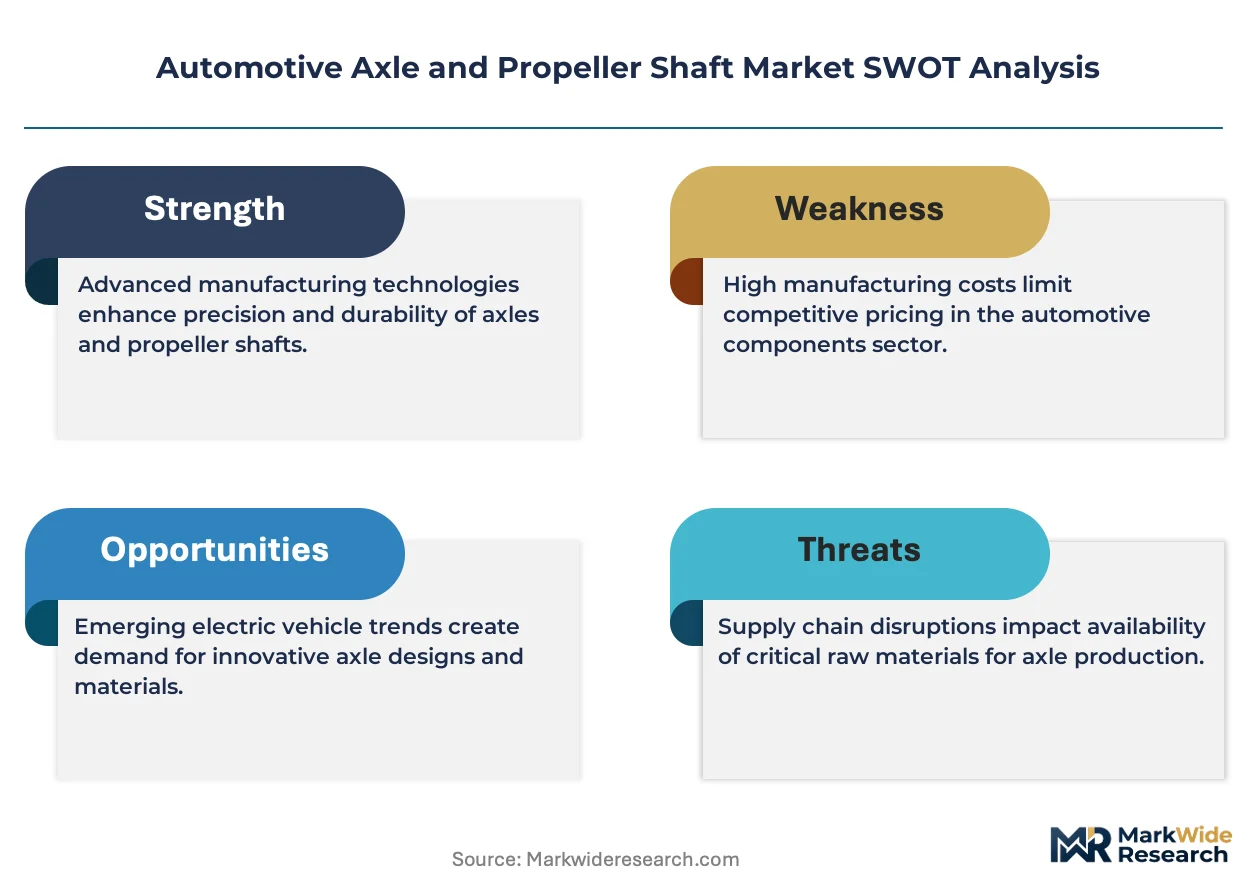
Regulations such as the EPA's fuel economy standards in the United States and China's dual carbon goals directly influence component design. These frameworks compel manufacturers to develop lighter and more efficient axle and propeller shaft systems to reduce overall vehicle emissions. Suppliers must now balance the high capital investment required for advanced composite materials against the persistent cost pressures from OEM procurement.
Market Dynamics
The central dynamic shaping the automotive axle and propeller shaft market is the regulatory mandate for improved fuel efficiency. This pressure compels a fundamental shift toward lightweight materials, directly influencing component design, cost structures, and supplier capabilities.
Growth Catalysts
- Commercial Vehicle Expansion:Demand from China's heavy-duty truck manufacturing sector provides significant volume, particularly for robust rear axle assemblies.
- Fuel Efficiency Mandates:Regulations like the EU Green Deal and EPA standards push OEMs to adopt lighter components, such as aluminum alloy axles, to meet emissions targets.
- Material Innovation:The development of cost-effective manufacturing processes for carbon fiber shafts creates new performance tiers for specialized vehicle applications.
Market Restraints
- High Capital Investment:The transition to composite material manufacturing requires substantial upfront investment in new tooling, machinery, and production lines, deterring some suppliers.
- Input Cost Volatility:Fluctuations in the price of raw materials like high-grade steel, aluminum, and carbon fiber precursors create margin pressure for component manufacturers.
- Performance Trade-offs:While lightweight, some alternative materials may not match the durability or torsional strength of traditional steel in extreme heavy-duty applications.
Strategic Opportunities
- Electric Vehicle Powertrains:The design of integrated e-axles for electric vehicles presents a significant opportunity for suppliers to develop new, value-added driveline systems.
- Aftermarket Upgrades:A growing aftermarket for performance and lightweight propeller shafts allows for targeting vehicle enthusiasts and fleet operators seeking efficiency gains.
- Regional Fleet Modernization:Government-backed fleet renewal programs in countries like Brazil and India offer a pathway for introducing more efficient axle and shaft technologies.
Industry Challenges
- Supplier Certification Hurdles:Achieving and maintaining IATF 16949 certification is a complex and costly process, creating a significant barrier for smaller, regional manufacturers.
- Composite Manufacturing Skills Gap:A scarcity of technicians and engineers with expertise in carbon fiber composite design, fabrication, and repair limits scalable production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Axle and Propeller Shaft Market |
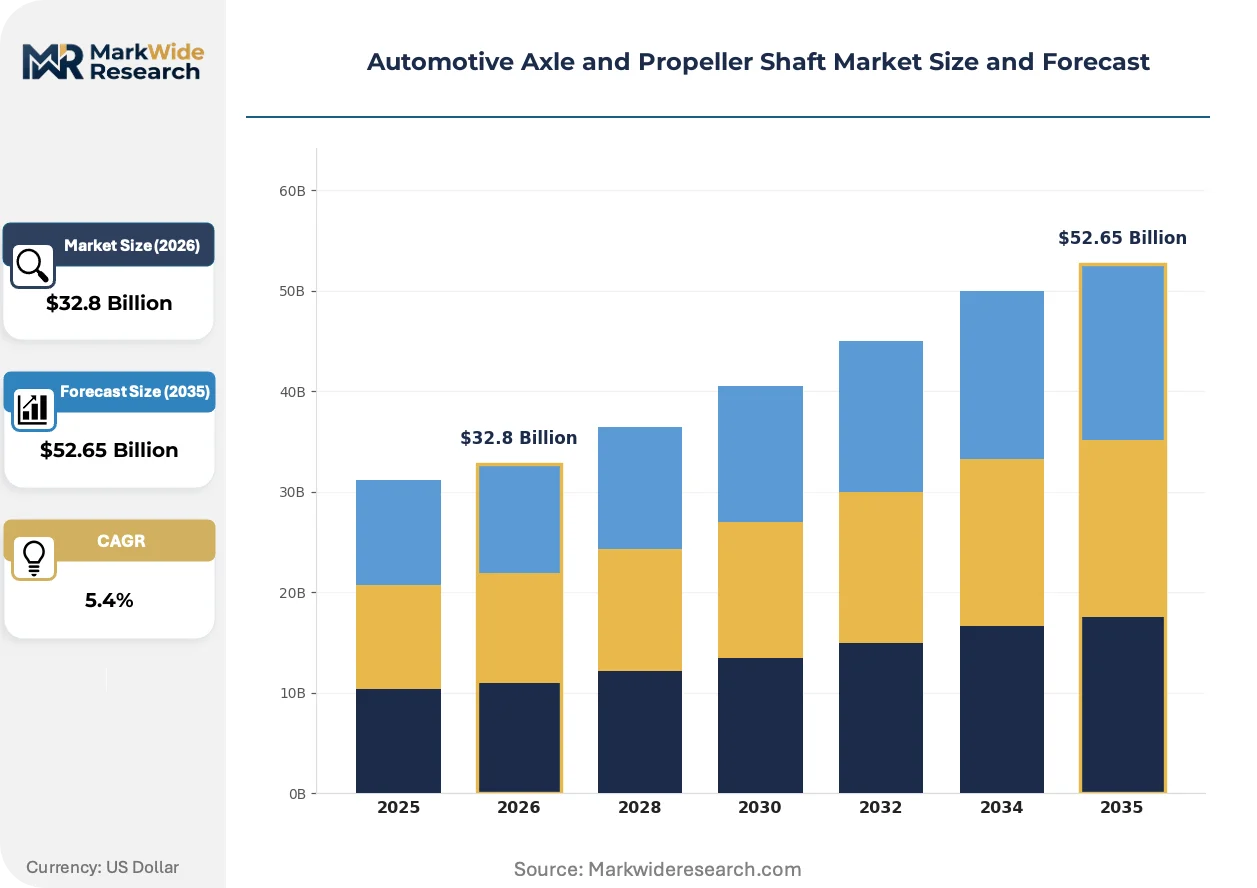
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Axle, Rear Axle, Propeller Shaft, Drive Shaft Material: Steel, Aluminum Alloy, Carbon Fiber, Composite Materials Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Construction Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | GKN PLC, JTEKT Corporation, Dana Holding Corporation, Gestamp Automocion S.A., Hyundai Wia Corporation, American Axle & Manufacturing Inc., Meritor Inc., Showa Corporation, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Axle and Propeller Shaft Market Strategic Shifts & Innovations
Material science advancements are fundamentally altering component capabilities and cost equations. This evolution is driven by a convergence of stringent environmental regulations and new demands from electric and high-performance vehicle architectures, redefining the standards for driveline efficiency.
Carbon fiber propeller shafts provide a superior strength-to-weight ratio compared to traditional steel. Adoption is accelerating in premium sports cars and specialized heavy-duty trucks where weight is critical for performance. This trend is bifurcating the market, creating a distinct segment for composites alongside the mainstream market for advanced steel and aluminum components.
China's national dual carbon goals impose strict emissions and fuel consumption limits on the automotive industry. This policy framework directly incentivizes vehicle mass reduction, particularly within the country's massive commercial vehicle fleet. Consequently, heavy-duty truck manufacturers are prioritizing the integration of lighter axle systems and propeller shafts to comply with these standards.
OEM sourcing strategies increasingly mandate IATF 16949 quality management certification for critical component suppliers. This certification-driven preference acts as a filter, consolidating the supply base by excluding non-certified manufacturers from new vehicle programs. The shift is most pronounced in North American and European markets where supply chain risk mitigation is paramount.
Automotive Axle and Propeller Shaft Market Segmentation
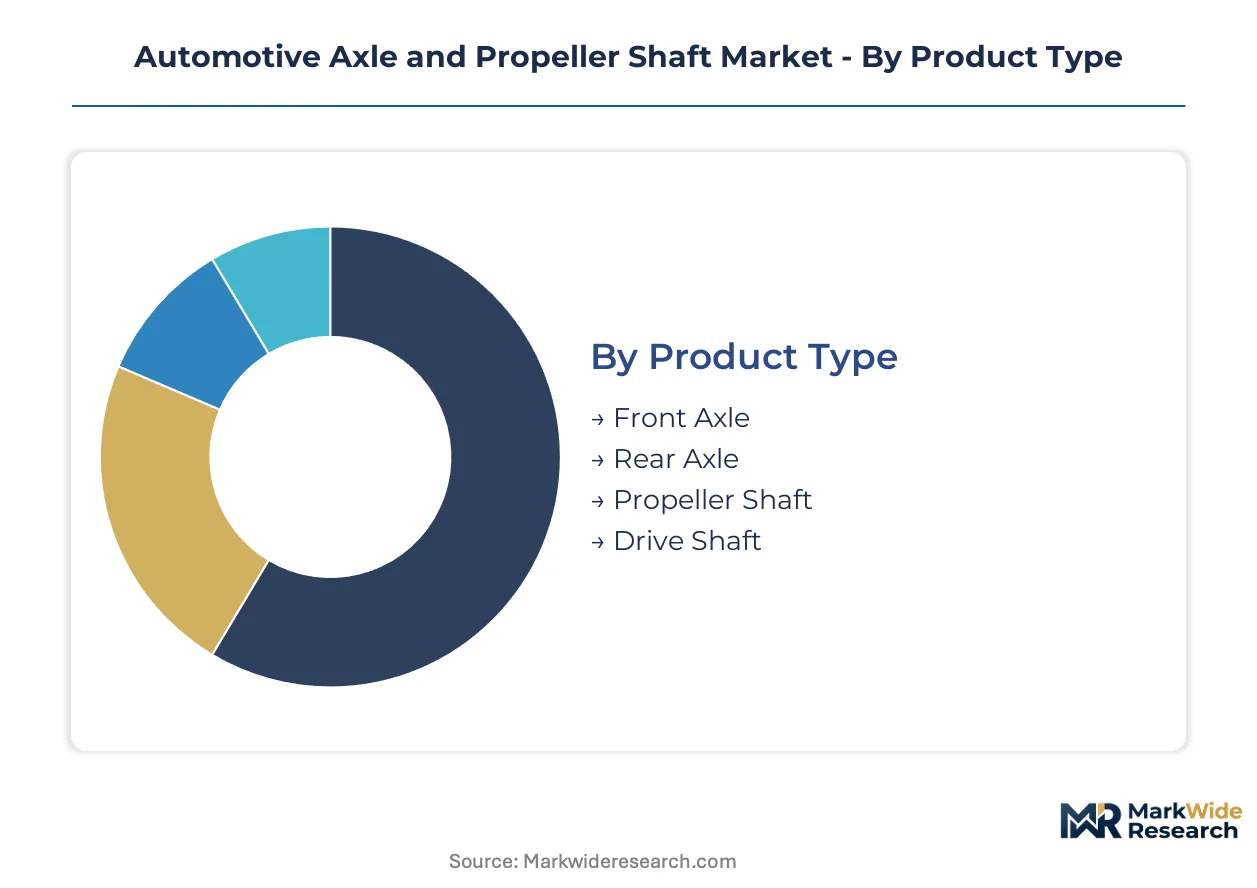
Understanding the segmentation of the automotive axle and propeller shaft market is critical for identifying specific demand drivers and technological shifts. This detailed breakdown highlights how different component types, materials, applications, and end-user segments contribute to the overall market dynamics, influencing strategic investment and product development.
Product Type:
The distribution channels for automotive axle and propeller shaft components differ significantly based on their functional role within a vehicle's driveline.
- Rear Axle:This structural component supports vehicle weight and transmits power to the driving wheels, predominantly used in commercial vehicles. Demand remains robust within China's heavy-duty truck manufacturing sector, driven by infrastructure development.
- Propeller Shaft:Designed to transmit torque and rotation, often fabricated from high-tensile steel or aluminum alloys to manage high rotational speeds. Adoption is accelerating in premium sports cars where weight reduction is critical for performance metrics.
- Front Axle:Primarily responsible for steering and supporting the front portion of the vehicle, integrating suspension and braking systems.
- Drive Shaft:A specific type of propeller shaft, typically connecting the transmission to the differential in front-engine, rear-wheel drive vehicles.
Rear Axle components dominate the installed base for commercial transport. Propeller Shaft technology is where performance and lightweight expansion concentrates.
Material:
Material selection for axle and propeller shaft components directly influences production cost and performance characteristics.
- Steel:This traditional material for axles and propeller shafts offers high strength, proven durability, and cost-effectiveness across various vehicle segments. Demand persists due to its reliable performance in demanding applications.
- Carbon Fiber:An advanced composite material providing a superior strength-to-weight ratio and enhanced torsional stiffness compared to traditional metals. Adoption is expanding in specialized heavy-duty trucks and performance vehicles, driven by stringent fuel efficiency mandates.
- Aluminum Alloy:Offers a significant weight reduction over steel, contributing to improved fuel economy and reduced emissions, particularly in passenger vehicles.
- Composite Materials:Encompasses a range of advanced materials beyond pure carbon fiber, offering tailored properties for specific strength, weight, and vibration damping requirements.
While Steel remains the foundational material for most applications, Carbon Fiber represents the fastest-growing trajectory for specialized, weight-sensitive designs.
Application:
The demand volume for automotive axles and propeller shafts varies substantially across different vehicle applications.
- Commercial Vehicles:This segment includes buses, vans, and medium-duty trucks, requiring robust axle systems and propeller shafts for heavy loads and continuous operation. Demand is particularly strong in emerging markets like India for government-backed fleet modernization programs.
- Heavy-Duty Trucks:These vehicles demand exceptionally durable and high-capacity axles and propeller shafts to withstand extreme operating conditions and payloads. China's dual carbon goals directly incentivize lighter component integration in this segment for emissions compliance.
- Passenger Vehicles:Encompasses a broad range from compact cars to luxury sedans, emphasizing efficiency, noise reduction, and ride comfort in driveline components.
- Construction Equipment:Requires highly robust and specialized axle and driveline systems designed for off-road conditions, heavy lifting, and extreme torque requirements.
The bulk of demand for these components arises from Commercial Vehicles. Heavy-Duty Trucks are showing dynamic shifts towards lighter component integration.
End User:
Procurement patterns for automotive axle and propeller shaft components are shaped by the distinct requirements of various end-user groups.
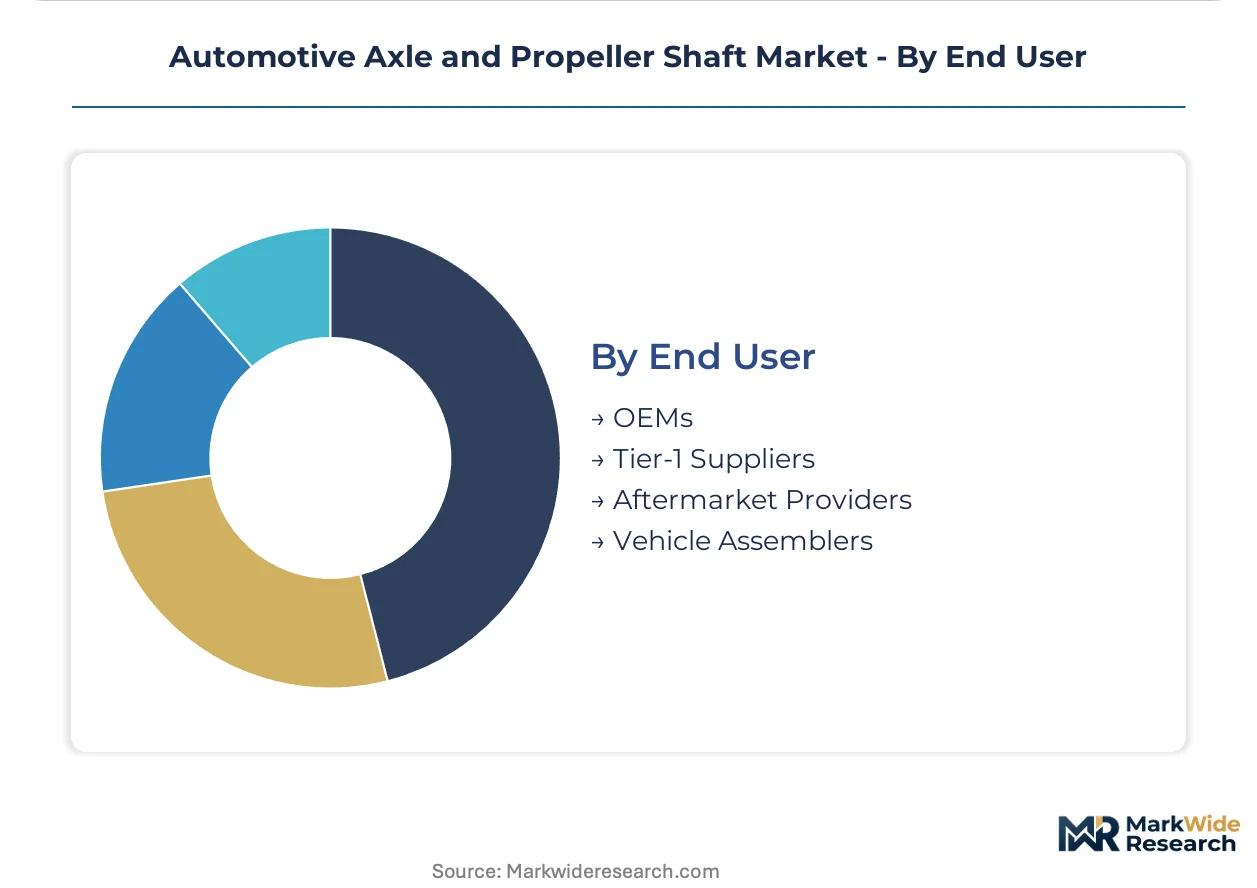
- OEMs:Original Equipment Manufacturers integrate axles and propeller shafts directly into their new vehicle production lines, requiring high volume and strict adherence to specifications. Sourcing strategies increasingly mandate IATF 16949 certification for critical component suppliers in North American and European markets.
- Aftermarket Providers:These entities supply replacement and upgrade components for vehicles already in service, catering to repair needs and performance enhancements. A growing segment targets fleet operators and performance enthusiasts seeking efficiency gains or enhanced durability through component upgrades.
- Tier-1 Suppliers:These companies often provide integrated driveline systems or major sub-assemblies to OEMs, managing complex supply chains and manufacturing processes.
- Vehicle Assemblers:Firms that assemble vehicles using components sourced from various suppliers, including axles and propeller shafts, often for niche markets or specialized conversions.
The established supply chain primarily serves OEMs for new vehicle builds. Aftermarket Providers offer opportunities for specialized repair and upgrade solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for automotive axles and propeller shafts centers on commercial vehicle manufacturers globally. These OEMs require robust, high-volume components to meet diverse transportation needs. The market's growth is particularly pronounced in heavy-duty truck segments across several key economies.
China
China's expansive commercial vehicle production ecosystem drives substantial demand for robust rear axle assemblies. China's dual carbon goals directly incentivize the integration of lighter components in its massive commercial vehicle fleet. Manufacturing hubs like the Yangtze River Delta are prioritizing advanced axle and propeller shaft systems to comply with these stringent standards.
United States
American Axle & Manufacturing Inc. specializes in driveline systems for light trucks and SUVs, reflecting a strong domestic market. The EPA's fuel economy standards compel manufacturers to develop lighter, more efficient axle and propeller shaft systems. Michigan's automotive corridor focuses on engineering and producing advanced components for these vehicle segments.
Germany
German automotive manufacturers require advanced axle and transmission technologies for both passenger and specialized heavy-duty vehicles. The EU Green Deal mandates push OEMs in Germany to adopt lighter components, such as aluminum alloy axles, to meet emissions targets. Bavaria's industrial clusters are a focal point for developing and integrating these innovative driveline solutions.
India
India's commercial vehicle segment, including buses and medium-duty trucks, requires robust axle systems for continuous operation. Government-backed fleet modernization programs in India offer a pathway for introducing more efficient axle and shaft technologies. Manufacturing centers in Maharashtra are scaling up production of durable and efficient components for these local fleets.
Automotive Axle and Propeller Shaft Market Key Industry Players
Player mix skews toward established, globally integrated manufacturers with diverse product portfolios. The market exhibits a tiered structure, separating certified suppliers from non-certified ones due to IATF 16949 requirements. Key strategic archetypes include full-system driveline specialists, material innovation pioneers, and regional component fabricators. Companies prioritize geographic expansion and portfolio diversification to capture new market opportunities.
Within the full-system driveline specialist archetype, Dana Holding Corporation leverages its extensive global manufacturing footprint, enabling it to serve original equipment manufacturers across multiple continents with integrated solutions. American Axle & Manufacturing Inc. occupies a specialized position, focusing its engineering and production capabilities on driveline systems primarily for light trucks and sport utility vehicles. ZF Friedrichshafen AG exemplifies a broader market approach, offering a comprehensive portfolio that includes advanced axle and transmission technologies, reflecting a diversified strategy in driveline solutions across various vehicle types and performance requirements.
| Leading Market Players |
|---|
| GKN PLC |
| JTEKT Corporation |
| Dana Holding Corporation |
| Gestamp Automocion S.A. |
| Hyundai Wia Corporation |
| American Axle & Manufacturing Inc. |
| Meritor Inc. |
| Showa Corporation |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
IATF 16949 certification gates supplier qualification and influences price differentiation within the automotive axle and propeller shaft market. This critical standard impacts supplier access to new OEM programs and the pricing power of certified manufacturers.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material prices like steel or aluminum, dominate OEM procurement. Price differentiation stems from IATF 16949 certification levels and the performance tier of materials such as carbon fiber. Pricing softness reflects persistent cost pressures from OEMs seeking to meet fuel efficiency mandates. Commercial vehicle operators in emerging markets exhibit the highest price sensitivity for standard steel components.
Supply Chain Analysis
Access to specialized carbon fiber precursors, primarily sourced from Japan and the United States, represents a manufacturing chokepoint for advanced propeller shafts. Geographic supply concentrates in China, Germany, and Japan for high-volume traditional axle components. The supply chain relies on consistent delivery of high-grade steel and aluminum alloys. Commodity price volatility presents a structural risk for component manufacturers. Distribution runs through a dual model: direct OEM supply and a growing aftermarket network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive axle and propeller shaft market is experiencing a buyer-power shift, driven by OEM consolidation and their stringent IATF 16949 certification mandates. This dynamic redefines supplier relationships and strategic imperatives across the value chain.
For Market Incumbents: Fortify core market share by investing in advanced material R&D for lightweighting solutions, especially for e-axle integration. Expand global manufacturing footprints to service OEMs in emerging markets, mitigating regional supply chain disruptions. Leverage IATF 16949 certification as a barrier to entry against non-certified competitors. Focus on cost-effective manufacturing processes to counter persistent OEM procurement pressure.
For New Entrants and Emerging Players: Lead with niche innovations in carbon fiber manufacturing for specialized heavy-duty truck applications. Target the aftermarket segment for performance upgrades, where efficiency gains command a premium. Develop cost-effective composite solutions for specific regional fleet modernization programs in India or Brazil. A go-to-market angle involves partnering with smaller, agile vehicle assemblers for custom driveline solutions.
For Investors and Strategic Acquirers: The EU Green Deal reshapes the acquisition landscape, prioritizing companies with proven lightweight material expertise and advanced e-axle technologies. Long-term viability hinges on suppliers capable of meeting stringent global emissions standards across the next decade. Target acquisition archetypes include specialized composite manufacturers or integrated driveline system providers with strong R&D pipelines. Watch for significant OEM partnerships with material science firms as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in E-Axle R&D | Develop integrated driveline systems crucial for electric vehicle powertrains. |
| Expand Carbon Fiber Production | Meet the growing demand for lightweight components in performance and commercial vehicles. |
| Secure Raw Material Offtakes | Mitigate input cost volatility for high-grade steel and aluminum alloys. |
| Achieve IATF 16949 Certification | Ensure qualification for critical OEM supply contracts in North American and European markets. |
| Target Aftermarket Performance Upgrades | Capture value from fleet operators and enthusiasts seeking efficiency and durability gains. |
Research Approach
Operator-level perspectives from OEM procurement managers, Tier-1 supplier R&D directors, aftermarket distributors, and heavy-duty fleet operators anchored the qualitative base. Primary interviews were combined with secondary validation from vehicle production databases, government regulatory filings, and material science journals. This approach facilitated bottom-up and top-down triangulation of market insights.
Sensitivity analysis informed the analytical framework, modeling market dynamics across the projection horizon. Segmentation dimensions modeled included product type, material, application, end-user, and regional production clusters. Compound annual growth rates were derived from historical trends and projected technological adoption curves. Key forecast inputs included vehicle production volumes and material cost trajectories.
Underlying assumptions cover stable regulatory enforcement and consistent raw material supply, with deviation risk concentrated in geopolitical trade policies and unforeseen technological breakthroughs. Practitioners should keep alternative scenarios live as material science advancements and global emissions targets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Nitrous Oxide System Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Apron Bus Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
Small Engine Market
Automotive Parts
China Automotive Parts Aluminum Die Casting Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automotive Roller Bearing Market