
 Global Automotive Gasoline Particulate Filter (GPF) Market | 2026-2036
Global Automotive Gasoline Particulate Filter (GPF) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Gasoline Particulate Filter (GPF) Market Intelligence
Substrate manufacturing capacity for ceramic and metallic filters is consolidating among a few specialized producers in Europe and Japan. This concentration of core material science expertise shapes the entire supply chain for after-treatment systems. Faurecia leverages its scale in exhaust systems to offer integrated solutions to major automakers. Corning Incorporated specializes in advanced ceramic substrates, which are critical for high-filtration efficiency.
An automotive gasoline particulate filter is an exhaust after-treatment device designed to capture fine particulate matter from gasoline direct injection engines. These filters typically use a wall-flow ceramic monolith structure with high porosity to trap soot particles. Demand from passenger vehicles dominates the market, driven by OEM installations to meet emissions targets. Within product types, catalyzed GPFs are gaining traction over non-catalyzed versions for their ability to simultaneously reduce gaseous pollutants.
Regulatory mandates are the primary market driver, with Europe's Euro 6d and China's 6b standards setting stringent particulate number limits. In the United States, EPA regulations on criteria pollutants indirectly encourage GPF adoption in specific vehicle platforms. The critical decision for suppliers and OEMs centers on optimizing filter material and design to minimize backpressure while maximizing particulate capture efficiency.
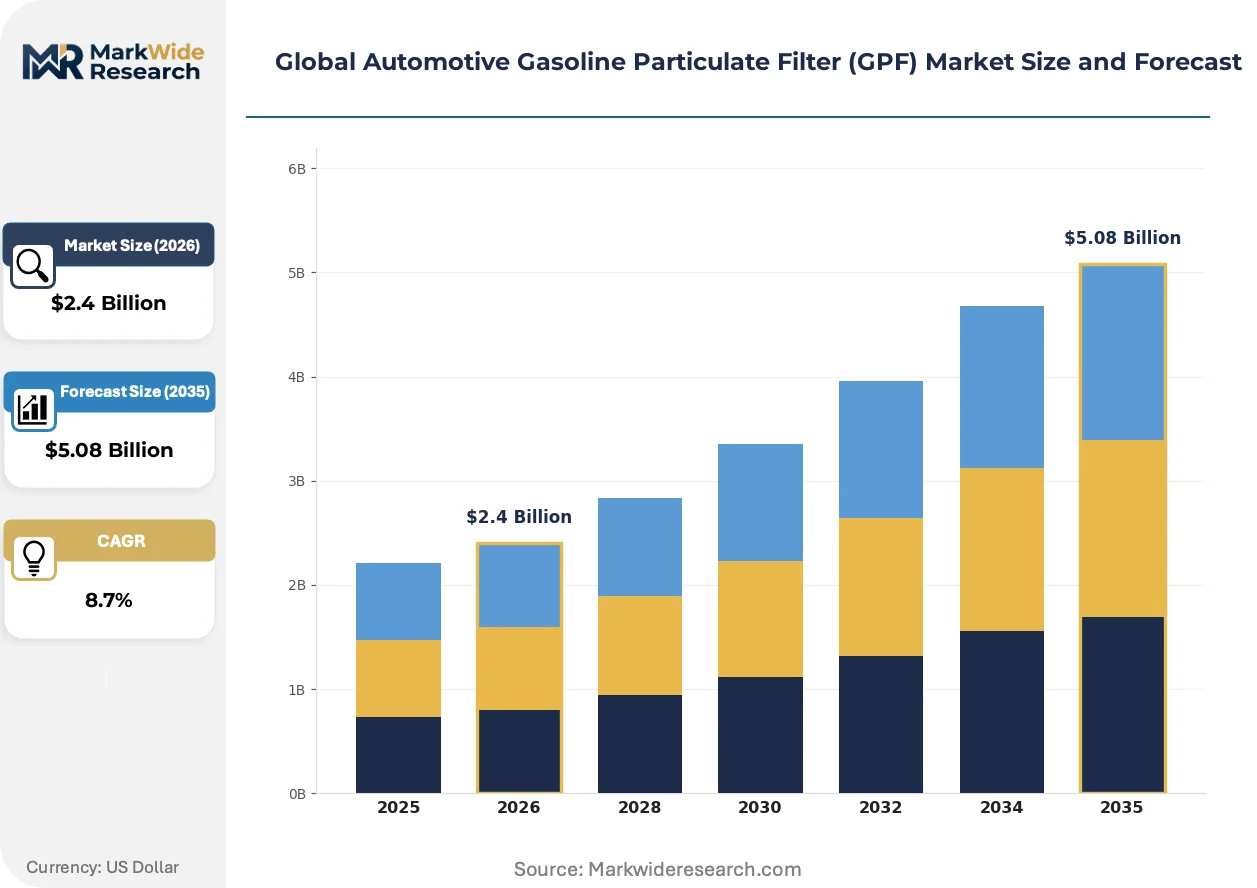
Market Dynamics
The market's structure is defined by non-negotiable regulatory pressure from governments in China and Europe. Emissions mandates like China's 6b and Europe's Euro 6d are the primary force compelling OEM adoption, making compliance a condition of market access.
Growth Catalysts
- Regulatory Mandates:China's 6b and Europe's Euro 6d standards impose strict particulate number limits, making GPFs essential for new GDI engines.
- GDI Engine Proliferation:The industry's shift to gasoline direct injection engines for fuel efficiency necessitates filters to manage their inherent particulate emissions.
- Aftermarket Development:A growing vehicle parc with factory-fit GPFs is creating demand for replacement filters in the independent service channel.
Market Restraints
- Substrate Supply Concentration:Manufacturing of core ceramic substrates is concentrated among a few suppliers in Europe and Japan, creating potential supply bottlenecks.
- Engine Performance Penalty:Filters introduce exhaust backpressure, which can negatively impact engine performance and fuel economy if not optimized in the design phase.
- Catalyst Cost Volatility:The use of platinum group metals in catalyzed GPFs exposes manufacturers to significant material cost fluctuations and supply risks.
Strategic Opportunities
- Emerging Market Regulations:Future emissions rules in large automotive markets like India and Brazil represent a major expansion opportunity as standards tighten.
- System Integration:Combining the GPF with the three-way catalyst into a single unit offers OEMs value through reduced system complexity and cost.
- Non-Road Applications:Applying GPF technology to gasoline-powered non-road machinery is an untapped segment as emissions rules for such equipment tighten.
Industry Challenges
- Vehicle Integration Complexity:OEMs face significant engineering challenges packaging GPFs into existing vehicle platforms without compromising performance, durability, or adding excessive cost.
- Accelerated Regulatory Timelines:The short timeframe between new emissions standards, such as the proposed Euro 7, severely pressures research, development, and validation cycles for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Gasoline Particulate Filter (GPF) Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Flow, Flow-Through, Catalyzed, Non-Catalyzed Technology: Diesel Particulate Filter, Gasoline Direct Injection, Lean Burn, Turbocharged Engines Application: Passenger Vehicles, Light Commercial Vehicles, Heavy-Duty Vehicles, Specialty Vehicles Customer Type: OEMs, Aftermarket Suppliers, Automotive Tier-1, Vehicle Assembly Plants |
| Companies Covered | Faurecia, Tenneco, NGK Insulators, Johnson Matthey, Bekaert, Corning Incorporated, Katcon, Continental, Denso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Gasoline Particulate Filter (GPF) Market Strategic Shifts & Innovations
Market development is focused on optimizing existing GPF technology for greater efficiency and integration rather than on disruptive new architectures. The primary effort is on refining materials and system design to meet successively stricter emissions rules at a manageable cost.
The catalyzed GPF (cGPF) combines particulate filtration with the reduction of gaseous pollutants in a single component. Automakers are adopting cGPFs for new GDI platforms to meet multiple emissions targets with one device. This development is consolidating the after-treatment system into fewer, more complex modules, favoring suppliers with integrated systems expertise.
Europe's proposed Euro 7 regulation introduces stricter limits on particulate numbers down to smaller sizes and under wider driving conditions. This forces a redesign of filter substrates and catalytic coatings for higher efficiency across the engine's operational map. Passenger vehicle OEMs are most affected, accelerating R&D in advanced ceramic materials.
A shift is occurring where automakers move from procuring standalone GPF components to sourcing fully integrated exhaust after-treatment systems. This model disrupts the traditional supply chain, favoring large Tier 1 integrators. This procurement evolution is most visible in high-volume car segments in China and Germany, where supply chain efficiency is critical.
Global Automotive Gasoline Particulate Filter (GPF) Market Segmentation
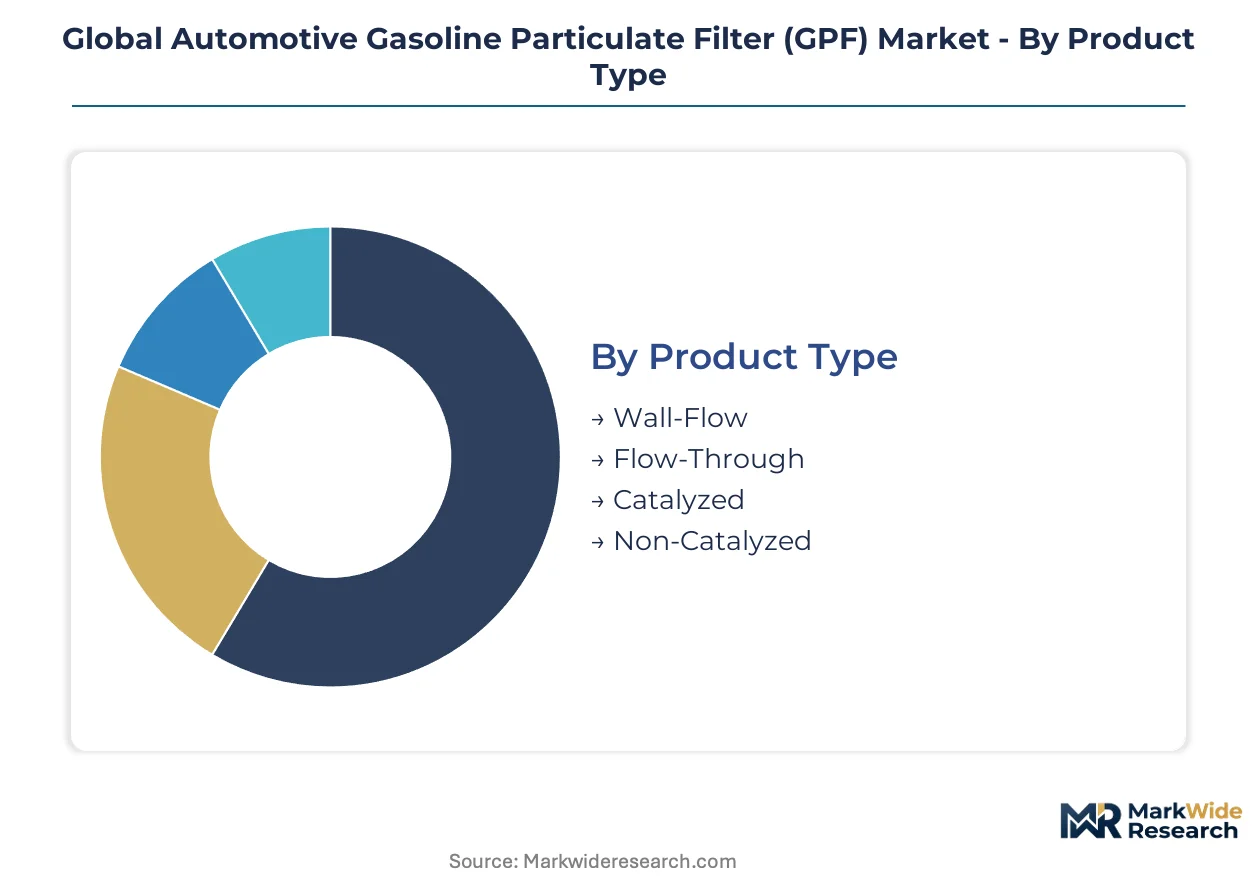
Segmentation provides a detailed lens into the Global Automotive Gasoline Particulate Filter (GPF) Market, revealing how diverse product types and applications respond to regulatory pressures. This breakdown helps identify areas of concentrated demand and technological evolution across the automotive industry.
Product Type:
The certification burden for automotive components heavily influences the development and deployment of different GPF product types. Each variant must demonstrate compliance with strict emissions standards before market entry.
- Catalyzed:This advanced GPF combines particulate filtration with the catalytic reduction of gaseous pollutants, offering a comprehensive after-treatment solution. Demand is concentrating in Europe for new GDI platforms, driven by Euro 6d standards requiring simultaneous pollutant reduction.
- Wall-Flow:Utilizing a ceramic monolith with alternating plugged channels, this design forces exhaust gas through porous walls to trap soot particles efficiently. Demand is strong in China for OEM installations, necessitated by China's 6b regulation for high particulate capture efficiency.
- Flow-Through:This filter design allows exhaust gases to pass directly through the structure, capturing particulates on internal surfaces with lower backpressure.
- Non-Catalyzed:Primarily focuses on trapping particulate matter, offering a simpler solution without additional chemical conversion of gaseous emissions.
Leading the category by volume: Wall-Flow. Growing fastest: Catalyzed.
Technology:
Different engine technologies dictate specific GPF designs to manage varying exhaust characteristics and particulate compositions effectively.
- Gasoline Direct Injection:These engines inject fuel directly into the combustion chamber, improving efficiency but inherently producing more fine particulate matter. Demand is concentrated globally in passenger vehicles, driven by the need to meet modern emissions standards like Euro 6d and China 6b.
- Turbocharged Engines:Utilizing an exhaust gas-driven turbine to increase engine power and efficiency, these engines are often found in combination with GDI systems. Demand is high in performance-oriented and downsized engines, where maintaining fuel economy while controlling emissions is critical.
- Diesel Particulate Filter:Specifically designed for diesel engines, this technology captures soot from diesel combustion processes.
- Lean Burn:Refers to engines operating with an excess of air, which can present challenges for traditional catalytic converters and may require specific after-treatment.
The integration of Gasoline Direct Injection technology is critical for GPF performance in modern passenger vehicles.
Application:
OEM volume dictates the scale of GPF integration across various vehicle application segments, influencing production capacities and supply chain logistics.
- Passenger Vehicles:Comprise cars and SUVs, representing the largest segment for GPF adoption due to widespread GDI engine use. Demand is primarily from new vehicle manufacturing in China and Germany, responding to stringent Euro 6d and China 6b emissions mandates.
- Light Commercial Vehicles:Include vans and small trucks, increasingly adopting GPFs as emissions regulations extend to this segment. Demand is growing in urban delivery fleets, where compliance with city-specific air quality zones is paramount.
- Heavy-Duty Vehicles:Encompass large trucks and buses, typically using diesel engines but may see GPF-like technologies for gasoline variants in niche applications.
- Specialty Vehicles:Covers a diverse range including recreational vehicles or industrial equipment, where emissions compliance is becoming more relevant.
This category highlights the differing requirements for emissions compliance across diverse vehicle types.
Customer Type:
The customer type significantly influences procurement patterns and supply chain relationships for GPF components and systems within the automotive industry.
- OEMs:Original Equipment Manufacturers integrate GPFs into newly produced vehicles to meet regulatory emissions targets. Demand is driven by new vehicle platforms requiring integrated after-treatment systems, particularly in high-volume markets like Europe and China.
- Automotive Tier-1:These suppliers develop and manufacture exhaust systems and components, including GPFs, for direct supply to OEMs. Demand from Tier-1s reflects their role in providing integrated solutions and managing sub-component sourcing.
- Aftermarket Suppliers:Provide replacement GPFs for vehicles already in operation, serving the independent service channel.
- Vehicle Assembly Plants:Represent the final stage of vehicle production where GPF systems are installed, often sourcing directly from Tier-1 suppliers.
Supply chain dynamics are heavily shaped by the interplay between these customer groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The manufacturing of core ceramic substrates, concentrated in Europe and Japan, influences the regional distribution of GPF demand. Demand is heavily concentrated in automotive manufacturing hubs where stringent emissions regulations are actively enforced. These areas drive both OEM installations and after-treatment system innovation.
China
China's automotive market represents a significant volume driver for GPF adoption, particularly in passenger vehicles. The nation's China 6b regulation mandates strict particulate number limits for new gasoline direct injection engines. Major automotive manufacturing clusters in the Yangtze River Delta and Pearl River Delta are rapidly integrating GPFs into new vehicle platforms.
Germany
Germany stands as a critical hub for GPF technology and demand within Europe. European Euro 6d standards necessitate GPF integration across a wide range of gasoline vehicles. Automotive engineering centers in Bavaria and Baden-Württemberg focus on optimizing filter design for performance and backpressure reduction.
Japan
Japan is a key player in the supply chain, particularly for advanced ceramic substrate manufacturing. While its domestic emissions standards are robust, Japanese suppliers like NGK Insulators are foundational to global GPF production. Research and development in materials science in cities like Nagoya and Tokyo continue to advance filter efficiency.
United States
The United States market sees GPF adoption influenced by EPA regulations on criteria pollutants, indirectly encouraging their use in specific vehicle platforms. Manufacturers are increasingly incorporating GPFs into GDI engines to align with global platforms and future-proof against tightening state-level emissions. Automotive production facilities in Michigan and the Southeast are adapting assembly lines for these systems.
India
India represents a future expansion opportunity as its emissions standards are projected to tighten significantly. Current Bharat Stage (BS) VI norms align with Euro 6, but future regulations will likely increase GPF penetration. Automotive manufacturing zones around Chennai and Pune are preparing for the eventual widespread adoption of these after-treatment devices.
Global Automotive Gasoline Particulate Filter (GPF) Market Key Industry Players
Global majors compete with regional champions across the automotive after-treatment systems market, creating a tiered competitive structure. The market is moderately consolidated, with a few large Tier 1 suppliers dominating integrated solutions. Strategic archetypes include specialized material science providers and large exhaust system integrators. Capacity expansion and system integration partnerships are dominant competitive moves.
Specialists in integrated exhaust systems, such as Faurecia, exemplify the Tier 1 integrator archetype, offering comprehensive solutions to major automakers. Corning Incorporated, a global material science company, anchors the specialized substrate segment, providing critical ceramic components. NGK Insulators, a Japan-based firm, occupies a position as a leading manufacturer of both ceramic substrates and finished GPF units.
| Leading Market Players |
|---|
| Faurecia |
| Tenneco |
| NGK Insulators |
| Johnson Matthey |
| Bekaert |
| Corning Incorporated |
| Katcon |
| Continental |
| Denso |
| Others |
Cost & Logistics Intelligence
Large, publicly traded material science corporations and family-owned specialists dominate the core GPF substrate supply, influencing pricing power through concentrated manufacturing capacity. This concentration shapes the entire after-treatment system market, impacting OEM procurement strategies.
Pricing Analysis
Warranty and service bundling often influences the perceived value of GPF systems, particularly for OEMs seeking integrated solutions. The dominant pricing model involves contract-based long-term offtake agreements with automotive manufacturers. Price differentiation stems from filtration efficiency, certification level (e.g., Euro 6d compliance), and volume scale. Pricing softness reflects intense OEM cost-down targets, especially in high-volume segments. Aftermarket suppliers exhibit high price sensitivity, while OEMs prioritize performance and regulatory compliance.
Supply Chain Analysis
Reverse logistics for GPF units primarily involves end-of-life recycling rather than widespread refurbishment or remanufacturing. Geographic supply concentration for advanced ceramic substrates lies in Japan and Europe, while finished GPF assembly is prominent in China and Germany. The supply chain draws from critical raw materials like advanced ceramic compounds and platinum group metals (PGMs). Commodity price volatility for PGMs creates a significant structural supply chain risk. Distribution runs through direct supply channels from Tier-1 integrators to automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GPF market is increasingly a vertical-integration race, where players pursue upstream control over specialized substrate manufacturing. This strategy mitigates supply bottlenecks and enhances cost control for integrated after-treatment solutions.
For Market Incumbents:Deploy advanced materials R&D to maintain a technological edge in ceramic substrate efficiency. Incumbents must also expand localized production capacity in high-demand regions like China to mitigate geopolitical supply risks. This defends against emerging Tier-2 entrants offering lower-cost alternatives. Investment in next-generation Euro 7 compliant designs secures long-term OEM contracts.
For New Entrants and Emerging Players:Launch via strategic partnerships with smaller automotive OEMs or specialty vehicle manufacturers. New entrants can target the emerging aftermarket segment with cost-effective replacement units for older GPF-equipped vehicles. Focus on less regulated non-road applications also offers a penetrable segment. Offer modular, easily integrated solutions to reduce vehicle integration complexity for OEMs.
For Investors and Strategic Acquirers:Distressed-cycle entries favor specialized material science firms in Europe and Japan, particularly those with patented ceramic substrate technology. The long-term viability of GPF technology is assured by tightening global emissions regulations for gasoline engines. Investors should seek targets with strong intellectual property in catalyzed GPF development. Monitor regulatory updates like proposed Euro 7 for early signals of accelerated technology shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Material Innovation | Enhances filtration efficiency and reduces backpressure for next-generation GDI engines. |
| Integrated System Development | Offers OEMs combined GPF and catalyst solutions, simplifying vehicle assembly. |
| Global Manufacturing Footprint Expansion | Establishes local production in China and India, aligning with regional demand. |
| PGM Sourcing Optimization | Mitigates material cost volatility and ensures stable supply for catalyzed GPFs. |
| Aftermarket Product Line Extension | Captures replacement demand from a growing installed base of GPF-equipped vehicles. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with automotive OEM platform engineers, Tier-1 exhaust system procurement leads, and ceramic material R&D directors provided critical qualitative insights. This approach combined bottom-up market sizing with top-down validation. Secondary data sources included vehicle production databases and emissions standards reports.
Data-stream reconciliation integrated historical market trends with future projections across the analysis window. Segmentation dimensions modeled included product type (catalyzed, wall-flow), technology (GDI, turbocharged), application (passenger vehicles, LCVs), and customer type (OEMs, aftermarket). Compound annual growth rates were derived from a multi-factor regression model. Key forecast inputs included GDI engine penetration rates and regional emissions regulation timelines.
Geopolitical trade tensions, accelerated EV adoption, and platinum group metal price volatility are the dominant revision risks. Forecasts reflect assumptions regarding regulatory enforcement and technological development. Practitioners should monitor global automotive policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Powerglide Shifter Market
Automotive Parts
Friction Pads Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Europe Industrial Roller Chain Drive Market
Automotive Parts
Odometer Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
Europe Automotive Lubricants Market