
 Europe Passenger Vehicles Lubricants Market | 2026-2036
Europe Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Passenger Vehicles Lubricants Market Foresight
Electric vehicle-adjacent service segments is broadening the addressable base for thermal management fluids and specialty greases. Shell plc leverages its integrated refining network to secure feedstock flexibility across Northwestern Europe. TotalEnergies SE anchors its position through OEM co-development programs with French and German automakers. BP plc competes via its Castrol brand strength in premium synthetic engine oils at independent workshops.
Europe passenger vehicles lubricants comprise refined base oils blended with additive packages to reduce friction, dissipate heat, and prevent wear in powertrain and chassis systems, with viscosity grades typically spanning SAE 0W-16 through 15W-40 depending on operating temperature and engine architecture. These formulations serve the essential commercial purpose of extending component life and maintaining fuel efficiency across internal combustion, hybrid, and increasingly electrified drivelines. Engine oil retains the dominant value pool given high-volume consumption and OEM specification complexity, while synthetic oil technology captures expanding margin as drain intervals extend and turbocharged downsized engines multiply. Bio-based lubricants represent the fastest-growing technology category, though from a small base, as REACH compliance costs and carbon accounting pressure reshape formulation economics.
The EU F-Gas Regulation and REACH framework administered by ECHA constrain additive chemistries and base oil sourcing, forcing reformulation investments that favor larger blenders with regulatory affairs capacity. ACEA oil sequences and OEM-specific approvals create tiered market access barriers where certification lag disadvantages smaller competitors. Stakeholders must monitor how the EU AI Act and embedded diagnostics mandates reshape predictive maintenance models and lubricant procurement patterns in fleet channels.
Market Dynamics
EU Green Deal carbon-accounting mandates are compressing formulation economics across Europe's passenger vehicle lubricants sector, forcing blenders to requalify base oil streams and additive packages under stricter lifecycle assessment protocols.
Growth Catalysts
- Extended drain intervals:Connected vehicle diagnostics enable predictive oil-life monitoring, expanding service windows for fleet operators in Germany and France.
- REACH-compliant bio-based formulations:Vegetable-derived esters and renewable Group III base oils gain traction as carbon-intensity thresholds tighten under EU climate frameworks.
- Turbocharged downsized engines:OEM powertrain strategies multiply demand for high-temperature-stable synthetics meeting ACEA C5 and C6 sequences.
Market Restraints
- Group II/III base oil supply concentration:Northwest European refining capacity constraints limit feedstock flexibility for mid-tier blenders.
- ECHA registration costs:Novel additive chemistry approvals require six-figure toxicology dossiers that disadvantage smaller formulators.
- Electric vehicle fluid substitution:Battery thermal management fluids displace engine oil volumes in pure-electric powertrains.
Strategic Opportunities
- Poland and Czech Republic fleet modernization:Central European commercial vehicle renewal programs create first-mover positioning for synthetic service packages.
- EU AI Act predictive maintenance mandates:Embedded lubricant-condition sensors generate recurring data-service revenue streams.
- Hybrid-specific formulations:Stop-start duty cycles and electric-range thermal cycling demand dedicated viscosity-stability chemistries.
Industry Challenges
- OEM approval timeline compression:ACEA sequence updates and Volkswagen 508.00/509.00 specifications require 18-24 month validation cycles that strain R&D bandwidth.
- Additive supply chain reconfiguration:REACH Annex XIV substance restrictions force reformulation of zinc dialkyldithiophosphate packages without performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Passenger Vehicles Lubricants Market |
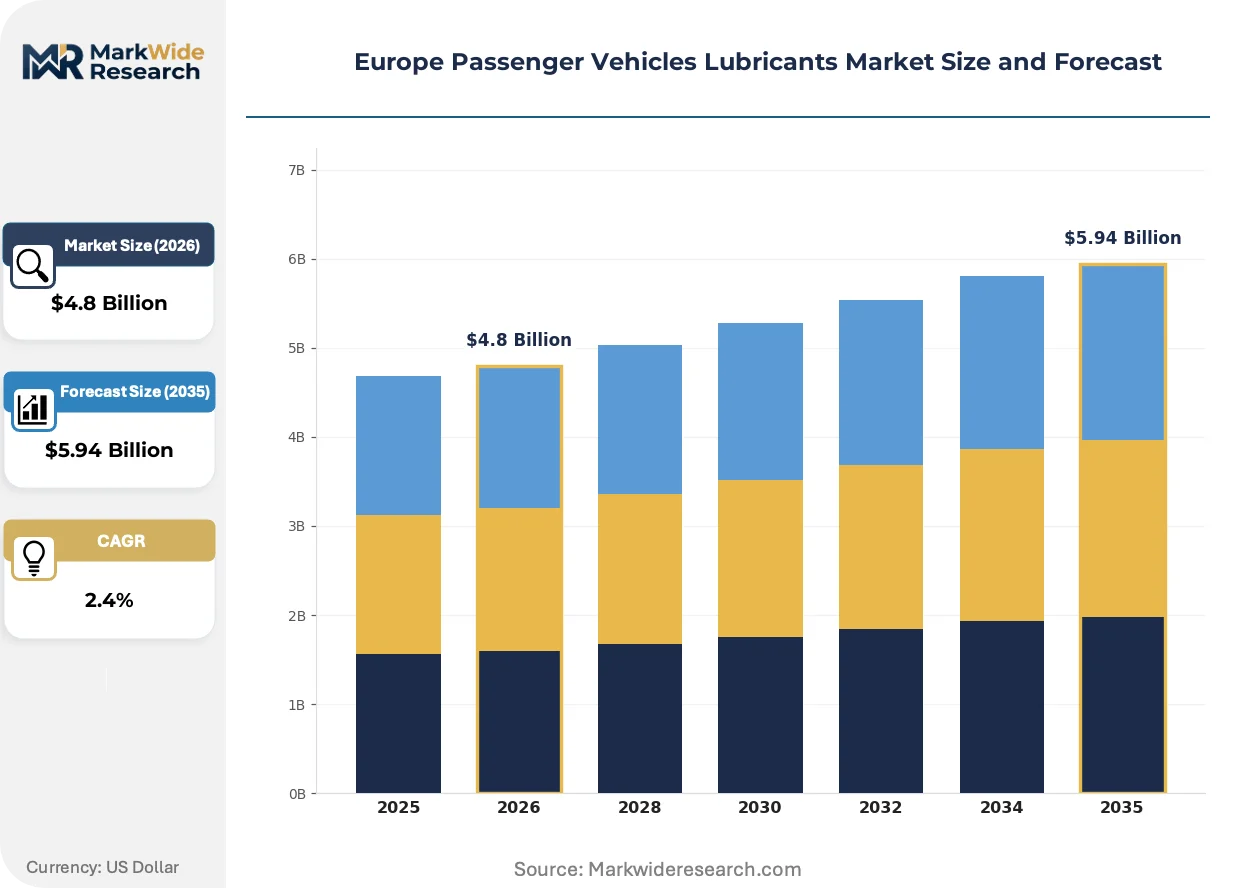
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $5.94 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Greases, Hydraulic Oil Technology: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-Based Lubricants Distribution Channel: Online Retail, Service Stations, Auto Parts Store, Direct Sales End User: Private Car Owners, Fleet Operators, Vehicle Manufacturers, Workshops |
| Companies Covered | Shell plc, BP plc, TotalEnergies SE, ExxonMobil Corporation, FUCHS SE, LUKOIL, Chevron Corporation, Valvoline Inc., Liqui Moly GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Passenger Vehicles Lubricants Market Shifts & Advancements
Formulation science is pivoting toward electrification-adjacent service categories while regulatory chemistry constraints intensify. Three developments are compressing competitive timelines across the value chain.
Smart thermal management fluids are integrating dielectric cooling and friction-modification properties into single formulations for hybrid and battery-electric architectures. German OEMs are qualifying these chemistries for combined inverter-transmission cooling circuits. This convergence is integrating lubricant suppliers into early-stage vehicle thermal system design.
The EU F-Gas Regulation and ECHA SVHC candidate list are restricting chlorinated paraffins and certain boron compounds in extreme-pressure additives. Blenders are reformulating with sulfur-phosphorus alternatives and ionic liquids. Premium synthetic engine oils face the steepest cost pass-through pressure.
Fleet procurement departments are consolidating lubricant contracts around total cost of ownership metrics rather than per-liter pricing. Leasing companies and mobility service providers in the United Kingdom are bundling fluid analysis and predictive replacement into service-level agreements. This recasts independent workshops as fulfillment nodes rather than decision-makers.
Europe Passenger Vehicles Lubricants Market Segmentation
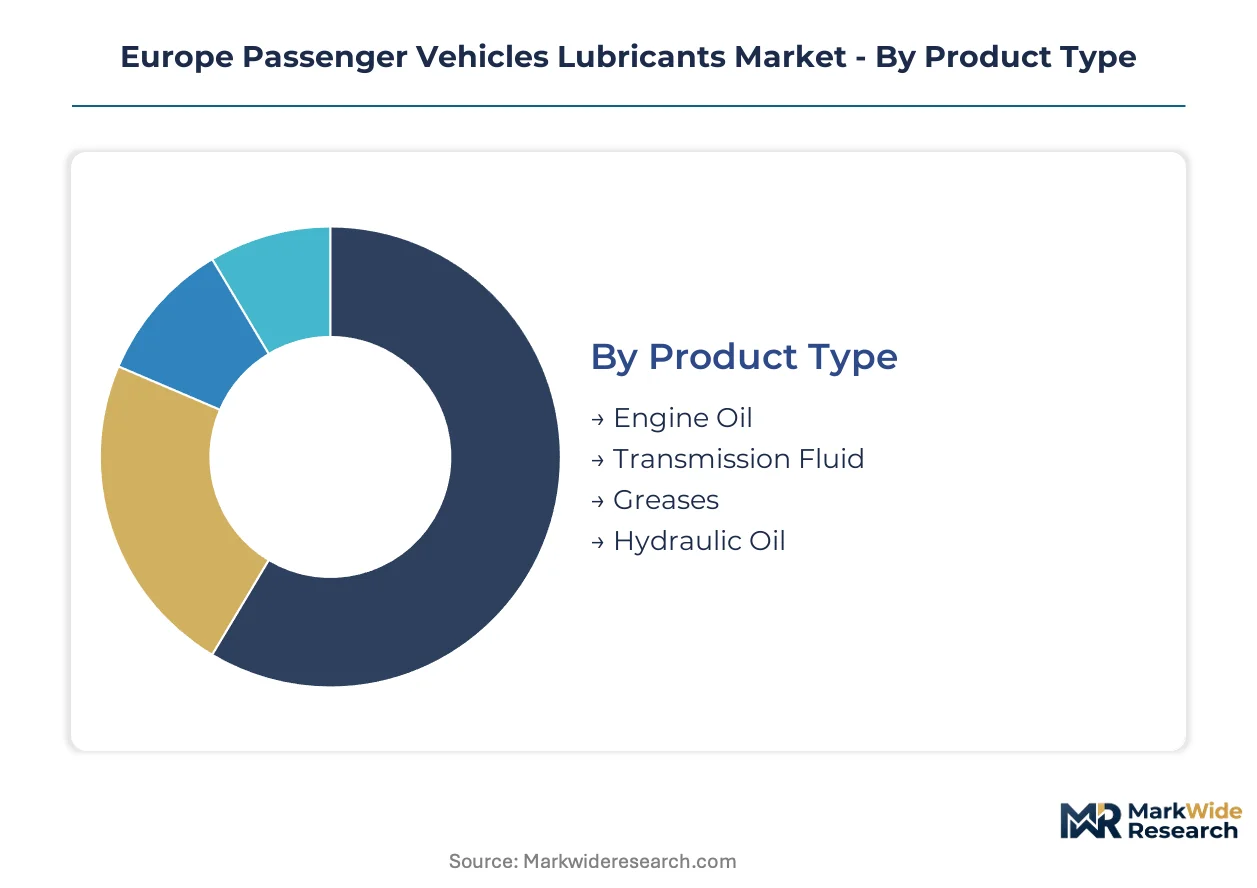
Segmentation in Europe's passenger vehicle lubricants market reveals how formulation chemistry, procurement channels, and end-user economics create distinct competitive battlegrounds. Each dimension carries different margin profiles and regulatory exposure across Germany, France, and the United Kingdom.
Product Type:
Buyers prioritize specification complexity and drain interval economics when selecting lubricant categories for their service programs.
- Engine Oil:High-performance base oils blended with detergent-dispersant and anti-wear additive packages meeting ACEA C3, C5, and C6 sequences. German OEM-affiliated workshops in Stuttgart and Munich drive premium synthetic volumes as turbocharged downsized architectures multiply.
- Transmission Fluid:Specialized formulations for dual-clutch, CVT, and electrified axle applications with friction-modification chemistries. Demand concentrates in French transmission plants supplying Renault and Stellantis assembly networks where fill-for-life specifications extend service revenue cycles.
- Greases:Lithium-complex and polyurea-thickened lubricants for chassis, wheel bearing, and electric motor bearing applications. UK independent workshops favor cartridge formats for brake caliper and suspension service.
- Hydraulic Oil:Anti-wear and synthetic ester formulations for power steering and active suspension systems. Central European fleet renewal programs in Poland generate replacement demand as hydraulic component complexity rises.
Engine oil leads on scale; transmission fluid leads on momentum.
Technology:
Carbon-intensity thresholds and REACH compliance costs reshape how blenders position their formulation tiers.
- Mineral Oil:Group I and II base stocks refined from solvent-extracted crudes with conventional additive treat rates. Price-sensitive private car owners in Southern Europe sustain residual demand despite specification obsolescence pressures.
- Synthetic Oil:Group III and PAO base oils delivering thermal-oxidative stability for extended drain intervals. German fleet operators specify synthetics exclusively as connected diagnostics validate oil-life algorithms.
- Semi-Synthetic Oil:Blends combining mineral and synthetic base stocks balancing performance uplift against formulation cost. French independent workshops push semi-synthetics as a compromise for older vehicle parc maintenance.
- Bio-Based Lubricants:Vegetable-derived esters and renewable hydrocarbons qualifying for EU Green Deal carbon-accounting preferences. REACH registration timelines and feedstock certification costs currently constrain volume expansion.
Synthetic oil dominates current revenue; bio-based lubricants gain share fastest.
Distribution Channel:
Procurement consolidation around total cost of ownership metrics restructures how lubricants reach end users.
- Online Retail:E-commerce platforms serving DIY enthusiasts and small independent garages with specification lookup tools. UK consumers show highest digital penetration for bulk engine oil purchases.
- Service Stations:Forecourt convenience formats capturing emergency top-up demand and impulse maintenance purchases. French motorway service areas maintain strong lubricant attachment rates.
- Auto Parts Store:Specialist retailers like Euro Car Parts and Feu Vert providing technical counter support and OEM-approved inventory. German counter staff certification requirements create service differentiation.
- Direct Sales:Blender-to-fleet contracts with embedded fluid analysis and predictive replacement scheduling. Leasing companies in the United Kingdom negotiate enterprise-wide supply agreements.
Direct sales commands margin; online retail climbs the fastest.
End User:
Service interval extension and electrification exposure vary sharply across customer categories.
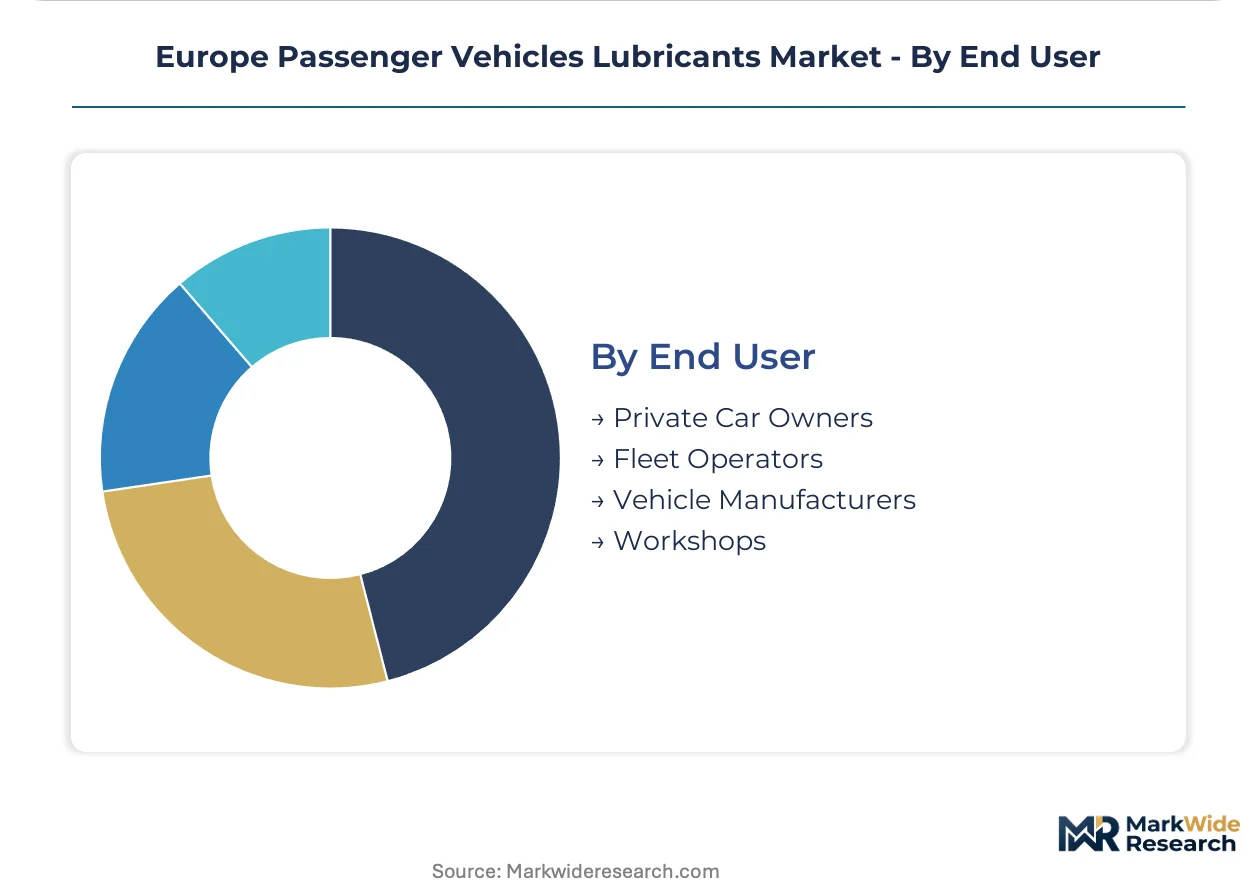
- Private Car Owners:Individual consumers selecting lubricants based on OEM handbook specifications and workshop recommendations. German owner compliance with manufacturer oil sequences remains highest in Europe.
- Fleet Operators:Commercial and corporate vehicle managers optimizing total fluid cost through bulk procurement and extended drain intervals. French utility fleets pilot predictive maintenance platforms.
- Vehicle Manufacturers:OEMs specifying factory-fill and service-fill lubricants through co-development programs with approved suppliers. German automakers enforce tight approval timelines for new ACEA sequences.
- Workshops:Independent and franchised service providers balancing inventory breadth against certification requirements. UK fast-fit chains consolidate supplier relationships to reduce complexity.
Fleet operators lead on volume concentration; vehicle manufacturers lead on specification control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor anchors European lubricant demand as Stuttgart and Munich workshops enforce premium synthetic specifications for turbocharged powertrains.
Germany
Fleet operators in Baden-Württemberg and Bavaria extend drain intervals using connected vehicle diagnostics validated by ACEA oil sequences. The KBA enforces strict OEM approval timelines that compress R&D cycles for new formulations. Stuttgart's OEM-affiliated workshops command premium synthetic volumes as Volkswagen 508.00/509.00 specifications multiply.
France
Renault and Stellantis transmission plants in Hauts-de-France drive fill-for-life fluid demand for dual-clutch and CVT applications. The EU Green Deal's carbon-accounting mandates accelerate bio-based ester formulations through ANSM regulatory pathways. Auvergne-Rhône-Alpes hosts TotalEnergies co-development programs with domestic automakers.
United Kingdom
Leasing companies and mobility providers consolidate procurement around total cost of ownership metrics rather than per-liter pricing. The UK's post-Brexit REACH alignment creates parallel registration requirements for additive chemistries. Midlands fast-fit chains reduce supplier complexity through enterprise-wide Castrol agreements.
Poland
Central European fleet renewal programs generate replacement demand for synthetic service packages as hydraulic component complexity rises. EU cohesion funding accelerates commercial vehicle modernization across Silesia and Greater Poland. Warsaw-based distributors capture spillover demand from German specification standards.
Czech Republic
Škoda Auto's Mladá Boleslav assembly network anchors OEM factory-fill specifications for ACEA C5 and C6 sequences. The country's automotive supplier density attracts blender direct-sales investments for embedded fluid analysis programs. Moravian fleet operators pilot predictive maintenance platforms linked to lubricant-condition sensors.
Europe Passenger Vehicles Lubricants Market Competitive Landscape
Strategic partnerships dominate the current landscape as blenders secure feedstock flexibility and OEM co-development access. The market structures around three tiers: integrated majors with refining networks, mid-scale specialists with regional formulation expertise, and niche players serving independent workshop channels. Two archetypes define competitive positioning: vertically integrated energy majors leveraging captive base oil supply, and additive-focused formulators competing on specification speed-to-market. M&A activity concentrates on Central European distribution assets, while technology licensing agreements accelerate bio-based qualification timelines.
Among integrated energy majors, Shell plc, BP plc, and TotalEnergies SE occupy positions defined by refining network scale and OEM relationship depth. Shell exemplifies the feedstock-flexibility archetype through its Northwestern European refining footprint. BP's Castrol brand sits within the premium synthetic tier serving independent workshop channels. TotalEnergies represents the co-development specialist model anchored in French and German automaker programs. These three majors illustrate how regulatory affairs capacity and certification lag management separate sustainable competitors from disadvantaged smaller blenders facing ECHA registration cost barriers.
| Leading Market Players |
|---|
| Shell plc |
| BP plc |
| TotalEnergies SE |
| ExxonMobil Corporation |
| FUCHS SE |
| LUKOIL |
| Chevron Corporation |
| Valvoline Inc. |
| Liqui Moly GmbH |
| Others |
Supply & Pricing Matrix
Fleet procurement consolidation around total cost of ownership metrics is compressing per-liter margins and forcing blenders to restructure formulation economics around predictive service bundling. This buyer-driven shift recasts independent workshops as fulfillment nodes while elevating direct-contract pricing power for integrated majors with embedded fluid analysis capabilities.
Pricing Analysis
Base oil and additive cost pass-through dominates pricing architecture across the European market. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels segments buyers by specification complexity and drain interval requirements. ACEA C5/C6 certification premiums face compression as REACH-compliant bio-based alternatives gain carbon-accounting preference. Private car owners in Southern Europe exhibit highest price sensitivity, while German fleet operators prioritize specification compliance over per-liter cost.
Supply Chain Analysis
EU Green Deal domestic-content preferences and REACH feedstock certification requirements are reshaping sourcing patterns toward verified renewable supply chains. Northwest European refining capacity in Germany, the Netherlands, and Belgium anchors Group II/III base oil supply. Additive packages draw from specialized chemical production in France and Germany. Single-source vulnerability concentrates around zinc dialkyldithiophosphate alternatives as ECHA SVHC restrictions force reformulation. Distribution runs through blender-owned bulk terminals serving direct fleet contracts and auto parts retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
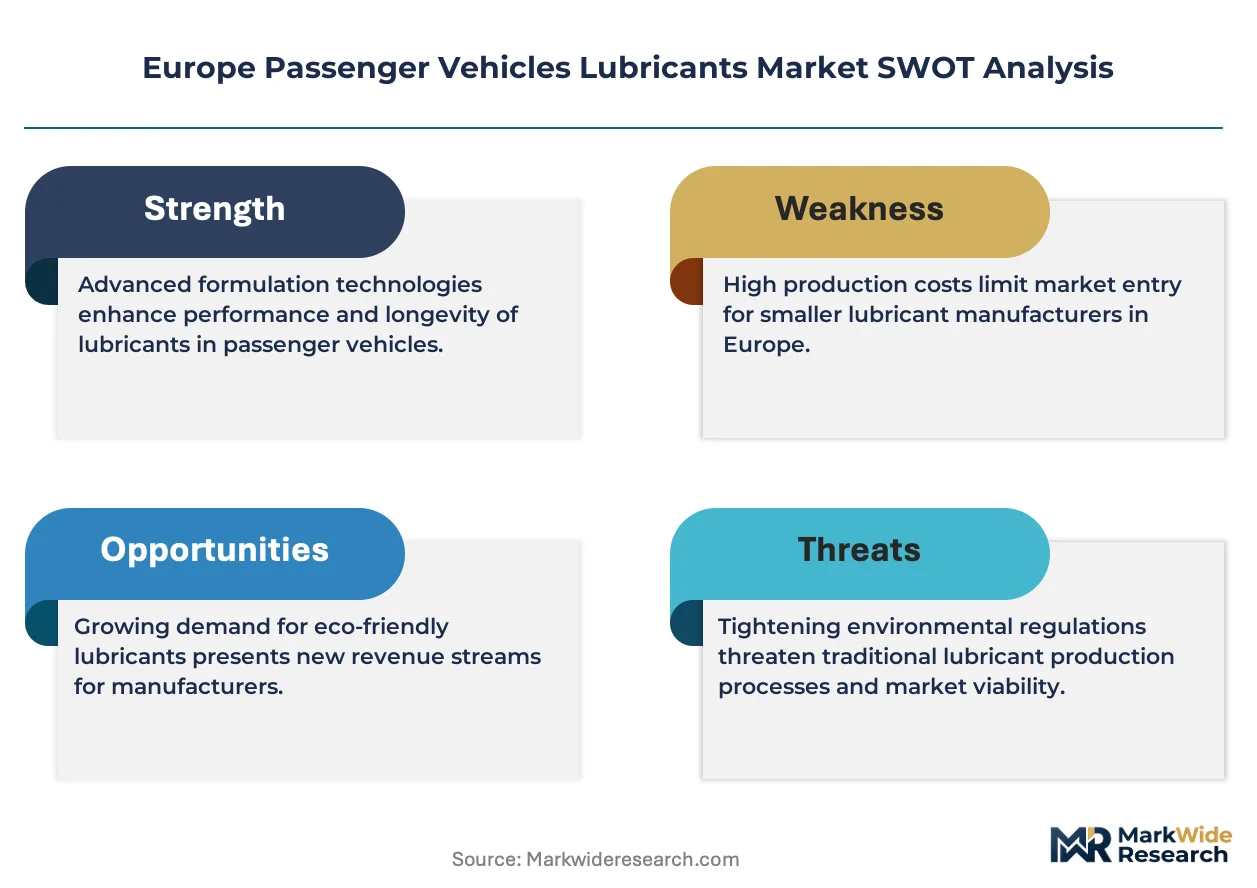
The European passenger vehicle lubricants market functions as a regulatory compounder where EU Green Deal carbon-intensity mandates and ECHA chemical restrictions continuously reshape formulation economics and competitive positioning.
For Market Incumbents: Deepen OEM co-development relationships to compress ACEA sequence approval timelines and defend against additive-focused formulators competing on specification speed-to-market. Prioritize backward integration into renewable base oil feedstocks to secure REACH-compliant supply chains before carbon-accounting thresholds tighten further. Expand embedded sensor deployment for predictive maintenance revenue streams. For New Entrants and Emerging Players: Polish and Czech fleet operators modernizing commercial vehicle parcs represent the most penetrable buyer archetype underserved by incumbent direct-sales infrastructure. Target synthetic service package contracts through fluid analysis bundling rather than commodity lubricant supply. Leverage bio-based formulation specialization to qualify for EU cohesion funding-linked procurement preferences. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale blenders possessing regional formulation expertise and established ECHA regulatory affairs capacity. Long-term viability hinges on electrification-adjacent thermal management fluid portfolios rather than pure engine oil exposure. Watch ACEA sequence update frequency as inflection indicator for R&D bandwidth requirements and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | Secures REACH-compliant base oil supply chains ahead of EU Green Deal carbon thresholds. |
| OEM Co-Development Program Expansion | Compresses Volkswagen 508.00/509.00 and ACEA C6 approval timelines against specification-speed competitors. |
| Predictive Maintenance Platform Deployment | Generates recurring data-service revenue from fleet operators extending drain intervals via connected diagnostics. |
| Central European Distribution Asset Acquisition | Captures Polish and Czech fleet modernization demand spilling over from German specification standards. |
| Bio-Based Formulation Certification Investment | Qualifies for EU Green Deal carbon-accounting preferences as ANSM pathways accelerate vegetable-derived ester adoption. |
Research Methodology
Coverage spans Germany, France, the United Kingdom, Poland, and the Czech Republic, with primary inputs from each market triangulated against secondary validation. Interviews with lubricant blending plant managers, OEM platform engineers, fleet procurement directors, aftermarket distribution partners, and ECHA regulatory affairs specialists combined with customs trade data, ACEA oil sequence documentation, SEC filings of integrated energy majors, and EU F-Gas Regulation implementation reports. Bottom-up volume modeling across product types and technologies reconciled with top-down market sizing.
Granularity extends to country-level formulation chemistry splits, OEM approval status by blender, and channel-specific procurement patterns across the projection horizon. Segmentation dimensions modeled include product type, base oil technology tier, distribution channel structure, and end-user category with propulsion architecture overlay. CAGRs derived from trend extrapolation of drain interval extension rates, electrification penetration curves, and regulatory compliance cost trajectories. Forecast inputs incorporate connected vehicle diagnostic adoption, REACH registration timelines, and bio-based feedstock certification velocity.
Underlying measurement precision varies by segment; synthetic oil and direct sales channels carry tighter precision than bio-based lubricants and online retail due to certification transparency and contract disclosure requirements. Forecasts reflect documented assumptions around EU Green Deal implementation pace and ECHA substance restriction timelines. Unanticipated regulatory acceleration or battery-electric vehicle penetration shifts could revise volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Fuel Injection Cleaning Machine Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
China Automotive Parts Aluminum Die Casting Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Large Volume Injector Market