
 Automotive Active Safety System Market | 2026-2036
Automotive Active Safety System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Safety System Market Intelligence
German automotive electronics manufacturing is consolidating around advanced driver-assistance platforms. Robert Bosch GmbH leverages its semiconductor subsidiary to secure captive supply of radar processing chips. Continental AG anchors European OEM relationships through integrated braking and sensor fusion architectures. ZF Friedrichshafen AG competes on mechatronic system scale across passenger and commercial vehicle programs.
Automotive active safety systems encompass sensor arrays, electronic control units, and actuation mechanisms that detect collision risks and autonomously intervene through braking, steering, or warning signals; radar units typically operate at 77 GHz with detection ranges exceeding 200 meters for highway-speed scenarios. Camera-based technology leads deployment volume due to lower unit costs and mature image-processing pipelines, while LiDAR segments command premium positioning in next-generation urban autonomy stacks. Passenger vehicles dominate end-user absorption, though fleet operators represent the fastest-growing adoption channel as telematics-linked safety mandates expand.
NHTSA in the United States and Euro NCAP in Europe enforce escalating crash-avoidance test protocols that de facto mandate automatic emergency braking on new vehicles. ECE R79 and UN R152 harmonize steering and braking intervention standards across EU member states and aligned markets. Stakeholders must monitor regulatory divergence between camera-centric and multi-sensor compliance pathways as type-approval frameworks evolve.
Market Dynamics
Regulatory mandates from NHTSA and Euro NCAP are compressing deployment timelines for automatic emergency braking and lane-keeping systems across all vehicle classes, forcing OEMs to redesign sensor architectures and procurement strategies simultaneously.
Growth Catalysts
- Euro NCAP 2026 Protocols:The expanded crash-avoidance test matrix mandates pedestrian and cyclist detection capabilities, compelling Tier-1 suppliers to accelerate radar-camera fusion development for European OEM platforms.
- Commercial Fleet Telematics:Insurance-linked safety mandates for long-haul trucking and last-mile delivery operators in the United States are driving bulk procurement of forward-collision warning systems with integrated driver monitoring.
- 77 GHz Radar Proliferation:Semiconductor process improvements at mature nodes are reducing bill-of-materials costs for mid-range detection modules, enabling mass-market vehicle segments to adopt highway-speed autonomous emergency braking.
Market Restraints
- LiDAR Cost Structure:Solid-state and mechanical LiDAR units remain priced at multiples of radar alternatives, constraining deployment to premium passenger vehicles and robotaxi fleets despite superior object classification fidelity.
- Semiconductor Concentration:Advanced radar processing chips and high-resolution image sensors depend on concentrated 28nm and 40nm foundry capacity in Taiwan and South Korea, exposing supply continuity to geopolitical friction.
- Sensor Calibration Complexity:Multi-sensor fusion architectures require precise factory calibration and recalibration after collision repair, increasing total cost of ownership and service network training burdens.
Strategic Opportunities
- India Safety Mandates:Bharat NCAP adoption and impending ABS-plus-airbag regulations for sub-4-meter vehicles create a greenfield market for cost-optimized camera-based active safety systems with localized software stacks.
- Construction and Mining Vehicles:Off-highway equipment operators in Australia and Canada are retrofitting proximity detection and automatic braking systems to comply with site-specific zero-harm policies and reduce insurance premiums.
- V2X Infrastructure Convergence:Cellular vehicle-to-everything roadside units in Germany and the United States are creating data fusion opportunities where infrastructure-supplied hazard warnings complement onboard sensor perception.
Industry Challenges
- Functional Safety Engineering Gap:ISO 26262 ASIL-D certification for braking and steering intervention systems requires specialized hardware and software competencies that outpace current university pipeline output.
- Homologation Timeline Compression:Divergent type-approval requirements between UN R152-aligned markets and NHTSA self-certification regimes force parallel validation tracks, stretching engineering resources and delaying platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Safety System Market |
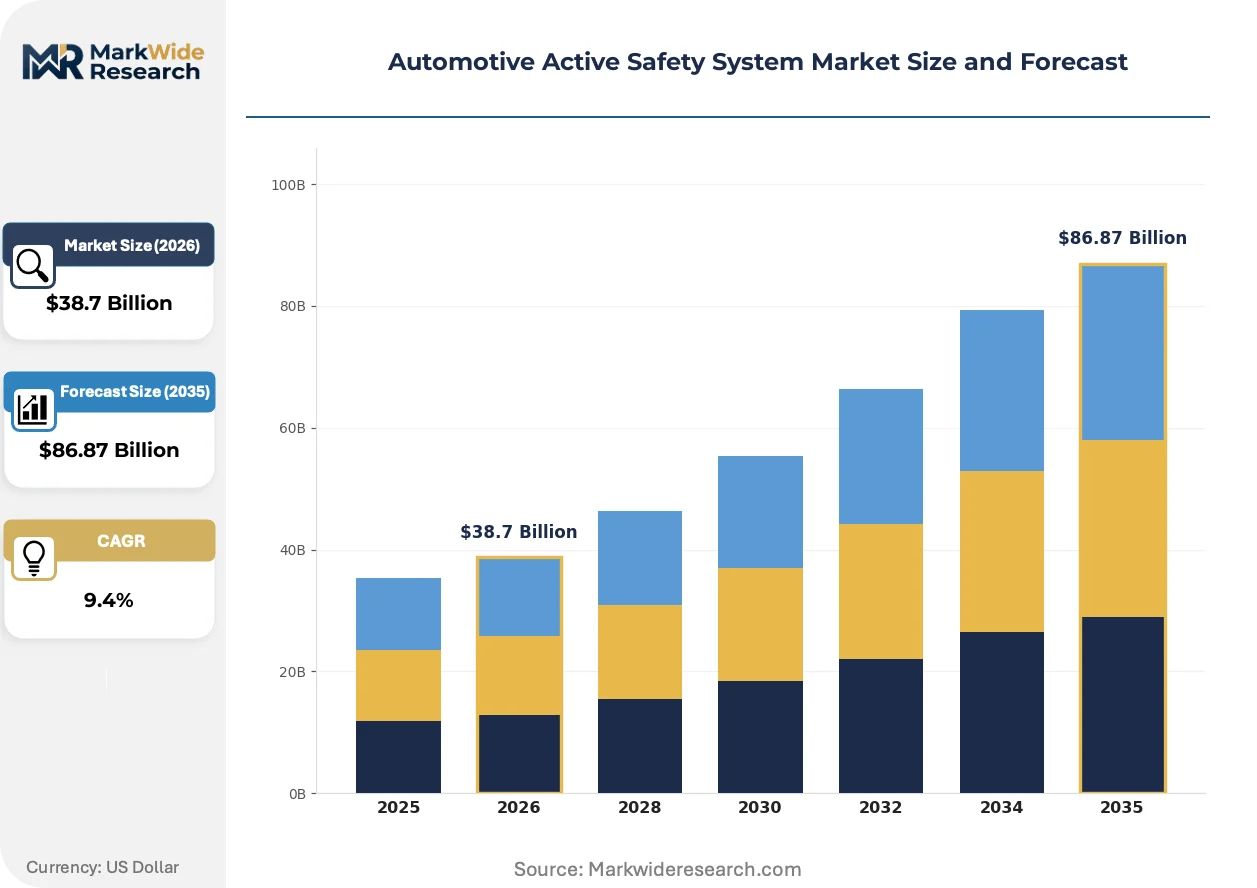
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Cruise Control, Collision Avoidance, Lane Departure Warning, Automatic Emergency Braking Technology: LiDAR, Radar, Camera-Based, Ultrasonic Sensors End User: Passenger Vehicles, Commercial Vehicles, Fleet Operators, OEMs Deployment: Onboard Systems, Cloud-Based Solutions, Integrated Platforms, Retrofit Solutions |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation, Magna International, Autoliv Inc., Valeo SA, Aptiv PLC, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Safety System Market Strategic Shifts & Innovations
Software-defined perception stacks are displacing fixed-function hardware architectures, enabling over-the-air capability expansion and accelerating the obsolescence of single-sensor dominance in safety-critical applications.
Occupant monitoring systems using near-infrared cameras and millimeter-wave radar are automating child presence detection and driver impairment assessment for regulatory compliance and liability reduction. Luxury and family vehicle segments in Germany and the United States are adopting these dual-modality interiors first. This convergence is automating the integration of biometric safety with traditional crash-avoidance domains, collapsing the historical separation between passive and active safety engineering teams.
UN R152 harmonization across EU member states and aligned markets is standardizing automatic emergency braking performance thresholds for passenger cars and light commercial vehicles. The regulation mandates specific speed ranges and pedestrian test scenarios that shape sensor selection and algorithm training data requirements. Chinese OEMs exporting to Europe are redesigning braking control modules to meet these intervention timing specifications, altering their supplier qualification criteria.
Fleet operators are consolidating safety system procurement through telematics platform providers rather than direct OEM channel relationships, bundling hardware, installation, and performance-based insurance discounts. This channel shift concentrates buying power among logistics technology aggregators in the United States and Germany. The transformation is most visible in refrigerated transport and hazardous materials hauling, where regulatory incident reporting requirements favor integrated data capture solutions.
Automotive Active Safety System Market Segmentation
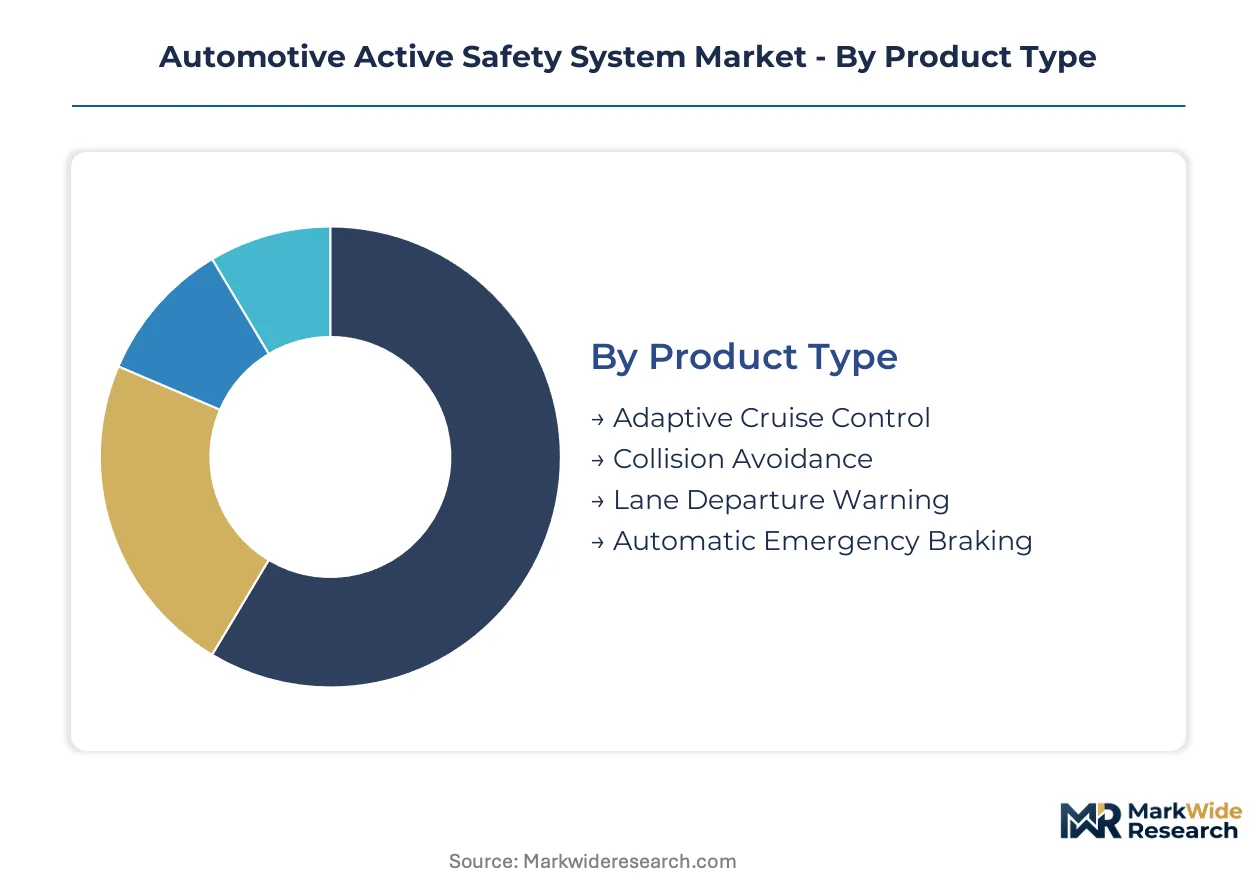
Active safety system segmentation reveals how sensor modalities, vehicle architectures, and procurement channels fragment engineering priorities and margin structures. Understanding these divisions exposes where standardization pressures collide with customization premiums across passenger and commercial vehicle programs.
Product Type:
Technology specification defines functional capability thresholds and regulatory compliance pathways for each intervention category.
- Adaptive Cruise Control:Radar-dominant systems modulate vehicle speed through longitudinal control algorithms with stop-and-go functionality for dense traffic. Highway-speed deployment in Germany and the United States concentrates procurement around 77 GHz modules with integrated braking actuation.
- Collision Avoidance:Multi-sensor fusion architectures combining radar returns with camera classification enable cross-traffic and blind-spot intervention. Euro NCAP 2026 protocols for cyclist detection are accelerating radar-camera integration in European OEM platforms.
- Lane Departure Warning:Camera-based edge detection monitors lane markings with haptic or audible driver alerts. Cost-optimized implementations dominate mass-market vehicle segments in China and India.
- Automatic Emergency Braking:UN R152-mandated intervention systems autonomously apply braking force when collision probability exceeds calibrated thresholds. Pedestrian detection requirements are expanding sensor suite complexity in export-oriented Chinese manufacturing.
Mature deployment sits with Lane Departure Warning. Newer deployment is concentrated in Automatic Emergency Braking.
Technology:
Cost tier and performance envelope stratify adoption across vehicle price bands and autonomy roadmaps.
- LiDAR:Solid-state and mechanical units generate dense point clouds for object classification at urban speeds. Robotaxi fleets in San Francisco and Phoenix absorb production volumes despite unit economics that exclude mass-market passenger vehicles.
- Radar:77 GHz frequency-modulated continuous-wave units penetrate weather conditions that disable optical sensors. Semiconductor process improvements at mature nodes are reducing bill-of-materials costs for highway-speed autonomous emergency braking deployment.
- Camera-Based:CMOS image sensors with dedicated neural processing units deliver lane recognition and traffic sign detection at the lowest per-unit cost. Image-processing pipeline maturity enables rapid feature expansion through over-the-air updates.
- Ultrasonic Sensors:Short-range acoustic detection supports parking assistance and low-speed maneuvering with minimal computational overhead. Proximity detection for construction equipment retrofitting in Australia leverages this technology's robustness to dust and vibration.
Volume concentration favors Camera-Based systems. Steepest expansion trajectory belongs to LiDAR as urban autonomy stacks commercialize.
End User:
Customer type determines procurement channel structure, warranty terms, and data ownership frameworks.
- Passenger Vehicles:OEM-integrated systems dominate with factory calibration and dealer service networks. NHTSA mandates are compressing deployment timelines across all vehicle classes.
- Commercial Vehicles:Long-haul trucking operators in the United States prioritize forward-collision warning with integrated driver monitoring for insurance-linked safety mandates.
- Fleet Operators:Telematics platform providers are consolidating procurement power through bundled hardware, installation, and performance-based insurance discounts in refrigerated transport segments.
- OEMs:Vehicle manufacturers specify sensor fusion architectures and qualify Tier-1 suppliers against Euro NCAP and NHTSA test protocols.
Procurement consolidation is shifting toward Fleet Operators. Engineering specification authority remains with OEMs.
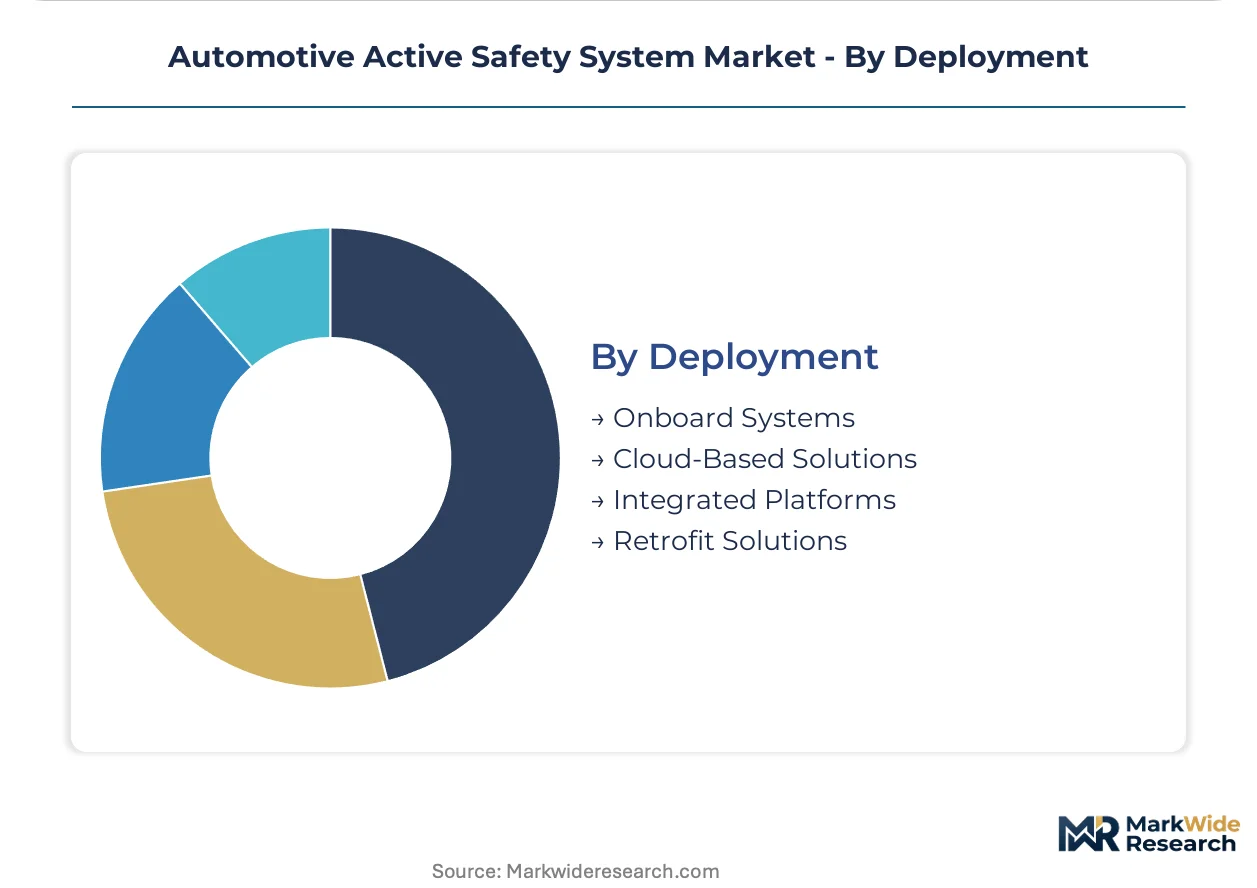
Deployment:
Integration depth shapes upgrade pathways and total cost of ownership across vehicle lifecycles.
- Onboard Systems:Edge-computing architectures process sensor data within vehicle-mounted electronic control units for sub-100-millisecond intervention latency. Functional safety certification to ISO 26262 ASIL-D dominates engineering resource allocation.
- Cloud-Based Solutions:Remote processing of aggregated fleet data enables predictive maintenance and map-based hazard warnings. German C-V2X roadside unit deployment creates infrastructure-supplied data fusion opportunities.
- Integrated Platforms:Unified braking, steering, and perception architectures from Continental AG and ZF Friedrichshafen AG reduce inter-supplier interface complexity. European OEM relationships anchor volume concentration.
- Retrofit Solutions:Aftermarket installation of collision warning systems serves commercial fleets and developing market vehicle parcs. Construction equipment operators in Canada deploy proximity detection retrofits for site-specific zero-harm compliance.
Factory-installed dominance characterizes Integrated Platforms. Aftermarket penetration is expanding fastest in Retrofit Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in Taiwan and South Korea anchor radar processing chip supply for active safety systems, while automotive assembly concentration in Germany, China, and the United States drives sensor module demand.
United States
NHTSA mandates for automatic emergency braking on all new light vehicles compress deployment timelines across Detroit Three and Tesla platforms. Insurance-linked safety mandates for long-haul trucking accelerate forward-collision warning procurement through telematics aggregators. Michigan's automotive corridor concentrates Tier-1 supplier engineering centers for sensor fusion development.
Germany
Euro NCAP 2026 protocols for pedestrian and cyclist detection reshape radar-camera integration specifications for BMW, Mercedes-Benz, and Volkswagen platforms. UN R152 harmonization standardizes braking intervention thresholds across EU type-approval frameworks. Stuttgart and Munich anchor Continental AG and Robert Bosch GmbH development centers for integrated braking architectures.
China
Domestic OEM export ambitions to Europe force redesign of braking control modules to meet UN R152 intervention timing specifications. MIIT regulations accelerate local sensor fusion platform development for BYD, NIO, and XPeng vehicle programs. Yangtze River Delta clusters concentrate LiDAR startup manufacturing for robotaxi fleet deployment.
Japan
Denso Corporation and Toyota Motor anchor domestic supply chain integration for 77 GHz radar modules across hybrid and battery-electric platforms. METI funding for autonomous driving validation facilities accelerates highway-speed automated system testing. Aichi Prefecture concentrates precision manufacturing for millimeter-wave antenna arrays.
India
Bharat NCAP adoption and impending ABS-plus-airbag regulations for sub-4-meter vehicles create procurement opportunities for cost-optimized camera-based systems. PLI scheme incentives for automotive electronics manufacturing attract sensor module assembly investment. Tamil Nadu and Gujarat host expanding electronics manufacturing clusters for localized software stack development.
Automotive Active Safety System Market Key Industry Players
Global majors compete with regional champions across semiconductor supply and system integration dimensions. The market exhibits tiered concentration with integrated braking suppliers, radar module specialists, and image sensor fabricators occupying distinct value chain positions. Three strategic archetypes dominate: diversified automotive electronics conglomerates, pure-play sensor technology vendors, and semiconductor foundries with automotive-qualified processes. Competitive moves center on captive chip supply arrangements and multi-sensor fusion platform consolidation.
Among diversified automotive electronics conglomerates, Robert Bosch GmbH, Continental AG, and ZF Friedrichshafen AG occupy positions spanning braking actuation, radar processing, and sensor fusion architecture supply. These Germany-based entities exemplify the integrated platform archetype through their control over mechatronic system design and OEM qualification pathways. Their scale across passenger and commercial vehicle programs anchors European market structure.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Magna International |
| Autoliv Inc. |
| Valeo SA |
| Aptiv PLC |
| Infineon Technologies AG |
| Others |
Cost & Logistics Intelligence
UN R152 intervention timing specifications gate qualified supply for European export markets, restricting premium-tier pricing access to Tier-1 suppliers with certified braking control architectures. OEMs in Germany and China absorb cost premiums for UN R152-compliant modules while mass-market segments in India and Southeast Asia face procurement constraints from limited certified supplier pools.
Pricing Analysis
Warranty and calibration service bundling separates factory-integrated platform pricing from aftermarket retrofit offerings, with European OEMs demanding multi-year service contracts for sensor fusion architectures. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification grade differentiation and volume scale commitments. Pricing pressure stems from semiconductor foundry capacity constraints at 28nm and 40nm nodes. Fleet operators exhibit highest price sensitivity due to telematics-aggregator procurement consolidation, while luxury passenger vehicle OEMs absorb premiums for integrated braking-steering platforms.
Supply Chain Analysis
77 GHz radar processing chip supply rests on Taiwanese and South Korean foundry capacity at mature semiconductor nodes. Silicon wafer fabrication draws from concentrated East Asian manufacturing clusters, while CMOS image sensor production centers on Japanese and South Korean fabricators. Single-source vulnerability exposure runs through Taiwan Strait geopolitical friction. Distribution runs through Tier-1 supplier direct OEM relationships and telematics platform provider channels for fleet segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive active safety system supply is constrained by ISO 26262 ASIL-D certification bottlenecks, with qualified engineering talent scarcity propping pricing for certified braking and steering intervention modules.
For Market Incumbents: To counter LiDAR cost erosion threatening radar-camera fusion margins, Tier-1 suppliers should deepen backward integration into 77 GHz semiconductor processing and secure captive radar chip supply through foundry partnership structures. Certification investment in Bharat NCAP-aligned software stacks for Indian market expansion provides additional defensive positioning. For New Entrants and Emerging Players: Telematics platform providers represent the most penetrable channel for aftermarket collision warning systems, particularly in refrigerated transport and hazardous materials hauling segments where insurance-linked mandates concentrate procurement. Construction equipment retrofitting in Australia and Canada offers white-space expansion for proximity detection specialists with dust-resistant ultrasonic sensor portfolios. For Investors and Strategic Acquirers: Chinese OEM braking control module redesigns for UN R152 compliance are the leading indicator that European export qualification capabilities will command acquisition premiums. Mid-cap sensor fusion specialists with certified European type-approval track records present viable targets. Watch for MIIT regulation acceleration signaling domestic Chinese platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Standardization | Continental AG and Robert Bosch GmbH reduce inter-supplier interface complexity for European OEM volume programs. |
| 77 GHz Radar Chip Supply Agreement | Captive semiconductor procurement insulates Tier-1 suppliers from Taiwan foundry concentration risk. |
| Software-Defined Perception Investment | Over-the-air capability expansion accelerates hardware obsolescence cycles and recurring revenue capture. |
| Indian Manufacturing Footprint Expansion | PLI scheme incentives attract sensor module assembly for cost-optimized camera-based system localization. |
| V2X Infrastructure Partnership | German C-V2X roadside unit deployment creates data fusion revenue streams complementing onboard perception. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automotive active safety system analysis. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet telematics operators combined with NHTSA rulemaking dockets, Euro NCAP test protocol documentation, and vehicle production databases. Bottom-up sensor shipment modeling and top-down OEM content-per-vehicle estimates provided triangulation validation.
Granularity-level modeling addressed vehicle class, propulsion architecture, sensor modality mix, and regional production cluster dimensions across the projection horizon. CAGRs derived from segment-specific adoption curves reflecting regulatory mandate phase-in schedules and OEM platform refresh cycles. Forecast inputs incorporated Euro NCAP 2026 protocol timing, Bharat NCAP implementation trajectory, and commercial fleet insurance mandate expansion patterns.
Caveats apply where semiconductor foundry capacity allocation shifts or geopolitical trade restrictions could materially shift the outlook. Forecasts reflect assumptions on regulatory harmonization between UN R152-aligned markets and NHTSA self-certification regimes. A small set of named triggers—Taiwan Strait supply disruption, Euro NCAP protocol acceleration, or Indian PLI scheme modification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market