
 Automotive Battery Pack Fire Barrier Pad Market | 2026-2036
Automotive Battery Pack Fire Barrier Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Pack Fire Barrier Pad Market Insights
China's Ningbo and Changzhou manufacturing corridors is reconfiguring supply geography for fire barrier substrates, pulling mica and aerogel conversion capacity toward cell producers. Aspen Aerogels leverages its pyrogenic silica expertise to anchor thermal runaway containment contracts with Korean battery makers. Morgan Advanced Materials sustains European OEM relationships through integrated mica mining and slitting operations in France and Germany. DuPont competes on aramid fiber formulations that meet both UL 94 V-0 and OEM-specific flame spread protocols.
An automotive battery pack fire barrier pad is a passive safety component engineered from ceramic fiber, aerogel, mica, or intumescent composites, typically rated for sustained exposure above 1,000 degrees Celsius to prevent thermal propagation between lithium-ion cells. Its primary purpose is to extend evacuation time by containing cell venting events within a single module rather than cascading across the full pack. Fiber-based pads occupy the volume tier due to established supply chains and compatibility with automated assembly, while composite sheets capture margin pools where OEMs specify multi-layer constructions combining thermal insulation with compression set resistance. Foam mats represent the fastest-growing substrate category as suppliers such as Zotefoams develop closed-cell polyimide grades that reduce pack mass against ceramic alternatives.
China's MIIT enforces GB 38031, which mandates five-minute no-fire propagation between cells, directly shaping pad thickness and material selection for vehicles sold domestically. The EU Battery Regulation, administered through ECHA and national type-approval bodies, requires disclosure of flame-retardant substance content, steering formulations away from halogenated chemistries toward mineral and ceramic alternatives. In the US, NHTSA's updated FMVSS 305 and NFPA 855 guidelines for battery energy storage systems are cross-pollinating automotive fire containment standards. Stakeholders must monitor how cell-to-chassis architectures eliminate traditional module housings, forcing barrier pad designs to integrate structural adhesion and dielectric isolation in single components.
Market Dynamics
Cell-to-pack architecture elimination of module housings forces fire barrier pads to absorb structural, thermal, and dielectric functions previously distributed across multiple components, compressing supplier margins while expanding technical specifications.
Growth Catalysts
- GB 38031 thermal propagation mandates:China's MIIT-enforced five-minute no-fire propagation standard requires thicker multi-layer pads, directly expanding material volume per vehicle.
- Solid-state battery commercialization:Higher energy density cells intensify thermal runaway severity, forcing OEMs to upgrade from fiber-based to aerogel-composite barriers.
- German automotive engineering corridor:Premium EV manufacturers in Stuttgart and Munich specify certified fire barrier assemblies, pulling substrate innovation toward European qualification protocols.
Market Restraints
- Pyrogenic silica supply concentration:Aerogel precursor manufacturing clusters in limited US and Chinese facilities, exposing buyers to input volatility and allocation risk.
- Halogenated chemistry substitution friction:EU ECHA disclosure requirements under the Battery Regulation force reformulation away from established flame-retardant supply chains.
- Ceramic fiber compression set limitations:Mineral wool substrates degrade under sustained mechanical load, restricting application in structural cell-to-chassis designs.
Strategic Opportunities
- Indian EV manufacturing scale-up:Domestic battery assembly under PLI scheme incentives creates demand for locally qualified fire barrier suppliers.
- Aramid-polyimide foam convergence:Hybrid constructions combining DuPont fiber technology with Zotefoams closed-cell grades enable mass reduction without thermal performance trade-offs.
- Second-life battery storage:Repurposed automotive packs for stationary energy storage require retrofitted fire containment, opening aftermarket pad retrofit demand.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled thermal-mechanical-electrical modeling for barrier pad design requires specialists rarely available outside aerospace and nuclear sectors.
- UL 2596 and OEM-specific protocol stacking:Battery enclosure certification timelines extend six to eighteen months as manufacturers sequence third-party and proprietary validation.
- Cell chemistry heterogeneity:LFP, NMC, and sodium-ion variants each propagate thermal runaway differently, forcing pad suppliers to maintain parallel qualification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Pack Fire Barrier Pad Market |
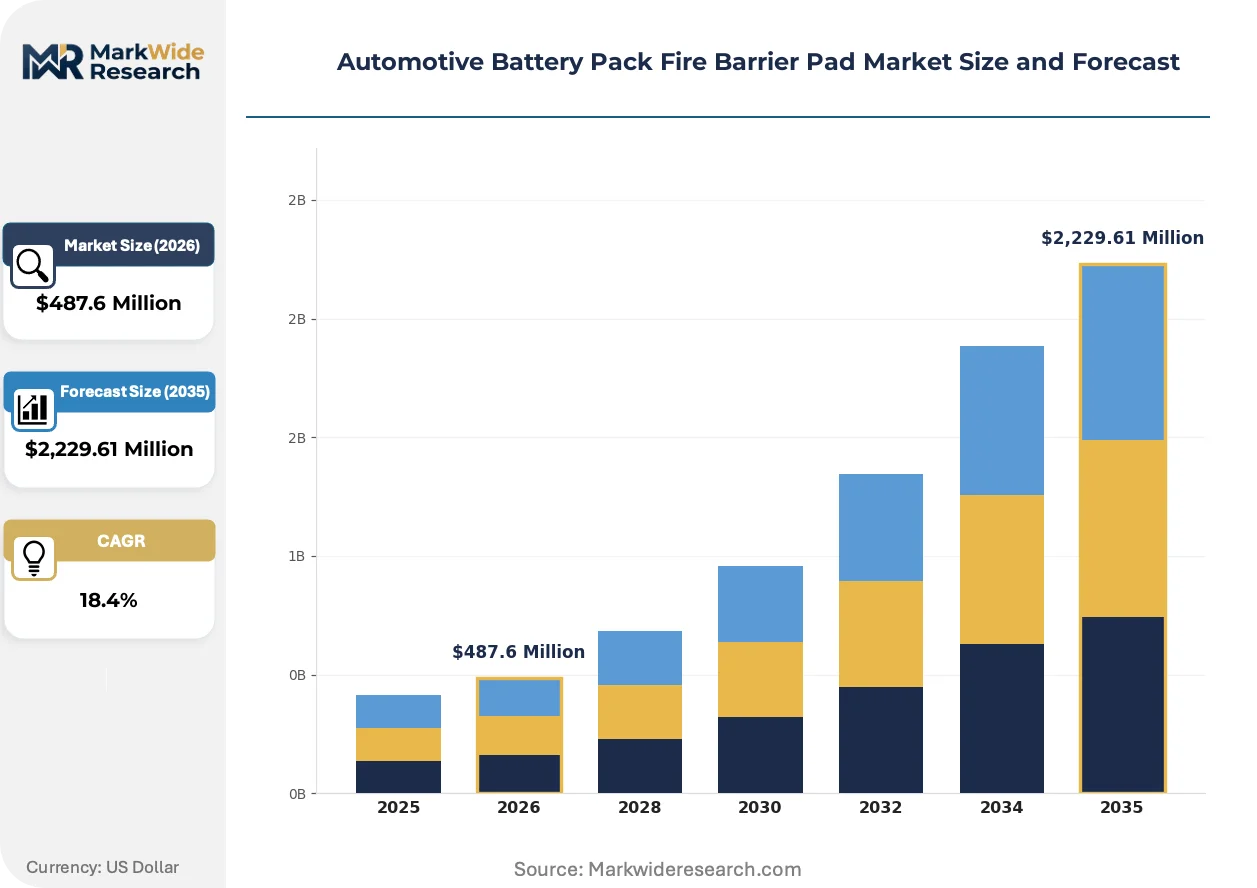
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber-Based Pads, Foam Mats, Composite Sheets, Ceramic Coatings, Graphene Layers Technology: Thermal Insulation, Fire Retardant Coating, Acoustic Damping, Shock Absorption, Chemical Resistance Application: Electric Vehicles, Hybrid Vehicles, Heavy-Duty Trucks, Two-Wheelers, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Fleet Operators |
| Companies Covered | 3M, Aspen Aerogels, Morgan Advanced Materials, Autoneum, Henkel, Zotefoams, Alkegen, DuPont, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Pack Fire Barrier Pad Market Trends and Innovations
Material science convergence with structural engineering is collapsing the traditional separation between thermal management and mechanical integrity in battery pack design.
Aerogel composite sheets are migrating from premium performance tiers toward volume EV platforms as Korean battery makers qualify pyrogenic silica formulations for 800-volt architectures. The technology compresses thickness requirements by forty percent against ceramic fiber equivalents while maintaining thousand-degree Celsius ratings, enabling pack energy density gains that cell chemistry alone cannot deliver.
ECHA administration of the EU Battery Regulation's flame-retardant disclosure mandate is redirecting formulation R&D toward mineral and ceramic alternatives. The industrial consequence is a supply chain pivot away from established halogenated chemistries toward mica and intumescent composites. German and French OEMs are most affected, pressing Morgan Advanced Materials and domestic suppliers to accelerate slitting and lamination capacity.
Buyer concentration among tier-one battery manufacturers is compressing supplier negotiation cycles from annual to quarterly frameworks. Direct OEM contracting is displacing module-house procurement for fire barrier specifications, most visible in South Korea where LG Energy Solution and Samsung SDI consolidate substrate qualification under single-vendor agreements.
Automotive Battery Pack Fire Barrier Pad Market Segmentation
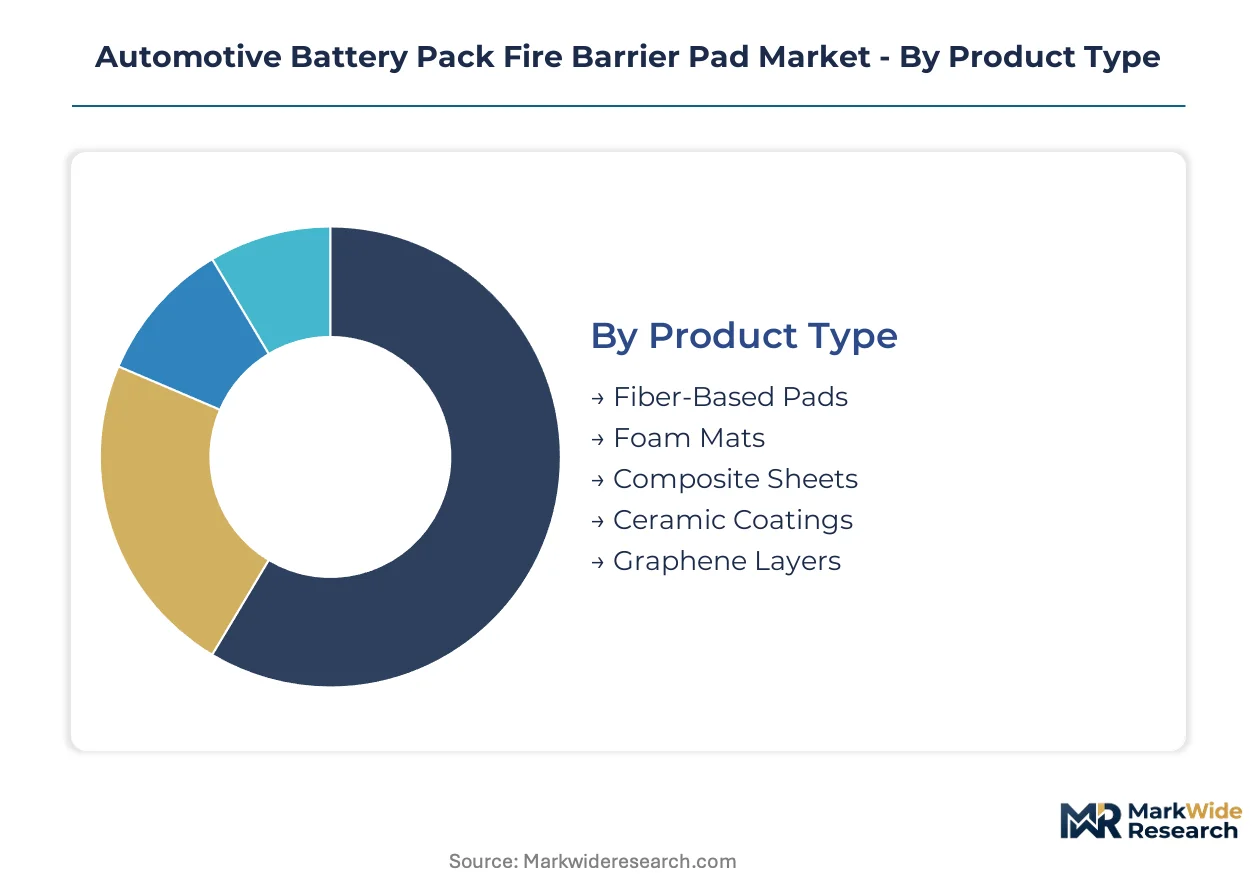
Fire barrier pad specifications diverge sharply across vehicle architectures and thermal management strategies. Cell-to-pack designs demand multi-functional substrates that combine insulation with structural load-bearing, while module-based systems tolerate simpler single-purpose materials. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
Mature fiber-based substrates anchor high-volume production, while emerging aerogel and graphene formulations capture technology-intensive applications demanding extreme thermal performance.
- Fiber-Based Pads:Woven ceramic or biosoluble mineral fiber constructions rated for sustained exposure above 1,000 degrees Celsius. German OEMs in Stuttgart specify these for mid-range EV platforms where automated slitting and lamination support high-throughput module assembly.
- Foam Mats:Closed-cell polyimide or melamine grades delivering mass reduction against ceramic alternatives. Korean battery makers at LG Energy Solution and Samsung SDI are qualifying these for 800-volt architectures where pack energy density gains justify premium substrate costs.
- Composite Sheets:Multi-layer laminates combining mica, aerogel, and intumescent chemistries for OEMs requiring UL 94 V-0 plus compression set resistance in single components.
- Ceramic Coatings:Spray-applied alumina-silica formulations for retrofit applications and second-life battery storage systems requiring field-applied fire containment.
- Graphene Layers:Emerging thermal interface materials leveraging anisotropic heat spreading to delay thermal runaway propagation in high-density cell configurations.
Fiber-based pads retain volume leadership; foam mats hold the steepest expansion curve.
Technology:
Cost tiers separate baseline thermal insulation from integrated multi-physics solutions commanding qualification premiums.
- Thermal Insulation:Core function across all substrate categories, measured by thermal conductivity and maximum service temperature. China's GB 38031 five-minute no-fire propagation mandate directly specifies minimum insulation performance thresholds.
- Fire Retardant Coating:Intumescent or ceramic surface treatments applied to base substrates. EU ECHA disclosure requirements under the Battery Regulation are forcing reformulation away from halogenated chemistries toward mineral alternatives.
- Acoustic Damping:Vibration absorption properties increasingly specified for luxury EV platforms where NVH performance differentiates brand positioning.
- Shock Absorption:Mechanical energy dissipation for cell-to-chassis architectures where barrier pads absorb crash loads previously handled by module housings.
- Chemical Resistance:Electrolyte containment and corrosion protection for packs using high-voltage cobalt-free chemistries.
Thermal insulation commands baseline procurement volume; fire retardant coating faces the most acute regulatory-driven substitution pressure.
Application:
Customer type stratification separates fleet-scale standardization from bespoke engineering for premium automotive platforms.
- Electric Vehicles:Battery electric passenger cars and light trucks representing the dominant demand sink. Cell-to-pack migration across Chinese, Korean, and German OEM lineages is forcing substrate suppliers to absorb structural and dielectric functions.
- Hybrid Vehicles:PHEV architectures with smaller battery packs but comparable thermal propagation risks. Japanese OEMs maintain distinct qualification protocols prioritizing space-constrained packaging.
- Heavy-Duty Trucks:Commercial vehicle packs with extended duty cycles and severe thermal cycling profiles. NHTSA FMVSS 305 cross-pollination with NFPA 855 stationary storage standards is elevating fire containment specifications.
- Two-Wheelers:Cost-optimized fiber pads for electric scooters and motorcycles where pack volume constraints limit substrate thickness.
- Specialty Vehicles:Mining equipment, agricultural machinery, and defense applications requiring customized thermal management solutions.
Electric vehicles retain volume leadership; heavy-duty trucks hold the steepest expansion curve.
End User:
Supply concentration dynamics concentrate negotiation leverage among tier-one battery manufacturers while fragmenting aftermarket procurement.
- OEMs:Direct contracting for fire barrier specifications is displacing module-house procurement, most visible at premium German and Korean manufacturers consolidating substrate qualification under single-vendor agreements.
- Tier-1 Suppliers:Battery module and pack assemblers facing margin compression as OEMs internalize barrier pad specification authority.
- Aftermarket Providers:Retrofit demand from second-life battery storage applications requiring field-installable fire containment solutions.
- Vehicle Assemblers:Contract manufacturers and white-label producers sourcing qualified barriers through tier-1 channels.
- Fleet Operators:Commercial vehicle purchasers specifying fire containment as part of total cost of ownership calculations for electric truck deployments.
OEMs retain volume leadership; aftermarket providers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys fire barrier pads primarily for GB 38031 compliance in cell-to-pack architectures, while German OEMs prioritize multi-layer composites for premium thermal performance, and Korean battery makers emphasize mass-reduction substrates for 800-volt platforms.
China
Domestic EV production exceeding seven million units annually drives substrate procurement volume through Ningbo and Changzhou manufacturing corridors. MIIT enforcement of GB 38031 mandates five-minute no-fire propagation standards, compelling thicker multi-layer pad specifications. Changzhou-based cell producers are pulling mica and aerogel conversion capacity toward battery assembly hubs to compress logistics cycles.
Germany
Premium manufacturers in Stuttgart and Munich specify certified fire barrier assemblies with integrated thermal and dielectric functions. ECHA administration of EU Battery Regulation flame-retardant disclosure requirements steers formulations toward mineral alternatives. Morgan Advanced Materials sustains OEM relationships through integrated mica mining and slitting operations in France and Germany.
South Korea
LG Energy Solution and Samsung SDI consolidate substrate qualification under single-vendor agreements, compressing supplier negotiation cycles to quarterly frameworks. Korean battery makers are qualifying closed-cell polyimide foam grades for 800-volt architectures where pack energy density gains justify premium substrate costs. Busan-Ulsan manufacturing belt anchors pyrogenic silica formulation capacity.
United States
NHTSA's updated FMVSS 305 and NFPA 855 guidelines for battery energy storage systems are cross-pollinating automotive fire containment standards. Pyrogenic silica supply concentration in limited domestic facilities exposes buyers to input volatility. Detroit-area OEM procurement teams are sequencing third-party and proprietary validation timelines extending six to eighteen months.
India
Domestic battery assembly under PLI scheme incentives creates demand for locally qualified fire barrier suppliers. BIS alignment with international thermal propagation standards is accelerating substrate qualification protocols. Tamil Nadu and Gujarat manufacturing corridors are attracting tier-one battery producers seeking to serve domestic EV and two-wheeler markets.
Automotive Battery Pack Fire Barrier Pad Market Competitive Landscape
Capability concentration sits with specialized material science firms possessing pyrogenic silica expertise and integrated mica supply chains; scale advantage sits with diversified chemical conglomerates with existing automotive qualification pathways. The market structures around three tiers: substrate innovators with proprietary formulations, converted material suppliers with lamination and slitting capacity, and diversified industrials leveraging cross-sector fire protection portfolios. Dominant competitive moves include backward integration into mineral mining operations and strategic partnerships with tier-one battery manufacturers for co-development of cell-to-pack barrier specifications.
Within the specialized aerogel tier, Aspen Aerogels exemplifies substrate innovation anchored in pyrogenic silica chemistry. Among diversified material conglomerates, 3M and DuPont occupy positions spanning automotive qualification pathways and cross-sector fire protection portfolios. Morgan Advanced Materials represents the integrated mining-to-conversion archetype with captive mica supply and European slitting operations.
| Leading Market Players |
|---|
| 3M |
| Aspen Aerogels |
| Morgan Advanced Materials |
| Autoneum |
| Henkel |
| Zotefoams |
| Alkegen |
| DuPont |
| Saint-Gobain |
| Others |
Pricing and Supply Chain Analysis
Pyrogenic silica precursor manufacturing clusters in limited US and Chinese facilities concentrate upstream supply, anchoring margin pools with aerogel substrate innovators while compressing returns for downstream converters lacking captive mineral access. Korean battery makers exploit this asymmetry through single-vendor qualification frameworks that extract volume discounts from dependent suppliers.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-one battery manufacturers and aerogel substrate suppliers, insulating qualified vendors from spot volatility while locking in quarterly price renegotiation cycles for fiber-based pad converters. Three-tier pricing structure across premium aerogel composites, standard ceramic fiber laminates, and economy-grade mineral wool separates OEMs by thermal performance certification and pack architecture complexity. Cost compression in fiber-based tiers is intensifying because Chinese cell producers internalize slitting operations under GB 38031 compliance mandates. Fleet operators and two-wheeler assemblers exhibit highest price sensitivity, whereas German premium OEMs prioritize UL 94 V-0 certification over unit cost.
Supply Chain Analysis
Extended payment terms from Korean battery makers to substrate suppliers—stretching to ninety days—force working capital strain onto converted material tier, accelerating consolidation toward vertically integrated mica miners. Raw material dependencies center on pyrogenic silica from US Gulf Coast facilities, mica sheet from Indian and Madagascan mines, and aramid fiber from DuPont's US and European polymer plants. Single-source vulnerability pervades aerogel precursor supply, with pyrogenic silica formulation capacity concentrated in Aspen Aerogels' Rhode Island complex and select Chinese state-owned chemical groups. Distribution runs through direct OEM contracting channels that displace traditional module-house procurement, particularly visible in South Korea's Busan-Ulsan manufacturing belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire barrier pad procurement is consolidating onto cell-to-pack platform architectures, creating ecosystem lock-in effects where substrate qualification for one OEM battery platform cascades across multiple vehicle programs through shared thermal management specifications.
For Market Incumbents: Entrench qualification relationships with Korean battery makers by co-developing 800-volt aerogel formulations that embed proprietary compression set specifications, blocking second-source substitution. Deepen captive mica supply through backward integration into Indian mining concessions before ECHA disclosure mandates tighten mineral traceability requirements. Priority defensive investment targets UL 2596 pre-certification capacity expansion in Changzhou to intercept Chinese OEM platform standardization decisions. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized battery assembly corridor by qualifying fiber-based pads for two-wheeler and entry-level EV platforms where incumbent aerogel suppliers lack cost-competitive offerings. White-space concentration sits with second-life battery storage retrofit applications requiring field-installable ceramic coating solutions, a segment absent from tier-one supplier roadmaps. Go-to-market leverage flows from partnerships with Tamil Nadu-based pack assemblers seeking localized fire barrier qualification under BIS-aligned thermal propagation protocols. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists possessing integrated mica mining-to-conversion capability and existing UL certification pathways, as these assets command scarcity premia under EU Battery Regulation flame-retardant disclosure timelines. Long-term viability hinges on substrate suppliers' capacity to absorb structural and dielectric functions into single components for cell-to-chassis architectures. Signal to monitor: Korean battery maker decisions to single-source versus dual-source aerogel qualification for next-generation 800-volt platforms, which would indicate consolidation versus fragmentation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mica Mining | Morgan Advanced Materials secures captive supply for EU Battery Regulation compliance. |
| Co-Development Partnership with Battery Makers | Aspen Aerogels anchors thermal runaway containment specifications for Korean 800-volt platforms. |
| UL 2596 Pre-Certification Investment | Accelerates OEM platform qualification timelines in Ningbo and Changzhou manufacturing corridors. |
| Closed-Cell Polyimide Foam Scale-Up | Zotefoams enables mass reduction for LG Energy Solution and Samsung SDI pack architectures. |
| Second-Life Storage Retrofit Capability | Captures aftermarket demand from stationary energy storage repurposing automotive packs. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one battery procurement directors, fire barrier substrate R&D leads, and thermal management system architects, then refined through secondary validation against MIIT GB standard filings, ECHA regulatory submissions, UL certification databases, and vehicle production registration data. Bottom-up estimates of pad content per vehicle by architecture type were triangulated against top-down market sizing from cell production forecasts.
Demand-supply balance modeling across the projection horizon segmented volume by substrate category, vehicle propulsion architecture, OEM tier, and regional production cluster, with CAGRs derived from regression against battery energy density trajectories and regulatory mandate implementation schedules. Industry-specific forecast inputs included cell-to-pack adoption curves by OEM lineage and pyrogenic silica capacity expansion announcements.
Stress conditions across pyrogenic silica supply disruption, ECHA flame-retardant restriction tightening, and Korean battery maker dual-qualification decisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and cell chemistry evolution; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Avalanche Airbags Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market