
 Automotive Airbag Silicone Market | 2026-2036
Automotive Airbag Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Airbag Silicone Market Analysis
Silicone-to-fabric bonding technology is fragmenting across multiple proprietary chemistries as airbag suppliers seek thinner, lighter coating layers that maintain gas-barrier integrity at extreme temperatures. Dow anchors its position through backward integration into siloxane monomers and regional compounding assets. Elkem Silicones competes on specialized high-tear-strength formulations for side-curtain applications. Wacker Chemie AG extends its footprint via automotive-qualified silicone rubber grades that meet Japanese OEM viscosity specifications.
Automotive airbag silicone comprises heat-cured polydimethylsiloxane formulations applied as coatings, gels, or foams onto woven nylon or polyester substrates to create gas-impermeable inflatable chambers; typical coatings achieve 20–50 micrometer thickness with Shore A hardness between 30 and 60 to balance foldability and burst resistance. Silicone rubbers dominate current volume owing to their established supply chains and processing familiarity among Tier-1 weavers, while silicone gels represent the fastest-expanding category as manufacturers adopt softer, lower-hysteresis materials for pedestrian-protection airbags. Passenger cars absorb the majority of silicone coating demand, though SUVs are pulling disproportionate volume growth due to larger curtain-airbag surface areas and multi-chamber designs.
The US NHTSA FMVSS 208 standard and the EU's UNECE R94/R95 regulatory frameworks mandate specific head-injury criteria and out-of-position occupant protection that directly determine silicone-coating thickness and seam-sealing requirements. Japan's MLIT aligns with these benchmarks through JIS D 0406 testing protocols, creating a harmonized compliance environment for multinational suppliers. Stakeholders must monitor evolving thermal-aging test cycles and hydrogen-siloxane emission thresholds that could disqualify incumbent formulations and force reformulation investments before next-generation vehicle platforms freeze their material specifications.
Market Dynamics
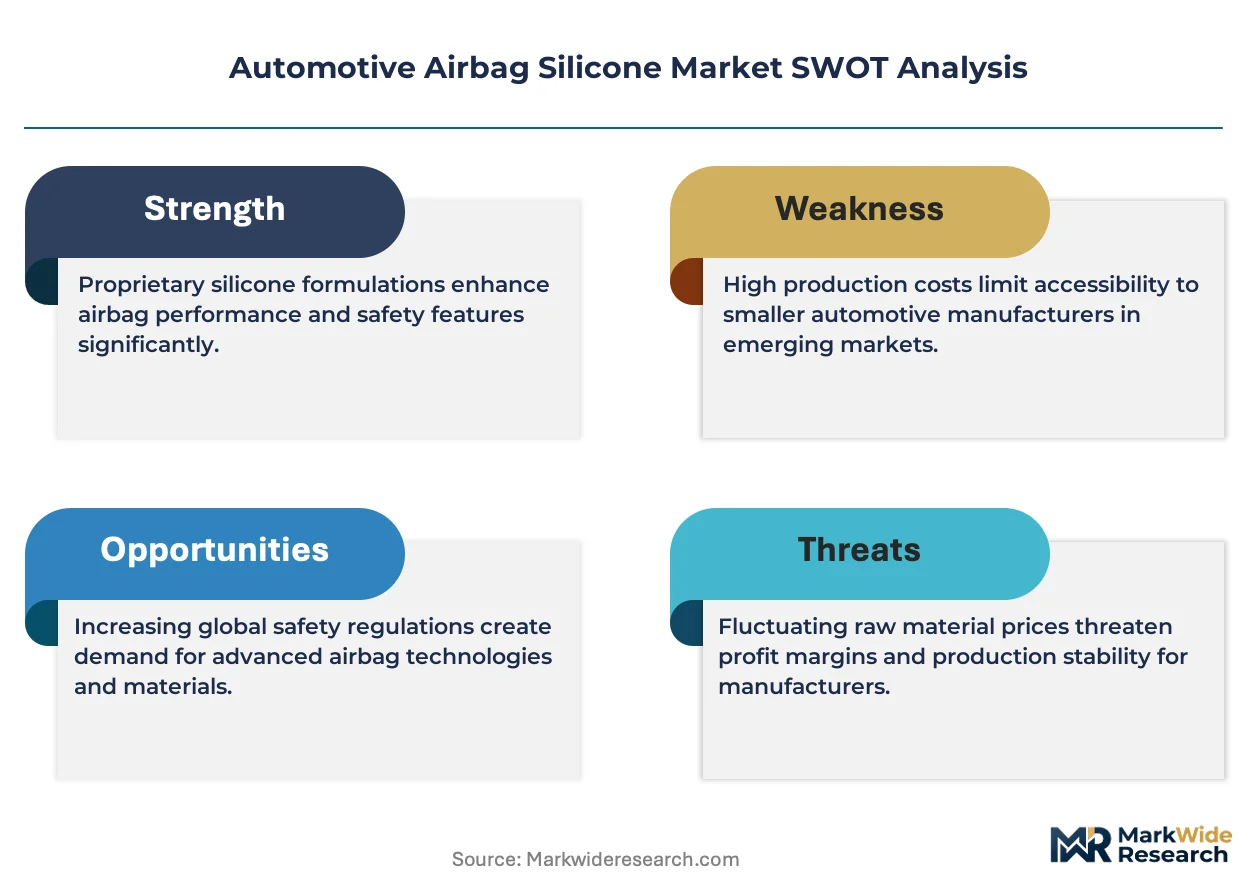
Automotive airbag silicone demand pivots on the forced migration from neoprene coatings to polydimethylsiloxane formulations driven by NHTSA FMVSS 208 and EU UNECE R94 head-injury mandates. Tier-1 weavers must retool coating lines to meet thinner-layer specifications while maintaining gas-barrier performance across thermal cycling extremes.
Growth Catalysts
- EU UNECE R94/R95:Mandated head-injury criteria force silicone-coated fabric upgrades in side-curtain and frontal airbag modules, compelling material transitions at German and Czech assembly plants.
- Side-curtain airbag expansion:SUVs and crossovers require larger inflatable surface areas with multi-chamber designs, multiplying silicone coating volume per vehicle platform.
- Japan JIS D 0406 alignment:Harmonized thermal-aging protocols with US and EU benchmarks enable single-formulation qualification for multinational OEM supply contracts.
Market Restraints
- Siloxane monomer concentration:Captive supply chains at Dow and Wacker Chemie AG limit second-source options for Tier-1 weavers seeking supply diversification.
- Hydrogen-siloxane emission thresholds:Evolving test cycles under EU REACH and EPA TSCA scrutiny threaten disqualification of incumbent formulations, forcing unbudgeted reformulation cycles.
- Neoprene cost anchoring:Legacy coating technology retains price advantage in budget vehicle segments, slowing silicone penetration in emerging-market passenger car platforms.
Strategic Opportunities
- Pedestrian-protection airbags:External inflatable systems for hood and A-pillar deployment require softer silicone gels with lower hysteresis, opening formulation specialization niches.
- India BIS automotive safety roadmap:Pending mandatory airbag regulations for entry-level vehicles create first-mover positioning for silicone coating qualification ahead of domestic supply chain maturation.
- Silicone gel-foam hybrid architectures:Converging gel flexibility with foam compressibility enables single-material solutions for complex-fold inflatable geometries in steering wheel and knee airbags.
Industry Challenges
- Coating thickness control at scale:Maintaining 20–50 micrometer uniformity across 1.5-meter fabric widths demands capital-intensive precision metering equipment and real-time vision inspection systems.
- Platform specification freeze timing:Material qualification must complete 18–24 months before SOP, compressing reformulation windows when regulatory test cycles update mid-development.
- Cross-functional skill scarcity:Polymer chemists with simultaneous silicone rheology and textile weaving expertise command premium compensation, constraining R&D bandwidth at mid-cap suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Airbag Silicone Market |
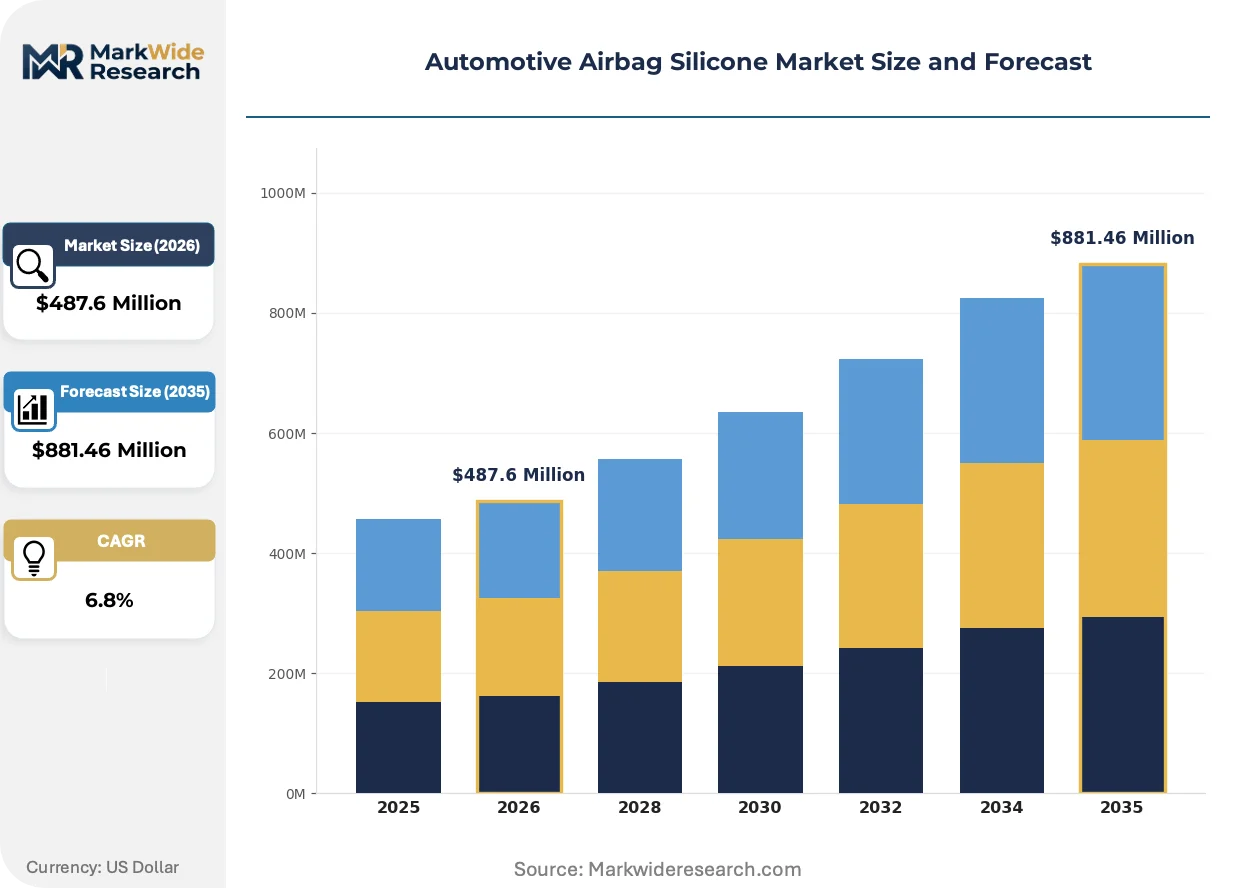
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Gels, Silicone Foams, Silicone Rubbers, Silicone Coatings Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, SUVs End User: Automotive Manufacturers, Tier-1 Suppliers, Aftermarket Providers, OEMs Technology: Compression Molding, Injection Molding, Extrusion, Casting |
| Companies Covered | Elkem Silicones, Global Safety Textiles, Dow, TOYOBO Co., Ltd., Toray Industries Inc, Momentive, Wacker Chemie AG, Porcher Industries, Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Airbag Silicone Market Emerging Trajectories
Silicone-to-fabric bonding technology is fragmenting across proprietary chemistries as suppliers race to deliver thinner, lighter coating layers without sacrificing gas-barrier integrity at temperature extremes. Three forces are reshaping competitive positioning.
Solventless liquid silicone rubber (LSR) coating systems are rendering obsolete traditional solvent-based neoprene dipping processes. German and Japanese Tier-1 weavers are adopting LSR at pilot scale for 2027 platform launches. The technology is rendering obsolete capital-intensive solvent recovery infrastructure while eliminating volatile organic compound compliance costs.
EU REACH Annex XVII restrictions on cyclic siloxane emissions are tightening test protocols for D4, D5, and D6 compounds in automotive interior applications. Formulators must validate reduced-migration grades or face market exclusion from German OEM supply lists. Side-curtain airbag fabric coaters in Bavaria and Baden-Württemberg are accelerating qualification of low-cyclic-content silicone rubbers ahead of 2026 enforcement milestones.
Japanese OEMs are consolidating silicone coating procurement under single-source qualification models with integrated compounders. Tier-1 airbag module assemblers in Aichi and Hiroshima prefectures now specify viscosity-certified grades direct from regional compounding assets, bypassing distributor intermediaries. This concentration is most visible in Toyota and Honda supply chains, where material traceability requirements have eliminated multi-source coating strategies.
Automotive Airbag Silicone Market Segmentation
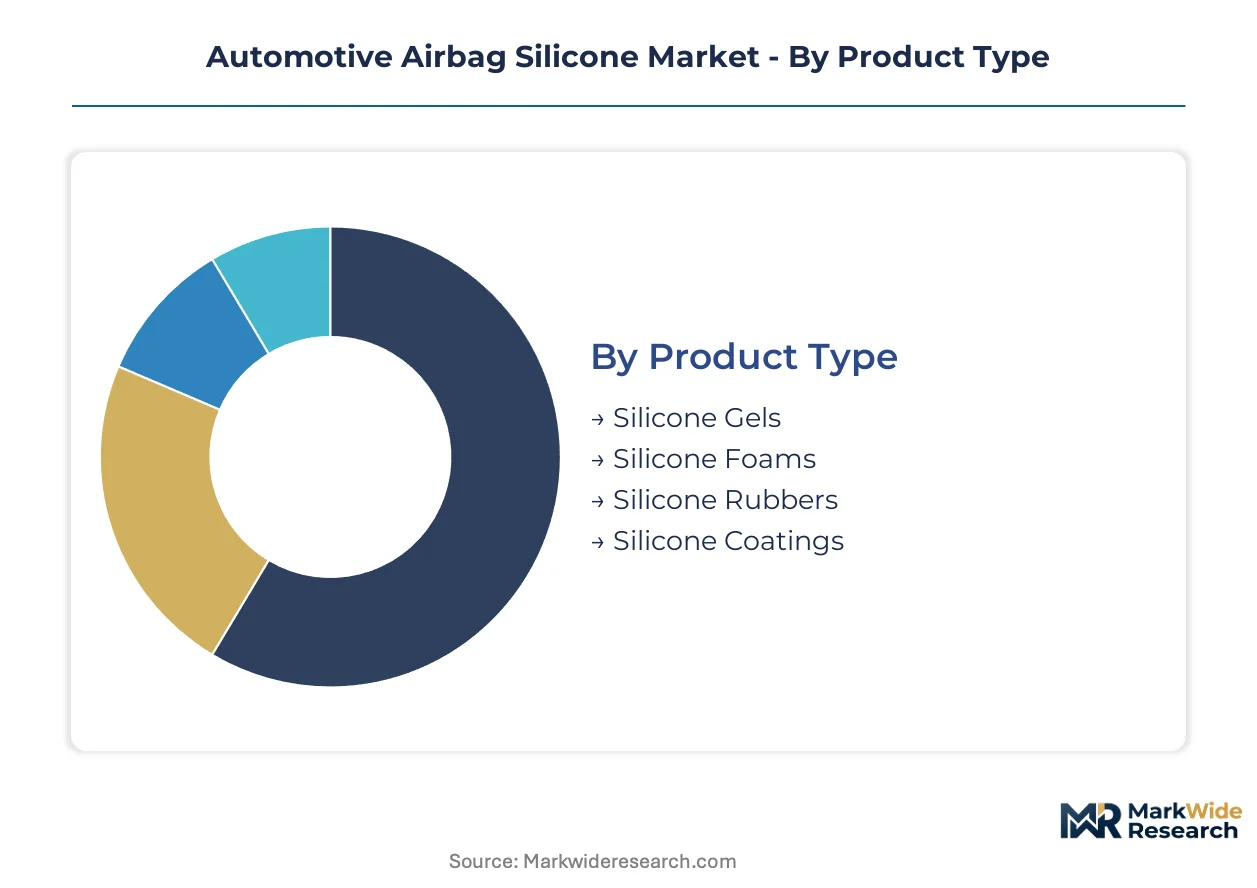
Automotive airbag silicone segmentation reveals how material specifications diverge across deployment geometries and manufacturing processes. Each dimension carries distinct qualification burdens and supply chain configurations that determine supplier competitiveness.
Product Type:
Material chemistry governs thermal performance envelopes and coating adhesion properties across inflatable chamber designs.
- Silicone Gels:Ultra-soft polydimethylsiloxane formulations with Shore 00 hardness enable pedestrian-protection airbags requiring minimal impact force. Japanese OEMs in Aichi Prefecture specify these grades for external hood-deployment systems where hysteresis control determines injury outcomes.
- Silicone Rubbers:Heat-cured elastomers with 30–60 Shore A hardness dominate current coating volumes through established supply chains at German and US Tier-1 weavers. NHTSA FMVSS 208 compliance timelines favor these proven formulations despite their higher density versus gel alternatives.
- Silicone Foams:Cellular structures provide compressibility for complex-fold geometries in steering wheel modules. Bavarian compounders supply automotive-qualified foam grades meeting JIS viscosity specifications.
- Silicone Coatings:Thin-film barrier layers applied via solventless LSR processes are displacing neoprene at pilot scale for 2027 platform launches.
Silicone rubbers hold installed capacity. Silicone gels are rotating up the share rankings.
Application:
Vehicle architecture determines inflatable surface area and chamber complexity, directly scaling silicone volume per platform.
- SUVs:Larger curtain-airbag footprints and multi-chamber side-protection systems multiply coating requirements versus compact passenger cars. US assembly plants in Tennessee and South Carolina drive disproportionate demand growth for extended-coverage inflatable structures.
- Passenger Cars:Frontal and knee airbag modules consume standardized coating widths at high production velocity. German OEMs in Stuttgart and Wolfsburg specify 20–30 micrometer thickness ranges for driver-side applications where packaging space constraints limit fold profiles.
- Commercial Vehicles:Heavy-duty cabin protection requires thicker barrier layers and reinforced seam sealing for rollover scenarios.
- Two-Wheelers:Emerging airbag vest applications for motorcyclists represent niche volume with specialized flexibility requirements.
SUVs command the steepest expansion trajectory. Passenger cars maintain volume dominance through production scale.
End User:
Procurement authority sits at different tiers of the supply pyramid, each with distinct technical qualification protocols.
- Tier-1 Suppliers:Integrated coating facilities adjacent to airbag module assembly plants in Germany, the United States, and Japan control material specification lock. Autoliv and ZF operate captive silicone compounding assets that bypass distributor intermediaries.
- Automotive Manufacturers:Direct material qualification by Toyota and Honda supply chains in Hiroshima Prefecture enforces single-source viscosity certification with full batch traceability.
- OEMs:Brand-holding entities delegate coating procurement to module assemblers while retaining crash-test validation authority.
- Aftermarket Providers:Replacement airbag fabric represents minimal volume given module replacement practices versus repair.
Tier-1 suppliers concentrate procurement leverage. Automotive manufacturers are asserting direct formulation control.
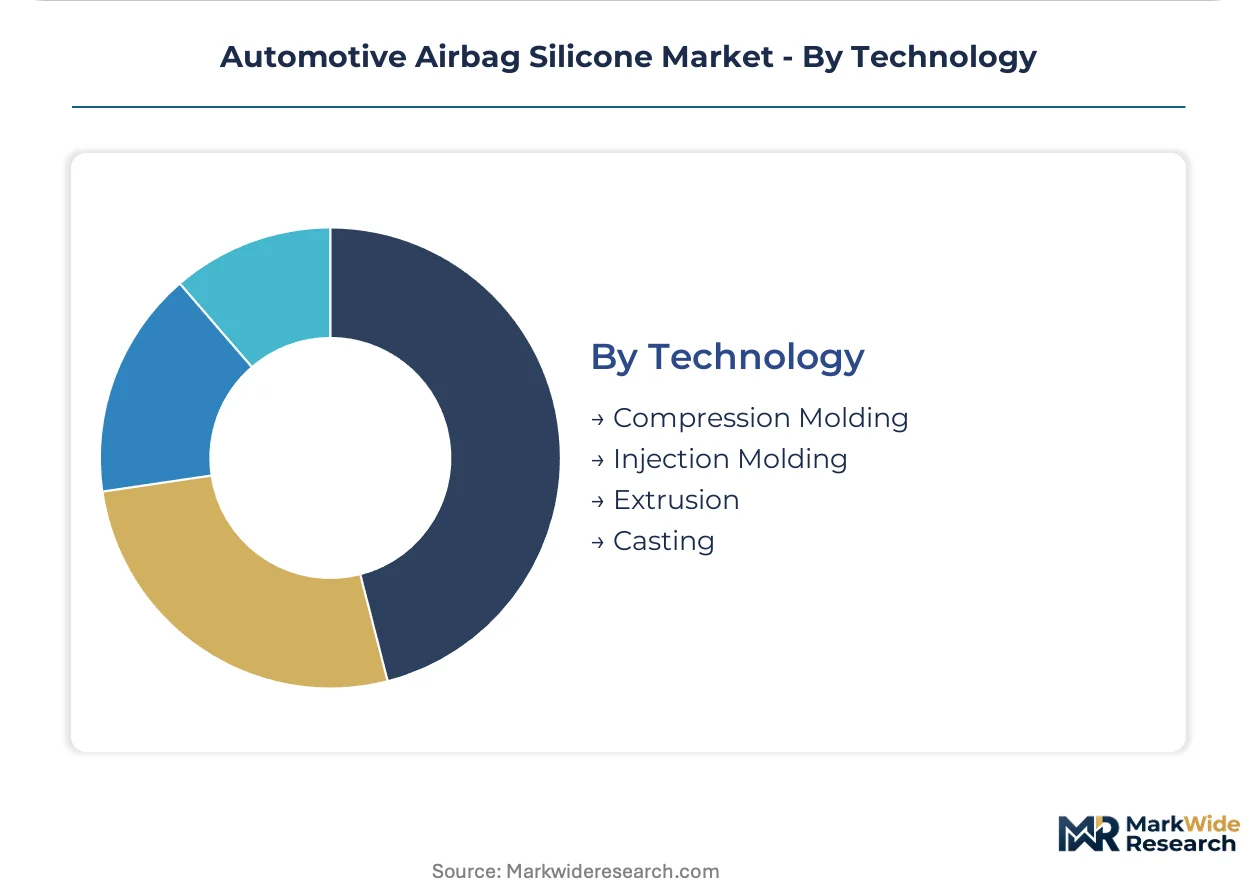
Technology:
Processing method determines coating uniformity, cycle time, and capital intensity for fabric conversion lines.
- Extrusion:Continuous coating deposition achieves 20–50 micrometer thickness control across 1.5-meter fabric widths. Japanese weavers in Aichi Prefecture operate precision metering equipment with real-time vision inspection for NHTSA-compliant barrier integrity.
- Injection Molding:Liquid silicone rubber injection enables complex three-dimensional inflatable geometries for knee airbag housings. German toolmakers supply automotive-qualified molding cells to Bavarian coating facilities.
- Compression Molding:Batch processes for thicker gel pads in pedestrian protection systems sacrifice throughput for material property control.
- Casting:Open-mold techniques persist in prototype and low-volume specialty applications with limited production scale.
Extrusion commands installed coating capacity. Injection molding is gaining share through LSR platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German silicone compounders export coated fabric substrates to assembly plants in the United States and Japan, forming the dominant trade corridor in automotive airbag materials. This three-node configuration concentrates specification authority with OEMs in Stuttgart, Detroit, and Toyota City.
United States
Tennessee and South Carolina assembly plants for SUVs and light trucks drive disproportionate demand for extended-coverage curtain airbags. NHTSA FMVSS 208 mandates determine silicone-coating thickness specifications for out-of-position occupant protection. Tier-1 weavers operate integrated coating lines adjacent to module assembly facilities in the Southeast manufacturing corridor.
Germany
Baden-Württemberg and Bavaria host the densest concentration of silicone-coating facilities serving European OEMs. EU UNECE R94 head-injury criteria force material upgrades from neoprene to polydimethylsiloxane formulations. Stuttgart-based module assemblers specify 20–30 micrometer coating layers for driver-side applications where packaging constraints limit fold profiles.
Japan
Aichi and Hiroshima prefectures concentrate procurement under single-source qualification models with integrated compounders. MLIT JIS D 0406 testing protocols align with US and EU benchmarks, enabling single-formulation qualification for multinational supply contracts. Toyota and Honda supply chains enforce viscosity-certified grades with full batch traceability requirements.
China
Domestic OEMs in Shanghai and Guangzhou are accelerating silicone-coating adoption as airbag penetration rises in entry-level passenger vehicles. MIIT automotive safety standards are converging with UNECE technical regulations, creating qualification pathways for multinational silicone suppliers. Yangtze River Delta fabric weavers are retooling lines to meet thinner-layer specifications for side-curtain modules.
India
Maharashtra and Tamil Nadu automotive clusters anticipate regulatory inflection as BIS develops mandatory airbag standards for entry-level vehicles. Pending regulations create first-mover positioning for silicone coating qualification ahead of domestic supply chain maturation. Chennai-based module assemblers are evaluating coating specifications for sub-4-meter passenger car platforms.
Automotive Airbag Silicone Market Vendor Landscape
On the supply side, the industry is consolidating around integrated compounders with captive siloxane monomer production and regional compounding assets. Three strategic archetypes dominate: diversified chemical conglomerates with backward integration into monomers, specialized silicone formulators with automotive-qualified grades, and Tier-1 weavers with captive coating capabilities. Competitive moves concentrate on capacity expansion in high-growth geographies and portfolio diversification into gel and foam formulations for pedestrian-protection applications.
Among diversified chemical conglomerates, Dow and Wacker Chemie AG exemplify the integrated archetype with upstream control over siloxane monomer supply. Elkem Silicones occupies a position within the specialized formulator tier, while Shin-Etsu Chemical Co., Ltd. anchors the Asia-Pacific supply base with Japan-based production assets. These three represent distinct strategic positions: monomer-integrated scale, formulation specialization, and regional production proximity to Japanese OEM qualification centers.
| Leading Market Players |
|---|
| Elkem Silicones |
| Global Safety Textiles |
| Dow |
| TOYOBO Co., Ltd. |
| Toray Industries Inc |
| Momentive |
| Wacker Chemie AG |
| Porcher Industries |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Single-source siloxane monomer dependency at Dow and Wacker Chemie AG determines both the premium commanded by certified automotive-grade formulations and the geographic clustering of Tier-1 coating facilities adjacent to module assembly plants in Germany, the United States, and Japan.
Pricing Analysis
The technology-generation pricing gap separates solventless liquid silicone rubber systems commanding premium positioning from legacy solvent-based neoprene coatings anchored in budget segments. Three-tier pricing structure across automotive-certified, industrial-grade, and economy formulations reflects differentiation by NHTSA FMVSS 208 compliance status and batch traceability depth. Cost compression in neoprene-competitive tiers is intensifying because legacy coaters retain price advantage in emerging-market passenger car platforms. Tier-1 weavers with integrated compounding assets exhibit lowest price sensitivity; aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for silicone-coated fabric substrates. Production gravity centers on Germany, the United States, and Japan, with raw material dependencies on siloxane monomers, woven nylon substrates, and platinum catalyst systems. Single-source vulnerability at monomer producers constrains second-source qualification timelines for multinational weavers. Distribution runs through captive coating facilities operated by Autoliv and ZF adjacent to OEM module assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive airbag silicone market is entering a cyclical recovery phase driven by regulatory mandate acceleration across EU UNECE R94/R95, US NHTSA FMVSS 208, and pending India BIS safety standards.
For Market Incumbents: Pre-empt gel formulation commoditization by accelerating low-cyclic-content silicone rubber qualification ahead of EU REACH Annex XVII enforcement milestones. Deepen backward integration into regional siloxane compounding assets to defend margin position against captive supply chain expansion at Dow and Wacker Chemie AG. Prioritize pedestrian-protection airbag certification to capture external deployment system growth.
For New Entrants and Emerging Players: Pursue white-space positioning in India BIS pre-regulation qualification cycles before domestic supply chain maturation locks out foreign compounders. Target silicone gel specialization for hood-deployment pedestrian protection systems where hysteresis specifications favor formulation expertise over scale. Establish direct technical partnership with Aichi Prefecture-based Tier-1 weavers seeking second-source viscosity-certified grades.
For Investors and Strategic Acquirers: EU REACH Annex XVII and EPA TSCA hydrogen-siloxane emission threshold tightening reshapes the acquisition landscape toward low-cyclic-content formulation capabilities. Long-term viability over the mid-decade window favors targets with integrated compounding assets and automotive OEM qualification track records. Monitor JIS D 0406 test cycle updates as signal for forced reformulation investment cycles that compress valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomers | Captive supply of D4/D5/D6 compounds secures formulation flexibility against REACH restriction volatility. |
| Low-Cyclic-Content Silicone Rubber Qualification | EU Annex XVII compliance enables continued German OEM supply list access through enforcement milestones. |
| Pedestrian-Protection Gel Formulation Development | External hood-deployment systems at Toyota and Honda create specialized demand with premium pricing. |
| Regional Compounding Asset Expansion | Proximity to Aichi and Hiroshima module assemblers satisfies single-source qualification and traceability mandates. |
| Solventless LSR Coating Line Conversion | Elimination of solvent recovery infrastructure reduces capital intensity for 2027 platform launch readiness. |
Methodological Framework
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, silicone compounding technical leads, and automotive textile weavers provided ongoing calibration across primary interview cycles. Secondary validation drew from NHTSA FMVSS 208 regulatory filings, EU UNECE R94/R95 technical documentation, JIS D 0406 test protocols, vehicle production databases, and customs trade records for siloxane monomer flows. Bottom-up coating volume estimates triangulated against top-down OEM airbag module production forecasts.
Scenario-bracketing framed demand projections across regulatory acceleration, baseline compliance, and delayed enforcement pathways. Segmentation dimensions encompassed product chemistry, vehicle architecture, procurement authority tier, and coating process technology. CAGRs derived from elasticity-adjusted volume build-ups against OEM platform SOP timelines. Forecast inputs incorporated hydrogen-siloxane emission threshold evolution and side-curtain airbag penetration rates in SUV segments.
Sensitivities concentrate around EU REACH test cycle updates, India BIS regulatory promulgation timing, and hydrogen-siloxane emission threshold stringency revisions. Forecasts reflect documented assumptions subject to revision when regulatory bodies publish amended protocols. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Motorcycle Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Global Automotive Braking System Market