
 Automotive Speed Limiter Market | 2026-2036
Automotive Speed Limiter Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Speed Limiter Market Analysis
Fleet operator consolidation across Europe and North America is realigning procurement patterns toward integrated speed management platforms. Continental AG leverages its embedded systems expertise to anchor long-term supply contracts with major commercial vehicle manufacturers. Bosch Mobility Solutions sustains technology leadership through proprietary engine management architectures that interface directly with vehicle powertrain controllers.
An automotive speed limiter is an active safety system that restricts vehicle speed through electronic control of throttle response, fuel injection, or braking intervention, typically operating within parameters of 5-250 km/h depending on configuration and jurisdictional requirements. The system serves to enforce regulatory speed compliance, reduce collision severity, and enable fleet operators to manage liability exposure across distributed vehicle assets. Hardware deployments currently dominate unit volumes due to mandatory OEM fitment requirements, while intelligent speed adaptation represents the fastest-expanding technology category as map-based predictive limiting gains regulatory traction in European markets. GPS-based systems command premium positioning where geofenced operational zones require dynamic limit enforcement.
The European Union's General Safety Regulation mandates intelligent speed assistance for all new vehicle types, while the UN ECE R79 standard governs steering and speed control system performance thresholds. India's Ministry of Road Transport has issued draft notifications requiring speed limiters on commercial vehicles exceeding defined gross vehicle weight classifications. Stakeholders must monitor divergence between regional certification requirements and emerging software-update capabilities that could reshape aftermarket installation economics.
Market Dynamics
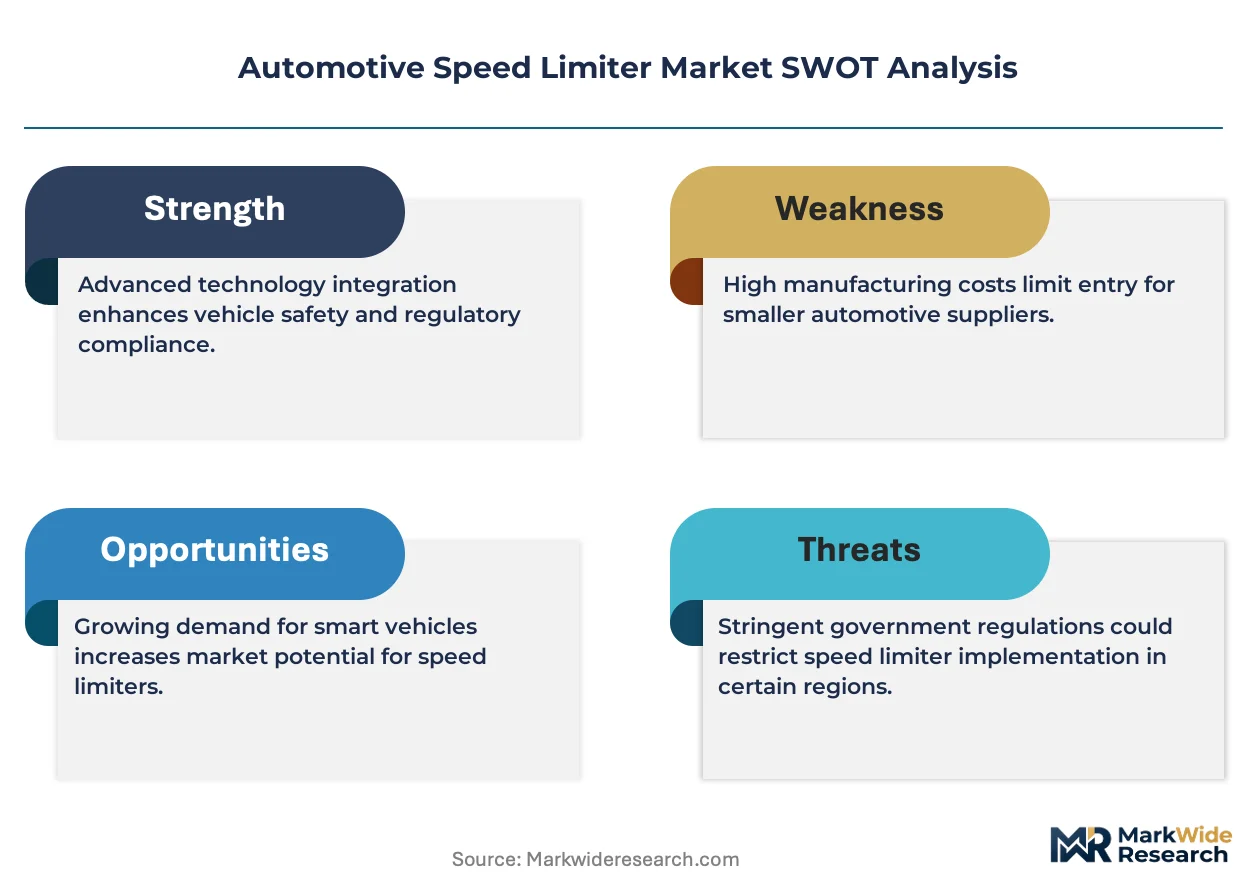
The EU's General Safety Regulation mandates intelligent speed assistance fitment on all new vehicle types, forcing OEMs to redesign electronic architectures around map-based predictive limiting rather than standalone hardware modules.
Growth Catalysts
- EU General Safety Regulation:Mandates intelligent speed assistance systems for all new vehicle types, compelling OEM integration and eliminating aftermarket-only deployment models.
- Commercial fleet liability management:Fleet operators across Germany and the Netherlands adopt speed limiters to reduce insurance premiums and accident-related legal exposure.
- Map-based predictive limiting:Real-time navigation data integration enables dynamic speed enforcement that adjusts to road conditions, construction zones, and temporary restrictions.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate automotive-grade microcontroller production, creating vulnerability in ECU sourcing for speed limiter systems.
- Technical limitation in GPS accuracy:Urban canyon effects and tunnel environments degrade signal reliability, requiring redundant inertial measurement unit backup that increases bill-of-materials cost.
- Regulatory friction from UN ECE R79:Steering and speed control performance thresholds create certification bottlenecks for systems combining adaptive cruise with intelligent speed adaptation.
Strategic Opportunities
- Underpenetrated India commercial vehicle segment:Draft Ministry of Road Transport notifications for mandatory speed limiters on heavy trucks create first-mover advantage for suppliers establishing local manufacturing.
- Technology convergence of V2X communication:Vehicle-to-infrastructure data exchange enables cooperative intelligent speed adaptation that responds to traffic signal timing and queue warnings.
- Subscription-based fleet management platforms:Telematics providers bundle speed limiter configuration with driver behavior analytics, creating recurring revenue streams beyond hardware sales.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering per ISO 26262 standards requires specialized expertise that outpaces European and Asian technical education pipeline output.
- Legacy powertrain integration complexity:Older commercial vehicle fleets with mechanical throttle linkages require expensive retrofit kits that compromise adoption economics for small operators.
- Cross-border certification timeline fragmentation:Divergent national type-approval processes between Germany's KBA and India's Automotive Research Association create parallel testing burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Speed Limiter Market |
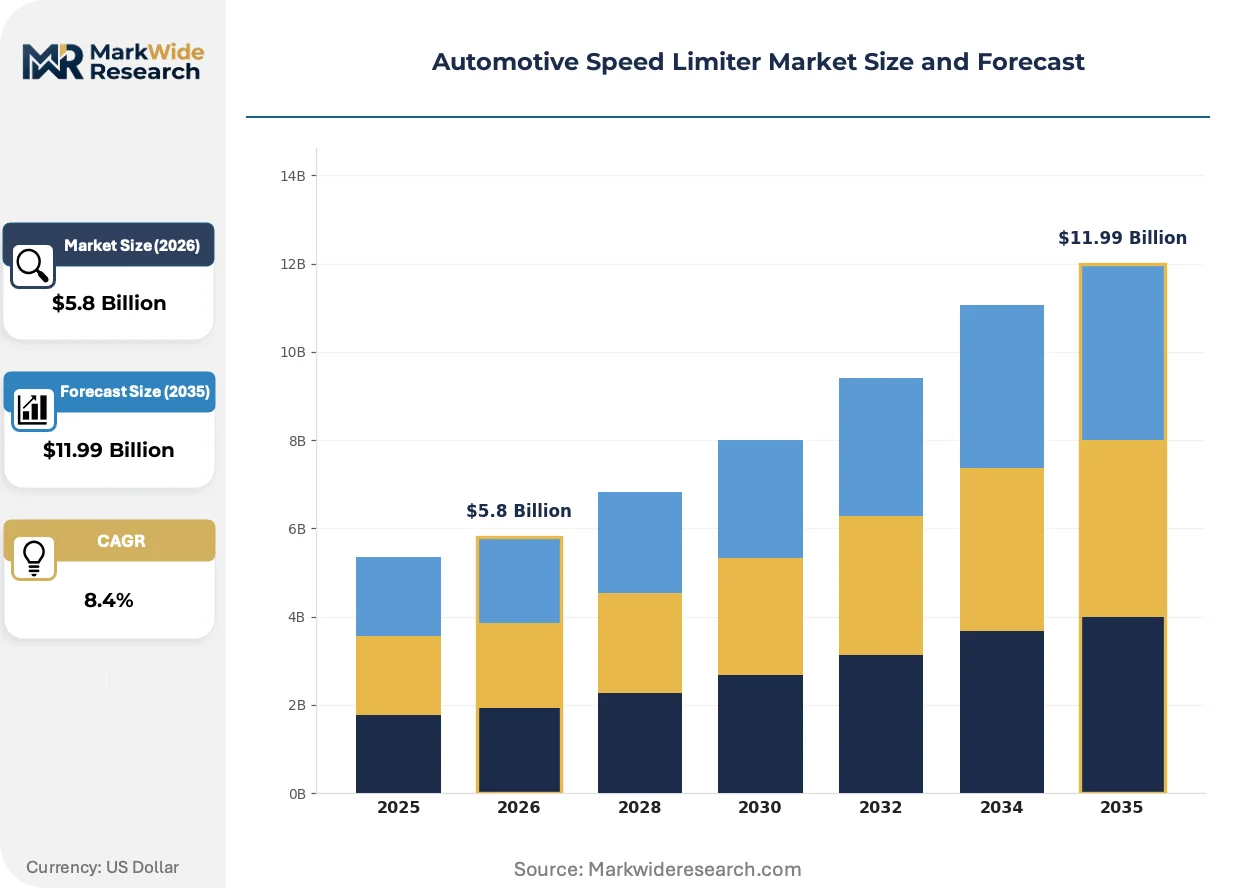
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Hybrid Systems, GPS-Based Systems Technology: Adaptive Control, User-Defined, Intelligent Speed Adaptation, Engine Management Application: Commercial Vehicles, Passenger Vehicles, Fleet Management, Aftermarket Installations End User: OEMs, Fleet Operators, Individual Consumers, Regulatory Bodies |
| Companies Covered | Valeo, Delphi Technologies, Continental AG, Autoliv, Wabco Holdings, Bosch Mobility Solutions, ZF Friedrichshafen, Mitsubishi Electric Corporation, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Speed Limiter Market Emerging Trajectories
Speed limiter technology is pivoting from reactive hardware enforcement toward predictive, map-aware systems that anticipate regulatory zones before drivers encounter them.
Camera-based traffic sign recognition is integrating with high-definition navigation maps to create redundant speed limit detection that operates when GPS signals degrade. German premium OEMs deploy this dual-sensor architecture as standard equipment, compressing the competitive window for standalone GPS-only systems. The technology is integrating engine management, transmission control, and brake intervention into unified powertrain domain controllers that execute speed reduction without driver perception.
REACH chemical regulations are accelerating the phase-out of legacy solder materials in automotive electronics, forcing ECU manufacturers to requalify assembly processes for lead-free alternatives. Industrial consequence includes extended validation cycles for speed limiter control modules destined for European markets. Powertrain suppliers with captive semiconductor packaging operations gain timeline advantage over outsourced competitors.
Fleet procurement departments now require speed limiter data export compatibility with third-party telematics platforms, unbundling hardware from proprietary software ecosystems. Equipment leasing companies and insurance underwriters in the United Kingdom specify open API access as a contract prerequisite. This pattern is most visible in long-haul trucking where operating lessors aggregate vehicle data across mixed OEM fleets.
Automotive Speed Limiter Market Segmentation
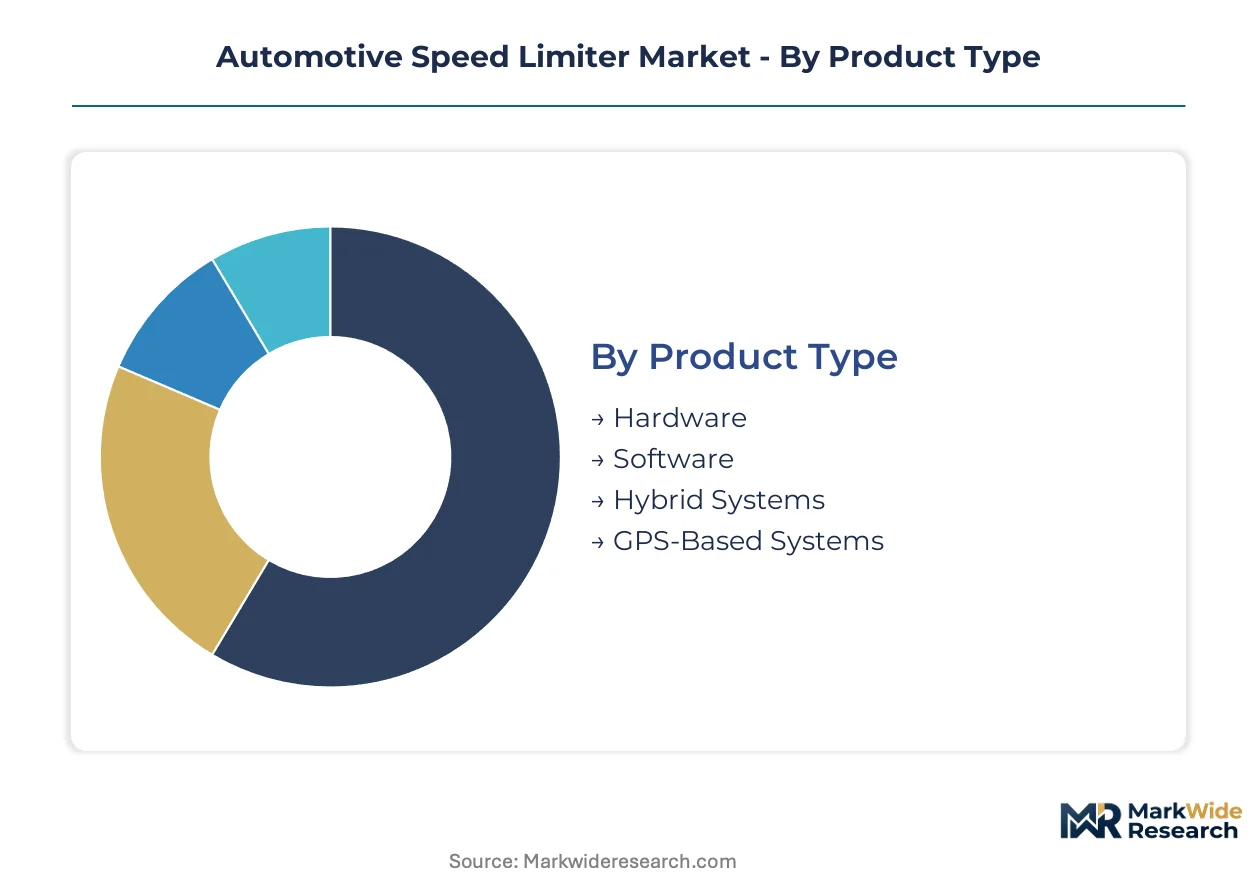
Speed limiter architectures fragment across standalone hardware modules, embedded software stacks, and hybrid configurations that blend both approaches. Procurement patterns diverge sharply between fleet operators seeking integrated telematics platforms and aftermarket buyers prioritizing retrofit economics.
Product Type:
Standalone hardware units dominate mandatory OEM fitments where regulatory compliance requires dedicated ECU architectures, while software-defined solutions embed directly into existing vehicle domain controllers.
- Hardware:Dedicated electronic control modules with discrete microcontrollers execute throttle intervention through hardwired powertrain interfaces. Germany's KBA type-approval framework favors these architectures for commercial vehicle mandates, though semiconductor sourcing constraints extend delivery timelines.
- Software:Embedded algorithms integrate with existing engine management systems, eliminating dedicated hardware while requiring rigorous ISO 26262 functional safety validation. Passenger vehicle OEMs in Japan and South Korea prefer this route for cost compression.
- Hybrid Systems:Combine dedicated safety processors with configurable software layers, bridging deterministic hardware response with updateable feature sets.
- GPS-Based Systems:Leverage satellite positioning with geofenced limit enforcement, commanding premium positioning in mining and construction fleet applications.
Hardware leads volumes today; software is gaining share fastest.
Technology:
Control philosophy separates reactive enforcement from predictive adaptation, with cost tiers clustering around sensor complexity and map integration depth.
- Intelligent Speed Adaptation:Fuses high-definition navigation maps with camera-based traffic sign recognition to anticipate regulatory zones before driver encounter. EU General Safety Regulation mandates are concentrating demand in France and Spain, where road signage variability rewards predictive systems.
- Adaptive Control:Real-time adjustment to traffic flow, weather conditions, and road geometry through fused sensor arrays. Premium commercial vehicle specifications in the Netherlands specify this capability for liability reduction.
- Engine Management:Direct fuel injection and ignition timing intervention without dedicated throttle actuators, prevalent in cost-optimized emerging market configurations.
- User-Defined:Configurable ceiling parameters set via dashboard interface or fleet telematics portal, common in parent-controlled passenger vehicle applications.
Intelligent Speed Adaptation commands premium positioning; Adaptive Control shows steepest expansion trajectory.
Application:
Deployment context determines hardware durability requirements, software update cadence, and integration complexity with legacy vehicle architectures.
- Commercial Vehicles:Heavy-duty ECUs withstand vibration and thermal cycling while interfacing with air brake systems and trailer electronics. India's draft Ministry of Road Transport notifications are accelerating procurement across Maharashtra and Gujarat freight corridors.
- Fleet Management:Centralized configuration platforms enable remote limit adjustment, geofenced enforcement, and driver behavior analytics aggregation. United Kingdom operating lessors specify open API compatibility as standard contract terms.
- Passenger Vehicles:Integration with cabin experience systems prioritizes imperceptible intervention and override transparency for consumer acceptance.
- Aftermarket Installations:Retrofit kits for mechanical throttle linkages face adoption friction from small operators despite regulatory pressure.
Commercial Vehicles anchor revenue today; Fleet Management is climbing the fastest.
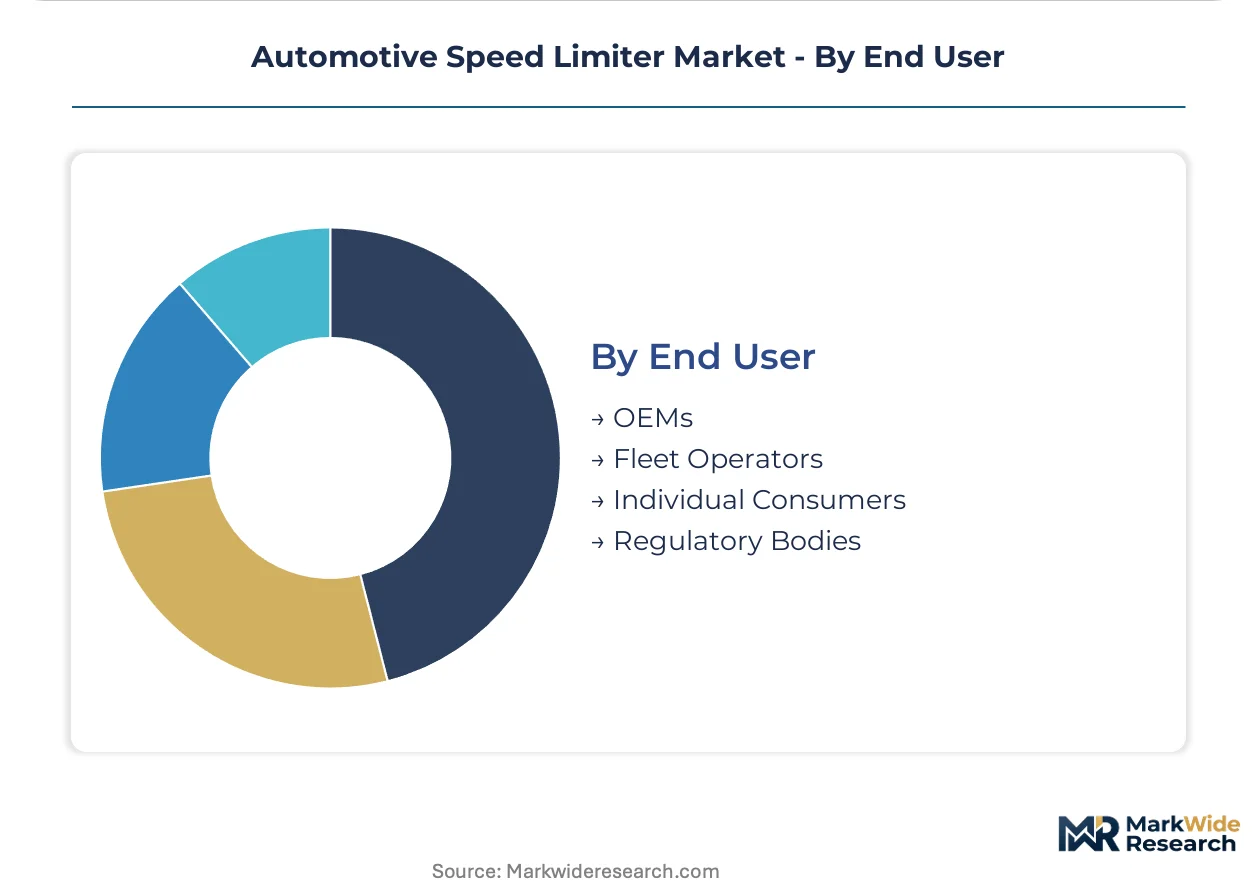
End User:
Procurement authority concentrates with entities bearing direct liability exposure, shaping pricing structures and service bundling strategies.
- Fleet Operators:Multi-vehicle owners negotiate enterprise pricing tied to insurance premium reductions and accident liability mitigation. German logistics conglomerates consolidate procurement through long-term supply agreements with embedded maintenance clauses.
- OEMs:Vehicle manufacturers integrate speed limiters as standard equipment to satisfy type-approval requirements, absorbing costs into base vehicle pricing.
- Regulatory Bodies:National transport authorities mandate fitment without direct procurement, acting as market makers through enforcement rather than purchasing.
- Individual Consumers:Parental control applications and insurance-linked voluntary installations represent niche demand with high price sensitivity.
Fleet Operators drive premium segment economics; OEMs capture baseline volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces the EU's most stringent intelligent speed assistance mandates, while India's draft commercial vehicle regulations are accelerating procurement across freight corridors. Market development diverges sharply between mature European compliance markets and emerging Asian enforcement zones.
Germany
KBA type-approval requirements and fleet liability protocols drive intelligent speed adaptation adoption among logistics operators. The EU General Safety Regulation mandates ISA fitment on all new commercial vehicle registrations from July 2024. Stuttgart's automotive electronics cluster concentrates Continental AG and Bosch Mobility Solutions engineering centers serving pan-European OEM contracts.
China
Commercial fleet electrification and intelligent vehicle mandates expand speed limiter integration into domain controller architectures. MIIT regulations on intelligent connected vehicles incorporate speed management as a core safety function. Shanghai's Yangtze River Delta electronics corridor hosts Denso Corporation and Mitsubishi Electric Corporation manufacturing facilities supplying domestic OEMs.
India
Draft Ministry of Road Transport notifications for mandatory speed limiters on heavy trucks above 3.5 tonnes gross vehicle weight accelerate supplier market entry. BIS certification requirements for automotive electronics create compliance barriers for uncertified imports. Maharashtra's Mumbai-Pune freight corridor and Gujarat's Mundra port logistics zone concentrate early fleet procurement activity.
United States
NHTSA speed limiter rulemaking for heavy-duty trucks remains under regulatory review, creating planning uncertainty for fleet operators. Insurance-linked voluntary installations gain traction among long-haul carriers seeking premium reductions. Michigan's Detroit-Warren automotive corridor anchors supplier engineering operations serving North American OEM integration programs.
United Kingdom
Operating lessors mandate open API telematics compatibility as standard contract terms, unbundling hardware from proprietary software ecosystems. DVSA enforcement protocols for commercial vehicle speed compliance intensify retrofit demand among small operators. Midlands logistics hubs around Birmingham and Coventry concentrate fleet management platform procurement.
Automotive Speed Limiter Market Vendor Landscape
German producers anchor the premium tier through embedded systems integration; Japanese and South Korean specialists hold positions in cost-optimized passenger vehicle configurations. Market structure consolidates around powertrain domain controller suppliers with captive semiconductor packaging capabilities. Three archetypes dominate: integrated tier-one powertrain suppliers, standalone safety electronics specialists, and telematics platform bundlers. Competitive moves center on functional safety engineering talent acquisition and backward integration into automotive-grade microcontroller sourcing.
Within the integrated tier-one tier, Continental AG and Bosch Mobility Solutions exemplify the European engineering-intensive model, while Denso Corporation represents Japanese manufacturing scale advantages. Continental AG anchors long-term supply contracts through embedded systems expertise. Bosch Mobility Solutions occupies a position defined by proprietary engine management architectures. Denso Corporation sits within the cost-optimized configuration segment serving high-volume Asian OEM programs. These three entities collectively illustrate the geographic and technical stratification governing procurement decisions across regulatory jurisdictions.
| Leading Market Players |
|---|
| Valeo |
| Delphi Technologies |
| Continental AG |
| Autoliv |
| Wabco Holdings |
| Bosch Mobility Solutions |
| ZF Friedrichshafen |
| Mitsubishi Electric Corporation |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Automotive-grade microcontroller silicon flows from Taiwan and South Korea through three-tier pricing structures across premium, standard, and economy levels, with EU REACH compliance costs compressing margins on lead-free solder requalification for European-bound ECU modules.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for cost-optimized passenger vehicle configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 functional safety certification grade and after-sales service bundling. Pricing pressure stems from semiconductor supply concentration as fleet operators negotiate enterprise volume discounts. Small commercial vehicle operators exhibit highest price sensitivity due to expensive mechanical throttle retrofit kit economics.
Supply Chain Analysis
Refurbishment flows for legacy mechanical throttle ECUs extend component lifecycles in India's aftermarket channel. Taiwan and South Korea anchor automotive-grade microcontroller production, while Germany and Japan supply precision throttle actuators. The chain draws from silicon wafers, rare earth magnets, and automotive-grade solder materials. Single-source vulnerability concentrates in 28nm automotive microcontroller fabrication. Distribution runs through Tier 1 powertrain suppliers with captive semiconductor packaging operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive speed limiter market compounds steadily as mandatory EU General Safety Regulation fitment creates baseline demand visibility across the analysis window.
For Market Incumbents: Deepen backward integration into automotive-grade microcontroller sourcing to defend against Taiwan supply concentration risk. Prioritize ISO 26262 functional safety engineering talent acquisition as embedded software expertise scarcity intensifies certification bottlenecks. Expand capacity in India's BIS-certified manufacturing corridors to capture first-mover advantage from Ministry of Road Transport mandates. For New Entrants and Emerging Players: Map-based predictive limiting algorithms offer a technology-first wedge into the fleet management software layer where open API compatibility requirements unbundle hardware from proprietary ecosystems. Target United Kingdom operating lessors with subscription-based telematics bundling. Pursue white-label supply contracts with European commercial vehicle OEMs seeking second-source intelligent speed adaptation modules. For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety engineering talent scarcity outpaces European and Asian technical education pipeline output. Five-to-ten year viability favors suppliers with captive semiconductor packaging and backward integration into ECU assembly. Target acquisition archetype: mid-tier safety electronics specialists with KBA type-approval credentials and established OEM relationships. Monitor India's BIS certification timeline acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microcontroller Sourcing | Taiwan supply concentration creates vulnerability for ECU manufacturers without captive semiconductor access. |
| ISO 26262 Functional Safety Certification Investment | German KBA type-approval requires rigorous validation that specialized engineering talent scarcity extends. |
| India Manufacturing Footprint Establishment | BIS certification barriers protect local assembly operations from uncertified import competition. |
| Open API Fleet Telematics Platform Development | United Kingdom operating lessors mandate data export compatibility as standard contract terms. |
| Map-Based Predictive Limiting R&D Expansion | EU General Safety Regulation mandates intelligent speed assistance fitment on all new commercial vehicle types. |
Methodological Framework
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers grounded qualitative findings. Secondary validation drew from vehicle production databases, IHS Markit registration data, UN ECE regulatory filings, and EU General Safety Regulation implementation guidance. Bottom-up and top-down triangulation reconciled segment-level unit economics with aggregate market sizing.
Bottom-up modeling projected volumes across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. Top-down validation anchored aggregate figures to OEM platform rollout schedules and regulatory mandate timelines. CAGRs were derived from segment growth rate differentials applied across the projection horizon. Forecast inputs incorporated fleet operator procurement consolidation patterns and semiconductor supply lead time assumptions.
The model holds under stable regulatory enforcement intensity; deviation in India's Ministry of Road Transport notification finalization or NHTSA rulemaking acceleration would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market