
 Automotive Brake Override System Market | 2026-2036
Automotive Brake Override System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Override System Market Outlook
ASIL-D certification requirements for safety-critical braking electronics is unwinding legacy architectures across the supply base. Robert Bosch GmbH leverages its integrated sensor-to-actuator pipeline to sustain engineering depth in electronic brake override modules. Continental AG anchors European OEM programs through captive semiconductor sourcing and in-house ASIC design. Denso Corporation dominates Japanese kei-car and compact vehicle platforms with cost-optimized sensor fusion packages.
An automotive brake override system is an active safety mechanism that electronically prioritizes brake command over accelerator input when simultaneous pedal depression exceeds calibrated thresholds, typically employing Hall-effect position sensors and redundant CAN bus signaling with sub-100-millisecond latency. Its primary commercial purpose is eliminating unintended acceleration incidents and satisfying functional safety mandates for SAE Level 2 and above driving automation. Electronic product types command the dominant value share as software-driven architectures displace mechanical interlocks, while sensor-based technology segments absorb disproportionate R&D investment due to fusion algorithm complexity and false-positive mitigation requirements. OEM installation types lock in the majority of volume through platform-level integration at vehicle design phase, though aftermarket retrofit channels are expanding for commercial fleet liability reduction.
NHTSA Federal Motor Vehicle Safety Standards, UNECE R79/R94 type approval frameworks, and Japan's MLIT safety device installation guidelines collectively mandate brake override capability or strongly incentivize its inclusion through NCAP scoring protocols. These regulations compress product development cycles and elevate validation costs, effectively filtering out suppliers lacking functional safety process maturity. Stakeholders must monitor the divergence between UNECE software update certification requirements and NHTSA's evolving autonomous vehicle exemption pathways, as regulatory misalignment threatens platform engineering economics.
Market Dynamics
ASIL-D certification mandates are compressing the supplier base by forcing functional safety process maturity onto brake override electronics, eliminating tier-two module houses lacking ISO 26262 audit trails while privileging integrated sensor-to-actuator pipelines.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standards:Mandated pedal misapplication prevention in the United States creates non-negotiable fitment requirements for all new passenger vehicles, locking in baseline demand regardless of consumer preference.
- Kei-car platforms in Japan:MLIT safety device installation guidelines for compact urban vehicles are accelerating cost-optimized sensor fusion adoption where packaging constraints favor electronic brake override over mechanical alternatives.
- Sensor fusion algorithm advancement:Hall-effect position sensing combined with redundant CAN bus architectures is reducing false-positive rates below calibration thresholds, removing the final barrier to SAE Level 2 automation integration.
Market Restraints
- Semiconductor supply concentration:Captive ASIC sourcing from German and Japanese foundries creates single-point vulnerability for European OEM programs, with 28nm automotive-grade wafer allocation favoring volume platform holders.
- Validation cost inflation:ASIL-D fault injection testing and hardware-in-the-loop simulation requirements add seven-figure certification overhead per platform variant, filtering out aftermarket retrofit specialists.
- Mechanical interlock substitution:Low-cost cable-actuated brake prioritization systems in emerging-market commercial fleets compete on first-cost despite inferior response latency.
Strategic Opportunities
- UNECE R79 type approval harmonization:Software update certification pathways in Europe are creating first-mover advantage for suppliers with OTA-capable brake override architectures, compressing validation cycles for mid-cycle platform refreshes.
- Commercial fleet liability reduction:Aftermarket retrofit channels for ride-hail and last-mile delivery vehicles in Germany and Japan are absorbing liability-driven demand outside OEM installation timelines.
- Dual-sensor fusion convergence:Integration of capacitive pedal position sensing with inertial measurement units is opening architecture differentiation for premium automation tiers.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 hardware and software architect talent concentrates at tier-one suppliers, constraining tier-two module houses from independent ASIL-D certification.
- Legacy platform integration friction:12-volt electrical architectures in existing vehicle fleets require voltage-level translation and signal conditioning retrofits, complicating aftermarket channel economics.
- Cross-regulatory divergence:Misalignment between NHTSA autonomous vehicle exemption pathways and UNECE software update requirements is forcing parallel validation tracks for global platform engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Override System Market |
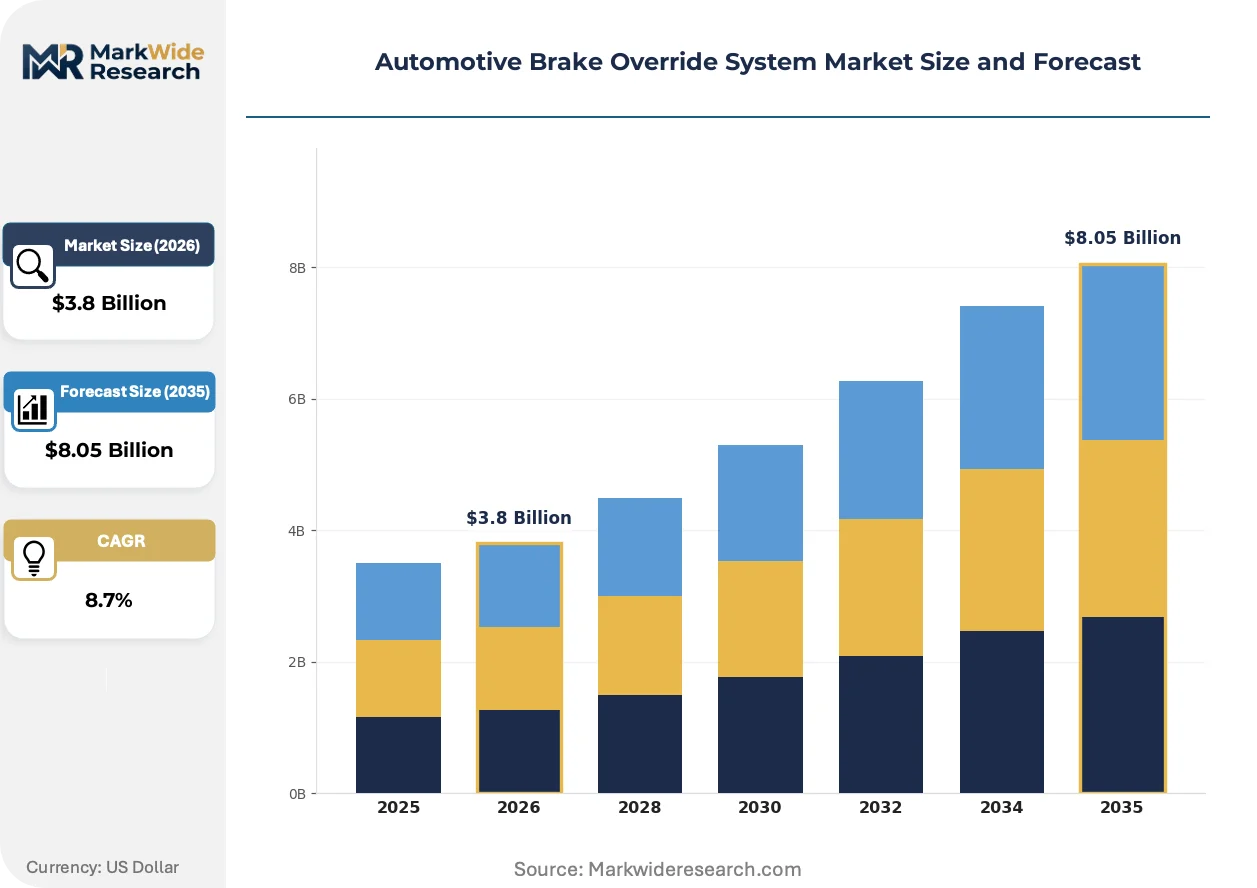
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Mechanical, Hybrid, Integrated Installation Type: OEM, Aftermarket, Retrofit, Custom End User: Fleet Operators, Individual Consumers, Dealerships, Manufacturers Technology: Adaptive Control, Sensor-based, Software-driven, Manual Override |
| Companies Covered | ZF Friedrichshafen AG, Valeo SA, Robert Bosch GmbH, Aptiv PLC, Magna International Inc., Continental AG, Toyota Motor Corporation, BorgWarner Inc., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Override System Market Strategic Shifts
Brake override system architecture is splitting between cost-optimized mechanical-electronic hybrids for mass-market fitment and fully deterministic software-defined platforms for automation-capable vehicles, with sensor fusion complexity driving R&D allocation.
Redundant Hall-effect position sensing with sub-100-millisecond latency is bifurcating the supplier landscape. Tier-one integrated module houses with captive semiconductor sourcing are securing German and Japanese OEM platform wins. Discrete component vendors without ASIC design capability are retreating to aftermarket retrofit channels or exiting brake override electronics entirely.
UNECE R79 steering equipment type approval and its software update certification appendix are compressing European product development cycles. Suppliers must demonstrate OTA update integrity for brake override parameters under functional safety governance. German OEM programs are responding by consolidating sourcing with partners holding both ASIL-D process maturity and cybersecurity management system certification.
Fleet procurement departments are unbundling brake override installation from base vehicle acquisition, negotiating direct supplier relationships for retrofit liability coverage. This channel disintermediation is most visible in United States ride-hail and Japanese compact commercial fleets, where aftermarket electronics specialists are capturing volume outside OEM captive finance structures.
Automotive Brake Override System Market Segmentation
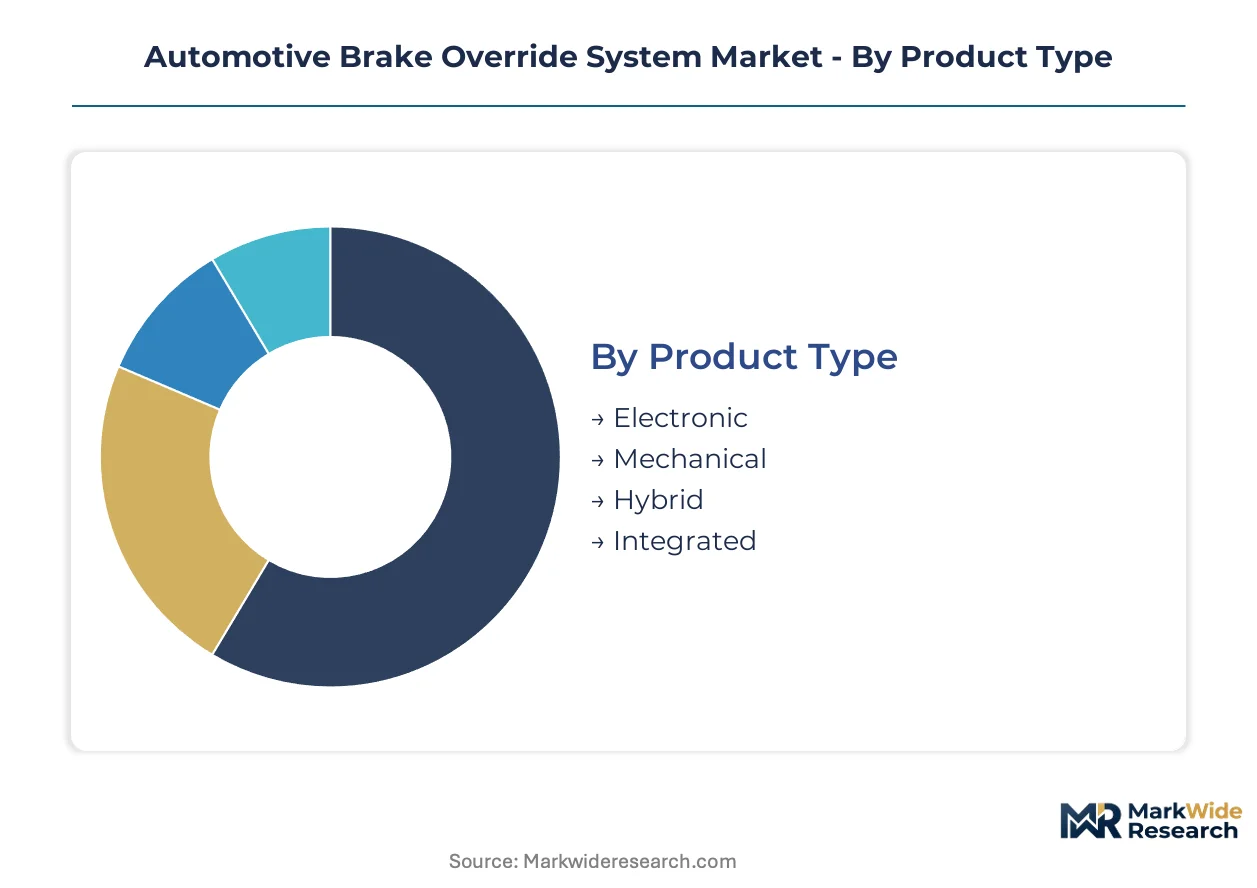
Brake override system segmentation reveals how functional safety mandates and automation roadmaps are fragmenting demand across hardware, software, and service layers. Each dimension exposes different vulnerability to cost pressure, regulatory timing, and supplier consolidation.
Product Type:
Mechanical interlocks face acute substitution pressure from electronic architectures as ASIL-D certification requirements harden and SAE Level 2 automation becomes baseline.
- Electronic:Hall-effect position sensors and redundant CAN bus signaling deliver sub-100-millisecond latency with deterministic fault detection. United States passenger vehicle OEMs are concentrating procurement here as NHTSA mandates eliminate mechanical alternatives from new platform designs.
- Hybrid:Combines electronic sensing with mechanical fallback actuation for emerging-market price sensitivity and legacy fleet compatibility. Demand clusters in Japanese kei-car platforms where MLIT guidelines permit phased electronic migration.
- Mechanical:Cable-actuated brake prioritization survives in commercial fleet retrofits and price-constrained segments. Brazil's ANVISA safety protocols still recognize mechanical compliance pathways.
- Integrated:Fused brake override with ADAS domain controllers and steer-by-wire systems. German OEM programs are specifying this for premium automation tiers where UNECE R79 software update certification applies.
Electronic architectures anchor the volume base while Integrated configurations gain share at the steepest rate.
Installation Type:
Channel economics diverge sharply between factory-integrated platforms and liability-driven retrofit procurement outside OEM timelines.
- OEM:Platform-level integration at vehicle design phase locks in multi-year supply agreements with ASIL-D certified module houses. Validation costs and semiconductor allocation priority favor incumbent tier-one suppliers with captive foundry relationships.
- Aftermarket:Fleet procurement departments in United States ride-hail and Japanese last-mile delivery segments are negotiating direct supplier relationships for liability coverage outside captive finance structures.
- Retrofit:12-volt electrical architecture translation requirements and signal conditioning complexity constrain economics. Germany's KBA type approval framework imposes parallel validation tracks for retrofit installations.
- Custom:Specialized commercial and defense vehicle applications with non-standard pedal geometries. Low volume and high engineering overhead limit supplier participation.
OEM installation commands the revenue concentration while Aftermarket channels expand most quickly through fleet disintermediation.
End User:
Risk transfer mechanisms and procurement authority are reshaping which stakeholders control supplier selection.
- Manufacturers:Platform engineering teams at German and Japanese OEMs specify brake override modules during vehicle architecture definition. ASIL-D process maturity and cybersecurity certification filter the supply base aggressively.
- Fleet Operators:United States ride-hail and Japanese compact commercial fleets are unbundling brake override from base vehicle acquisition. Direct supplier contracts for retrofit liability coverage are displacing OEM captive channels.
- Individual Consumers:Minimal direct engagement due to OEM standard fitment mandates. Awareness concentrates in markets with visible unintended acceleration litigation history.
- Dealerships:Service bay retrofit capacity and diagnostic tool compatibility determine aftermarket capture rates. Limited technical depth constrains ASIL-D system installation.
Manufacturers retain specification control while Fleet Operators are capturing procurement autonomy fastest.
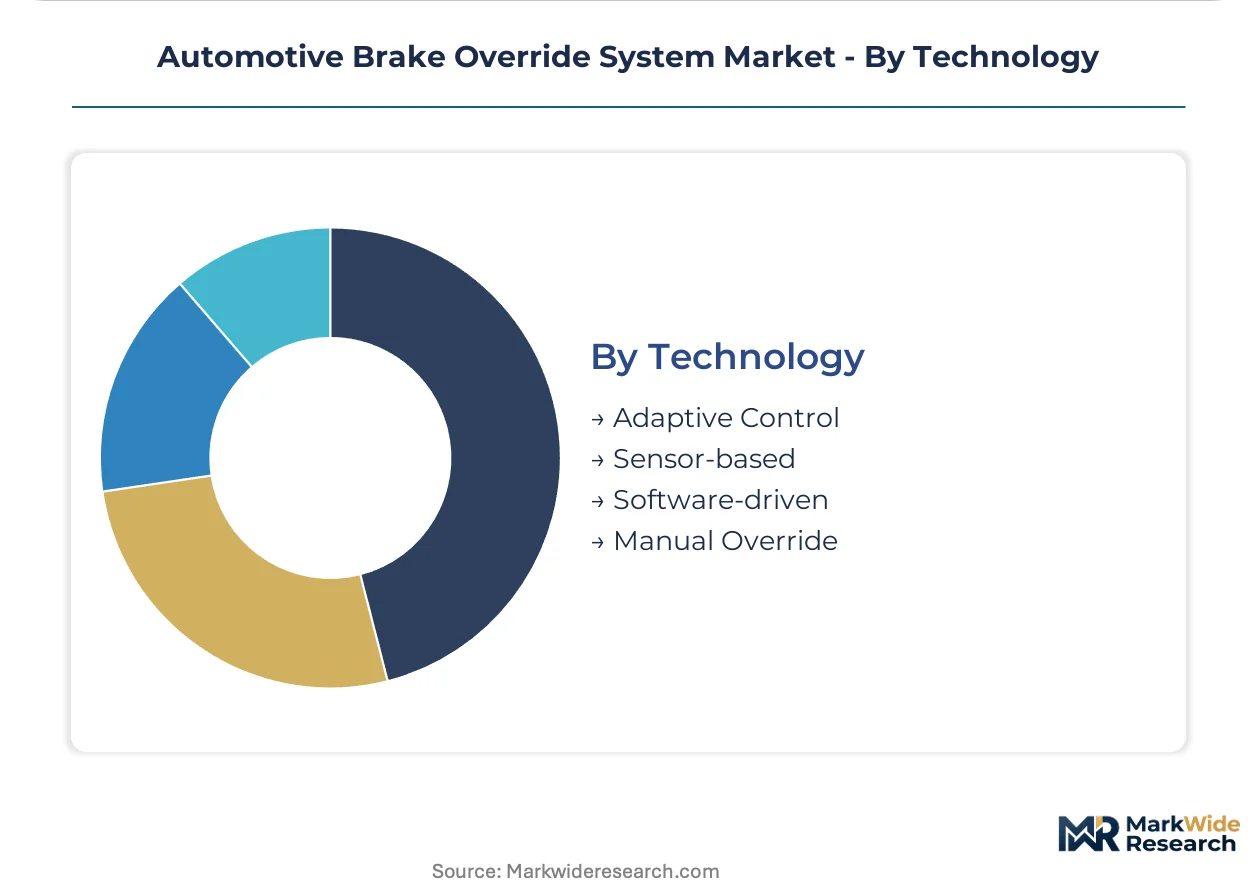
Technology:
Software certification requirements and sensor fusion complexity are elevating R&D allocation toward deterministic architectures.
- Sensor-based:Redundant Hall-effect and emerging capacitive pedal position sensing with inertial measurement unit fusion. False-positive mitigation algorithms absorb disproportionate engineering investment across German and Japanese OEM programs.
- Software-driven:Deterministic brake command prioritization with OTA update capability under functional safety governance. UNECE R79 software certification appendix is compressing European validation cycles for suppliers with cyber-security management systems.
- Adaptive Control:Dynamic threshold calibration based on vehicle load, road grade, and driver behavior patterns. Premium automation tier differentiation in German OEM portfolios.
- Manual Override:Driver-actuated mechanical or electronic bypass for track and emergency vehicle applications. Niche volume with specialized regulatory treatment.
Sensor-based platforms anchor current production while Software-driven architectures are climbing the fastest toward automation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in brake override electronics tilt toward net-import dependence in emerging automotive clusters, while established manufacturing hubs sustain component surpluses. Germany and Japan anchor export capacity for ASIL-D certified modules. The United States absorbs substantial inbound volume despite domestic assembly presence.
United States
NHTSA Federal Motor Vehicle Safety Standards mandate pedal misapplication prevention across all new passenger vehicles, creating non-negotiable fitment demand. The regulation compresses supplier qualification timelines and elevates validation overhead. Detroit's automotive corridor concentrates OEM engineering activity, with tier-one module houses securing multi-year platform agreements.
Germany
UNECE R79 type approval and its software update certification appendix accelerate OTA-capable brake override adoption. KBA oversight imposes parallel validation tracks for retrofit installations, filtering aftermarket participation. Stuttgart and Wolfsburg host concentrated OEM specification teams, driving integrated sensor-to-actuator procurement.
Japan
MLIT safety device installation guidelines for kei-car and compact urban platforms accelerate cost-optimized sensor fusion fitment. Metropolitan Tokyo and Nagoya anchor supplier engineering centers, with tier-one houses capturing kei-car platform wins through localized semiconductor sourcing.
China
GB standards adoption for functional safety in braking electronics is tightening, with MIIT guidelines converging toward ASIL-D equivalence for export-bound vehicles. Yangtze River Delta clusters around Shanghai concentrate module assembly capacity, though captive semiconductor sourcing remains underdeveloped.
South Korea
MFDS-aligned automotive safety protocols and domestic OEM automation roadmaps are driving brake override integration into SAE Level 2 platforms. Seoul Capital Area engineering centers specify fused brake-ADAS architectures, with tier-one suppliers securing platform-level contracts.
Automotive Brake Override System Market Competitive Environment
Listed leaders compete with private specialists across certification depth and captive semiconductor access. The supplier base compresses around tier-one module houses possessing ISO 26262 audit trails and in-house ASIC design capability. Three archetypes dominate: integrated sensor-to-actuator pipelines, semiconductor-captive European system houses, and cost-optimized Japanese kei-car specialists. Competitive moves concentrate on ASIL-D certification preemption and foundry allocation security for 28nm automotive-grade wafers.
Within the integrated pipeline tier, Robert Bosch GmbH and Continental AG exemplify engineering-depth positioning, while Denso Corporation occupies a distinct niche in compact vehicle cost optimization. Bosch's Stuttgart-based structure and Continental's AG status reflect listed-fundamented scale, whereas Denso's corporate form enables kei-car platform concentration. These three anchors illustrate how geographic regulatory alignment—German UNECE software certification, Japanese MLIT compact vehicle guidelines—shapes divergent capability investment.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Valeo SA |
| Robert Bosch GmbH |
| Aptiv PLC |
| Magna International Inc. |
| Continental AG |
| Toyota Motor Corporation |
| BorgWarner Inc. |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Electronic brake override modules displacing mechanical interlocks across passenger vehicle platforms simultaneously concentrates procurement power with ASIL-D certified tier-one suppliers and compresses price premiums for legacy mechanical alternatives. NHTSA mandates in the United States and UNECE R79 software certification in Germany are accelerating this substitution, rewiring supply geography toward Stuttgart, Wolfsburg, and Nagoya engineering clusters while squeezing margins for uncertified component vendors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with multi-year platform agreements locking in volume commitments. Price differentiation centers on ASIL-D certification grade and captive semiconductor sourcing capability, with German and Japanese module houses commanding premiums over tier-two competitors. Cost compression in hybrid and mechanical tiers is intensifying because emerging-market commercial fleets prioritize first-cost over response latency. Fleet operators in United States ride-hail segments exhibit highest price sensitivity, while German premium OEMs demonstrate lowest sensitivity due to automation integration requirements.
Supply Chain Analysis
Strategic stockpiling of 28nm automotive-grade wafers dominates inventory strategy among tier-one module houses seeking foundry allocation security. Semiconductor supply concentrates in Taiwan, South Korea, and Japan, with Hall-effect position sensors and redundant CAN bus controllers drawing from German and Japanese captive ASIC design. Single-source vulnerability in European foundry relationships creates structural risk for Continental AG anchored programs. Distribution runs through OEM platform engineering teams and direct fleet procurement channels, bypassing traditional aftermarket intermediaries for ASIL-D certified installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brake override system demand is accelerating through regulatory inflection as NHTSA mandates and UNECE R79 software certification harden fitment requirements across SAE Level 2 automation platforms. This regulatory compression is filtering supplier bases and creating asymmetric growth windows for certified participants.
For Market Incumbents: Shield platform engineering relationships by deepening backward integration into 28nm automotive-grade wafer allocation and accelerating ASIL-D certification preemption for next-generation sensor fusion architectures. Threat from software-defined vehicle entrants with deterministic brake command prioritization demands cybersecurity management system certification as defensive moat. Channel control through direct fleet procurement partnerships anchors volume outside OEM captive finance structures.
For New Entrants and Emerging Players: Aftermarket retrofit liability coverage for United States ride-hail and Japanese last-mile delivery fleets represents the most penetrable white-space where incumbents under-serve through OEM-centric sales structures. Target commercial fleet procurement departments with unbundled brake override installation separate from base vehicle acquisition. Go-to-market angle centers on 12-volt electrical architecture translation expertise and KBA parallel validation track navigation for retrofit installations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed tier-two module houses possessing ISO 26262 process maturity but lacking captive semiconductor sourcing. Long-term viability over the projection horizon hinges on ASIL-D certification depth and foundry relationship security. Signal to watch is UNECE R79 software update certification divergence from NHTSA autonomous vehicle exemption pathways compressing platform engineering economics.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Preemption | ISO 26262 audit trail investment filters tier-two competitors from German OEM platform bids. |
| Captive Semiconductor Sourcing | In-house ASIC design secures 28nm wafer allocation priority for electronic brake override modules. |
| OTA-Capable Architecture Development | UNECE R79 software update certification compresses European validation cycles for mid-cycle refreshes. |
| Commercial Fleet Direct Procurement | Liability coverage contracts with United States ride-hail operators disintermediate OEM captive channels. |
| Sensor Fusion Algorithm Investment | Capacitive pedal position sensing with inertial measurement unit integration opens premium automation tiers. |
Study Parameters
A standing panel of OEM platform engineers, tier-one supplier procurement leads, aftermarket fleet operations managers, and functional safety certification auditors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from NHTSA Federal Motor Vehicle Safety Standards filings, UNECE R79 type approval databases, vehicle production registries, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up platform-level volume estimates triangulated against top-down regulatory mandate penetration assumptions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, installation channel, end-user procurement authority, and technology architecture complexity. CAGRs derived from regression analysis of historical fitment rates against regulatory timeline acceleration. Industry-specific forecast inputs encompassed semiconductor foundry capacity allocation schedules and MLIT safety device installation guideline implementation phases.
Forecasts assume regulatory continuity in United States NHTSA, German KBA, and Japanese MLIT regimes; material policy shifts would require re-modeling. Specific risk factors include UNECE-NHTSA software certification divergence, 28nm wafer supply disruption, and functional safety engineer talent scarcity constraining tier-two certification timelines. Revision becomes warranted when ASIL-D certification backlog durations or foundry allocation priority thresholds cross destabilizing levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Stolen Vehicle Tracking System Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Vehicle Barrier System Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
Anti-Fog Lights Market