
 Marine Interiors Market | 2026-2036
Marine Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Interiors Market Analysis
Modular cabin manufacturing is reshaping how marine interiors are fabricated and installed, shifting production from shipyard floors to controlled factory environments. ALMACO Group leverages turnkey cabin module delivery to compress build schedules for cruise operators. Kaefer GmbH anchors its position through integrated HVAC and insulation packages bundled with interior fit-outs. Bolidt specializes in poured polyurethane flooring systems that eliminate seams and reduce maintenance cycles in high-traffic galley and deck areas.
Marine interiors encompass the complete fitted environment within commercial and leisure vessels, including fire-rated wall assemblies, vibration-dampened flooring, custom furniture, and LED lighting networks engineered to withstand salt corrosion and continuous motion. Cruise liners command the largest application share, with owners specifying lightweight composite paneling to reduce fuel consumption while expanding passenger capacity. Flooring represents a mature, high-margin segment where polyurethane and vinyl systems dominate refurbishment cycles, while wall paneling in aluminum-honeycomb composites shows the fastest growth trajectory among newbuild specifications.
The International Maritime Organization enforces SOLAS fire-safety protocols that directly determine material selection for ceilings, bulkheads, and furnishings across all oceangoing vessels. The EU's F-Gas Regulation restricts refrigerants in marine HVAC systems, pushing shipyards toward alternative climate-control designs that reshape interior spatial planning. Classification societies including Lloyd's Register and DNV mandate smoke-toxicity thresholds that filter which upholstery and surface treatments gain market access. Stakeholders must track how impending IMO carbon-intensity regulations will cascade into weight-reduction mandates that favor composite over traditional wood interiors.
Market Dynamics
Modular prefabrication is restructuring marine interiors production, compressing shipyard build cycles by relocating cabin assembly to climate-controlled factories where fire-rated composites cure under optimal conditions rather than on wet docks.
Growth Catalysts
- IMO SOLAS fire-safety mandates:Stricter flame-retardant standards for bulkheads and furnishings are forcing retrofit demand across existing fleets, expanding specification volumes for certified composite paneling.
- Cruise line capacity expansion:Operators are commissioning larger vessel classes that multiply interior square footage per hull, concentrating procurement of lightweight wall systems and vibration-dampened flooring.
- German shipyard clustering:Meyer Werft and MV Werften in Papenburg and Rostock anchor premium interior specification, drawing specialized suppliers into geographic proximity.
Market Restraints
- Aluminum-honeycomb raw material volatility:Aerospace and automotive sectors compete for the same lightweight core supply, creating price spikes that compress margins on composite paneling.
- EU F-Gas Regulation HVAC constraints:Restricted refrigerant options force costly redesigns of climate-control routing, adding spatial complexity to cabin module layouts.
- Certification timeline bottlenecks:Lloyd's Register and DNV smoke-toxicity testing queues extend lead times for upholstery and surface treatments, delaying installation schedules.
Strategic Opportunities
- Expedition cruise expansion:Polar-class vessel operators in Norway and Iceland are specifying ice-rated interiors with thermal insulation packages that exceed standard cruise specifications.
- Digital twin integration:Convergence of BIM modeling with modular manufacturing enables virtual fit-checking before physical production, reducing shipyard rework.
- EU Green Deal ship recycling mandates:End-of-life vessel dismantling rules are creating demand for demountable interior systems using mechanically fastened rather than adhesively bonded components.
Industry Challenges
- Skilled laminator shortages:Fire-rated composite fabrication requires certified technicians trained in resin infusion and vacuum bagging, with recruitment gaps acute in Baltic shipyard regions.
- Legacy vessel integration complexity:Retrofit projects must reconcile modern modular cabin footprints with existing steel grid spacing, forcing costly structural modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Interiors Market |
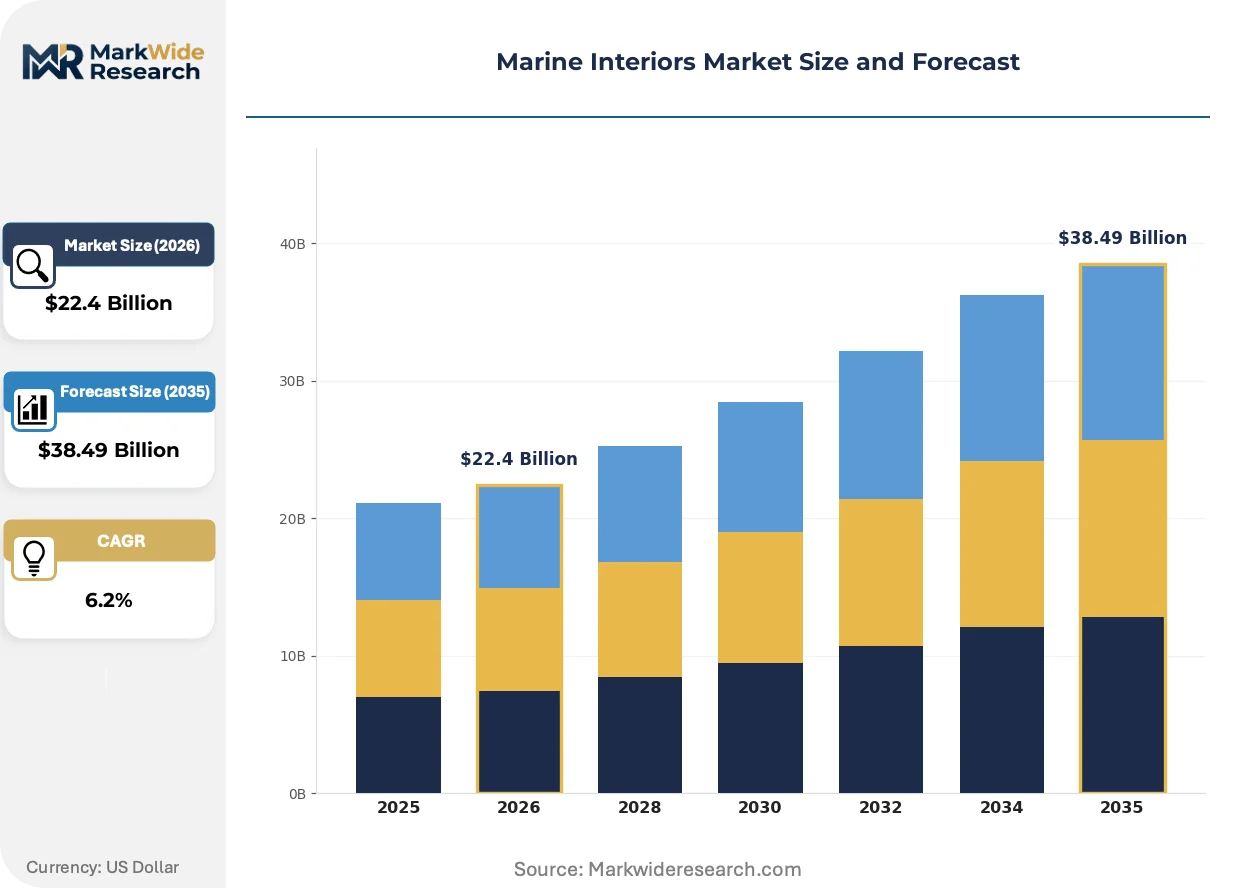
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $38.49 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Flooring, Wall Paneling, Lighting Application: Yachts, Ferries, Cargo Ships, Cruise Liners Material: Wood, Composite, Metal, Upholstery End User: Shipbuilders, Interior Designers, Owners, Operators |
| Companies Covered | Trimline Ltd, Bolidt, R&M Group, Aros Marine, Forbo Flooring Systems, ALMACO Group, Kaefer GmbH, NORAC AS, Marine Interiors S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Interiors Market Emerging Trajectories
Digital fabrication and regulatory tightening are converging to transform how marine interiors are specified, produced, and certified, with implications rippling from raw material selection through final shipyard installation.
Poured polyurethane flooring systems are collapsing the traditional seam-sealed vinyl installation model. Cruise operators and ferry owners are specifying continuous resin surfaces for galleys and public decks to eliminate grout-line maintenance. This shift compresses flooring lifecycle costs while reducing downtime during refurbishment windows.
The EU's F-Gas Regulation is redirecting marine HVAC engineering toward CO2 and ammonia-based climate systems. Shipyards in Germany and Finland are reconfiguring ceiling plenum depths and duct routing to accommodate larger heat exchangers. Wall paneling specifications are adapting to integrate chilled beam distribution rather than conventional forced-air vents.
Buyer concentration among mega-cruise operators is compressing supplier negotiation cycles. Royal Caribbean and Carnival Corporation are consolidating interior procurement through framework agreements that lock in multi-vessel pricing. Tier-two shipyards in Italy and France are responding by forming purchasing consortia to match volume discounts.
Marine Interiors Market Segmentation
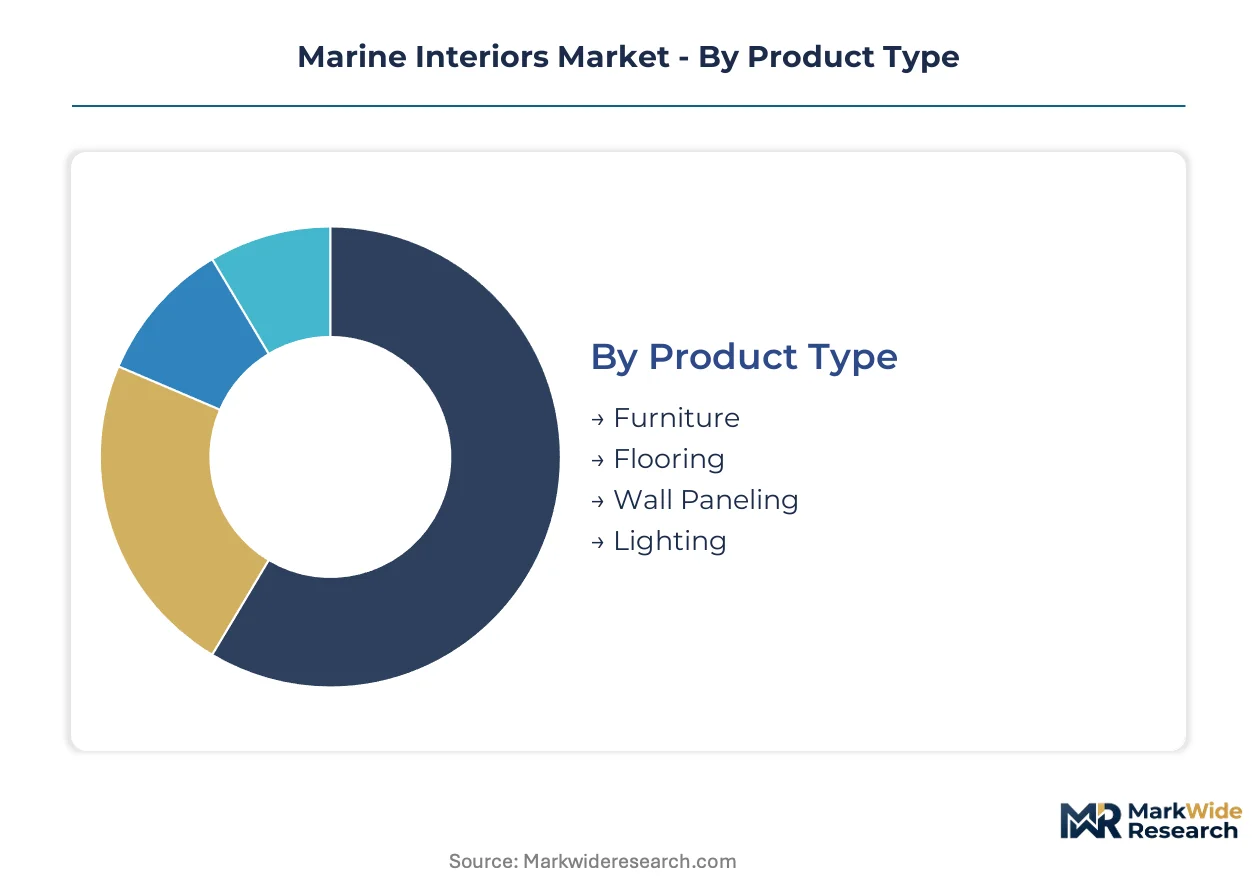
Segmentation in marine interiors separates specification pathways that diverge sharply on fire-certification burden, weight constraints, and refurbishment frequency. Cruise operators prioritize lightweight composites for fuel efficiency, while cargo fleets emphasize durability cycles over aesthetic refinement.
Product Type:
Cost tier structures procurement, with flooring commanding premium margins on lifecycle contracts and wall paneling driving newbuild volume.
- Furniture:Modular cabin systems integrate fixed and loose elements—berths, seating, storage—engineered for 15-year salt corrosion resistance. Demand clusters in German shipyards where Meyer Werft specifies custom millwork for luxury cruise contracts.
- Flooring:Poured polyurethane systems eliminate seam maintenance in galleys and high-traffic decks. Cruise operators in Mediterranean and Baltic routes specify continuous resin surfaces to compress refurbishment downtime.
- Wall Paneling:Aluminum-honeycomb composites meet SOLAS flame-retardant mandates while reducing hull weight. Retrofit fleets in Northern Europe drive specification for fire-rated paneling that integrates HVAC routing.
- Lighting:LED networks with IP67 sealing withstand vibration and humidity in engine-adjacent spaces. Ferry operators prioritize circadian rhythm systems for passenger well-being on overnight routes.
Flooring holds installed capacity. Wall paneling is rotating up the share rankings.
Application:
Volume concentrates where passenger density multiplies interior square footage per hull, with vessel class determining fire-safety tier and material specification intensity.
- Cruise Liners:Mega-vessels exceed 200,000 GT with casino, theater, and retail interiors demanding certified composites across 3,000+ cabins. Royal Caribbean and Carnival framework agreements consolidate procurement for multi-ship programs.
- Yachts:Superyacht builds above 60 meters specify bespoke millwork and stone surfaces without weight constraints. Mediterranean shipyards in Italy and Turkey dominate high-value custom fit-outs.
- Ferries:Ro-Pax vessels require rapid-turnaround cabin modules for 12-hour route cycles. Scandinavian operators specify demountable interiors to accommodate seasonal capacity swings.
- Cargo Ships:Minimal accommodation blocks prioritize steel-backed vinyl flooring and phenolic-resin wall panels for 25-year service intervals. Bulk carrier owners defer refurbishment to statutory survey windows.
Cruise liners hold installed capacity. Ferries are rotating up the share rankings.
Material:
Supply concentration shapes specification, with aerospace competition constraining aluminum-honeycomb availability and FSC-certified timber facing EU Green Deal traceability mandates.
- Composite:Glass-reinforced phenolic and aluminum-honeycomb sandwich panels achieve Class A fire ratings at 40% weight reduction versus plywood. German and Finnish shipyards specify composites for polar-class ice-rated interiors requiring thermal insulation integration.
- Wood:Teak and oak remain specified for yacht salons and cruise luxury suites despite SOLAS exemption paperwork. Southeast Asian supply chains face EUDR deforestation due diligence requirements.
- Metal:Stainless steel framing and aluminum extrusions provide structural backing for soft-fit elements. Galley and hospital areas specify metal-core furniture for hygiene washdown protocols.
- Upholstery:Inherently flame-retardant fabrics with IMO FTP Code Part 8 certification replace surface-treated textiles. Smoke-toxicity testing queues at Lloyd's Register delay new pattern approvals.
Wood holds installed capacity. Composite is rotating up the share rankings.
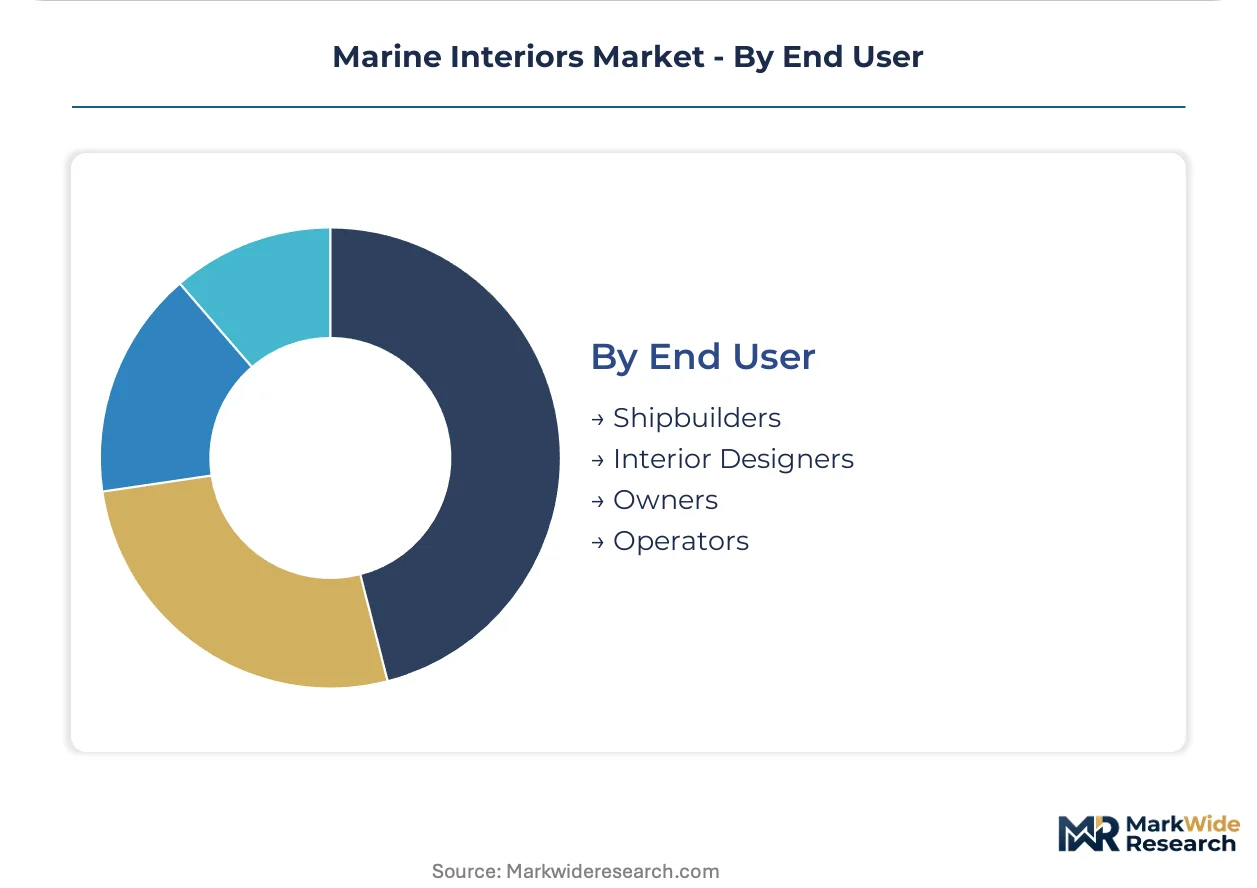
End User:
Customer type determines specification authority, with shipbuilders controlling newbuild material selection and operators driving retrofit demand through refurbishment cycles.
- Shipbuilders:Meyer Werft, MV Werften, and Fincantieri consolidate interior procurement through captive supply agreements. German yards specify modular cabin packages from ALMACO and Kaefer to compress build schedules.
- Operators:Cruise lines commission mid-life refits at 10-15 year intervals, replacing soft furnishings and lighting networks. Expedition operators in Norway and Iceland specify upgraded thermal packages for polar route expansion.
- Interior Designers:Studio-based firms translate brand concepts into technical specifications for wall coverings and fixed furniture. Luxury yacht projects engage London and Milan studios for bespoke material curation.
- Owners:Private yacht and small ferry owners direct refurbishment through shipyard project management, with material selection constrained by classification society survey windows.
Shipbuilders hold installed capacity. Operators are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports marine interior systems to shipyards across Northern Europe while importing specialized aluminum-honeycomb core materials from aerospace suppliers in the United States and Japan. This trade pattern concentrates high-value fabrication in Papenburg and Rostock while sourcing raw materials globally.
Germany
Meyer Werft and MV Werften drive specification for premium cruise interiors, with modular cabin contracts compressing build schedules by 30 percent. The EU's F-Gas Regulation forces HVAC redesigns that reshape ceiling plenum depths in newbuild specifications. The Papenburg cluster anchors production, drawing ALMACO and Kaefer into captive supply agreements for turnkey interior delivery.
Italy
Fincantieri consolidates procurement across multi-ship programs, concentrating demand for fire-rated composite paneling in Monfalcone and Trieste yards. The EU Green Deal's ship recycling mandates push specification toward mechanically fastened rather than adhesively bonded interior systems. Mediterranean superyacht builders in Viareggio and Livorno specify bespoke millwork without weight constraints.
Finland
Polar-class icebreaker and expedition cruise orders expand thermal insulation requirements beyond standard cruise specifications. The country's national maritime regulator enforces IMO SOLAS protocols with additional ice-rating certifications for Arctic routes. Turku shipyards coordinate with composite suppliers to integrate HVAC routing within wall assemblies for reduced hull penetrations.
United States
Royal Caribbean and Carnival Corporation framework agreements lock in multi-vessel pricing for interior procurement, compressing supplier negotiation cycles. The US Coast Guard enforces SOLAS-equivalent fire-safety standards for vessels calling at American ports. Florida-based refurbishment facilities handle mid-life retrofits for Caribbean-deployed fleets, replacing soft furnishings and LED networks at 10-15 year intervals.
Norway
Expedition cruise operators specify upgraded thermal packages for polar route expansion into Svalbard and Antarctic waters. The Norwegian Maritime Authority mandates smoke-toxicity thresholds that filter upholstery approvals through Lloyd's Register testing queues. Bergen and Oslo clusters concentrate design engineering for ice-rated interiors with integrated climate-control systems.
Marine Interiors Market Vendor Landscape
On the supply side, the industry is consolidating around turnkey modular providers that compress shipyard installation schedules through factory-based prefabrication. Tier-one fabricators bundle HVAC, insulation, and interior fit-outs into single-source contracts, while specialized flooring and lighting suppliers occupy narrower vertical niches. Two strategic archetypes dominate: integrated module deliverers and material-specific specialists. Competitive moves center on geographic co-location with German shipyard clusters and backward integration into composite core manufacturing to secure aluminum-honeycomb supply.
Within the integrated module tier, ALMACO Group and Kaefer GmbH exemplify turnkey cabin delivery models that relocate assembly from wet docks to climate-controlled factories. Bolidt occupies a position among poured-system flooring specialists, representing the segment where continuous resin surfaces displace traditional seam-sealed vinyl installations. These three anchors illustrate how supplier positioning diverges between full-package integrators and single-product depth players.
| Leading Market Players |
|---|
| Trimline Ltd |
| Bolidt |
| R&M Group |
| Aros Marine |
| Forbo Flooring Systems |
| ALMACO Group |
| Kaefer GmbH |
| NORAC AS |
| Marine Interiors S.p.A. |
| Others |
Supply Flow & Price Mechanics
Aluminum-honeycomb raw material volatility functions as the central risk vector that simultaneously widens pricing spreads between premium composite paneling and standard-grade alternatives while compressing supply chain configurations toward captive core manufacturing in Germany and Finland.
Pricing Analysis
Next-generation aluminum-honeycomb composite paneling commands substantial premiums over prior-generation plywood-based systems and current-generation glass-reinforced phenolic alternatives. Pricing stratifies across premium, standard, and economy tiers based on SOLAS fire-certification grade and volume scale under framework agreements. Cost compression in standard-grade flooring is intensifying because cruise operators are consolidating procurement through Royal Caribbean and Carnival multi-vessel contracts. Cargo ship owners exhibit highest price sensitivity due to deferred refurbishment cycles, while expedition cruise operators show lowest sensitivity when specifying polar-class thermal packages.
Supply Chain Analysis
Export-control regimes on aerospace-grade aluminum alloys restrict material flows from United States and Japanese suppliers to European fabricators, forcing German shipyards to diversify sourcing. Supply concentrates in Germany, Italy, and Finland for finished cabin modules, while drawing aluminum-honeycomb core from aerospace suppliers in the United States and Japan. Raw material dependencies center on phenolic resin systems, FSC-certified timber, and flame-retardant upholstery textiles. Single-source vulnerability in aerospace-grade core supply creates structural risk. Distribution runs through captive supply agreements between Meyer Werft and turnkey module providers rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine interiors market functions as a defensive-moat story where regulatory entrenchment through SOLAS certification timelines creates switching costs that lock shipyards into established supplier relationships.
For Market Incumbents: Build certification-backlog moats by expanding Lloyd's Register and DNV smoke-toxicity testing capacity to extend lead-time advantages over emerging competitors. Deepen backward integration into aluminum-honeycomb core manufacturing to neutralize aerospace-sector competition for lightweight materials. Threat substitution from poured polyurethane flooring specialists like Bolidt demands counterinvestment in seamless resin system capabilities. Capacity addition in Finnish polar-class fabrication clusters captures expedition cruise expansion. For New Entrants and Emerging Players: Mid-life retrofit cycles for Mediterranean and Baltic ferry fleets represent the most penetrable entry point for modular cabin specialists without German shipyard captive relationships. Scandinavian Ro-Pax operators seeking demountable interiors for seasonal capacity swings offer second-tier access. Go-to-market execution should target shipyard project management offices directly rather than operator procurement teams, leveraging EU Green Deal ship recycling mandates as conversation entry point. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated module deliverers with captive HVAC and insulation bundling capabilities over standalone component specialists. Long-term viability across the five-to-ten year window hinges on regulatory entrenchment deepening through IMO carbon-intensity regulations. Acquisition target archetype: turnkey cabin providers with established Lloyd's Register and DNV certification pipelines. Signal to watch: framework agreement renewal timing at Royal Caribbean and Carnival as indicator of procurement consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum-Honeycomb Core | Neutralizes aerospace competition and stabilizes input costs for German fabricators supplying Meyer Werft. |
| Digital Twin Integration with BIM Modeling | Reduces shipyard rework for ALMACO and Kaefer by enabling virtual fit-checking before physical production. |
| CO2-Based HVAC System Redesign | Accommodates EU F-Gas Regulation restrictions while reshaping ceiling plenum depths in Finnish newbuild specifications. |
| Demountable Interior System Development | Captures EU Green Deal ship recycling mandate demand for mechanically fastened components in Italian yards. |
| Polar-Class Thermal Package Expansion | Addresses Norwegian expedition cruise operator specifications for Svalbard and Antarctic route expansion. |
Methodological Framework
Initial hypotheses were tested against primary input from shipyard procurement directors, modular cabin manufacturing executives, classification society surveyors, and marine HVAC engineering leads and refined through secondary validation against Lloyd's Register certification databases, DNV technical standards, IMO SOLAS amendment records, and EU F-Gas Regulation implementation guidance. Bottom-up triangulation across shipyard order books and top-down reconciliation against cruise operator fleet expansion announcements anchored volume estimates.
Demand-supply balance framing structured the analytical approach across the analysis window, with segmentation modeled across product type, application vessel class, material composition, and end-user procurement authority. CAGRs were derived from regression analysis of historical shipyard output against projected newbuild and retrofit cycle timing. Industry-specific forecast inputs incorporated aluminum-honeycomb aerospace demand competition and IMO carbon-intensity regulation implementation trajectories.
Practitioners should monitor SOLAS amendment schedules, EU Green Deal ship recycling rule finalization, and aerospace sector aluminum-honeycomb demand spikes for early signals requiring forecast reassessment. Material shifts in regulatory certification timelines or raw material allocation priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Japan Marine Composites Market
Marine
Marine Transport Refrigeration Unit Market
Marine
Marine Asset Integrity Services Market
Marine
Marine Engine Cooling Systems Market
Marine
Marine Fin Stabilizer Market
Marine
Marine Pipes Market
Marine
Marine Chartplotter Market
Marine
Marine Turbocharger Market
Marine
Marine Shackle Market
Marine
Passenger Vessel Propeller Market
Marine
Submarine Propulsion Systems Market
Marine
Marine Big Data Market
Marine
Marine Lighting Market
Marine
US Fish Finders Market
Marine
Marine LED Lights Market
Marine
Marine Fuel Injector Market