
 Automotive Door Guards Market | 2026-2036
Automotive Door Guards Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Guards Market Outlook
Aftermarket parts distribution is reshaping how automotive door guards reach end users, with digital platforms and specialized retailers competing for installer loyalty. WeatherTech leverages its direct-to-consumer infrastructure to control pricing and brand positioning across North America. KIRCHHOFF Automotive GmbH anchors European OEM supply through its stamped-metal and composite guard capabilities. Dorman Products, Inc. competes aggressively in the replacement channel with broad SKU coverage and rapid fulfillment.
Automotive door guards are protective strips, moldings, or panels affixed to vehicle door edges to prevent denting, chipping, and corrosion damage from contact with adjacent objects or environmental exposure. Most guards incorporate thermoplastic olefin (TPO), acrylonitrile butadiene styrene (ABS), or aluminum substrates with adhesive backing or mechanical fastening systems, designed to absorb impact energy while maintaining paint compatibility. Metal guards dominate OEM fitment for structural rigidity and crash integration, while adhesive-mount products lead the aftermarket due to consumer-friendly installation without drilling. Composite guards represent the fastest-expanding category as manufacturers blend carbon fiber or glass-reinforced polymers to reduce mass while preserving impact resistance.
NHTSA side-impact standards and ECE R95 regulations govern door structural performance, indirectly elevating guard specifications for energy absorption and pedestrian protection. EPA material restrictions and REACH substance controls constrain adhesive formulations and coating chemistries, pushing suppliers toward water-based and low-VOC alternatives. Stakeholders must monitor evolving collision-test protocols and material compliance deadlines to align R&D pipelines with certification requirements.
Market Dynamics
OEM procurement of integrated door protection systems is compressing aftermarket margins while lightweighting mandates from NHTSA and EU regulators accelerate composite material substitution across guard assemblies.
Growth Catalysts
- EU Pedestrian Safety Directives:ECE R95 protocols mandate enhanced energy absorption at door edges, forcing automakers to upgrade guard specifications across new vehicle platforms.
- Thermoplastic Olefin Formulation Advances:TPO compounds with improved paint compatibility are displacing legacy ABS substrates in premium vehicle fitments.
- German Premium Manufacturing Cluster:BMW, Mercedes-Benz, and Volkswagen procurement specifications for advanced guard assemblies concentrate demand in Stuttgart and Munich supplier networks.
Market Restraints
- Aluminum Sheet Volatility:Metal guard producers face input cost swings from LME aluminum pricing, compressing margin buffers on stamped OEM components.
- REACH Substance Restrictions:ECHA adhesive formulation constraints limit solvent-based bonding chemistries, forcing costly water-based alternative qualification.
- Structural Rigid Panel Substitution:Full aluminum door shells with integrated reinforcement ribs reduce discrete guard attachment points on luxury EV architectures.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for advanced manufacturing create tariff-advantaged export capacity for composite guard producers.
- Direct-to-Consumer Digital Channels:Installer-facing platforms bypass traditional jobber distribution, capturing margin previously lost to wholesale intermediaries.
- Carbon Fiber-Glass Hybrid Convergence:Blended polymer matrices combine impact resistance with mass reduction, opening EV-specific guard specifications previously closed to metals.
Industry Challenges
- Multi-Material Bonding Certification:OEM qualification timelines for adhesive systems spanning TPO, aluminum, and carbon fiber substrates extend 18-24 months.
- Paint Shop Integration Complexity:Guard assemblies must survive e-coat bake cycles without delamination or outgassing, requiring specialized primer development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Guards Market |
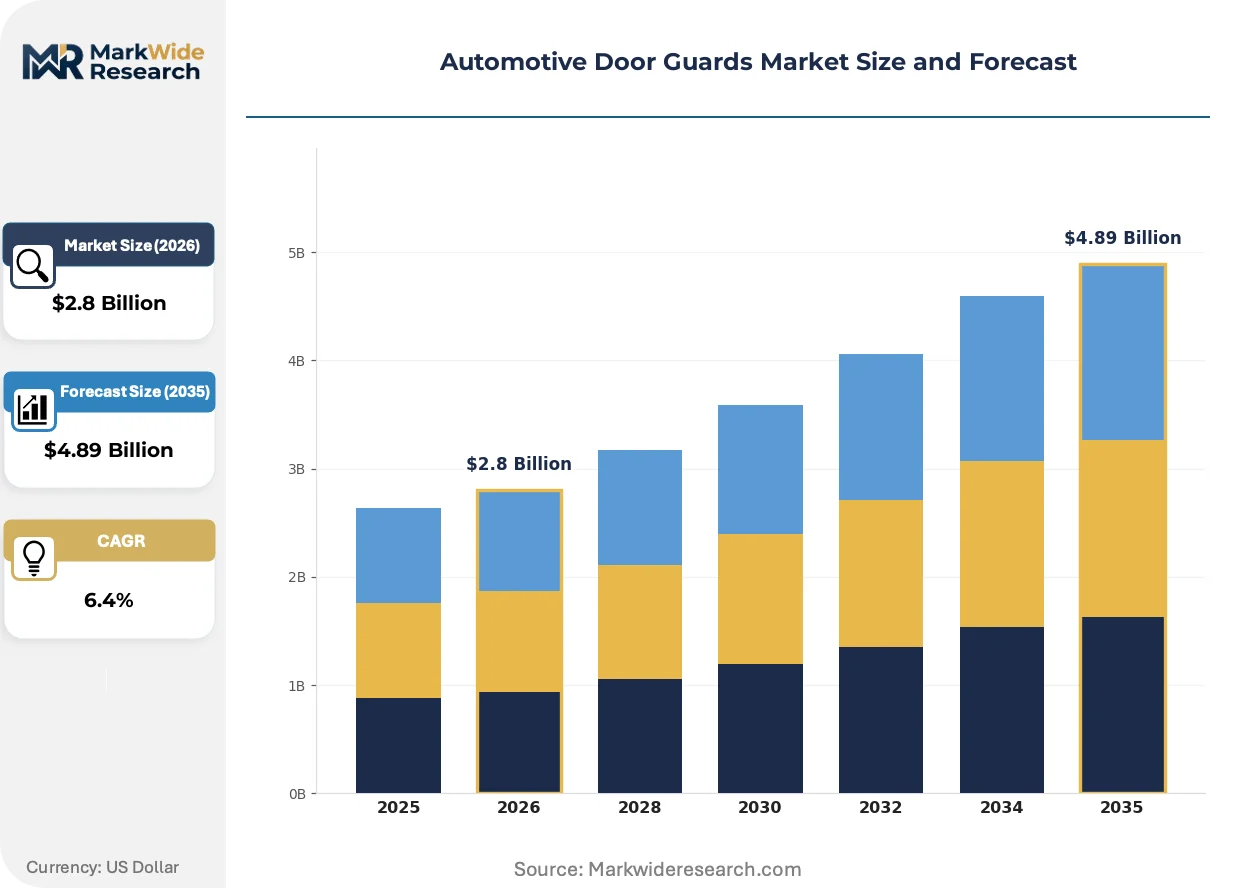
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Guards, Metal Guards, Rubber Guards, Composite Guards End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Installation Type: Adhesive Mount, Drill Mount, Clip-On, Snap-On Distribution Channel: Direct Sales, Online Retail, Automotive Parts Stores, Wholesalers |
| Companies Covered | 3M Company, WeatherTech, Auto Ventshade (AVS), Trim-Lok Inc., Putco Inc., KIRCHHOFF Automotive GmbH, GNS America, BENTELER International, Dorman Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Guards Market Strategic Shifts
Material science breakthroughs and regulatory convergence are restructuring how door protection systems integrate with vehicle architectures rather than attaching as discrete accessories.
Glass-reinforced polymer composites are hybridizing traditional metal guard construction by embedding continuous fiber mats within injection-molded TPO carriers. Tier-1 suppliers serving German OEMs have accelerated adoption to meet 2025 lightweighting targets. This hybridization is compressing pure aluminum guard share in C-segment and above vehicle categories.
REACH Annex XVII restrictions on phthalate plasticizers and isocyanate-based adhesives are forcing reformulation of guard mounting systems across European supply chains. Water-based acrylic and UV-cure alternatives now dominate new product development pipelines. Aftermarket adhesive-mount guard producers face compressed compliance windows as ECHA substance evaluation timelines accelerate.
Fleet procurement centralization among ride-hail operators and commercial leasing companies is consolidating guard specification authority away from individual vehicle owners. Bulk purchasing agreements with direct-installer networks displace traditional retail auto parts channels. This concentration is most visible in US metropolitan markets where Uber and Lyft vehicle supply contracts specify standardized protection packages.
Automotive Door Guards Market Segmentation
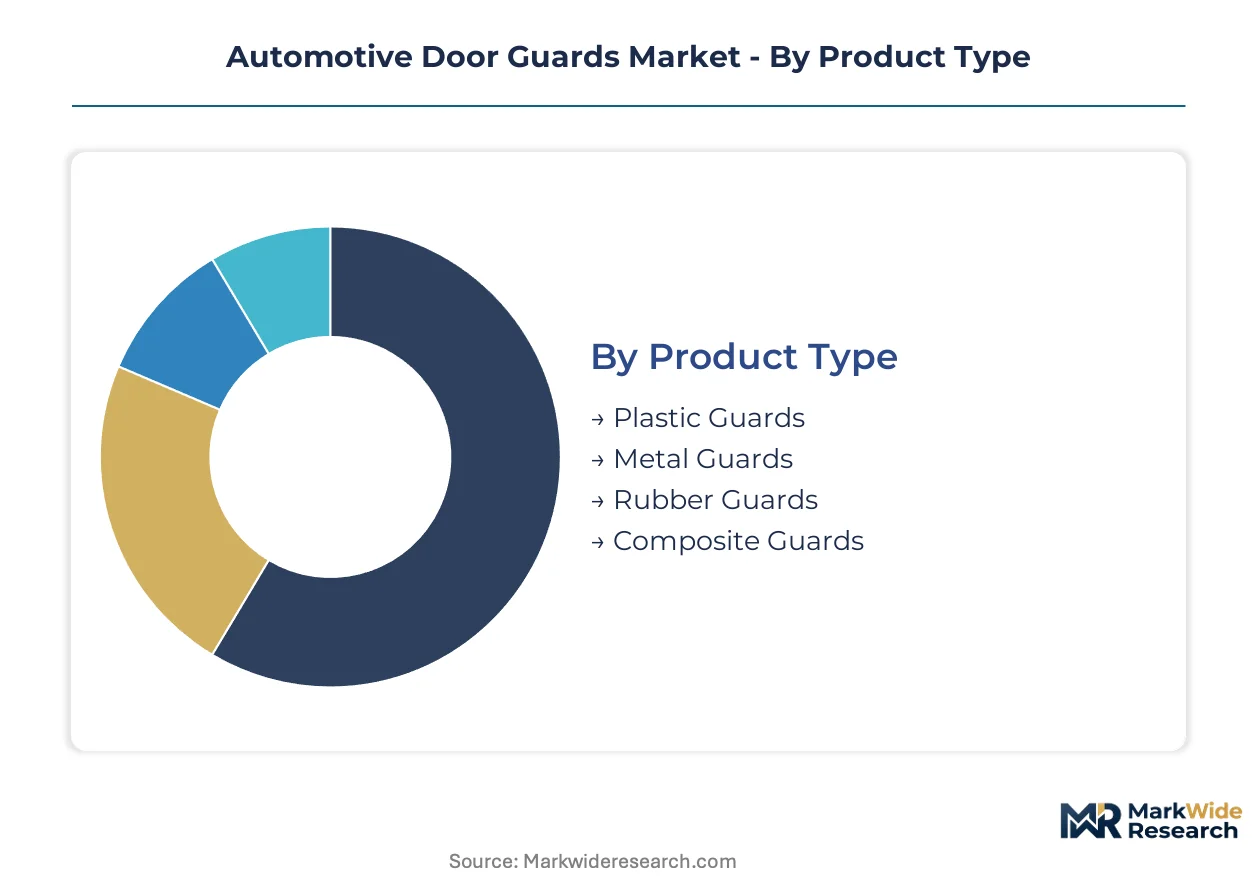
Automotive door guard segmentation reveals how material selection, procurement authority, and installation complexity fragment commercial opportunity across distinct value pools. Each dimension carries different margin profiles, technical qualification barriers, and channel control dynamics that shape supplier positioning.
Product Type:
After-sales service intensity varies sharply across material categories, with metal and composite guards demanding specialized collision-repair integration while plastic alternatives support rapid field replacement.
- Metal Guards:Stamped aluminum or steel substrates deliver structural rigidity for OEM crash integration and pedestrian energy absorption. German premium manufacturers specify these for ECE R95 compliance on luxury platforms, though aluminum LME volatility squeezes supplier margins.
- Composite Guards:Glass-reinforced polymer and carbon-fiber hybrid matrices reduce mass while preserving impact resistance. EV architectures in Stuttgart and Munich supplier networks are accelerating adoption for lightweighting targets, opening specifications previously closed to pure metal construction.
- Plastic Guards:TPO and ABS formulations dominate aftermarket adhesive-mount applications due to paint compatibility and consumer-friendly installation.
- Rubber Guards:EPDM and thermoplastic elastomer strips serve cost-sensitive fleet specifications and commercial vehicle protection.
By volume, plastic guards lead. By growth pace, composite guards are expanding most quickly.
End User:
Cost tier stratification separates integrated OEM supply from fragmented aftermarket procurement, with fleet centralization emerging as a distinct volume concentration mechanism.
- OEMs:Tier-1 direct supply relationships require 18-24 month qualification timelines for multi-material bonding systems and e-coat bake survivability. NHTSA side-impact and EU pedestrian safety mandates elevate guard specifications to structural performance standards.
- Fleet Operators:Ride-hail and commercial leasing procurement centralization displaces individual owner decision-making. Uber and Lyft vehicle supply contracts in US metropolitan markets specify standardized protection packages, consolidating specification authority with fleet managers.
- Aftermarket Providers:Independent installers and mobile service networks compete on speed and convenience for consumer replacement demand.
- Dealerships:Franchise service departments capture warranty-related guard replacement and upsell protection packages on new vehicle deliveries.
By revenue contribution, OEMs dominate. By margin expansion, fleet operators are gaining share fastest.
Installation Type:
Application complexity determines whether guard fitment remains a DIY consumer activity or requires professional technician intervention with specialized tooling.
- Adhesive Mount:Pressure-sensitive backing systems eliminate drilling and support consumer self-installation. REACH Annex XVII restrictions on solvent-based adhesives are forcing water-based acrylic and UV-cure reformulation across European supply chains.
- Drill Mount:Mechanical fastening provides permanent attachment for commercial and heavy-duty applications where adhesive shear strength proves insufficient.
- Clip-On:Factory-style attachment points enable dealer technician installation without paint damage.
- Snap-On:Tool-free engagement suits temporary protection and rental fleet turnover applications.
By unit volume, adhesive mount leads. By technical differentiation, drill mount commands premium positioning.
Distribution Channel:
Customer type fragmentation splits between institutional procurement through direct sales and fragmented consumer access via digital platforms and retail counter presence.
- Direct Sales:Tier-1 supplier OEM contracts and fleet purchasing agreements bypass intermediaries, capturing margin otherwise lost to distribution layers. WeatherWeatherTech's direct-to-consumer infrastructure exemplifies this control in North America.
- Online Retail:Digital platforms enable installer-facing procurement with rapid fulfillment and SKU breadth. Dorman Products competes aggressively through this channel with broad catalog coverage.
- Automotive Parts Stores:Counter presence and same-day availability serve emergency replacement and professional installer demand.
- Wholesalers:Traditional jobber networks face compression as digital channels disintermediate inventory holding and credit extension functions.
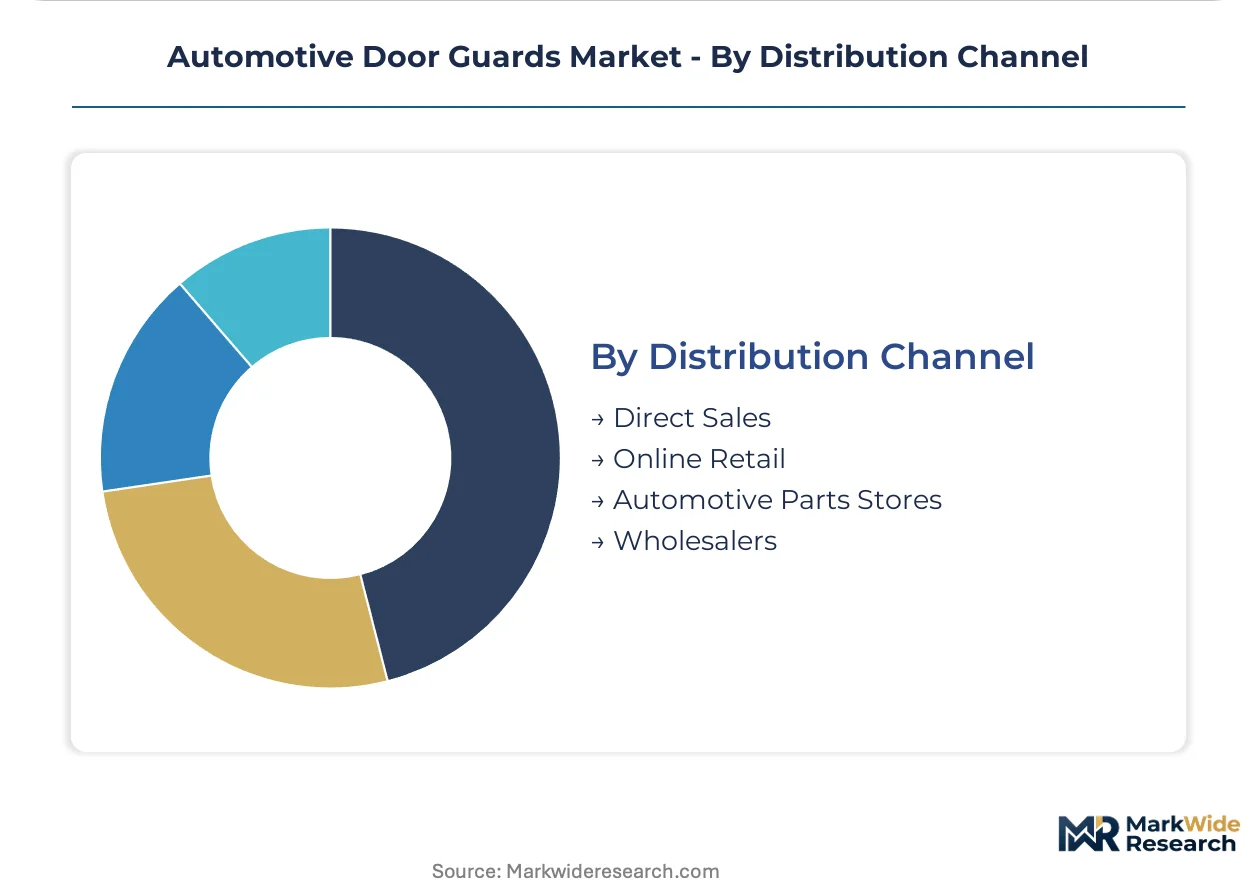
By transaction volume, online retail is climbing the fastest. By absolute value, direct sales maintains dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European automotive component logistics, channeling stamped-metal and composite guard assemblies into Stuttgart and Munich manufacturing clusters. This maritime infrastructure underwrites Germany's concentration of premium OEM procurement.
United States
Ride-hail fleet centralization in metropolitan markets concentrates guard specification authority with Uber and Lyft procurement teams. NHTSA side-impact protocols mandate enhanced energy absorption standards that elevate guard performance requirements. Detroit-area Tier-1 suppliers integrate these specifications into domestic light-truck and SUV platforms.
Germany
BMW, Mercedes-Benz, and Volkswagen procurement networks drive demand for advanced guard assemblies meeting ECE R95 pedestrian safety mandates. REACH Annex XVII restrictions on phthalate plasticizers force adhesive reformulation across Stuttgart supplier networks. Munich-area composite specialists accelerate glass-reinforced polymer adoption for EV lightweighting targets.
China
Dual carbon goals from MEE accelerate carbon fiber-glass hybrid substitution in domestic EV architectures. GB standards for side-impact protection elevate guard specifications for local manufacturers. Yangtze River Delta stamping clusters adapt capacity toward composite guard production for NIO, BYD, and Xpeng supply chains.
India
PLI scheme incentives for advanced auto components attract composite guard manufacturing investment toward Tamil Nadu and Gujarat. BIS certification requirements for automotive adhesives constrain formulation choices for domestic producers. Pune supplier networks expand capacity to serve Maruti Suzuki and Tata Motors procurement.
Japan
METI carbon-neutrality roadmaps pressure domestic OEMs toward mass-reduction in door assemblies. JIS standards for pedestrian impact protection align with ECE R95 equivalency. Nagoya-area Tier-1 suppliers integrate hybrid polymer guards into Toyota and Honda platform designs.
Automotive Door Guards Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying stamped substrates, adhesive systems, and fastening hardware. The market exhibits moderate consolidation, with a handful of full-service Tier-1 suppliers controlling OEM direct contracts while dozens of regional fabricators populate aftermarket channels. Three archetypes dominate: vertically integrated metal stampers serving premium German OEMs; direct-to-consumer specialists with owned distribution infrastructure; and catalog-broad replacement-channel competitors. Capacity expansion and multi-material bonding certification represent the primary competitive vectors.
Within the vertically integrated stamping tier, KIRCHHOFF Automotive GmbH and BENTELER International occupy positions anchored to German premium OEM supply chains. WeatherTech exemplifies the direct-to-consumer archetype through its North American infrastructure control. Dorman Products, Inc. represents the replacement-channel specialist model with broad SKU coverage.
| Leading Market Players |
|---|
| 3M Company |
| WeatherTech |
| Auto Ventshade (AVS) |
| Trim-Lok Inc. |
| Putco Inc. |
| KIRCHHOFF Automotive GmbH |
| GNS America |
| BENTELER International |
| Dorman Products, Inc. |
| Others |
Value Chain & Pricing Dynamics
Aluminum sheet concentration in Yangtze River Delta stamping clusters concentrates upstream cost leverage among Chinese semi-finished suppliers, pushing margin compression downstream onto German Tier-1 guard assemblers and North American aftermarket distributors. This geographic asymmetry in raw material control shapes where pricing power accrues across the value chain.
Pricing Analysis
Volume-discount tiering structures separate OEM direct contracts from fragmented aftermarket procurement, with fleet purchasing agreements occupying a negotiated middle tier. OEM qualification requirements and 18-24 month bonding certification timelines create price differentiation between certified and uncertified guard assemblies. Pricing pressure stems from aluminum LME volatility compressing margin buffers on stamped metal components. Aftermarket adhesive-mount segments exhibit highest price sensitivity due to consumer DIY substitution elasticity, while OEM direct contracts show lowest sensitivity given crash-integration mandates.
Supply Chain Analysis
Export-control regimes on carbon fiber precursor technologies limit composite guard production expansion outside authorized manufacturing jurisdictions, constraining supply elasticity for EV lightweighting specifications. Guard assembly draws from aluminum sheet mills in China, polymer compounders in Germany, and adhesive formulators in the United States. Single-source vulnerability concentrates in specialized e-coat bake-compatible primer systems qualifying for OEM paint shop integration. Distribution runs through direct Tier-1 OEM contracts, fleet purchasing agreements, and digital installer-facing platforms competing with traditional jobber networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive door guards are shifting toward platform-economics logic as fleet procurement centralization and multi-material bonding certification create winner-take-most dynamics around integrated supply relationships rather than discrete component sales.
For Market Incumbents: Insulate OEM direct relationships through captive investment in carbon fiber-glass hybrid molding capacity serving Stuttgart and Munich EV architectures. Deepen backward integration into specialized primer development for e-coat bake survivability to extend qualification timelines that lock out substitute adhesive suppliers. Threat substitution from full aluminum door shells with integrated reinforcement ribs demands structural response through composite guard performance differentiation. For New Entrants and Emerging Players: Establish a beachhead in India PLI-incentivized composite guard manufacturing for export-advantaged supply into European aftermarket channels. Fleet operator procurement centralization in US metropolitan markets offers the most penetrable entry vector through standardized protection package specifications. Go-to-market execution should prioritize direct-installer digital platforms bypassing wholesale jobber intermediaries. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap composite specialists with active OEM qualification pipelines and captive polymer compounding capabilities. Long-term viability across the analysis window hinges on positioning for EV platform standardization waves rather than legacy ICE vehicle replacement cycles. Watch for inflection signals in OEM composite guard specification share displacing aluminum on C-segment and above vehicle categories.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Capacity Expansion | Glass-reinforced polymer investment secures EV lightweighting specifications from BMW and Mercedes-Benz procurement. |
| Multi-Material Bonding Certification | Adhesive system qualification spanning TPO, aluminum, and carbon fiber substrates locks in 18-24 month OEM exclusivity. |
| Direct-to-Consumer Channel Control | Owned digital infrastructure captures margin otherwise lost to wholesale jobber networks in North American aftermarket. |
| Fleet Procurement Partnership | Standardized protection packages with Uber and Lyft consolidate specification authority away from fragmented retail channels. |
| Water-Based Adhesive Reformulation | REACH Annex XVII compliance for phthalate-free bonding chemistries maintains European market access against regulatory deadlines. |
Study Parameters
Desk research of vehicle production databases, IHS Markit registration data, and customs trade flows preceded structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, and dealership operations managers. Secondary validation drew from NHTSA side-impact protocol filings, ECE R95 regulatory submissions, and REACH Annex XVII substance restriction updates. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators to ensure convergence.
Assumption sets held aluminum pricing volatility and regulatory compliance timelines fixed while varying EV penetration rates and fleet procurement centralization speeds across the projection horizon. Segmentation dimensions modeled included vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from slope analysis of normalized adoption curves fitted to historical material substitution patterns in adjacent automotive exterior components.
Stress conditions across aluminum LME price bands, REACH substance evaluation acceleration scenarios, and composite guard specification share displacement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding lightweighting mandate enforcement and paint shop integration qualification timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market