
 North America Automotive Adaptive Lighting System Market | 2026-2036
North America Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Adaptive Lighting System Market Analytics
Matrix LED specification-tier upgrades is redrawing competitive boundaries across the North America Automotive Adaptive Lighting System Market. HELLA KGaA Hueck & Co. leverages its captive chip supply to dominate premium OEM contracts. Valeo Group anchors its position through R&D intensity in dynamic curve algorithms. Koito Manufacturing Co., Ltd. specializes in laser module miniaturization for electric vehicle platforms.
Automotive adaptive lighting systems integrate sensors, control electronics, and variable-beam headlamps that adjust intensity and direction based on vehicle speed, steering angle, and ambient conditions, typically operating within 4500-6500 Kelvin color temperature ranges for optimal roadway illumination. These systems primarily enhance nighttime driving safety while reducing glare for oncoming traffic. Matrix LED technology leads product type deployments due to its pixel-level beam control and declining semiconductor costs. Adaptive front lighting technology captures the largest technology share, though night vision integration represents the fastest-growing segment as thermal imaging costs fall. OEM end users command the dominant channel, with aftermarket providers gaining traction in legacy vehicle retrofit programs.
NHTSA Federal Motor Vehicle Safety Standard 108 shapes headlamp performance requirements across the United States, while Transport Canada's CMVSS 108 establishes parallel compliance thresholds. The EPA's fuel economy testing protocols indirectly incentivize LED adoption through wattage reduction credits. Stakeholders must monitor pending NHTSA rulemakings on adaptive driving beam legalization, as this regulatory determination will reshape product roadmaps and manufacturing commitments across the continent.
Market Dynamics
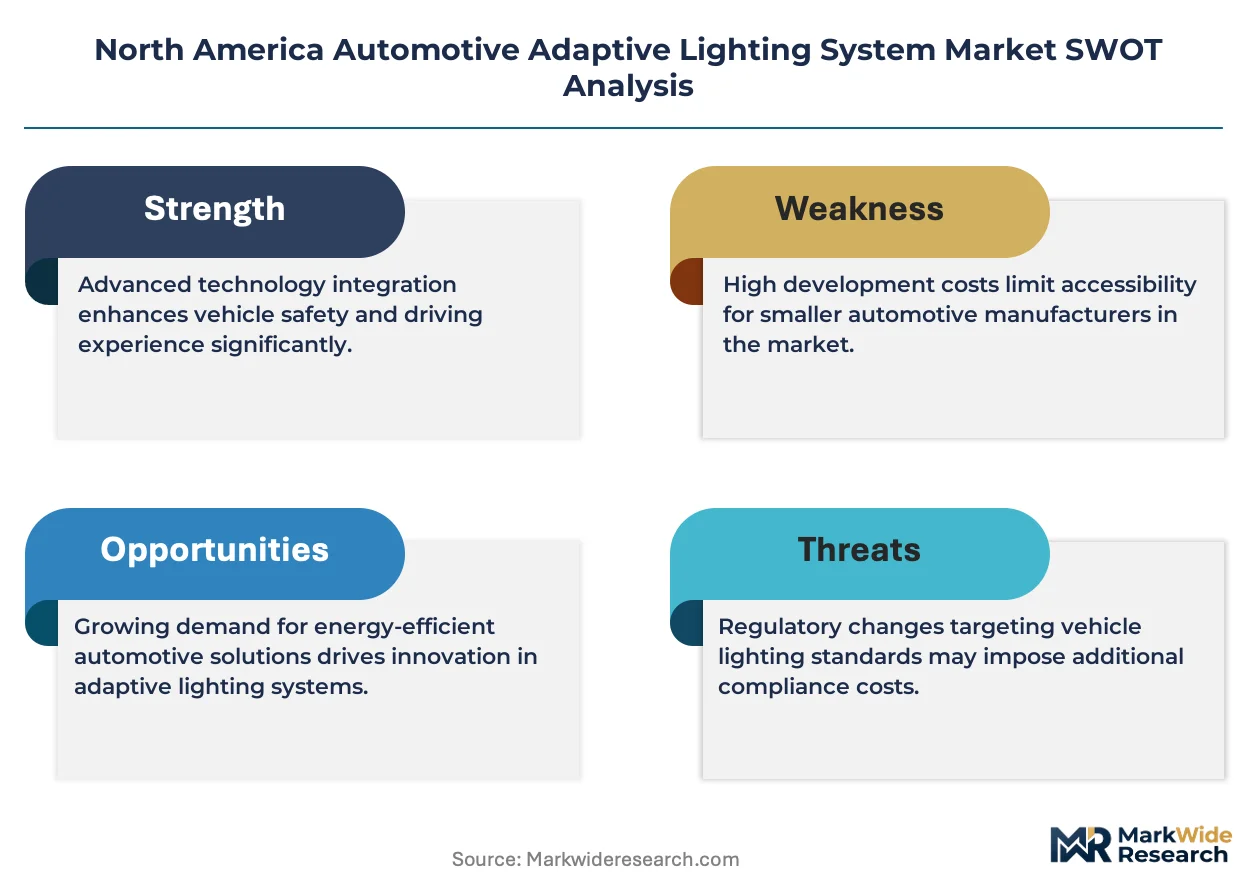
Matrix LED pixel-level beam control is compressing halogen and xenon incumbent positions across vehicle lineups, while NHTSA's pending adaptive driving beam legalization creates manufacturing commitment uncertainty throughout the Great Lakes corridor.
Growth Catalysts
- EPA wattage reduction credits:Fuel economy testing protocols indirectly reward LED adoption, pushing OEMs toward adaptive systems in internal combustion and electric platforms alike.
- Electric vehicle platform proliferation:Michigan and Ontario manufacturers integrate laser module miniaturization into premium EV architectures, creating factory-fit demand for compact adaptive lighting.
- Transport Canada CMVSS 108 alignment:Harmonized compliance thresholds with US standards reduce certification friction for cross-border component sourcing.
Market Restraints
- Semiconductor supply concentration:Captive chip fabrication capacity remains concentrated among tier-one lighting suppliers, constraining second-tier OEM access.
- Legacy vehicle electrical architecture incompatibility:Pre-2018 model year vehicles lack CAN bus bandwidth and power conditioning for retrofit adaptive system integration.
- NHTSA rulemaking timeline opacity:Pending adaptive driving beam legalization delays product roadmap finalization and capital allocation decisions.
Strategic Opportunities
- Night vision integration convergence:Thermal imaging cost compression enables bundled adaptive lighting and pedestrian detection systems in mid-luxury segments.
- Aftermarket retrofit channel expansion:Cleveland-area distributors develop plug-and-play matrix LED upgrade kits for legacy domestic pickup trucks.
- Great Lakes corridor cluster density:Proximity of Detroit, Windsor, and Cleveland testing facilities accelerates validation cycles for new beam pattern algorithms.
Industry Challenges
- Embedded software talent scarcity:Dynamic curve algorithm development requires specialized automotive lighting control engineers concentrated among a handful of suppliers.
- Photometric certification timeline compression:NHTSA and Transport Canada parallel testing requirements extend homologation schedules for multi-market product launches.
- Thermal management integration complexity:High-output LED and laser modules demand sophisticated cooling architectures that conflict with aerodynamic packaging constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Adaptive Lighting System Market |
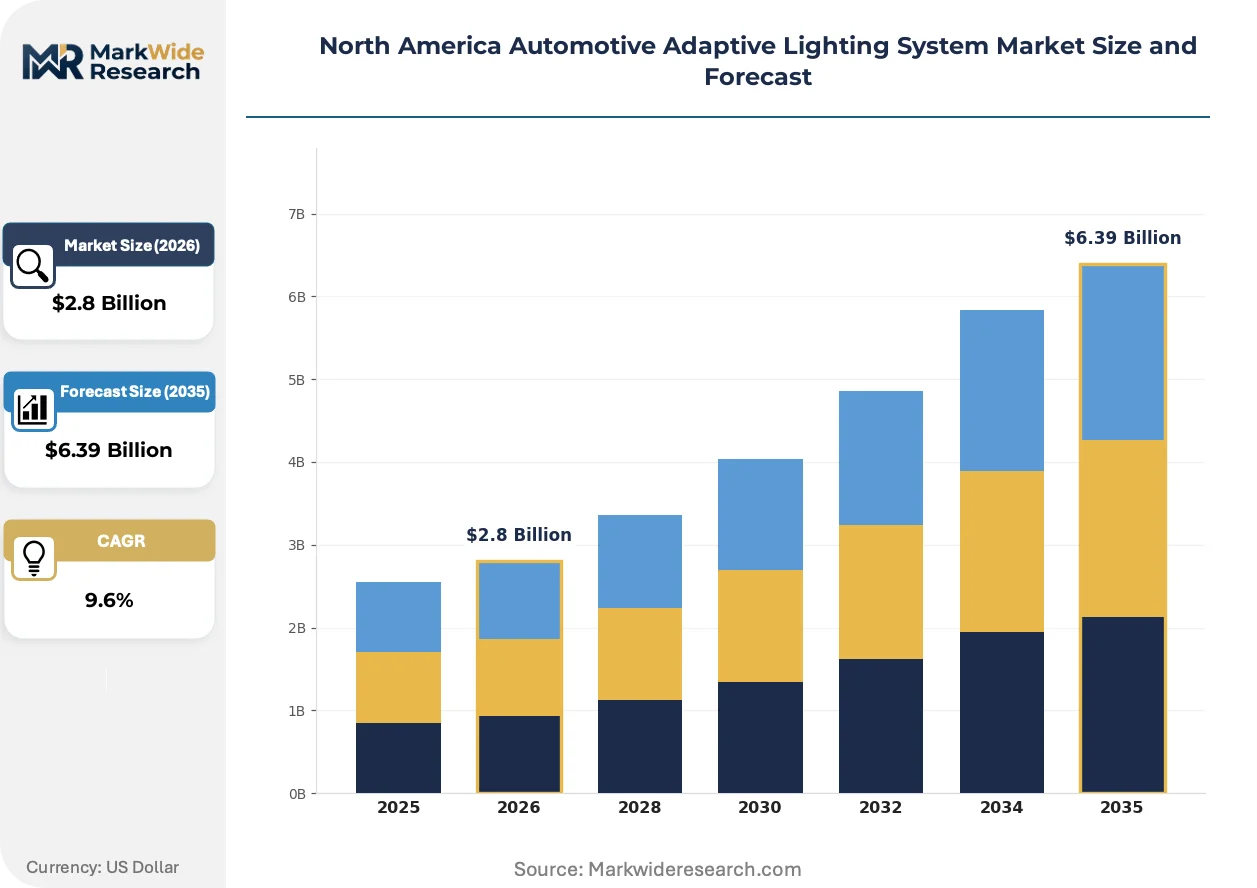
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matrix LED, Laser, Xenon, Halogen Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Electric Vehicles Technology: Adaptive Front Lighting, Dynamic Curve Light, Automatic High Beam, Night Vision End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Automotive Retailers |
| Companies Covered | HELLA KGaA Hueck & Co., Valeo Group, Stanley Electric, Koito Manufacturing Co., Ltd., Koninklijke Philips N.V., OsRam Licht AG, Hyundai Mobis, Texas Instruments, Magneti Marelli SpA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Adaptive Lighting System Market Evolving Landscape
Digital light processing is eroding mechanical actuator dominance in beam steering, while regulatory harmonization pressures and buyer preference for bundled safety systems reconfigure supplier-OEM relationships.
Micro-LED array technology enables 10,000+ individually addressable pixels per headlamp unit, delivering precision glare-free high beam operation. Premium passenger vehicle manufacturers in Ontario and Michigan are adopting this architecture for 2027 model year launches. Conventional mechanical swiveling headlamp designs are displacing fixed-beam configurations across luxury and near-luxury segments, compressing incumbent supplier margins.
NHTSA Federal Motor Vehicle Safety Standard 108 amendments under review would legalize adaptive driving beam functionality previously restricted to European and Asian markets. This regulatory shift would unlock full matrix LED capability for US-bound vehicles, altering competitive positioning among lighting system architects. Canadian regulators at Transport Canada typically harmonize with NHTSA determinations within 12-18 months, creating coordinated market access.
Fleet procurement managers now specify adaptive lighting as standard equipment rather than optional content, collapsing the traditional premium-mid-economy equipment hierarchy. Tier-one OEMs are responding with scalable platform architectures spanning multiple vehicle classes. This specification elevation is most pronounced in corporate fleet acquisitions concentrated in the US Southeast and Texas metropolitan markets.
North America Automotive Adaptive Lighting System Market Segmentation
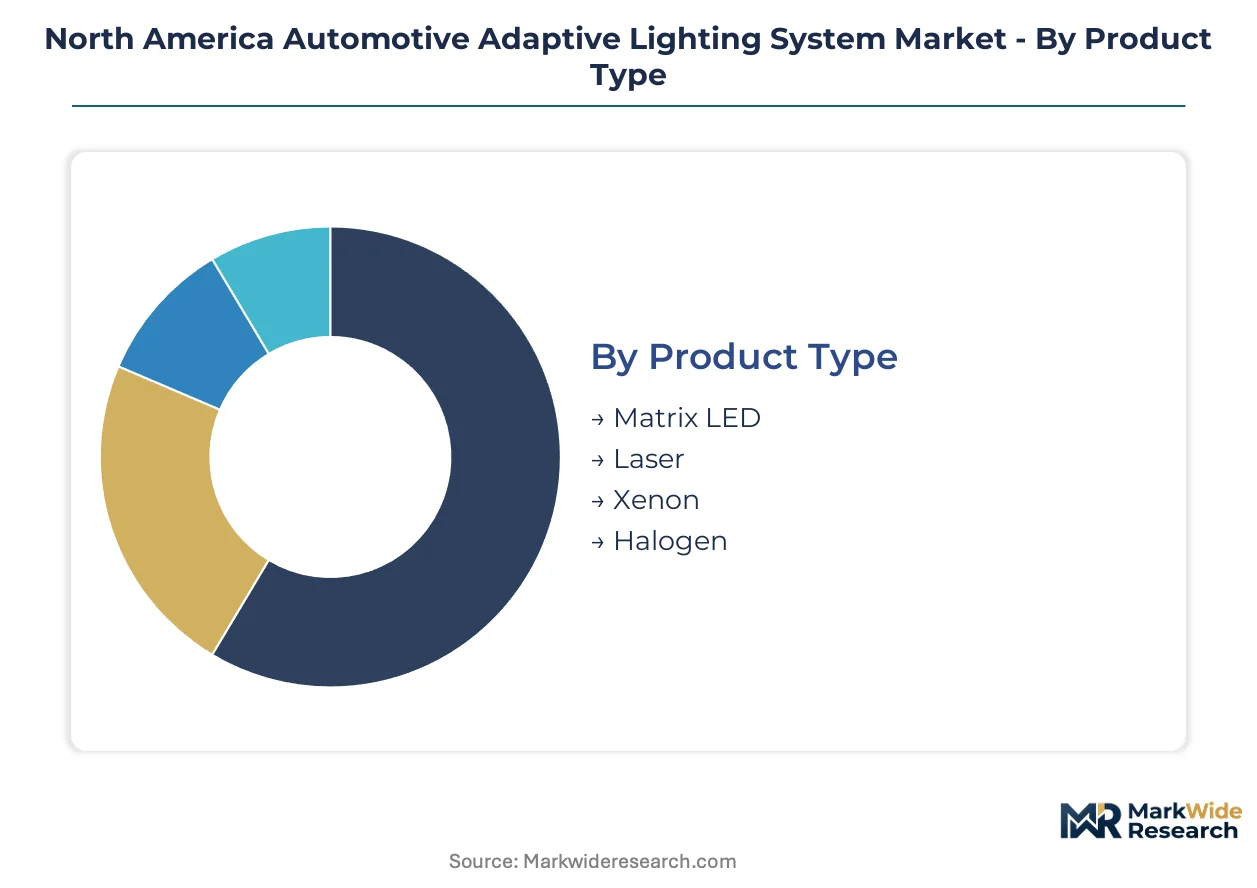
Segmentation in the North America Automotive Adaptive Lighting System Market reveals how regulatory thresholds and platform electrification reshape procurement patterns across distinct technology tiers. Manufacturers calibrate specification investments against NHTSA certification timelines and EPA fuel economy credit structures.
Product Type:
NHTSA Federal Motor Vehicle Safety Standard 108 amendments differentiate which beam control architectures gain US market access, compressing legacy technology windows while accelerating LED and laser module qualification.
- Matrix LED:Pixel-level beam control enables glare-free high beam operation through individually addressable semiconductor elements. Michigan and Ontario luxury OEMs concentrate factory-fit demand here as semiconductor cost curves improve manufacturing economics.
- Laser:Miniaturized diode architectures deliver extended throw distances in compact form factors optimized for electric vehicle front-end packaging constraints. Koito Manufacturing's captive chip supply secures tier-one positioning for premium EV platforms.
- Xenon:High-intensity discharge technology retains aftermarket retrofit relevance for legacy domestic pickup trucks in Cleveland-area distribution channels.
- Halogen:Incandescent filament designs persist in entry-level fleet configurations where cost minimization overrides adaptive functionality requirements.
Matrix LED handles the majority of throughput; laser is the fastest mover on share.
Application:
Platform electrification intensity across vehicle categories determines adaptive lighting specification depth and thermal management integration complexity.
- Passenger Vehicles:Luxury and near-luxury segments in the Great Lakes corridor drive matrix LED standardization as fleet procurement managers collapse optional equipment hierarchies.
- Electric Vehicles:Aerodynamic packaging constraints and wattage reduction credit optimization accelerate laser module adoption for extended-range premium architectures.
- Commercial Vehicles:Long-haul trucking operators in Texas metropolitan markets specify adaptive curve lighting for nighttime highway safety compliance.
- Off-Road Vehicles:Recreational and agricultural equipment manufacturers integrate basic automatic high beam functionality for unlit rural operation.
Passenger vehicles anchor volume commitments; electric vehicles are expanding most quickly on specification penetration.
Technology:
Software-defined beam control algorithms now differentiate supplier competitiveness more than mechanical actuator precision.
- Adaptive Front Lighting:Sensor-fused headlamp swiveling based on steering angle and vehicle speed captures the dominant technology share across US and Canadian OEM platforms.
- Night Vision:Thermal imaging convergence with adaptive beam patterns enables pedestrian detection integration in mid-luxury segments as sensor costs compress.
- Dynamic Curve Light:Predictive beam trajectory algorithms require specialized automotive lighting control engineering talent concentrated among HELLA and Valeo development centers.
- Automatic High Beam:Camera-based oncoming vehicle detection represents the baseline specification tier for standard equipment mandates.
Adaptive front lighting manages the bulk of installed base; night vision is climbing the fastest on bundled safety system demand.
End User:
Channel power concentration determines pricing leverage and roadmap influence across the value chain.
- OEMs:Factory-fit specification authority at Detroit, Windsor, and Cleveland manufacturing plants drives volume commitments and validation cycle acceleration.
- Tier-1 Suppliers:HELLA, Valeo, and Koito integrate captive semiconductor fabrication with dynamic curve algorithm development to defend premium contract positioning.
- Aftermarket Providers:Cleveland-area distributors develop CAN bus-compatible retrofit kits targeting legacy domestic pickup trucks.
- Automotive Retailers:Dealer network service departments capture maintenance and upgrade revenue from out-of-warranty adaptive system calibration.
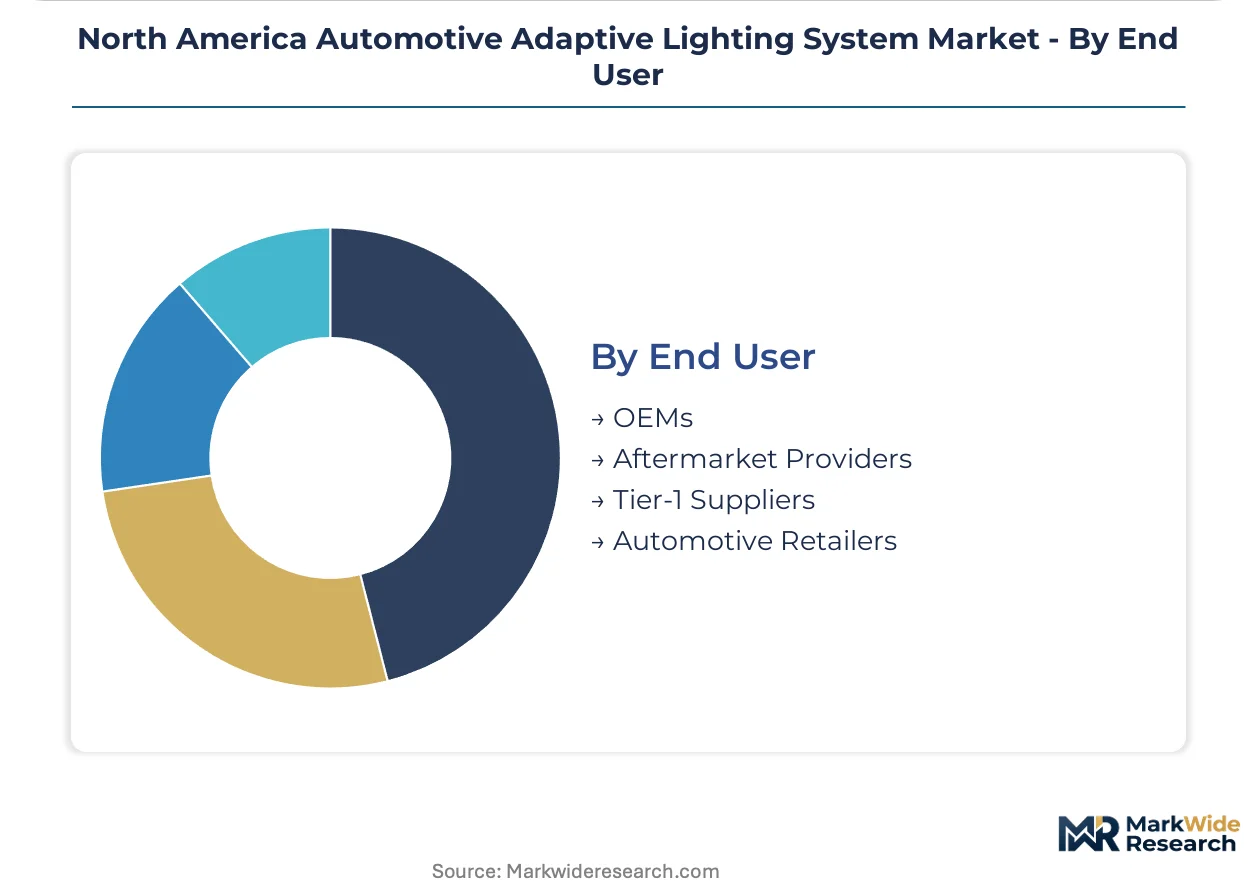
OEMs command the dominant procurement channel; aftermarket providers are gaining traction fastest on legacy fleet retrofit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of semiconductor substrates and optical components concentrate through Great Lakes port infrastructure, while finished adaptive lighting systems move southward to Mexican assembly plants serving US-bound vehicle production.
United States
Michigan and Ohio factory complexes drive matrix LED specification for Detroit Three premium lineups. NHTSA Federal Motor Vehicle Safety Standard 108 amendments under review would legalize adaptive driving beam functionality previously restricted to European markets. Cleveland testing facilities validate beam pattern algorithms for cross-platform deployment.
Canada
Ontario's Windsor corridor hosts concentrated OEM assembly operations sourcing adaptive systems for US-Canada integrated production. Transport Canada's CMVSS 108 typically harmonizes with NHTSA determinations within 12-18 months, reducing certification friction. Toronto-area engineering centers develop thermal management solutions for electric vehicle front-end packaging constraints.
Mexico
Nuevo León and Bajío Region assembly plants integrate adaptive lighting modules for export to US market vehicles. Mexico's automotive manufacturing incentives attract tier-one supplier co-location for just-in-sequence delivery. Querétaro precision manufacturing clusters produce optical components for North American lighting system integrators.
North America Automotive Adaptive Lighting System Market Competitive Landscape
Listed leaders compete with private specialists across semiconductor supply and algorithm development dimensions. The supplier base consolidates around captive chip fabrication capabilities and dynamic curve software competencies. Three archetypes dominate: integrated semiconductor-lighting houses, algorithm-specialized tier-ones, and component-focused technology licensors. Capacity expansion and strategic partnerships constitute the primary competitive moves as NHTSA rulemaking timelines create planning uncertainty.
Within the integrated semiconductor tier, HELLA KGaA Hueck & Co. and Koito Manufacturing Co., Ltd. occupy positions defined by captive supply chain control. Valeo Group exemplifies the algorithm-specialized archetype through its development center concentration. These three entities anchor competitive positioning across premium OEM contract negotiations in the Great Lakes corridor.
| Leading Market Players |
|---|
| HELLA KGaA Hueck & Co. |
| Valeo Group |
| Stanley Electric |
| Koito Manufacturing Co., Ltd. |
| Koninklijke Philips N.V. |
| OsRam Licht AG |
| Hyundai Mobis |
| Texas Instruments |
| Magneti Marelli SpA |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts between Detroit Three OEMs and tier-one lighting suppliers lock in semiconductor substrate access while fixing component pricing visibility across NHTSA certification cycles. These arrangements concentrate procurement leverage among manufacturers with captive chip fabrication, compressing margin flexibility for second-tier suppliers dependent on spot market gallium nitride wafers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the North America Automotive Adaptive Lighting System Market. Pricing stratifies across matrix LED, laser module, and xenon retrofit tiers based on certification grade and volume scale commitments. Cost compression in entry-level halogen replacements is intensifying because EPA wattage reduction credits push fleet procurement toward LED standardization. Fleet procurement managers at commercial vehicle operators exhibit highest price sensitivity, while luxury passenger vehicle platform engineers prioritize performance specifications over unit cost.
Supply Chain Analysis
Taiwaan Strait maritime transit underwrites gallium nitride substrate flows to Michigan and Ontario assembly plants. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with optical component finishing anchored in Mexico's Querétaro precision manufacturing clusters. The supply chain draws from germanium substrates, rare-earth phosphors, and automotive-grade silicon controllers as critical inputs. Single-source vulnerability around captive chip fabrication capacity at HELLA and Koito facilities creates concentration risk. Distribution runs through Great Lakes port infrastructure into just-in-sequence delivery networks serving Detroit, Windsor, and Cleveland manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Automotive Adaptive Lighting System Market is recovering from semiconductor allocation constraints that suppressed factory-fit installations during recent supply shocks. Vehicle production normalization across Michigan and Ontario assembly plants is rebuilding order backlogs for matrix LED and laser module platforms.
For Market Incumbents: Consolidate algorithm development talent pools around dynamic curve lighting and night vision integration competencies to defend against software-defined lighting entrants. Backward integration into thermal management component production secures margin control as LED output densities rise. Capacity reservation agreements with gallium nitride wafer suppliers in Taiwan and South Korea reduce single-source exposure. For New Entrants and Emerging Players: Aftermarket CAN bus retrofit kit development for legacy domestic pickup trucks represents a service-layer gap where incumbents under-serve price-sensitive fleet operators. Cleveland-area distribution channels offer lowest competitive density for plug-and-play matrix LED upgrades. Partner with regional automotive electrical specialists to bypass tier-one supplier certification barriers. For Investors and Strategic Acquirers: Algorithm-specialized tier-one suppliers with captive thermal imaging partnerships present attractive acquisition targets as night vision integration accelerates. Long-term viability hinges on NHTSA adaptive driving beam legalization unlocking full matrix LED functionality for US-bound vehicles. Monitor Transport Canada CMVSS 108 harmonization announcements as inflection indicators for coordinated North American market access.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Supply Agreement | Captive gallium nitride wafer access secures tier-one OEM contract positioning against spot-market competitors. |
| Algorithm Development Partnership | Dynamic curve lighting software co-development with Michigan engineering centers accelerates validation cycles. |
| Retrofit Channel Expansion | Cleveland distributor relationships unlock legacy domestic pickup truck aftermarket demand for matrix LED upgrades. |
| Thermal Management Integration | In-house cooling architecture production resolves packaging conflicts with aerodynamic EV front-end constraints. |
| Night Vision Convergence Program | Thermal imaging bundling with adaptive beams captures mid-luxury segment specification elevation trends. |
Research Methodology
A standing panel of OEM platform engineers, tier-one supplier procurement directors, aftermarket distributors, and NHTSA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA fuel economy certification filings, and Transport Canada CMVSS compliance records. Bottom-up segment sizing triangulated against top-down automotive lighting content-per-vehicle estimates.
Consistency checks against external production forecasts and semiconductor consumption indices validated volume and value outputs across the projection horizon. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster as segmentation dimensions. CAGRs were derived from fitted growth curves applied to technology penetration rates and platform electrification timelines. NHTSA rulemaking status and EPA credit structure adjustments served as scenario-modifying inputs.
Forecasts assume regulatory continuity in NHTSA Federal Motor Vehicle Safety Standard 108 and Transport Canada CMVSS 108 regimes; material policy shifts would require re-modeling of adaptive driving beam legalization timelines. Semiconductor supply concentration, thermal management integration complexity, and embedded software talent scarcity constitute specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as NHTSA rulemaking determinations and EPA protocol amendments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market