
 Global Automotive Safety System Market | 2026-2036
Global Automotive Safety System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Safety System Market Analysis
ASIL-D functional safety certification is unwinding the competitive landscape for Tier-1 suppliers serving premium OEM programs. Autoliv Inc. leverages its airbag and restraint electronics integration to sustain dominance in passive safety architectures. Robert Bosch GmbH anchors active safety revenues through radar and camera fusion platforms. Continental AG competes on sensor-to-brake pipeline latency in emergency braking systems.
Automotive safety systems encompass electronic and electromechanical assemblies engineered to prevent collisions, mitigate occupant injury, and enable post-crash response, typically integrating accelerometers above 100g range, pyrotechnic initiators with sub-millisecond response, and 77GHz radar modules for forward object detection. LiDAR and V2X technology segments command premium positioning as OEMs pursue Level 3 autonomy readiness, while vision systems dominate unit volume through cost-scaled camera-on-chip designs. Passenger cars anchor application demand, though commercial vehicle mandates for automatic emergency braking are accelerating fleet retrofit cycles.
NHTSA, ECE R79, and the EU General Safety Regulation shape product homologation timelines and sensor redundancy requirements across export markets. FMVSS 214 side-impact protocols and UN R135 pole-impact standards force structural redesigns that cascade into airbag and curtain module specifications. Stakeholders must calibrate R&D allocation between regulatory compliance baselines and consumer-facing differentiation in automated collision avoidance.
Market Dynamics
ASIL-D functional safety certification is compressing the supplier base for premium OEM programs, forcing Tier-1 architects to absorb sensor fusion complexity that previously cascaded across multiple vendors. This certification tier now gates access to Level 2+ autonomy contracts.
Growth Catalysts
- Euro NCAP 2026 protocols:The revised assessment framework mandates direct driver monitoring and vulnerable road user detection, forcing airbag and vision system upgrades across vehicle portfolios destined for European type approval.
- Commercial fleet mandates:NHTSA's automatic emergency braking requirement for heavy trucks is accelerating retrofit cycles and expanding addressable unit volume beyond original equipment installation.
- 77GHz radar proliferation:Cost curves for millimeter-wave front-end modules are enabling multi-radar architectures that previously concentrated in luxury segments alone.
Market Restraints
- Semiconductor supply concentration:Advanced driver-assistance SoCs and radar MMICs depend on fabrication nodes concentrated in Taiwan and South Korea, exposing safety system production to single-point geopolitical risk.
- Pyrotechnic initiator input volatility:Zirconium and potassium perchlorate prices fluctuate with defense sector procurement cycles, compressing margin predictability for airbag inflator manufacturers.
- Homologation timeline friction:UN R79 steering system amendments and FMVSS 214 side-impact revisions create overlapping certification windows that delay platform launches by 8-14 months.
Strategic Opportunities
- India fleet modernization:The country's central automotive regulator is phasing in ABS and airbag requirements for commercial vehicles, opening retrofit demand from an installed base exceeding 8 million medium and heavy trucks.
- Camera-LiDAR fusion:Convergence of solid-state ranging with cost-scaled vision systems enables Level 3 highway automation without mechanical scanning complexity, repositioning sensor suite economics.
- Post-crash connectivity:eCall mandates and stolen vehicle tracking requirements are integrating cellular modems with restraint deployment electronics, creating recurring service revenue attachment.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 certified systems architects command premium compensation that Tier-2 suppliers struggle to match, constraining R&D velocity for mid-market participants.
- Legacy platform integration friction:12V electrical architectures in aging vehicle fleets resist the power and data bandwidth demands of fused sensor suites, complicating retrofit packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Safety System Market |
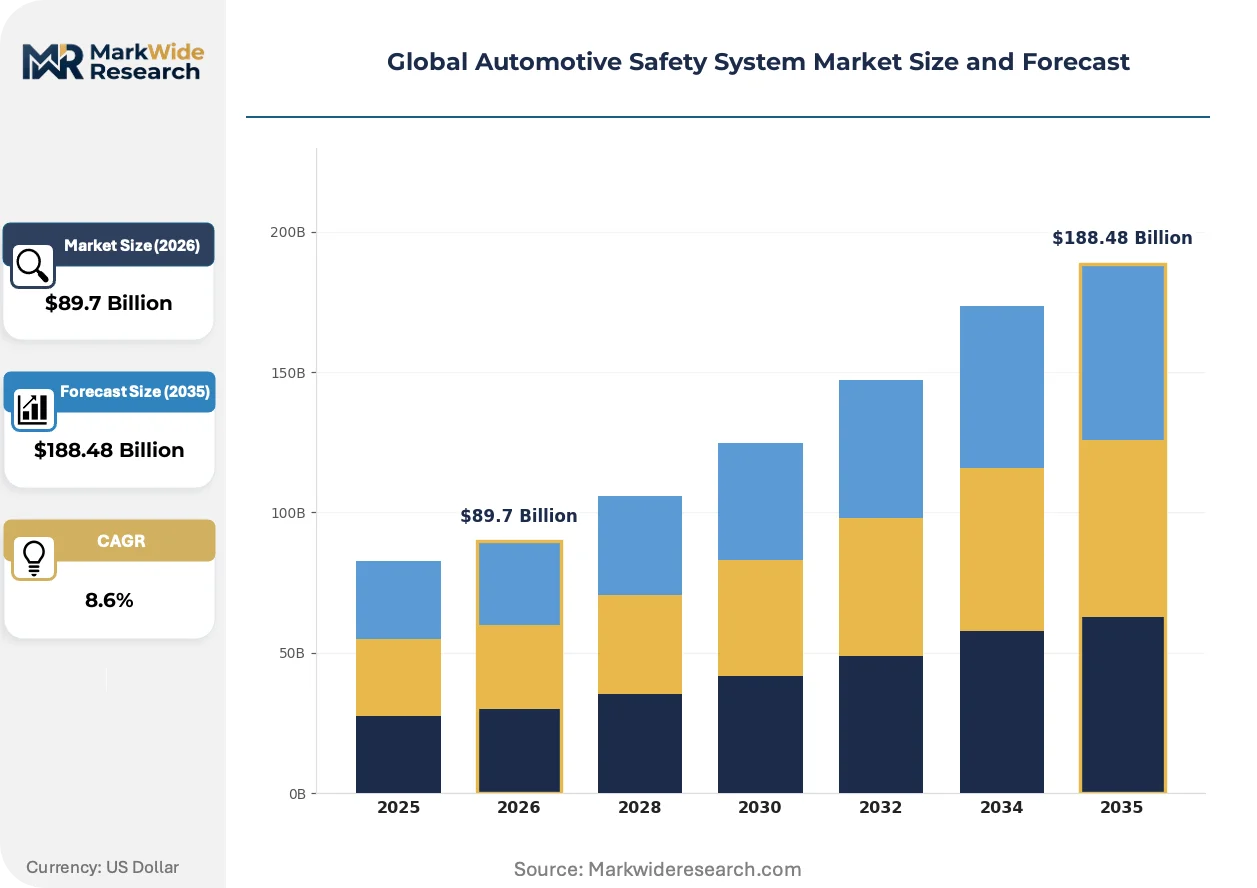
| Market Size in 2026 | $89.7 Billion |
| Market Size in 2035 | $188.48 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airbags, Anti-lock Braking System, Electronic Stability Control, Adaptive Cruise Control Technology: LiDAR, Radar, Vision Systems, Vehicle-to-Everything (V2X) End User: Original Equipment Manufacturers, Aftermarket Providers, Tier-1 Suppliers, Fleet Operators Application: Passenger Cars, Commercial Vehicles, Emergency Vehicles, Two-Wheelers |
| Companies Covered | Autoliv Inc., Magna International Inc., Robert Bosch GmbH, Valeo SA, Aptiv PLC, Continental AG, DENSO Corporation, Mobileye Global Inc., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Safety System Market Emerging Trajectories
Sensor fusion architectures are collapsing discrete electronic control units into domain-consolidated compute platforms, redrawing competitive boundaries between semiconductor suppliers and traditional Tier-1 system integrators.
Occupant classification sensors are miniaturizing from discrete pressure mats to capacitive and ultrasonic elements embedded directly in seat foam structures. Premium OEMs in Germany and Japan are adopting these designs for weight and packaging efficiency. This transition is miniaturizing the physical footprint of restraint decision systems while forcing seat suppliers to absorb electronics competency previously held by safety specialists.
The EU General Safety Regulation mandates intelligent speed assistance and lane-keeping systems as standard equipment from mid-2024, eliminating the option to delete active safety features from base trim configurations. This removes price-based segmentation as a competitive lever and compresses volume concentration among suppliers qualified for high-run economy programs. Southern European markets with older fleet demographics show the steepest compliance-driven replacement cycles.
Fleet operators are unbundling safety system maintenance from comprehensive service contracts, creating direct procurement relationships with component remanufacturers and calibration specialists. This channel disintermediation is most pronounced in North American long-haul trucking, where telematics-enabled predictive maintenance contracts now specify sensor health monitoring as a separate line item. Independent service networks in Ohio, Michigan, and Texas are capturing margin that previously flowed through OEM dealer channels.
Global Automotive Safety System Market Segmentation
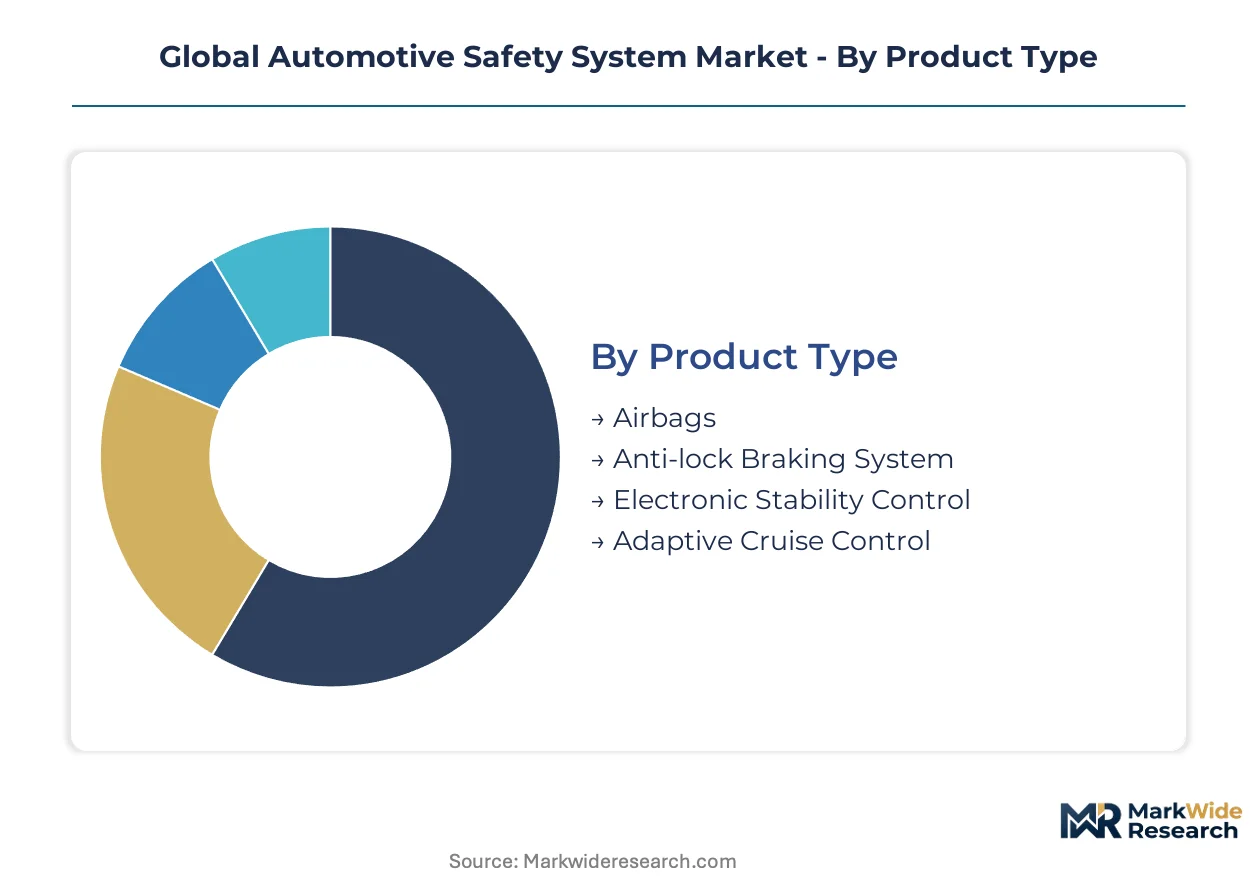
Safety system procurement channels diverge sharply between OEM-integrated architectures and retrofit fleet installations, with technology maturity dictating which segments flow through direct supply agreements versus independent distribution networks. Component qualification tiers—particularly ASIL-D certification—further stratify addressable customer bases across premium and volume vehicle programs.
Product Type:
Channel mix for passive safety components runs predominantly through captive OEM supply agreements, while active systems increasingly penetrate aftermarket retrofit channels as fleet mandates expand compliance-driven replacement cycles.
- Airbags:Pyrotechnic restraint modules integrating multi-stage inflators and seat-occupant classification electronics. Demand concentrates in Germany and Japan where Euro NCAP and JNCAP protocols mandate advanced curtain and knee protection systems, though zirconium supply volatility compresses margin predictability for inflator manufacturers.
- Anti-lock Braking System:Hydraulic modulator assemblies with wheel-speed sensor feedback loops. India's commercial vehicle fleet modernization—covering over 8 million medium and heavy trucks—drives retrofit channel expansion as BIS phased mandates take effect.
- Electronic Stability Control:Yaw-rate and lateral-acceleration sensor fusion modules. Standard fitment in EU and US passenger vehicles leaves growth concentrated in emerging market commercial applications.
- Adaptive Cruise Control:Radar-camera fusion processors with longitudinal vehicle control algorithms. Premium OEM programs in the United States and Germany absorb qualified Tier-1 capacity.
Airbags dominate installed base across all production geographies. Adaptive Cruise Control is where expansion concentrates as Level 2+ autonomy contracts multiply.
Technology:
Cost tier stratification separates mechanical scanning architectures from solid-state designs, with volume-scaled camera-on-chip solutions commanding economy program fitment while ranging sensors concentrate in premium segment development.
- LiDAR:Solid-state and hybrid scanning modules for high-resolution 3D environment mapping. German premium OEMs anchor near-term demand for highway automation readiness, though unit economics resist mass-market penetration.
- Radar:77GHz front-end modules with MIMO antenna configurations. Cost curves enable multi-radar architectures—corner, front, and rear—that previously concentrated in luxury segments alone, expanding addressable volume.
- Vision Systems:CMOS image sensors with embedded neural processing for object classification. Camera-on-chip scaling dominates unit economics across economy and mid-market vehicle programs.
- Vehicle-to-Everything (V2X):DSRC and C-V2X transceivers enabling cooperative perception. Regulatory fragmentation between FCC-mandated spectrum in the United States and ETSI frameworks in Europe complicates single-SKU global deployment.
Vision Systems anchor current production volumes. LiDAR is climbing the fastest as solid-state designs approach cost thresholds for Level 3 highway automation.
End User:
Customer type determines specification authority—OEMs retain architecture control for integrated active-passive suites, while fleet operators increasingly unbundle maintenance procurement from comprehensive service contracts.
- Original Equipment Manufacturers:Vehicle assemblers specifying system-level performance and homologation compliance. German and Japanese OEMs concentrate procurement of ASIL-D certified architectures for premium programs.
- Aftermarket Providers:Independent distributors and installation networks serving regulatory retrofit mandates. India's commercial vehicle ABS and airbag phase-in creates channel expansion.
- Tier-1 Suppliers:System integrators absorbing sensor fusion complexity previously cascaded across multiple vendors. Certification scarcity compresses the qualified supplier base.
- Fleet Operators:Direct procurement relationships with component remanufacturers and calibration specialists. North American long-haul trucking shows pronounced channel disintermediation.
Original Equipment Manufacturers retain volume concentration. Fleet Operators are gaining share fastest as predictive maintenance contracts specify sensor health monitoring separately.
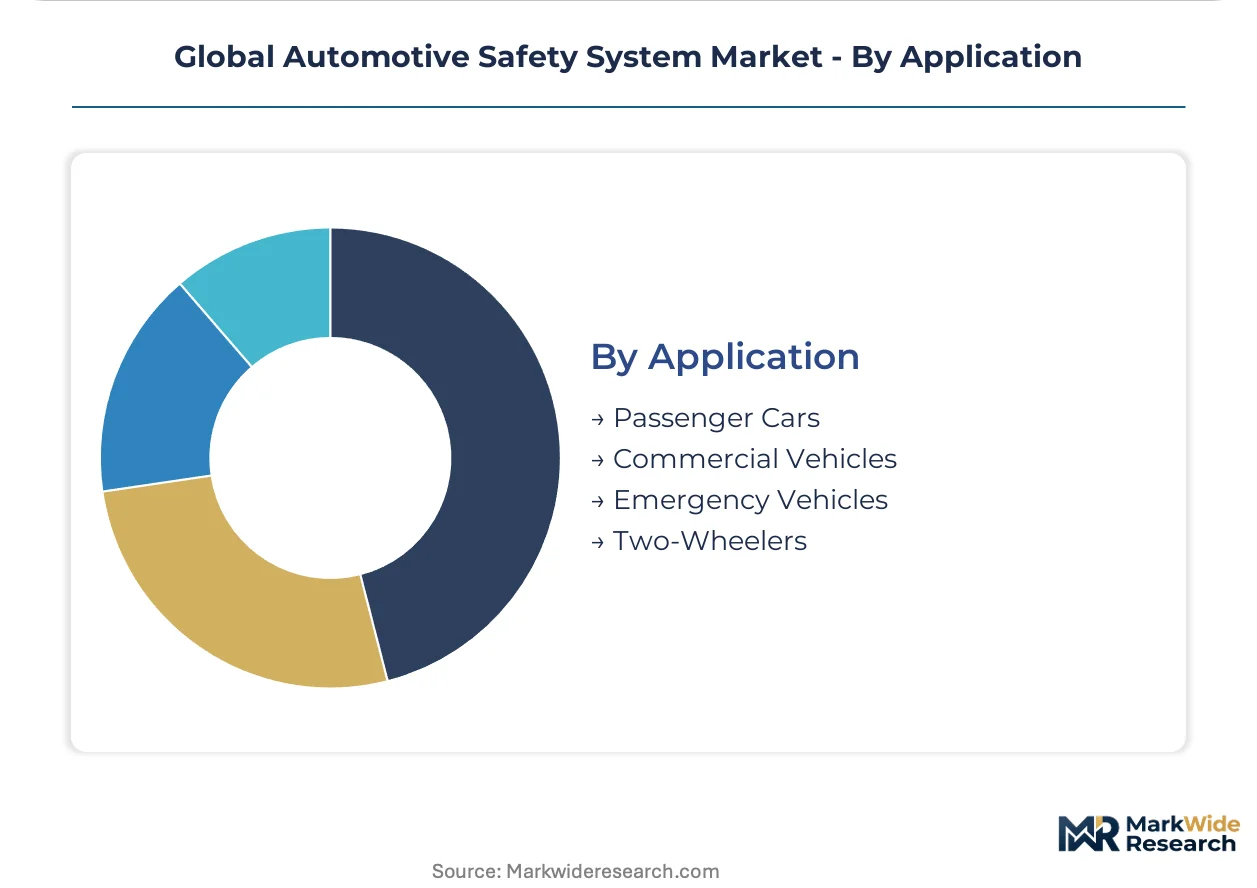
Application:
Application maturity varies by regulatory enforcement intensity—passenger car mandates are largely complete in developed markets, while commercial vehicle requirements are accelerating retrofit cycles.
- Passenger Cars:Multi-airbag configurations and fused active safety suites as standard equipment. EU General Safety Regulation mandates eliminate deletion options from base trim configurations.
- Commercial Vehicles:Automatic emergency braking and stability control for heavy truck fleets. NHTSA mandates accelerate retrofit demand beyond original equipment installation.
- Emergency Vehicles:Specialized lighting integration and collision avoidance for high-speed response operations. Municipal procurement specifications vary by jurisdiction.
- Two-Wheelers:ABS and combined braking system modules for motorcycles and scooters. Cost-scaled sensor implementations target high-volume Asian production.
Passenger Cars anchor revenue concentration. Commercial Vehicles show the steepest expansion trajectory as fleet mandates proliferate across North America and Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a substantial export surplus in automotive safety components, shipping integrated airbag modules and radar systems to assembly plants across Eastern Europe and North America. Import dependency concentrates in specialized semiconductor substrates and pyrotechnic initiator chemicals sourced from Asian suppliers.
United States
NHTSA mandates for automatic emergency braking in heavy trucks drive retrofit demand across the 3.5 million-unit commercial fleet. FMVSS 214 side-impact protocols force structural redesigns that cascade into curtain airbag specifications. Michigan and Ohio host concentrated Tier-1 engineering centers where sensor fusion platforms undergo validation for Detroit Three OEM programs.
Germany
Euro NCAP 2026 assessment frameworks mandate direct driver monitoring and vulnerable road user detection, compelling airbag and vision system upgrades. The EU General Safety Regulation eliminates deletion options for active safety features from base trim configurations. Stuttgart and Munich anchor development of ASIL-D certified architectures for premium OEM programs.
Japan
JNCAP protocols mandate advanced curtain and knee protection systems across domestic vehicle portfolios. METI coordinates standardization of 77GHz radar interfaces to reduce supplier qualification friction. Nagoya and Tokyo metropolitan areas concentrate electronics manufacturing for seat-occupant classification sensors and restraint control modules.
India
BIS phased mandates for ABS and airbag installation in commercial vehicles cover an installed base exceeding 8 million medium and heavy trucks. Central automotive regulator timelines accelerate retrofit channel expansion beyond original equipment installation. Tamil Nadu and Maharashtra host emerging electronics packaging operations serving domestic OEM assembly.
China
GB standards for passenger car safety systems tighten structural and active braking requirements for domestic market type approval. MIIT promotes local sourcing quotas for radar and camera modules in government procurement vehicles. Yangtze River Delta clusters concentrate vision system assembly and testing operations for both domestic OEMs and export programs.
Global Automotive Safety System Market Vendor Landscape
Listed leaders compete with private specialists across certification tier access, with publicly traded Tier-1 suppliers commanding premium valuation multiples against family-owned component fabricators. The supplier base compresses vertically as ASIL-D functional safety certification gates access to Level 2+ autonomy contracts. Three archetypes dominate: integrated passive-active suite architects, sensor fusion platform specialists, and pyrotechnic restraint module fabricators. Capacity consolidation and strategic technology licensing represent the dominant competitive moves reshaping vendor relationships.
Within the integrated suite tier, Autoliv Inc. and Robert Bosch GmbH exemplify divergent strategic positioning—Autoliv anchoring passive safety electronics integration while Bosch represents active safety sensor fusion. Continental AG occupies a position spanning both domains. These three entities illustrate how certification scarcity compresses the qualified supplier base for premium OEM programs.
| Leading Market Players |
|---|
| Autoliv Inc. |
| Magna International Inc. |
| Robert Bosch GmbH |
| Valeo SA |
| Aptiv PLC |
| Continental AG |
| DENSO Corporation |
| Mobileye Global Inc. |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
Solid-state LiDAR substitution for mechanical scanning units is redrawing procurement geography from German precision optics houses toward Asian semiconductor packaging clusters, compressing premium-tier pricing power while elevating volume-scale cost curves for economy programs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with ASIL-D certified Tier-1 suppliers, where pricing stratifies across premium, standard, and economy tiers driven by functional safety certification grade and volume scale commitments. Cost compression in economy radar modules is intensifying because 77GHz MMIC fabrication is migrating to higher-volume nodes. Fleet operators show highest price sensitivity due to unbundled maintenance procurement, while premium German OEMs absorb certification premiums with least negotiation leverage.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for pyrotechnic initiator chemicals sourced from South Korean and Taiwanese specialty chemical producers. Semiconductor substrates draw from Taiwan, South Korea, and Japan, while airbag module assembly concentrates in Germany, Mexico, and China. Single-source vulnerability in 77GHz radar MMIC fabrication exposes safety system production to geopolitical disruption. Distribution runs through captive OEM supply agreements for passive components and independent retrofit networks for active system mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a post-regulatory-mandate cyclical recovery phase justified by Euro NCAP 2026 protocol implementation forcing portfolio-wide safety upgrades across European-bound vehicle production.
For Market Incumbents: Consolidate sensor fusion engineering capacity through selective acquisition of ISO 26262-certified systems architects in Stuttgart and Nagoya engineering corridors, defending against emerging silicon vendors disintermediating discrete ECU tiers. Deepen backward integration into 77GHz radar MMIC design to capture margin migrating from module assembly toward semiconductor content. For New Entrants and Emerging Players: ASIL-D certification fast-track partnerships with German TUV and US-based functional safety consultancies unlock access to Level 2+ autonomy contracts currently gated to three dominant Tier-1 integrators. Target India's commercial vehicle retrofit channel where BIS mandates exceed qualified supplier capacity, deploying camera-on-chip vision systems through aftermarket distributor networks in Tamil Nadu and Maharashtra. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated passive-active suite architects over pure-play sensor specialists. Long-term viability centers on five-to-ten year OEM platform lock-in cycles where ASIL-D qualification creates switching costs. Watch NHTSA rulemaking on heavy-truck automatic emergency braking as the inflection signal for retrofit channel valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Gates access to Level 2+ autonomy contracts with German premium OEMs. |
| Radar-Camera Fusion Platform Development | Absorbs ECU consolidation pressure from semiconductor suppliers. |
| India Commercial Vehicle Retrofit Expansion | Captures BIS-mandated ABS and airbag installation across 8 million trucks. |
| Solid-State LiDAR Cost Curve Engineering | Enables Level 3 highway automation without mechanical scanning complexity. |
| Post-Crash Connectivity Integration | Attaches recurring service revenue to eCall mandate compliance. |
Methodological Framework
The analysis maps active safety sensor fusion, passive restraint electronics, and V2X connectivity modules, each validated through Tier-1 supplier procurement directors, OEM platform engineering leads, and aftermarket distributor operations managers. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS filings, and Euro NCAP assessment protocols. Bottom-up component demand modeling and top-down OEM program aggregation provided triangulation checks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from fitted trend extrapolation moderated by regulatory mandate timing and technology substitution curves. Industry-specific forecast inputs incorporated ASIL certification penetration rates and fleet mandate compliance schedules.
Underlying assumptions cover regulatory enforcement intensity, semiconductor fabrication node availability, and pyrotechnic chemical supply stability, with deviation risk concentrated in geopolitical disruption of Taiwan-based MMIC production and zirconium price volatility from defense sector procurement cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Automotive Active Safety Sensors Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market