
 Europe Refrigerated Container Shipping Market | 2026-2036
Europe Refrigerated Container Shipping Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Refrigerated Container Shipping Market Insights
CE marking under the EU's Marine Equipment Directive is redrawing competitive access for reefer container manufacturers serving European trade lanes. Mediterranean Shipping Company dominates Trans-Atlantic reefer routes through its integrated terminal network at Valencia and Antwerp. A.P. Moller - Maersk anchors its European cold chain position through controlled investments in shore power infrastructure and remote monitoring platforms. CMA CGM Group differentiates via specialized pharmaceutical-grade container fleets that sustain temperature integrity across extended inland rail corridors.
Europe refrigerated container shipping encompasses the temperature-controlled maritime transport of perishable cargo using engineered intermodal boxes equipped with integrated refrigeration units, typically maintaining set points between minus 30 degrees Celsius and plus 30 degrees Celsius through compressor-driven active cooling or cryogenic systems. These units serve pharmaceutical distributors, fresh produce exporters, and protein processors requiring uninterrupted cold chains from origin packhouses to destination distribution centers. Reefer containers capture the dominant volume position across European port throughput, while dual-temperature systems represent the fastest-growing configuration as shippers consolidate mixed-cargo loads to optimize slot utilization and reduce per-unit freight costs. Active cooling technologies command premium positioning in pharmaceutical lanes where Good Distribution Practice compliance necessitates continuous data logging and alarm redundancy.
The European Maritime Safety Agency enforces vessel energy efficiency standards that accelerate fleet renewal toward electrically-powered reefer plugs and battery-hybrid auxiliary systems. REACH and the EU F-Gas Regulation jointly constrain refrigerant selection, compelling carriers to retrofit existing containers with lower-global-warming-potential alternatives or retire aging assets ahead of schedule. Stakeholders must monitor the interplay between port electrification timelines and container power specifications as shore-side infrastructure investments reshape compatibility requirements across Northern and Mediterranean hub terminals.
Market Dynamics
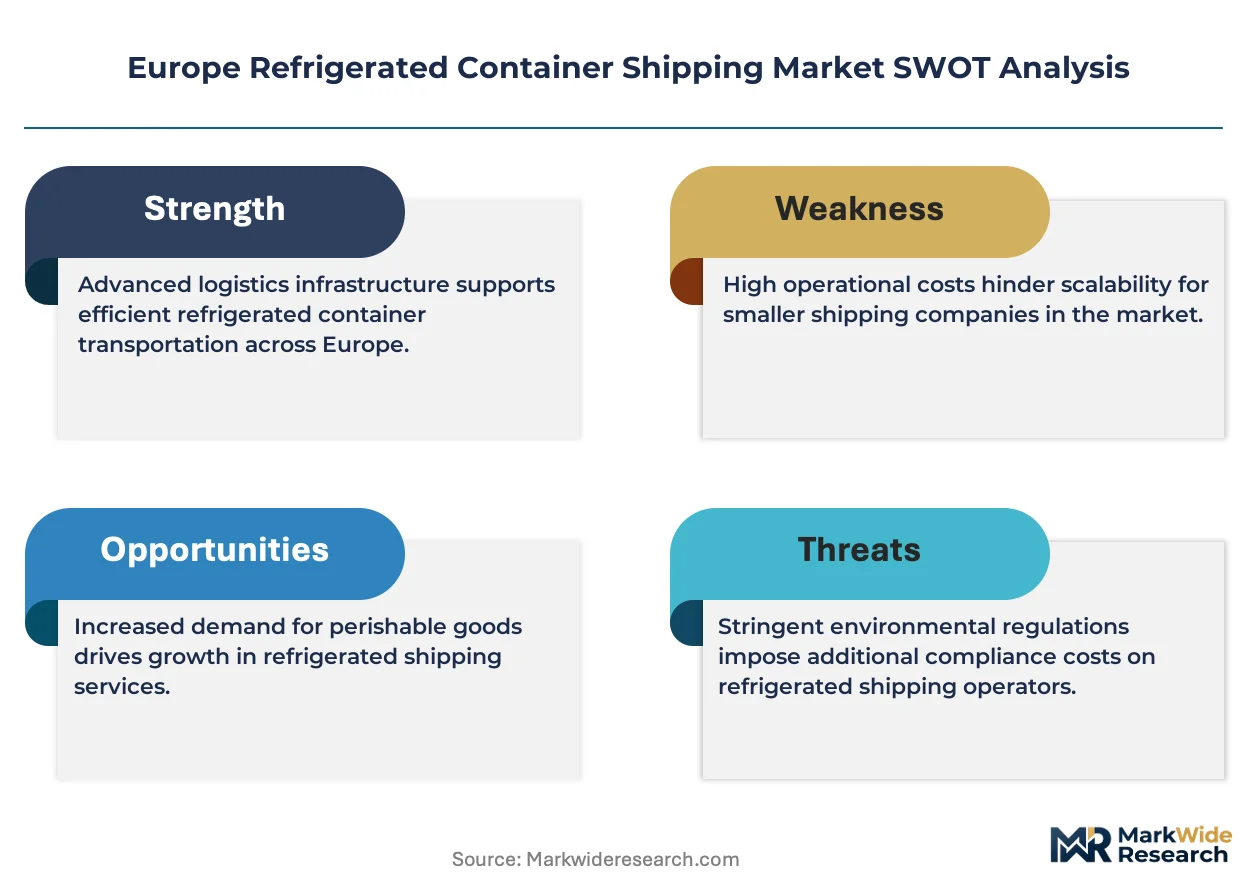
EU F-Gas Regulation mandates are forcing container fleet operators to accelerate refrigerant retrofits or retire hydrofluorocarbon-dependent assets ahead of economic end-of-life schedules.
Growth Catalysts
- Pharmaceutical cold chain expansion:Northern European trade corridors are absorbing temperature-controlled capacity as biologics distributors route more insulin, vaccines, and cell therapies through Hamburg and Rotterdam hubs.
- REACH compliance upgrades:Chemical safety registrations for refrigerant alternatives are clearing regulatory pathways for lower-global-warming-potential cooling systems across EU member state fleets.
- Shore power infrastructure:Battery-hybrid auxiliary systems at Antwerp, Valencia, and Algeciras terminals are reducing diesel generator runtime and enabling overnight grid-connected cold storage.
Market Restraints
- Refrigerant supply concentration:Production of R-452A and R-513A alternatives concentrates among three chemical suppliers, creating input cost volatility during phasedown transition windows.
- CE marking friction:Marine Equipment Directive conformity assessments for integrated reefer units are extending lead times by four to six months for non-EU manufacturers.
- Container manufacturing bottlenecks:Corten steel and aluminum alloy availability constraints at Chinese and South Korean fabrication yards are compressing new-build delivery schedules.
Strategic Opportunities
- Rail-pharma corridors:Spain-to-Germany intermodal routes are opening for temperature-validated container movements as Iberian track electrification completes.
- CE marking advisory services:Technical documentation preparation and Notified Body liaison represent adjacent revenue streams for logistics providers with regulatory expertise.
- Dual-temperature configurations:Mixed-cargo consolidation demand from protein processors and fresh produce exporters is driving specification for partitioned cooling zones within single units.
Industry Challenges
- Refrigeration technician scarcity:Containerized cooling system diagnostics and compressor overhaul skills are concentrating among aging workforces in Baltic and North Sea port clusters.
- Legacy telemetry integration:Remote monitoring platform upgrades are requiring middleware development to bridge 1990s-era data loggers with cloud-based fleet management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Refrigerated Container Shipping Market |
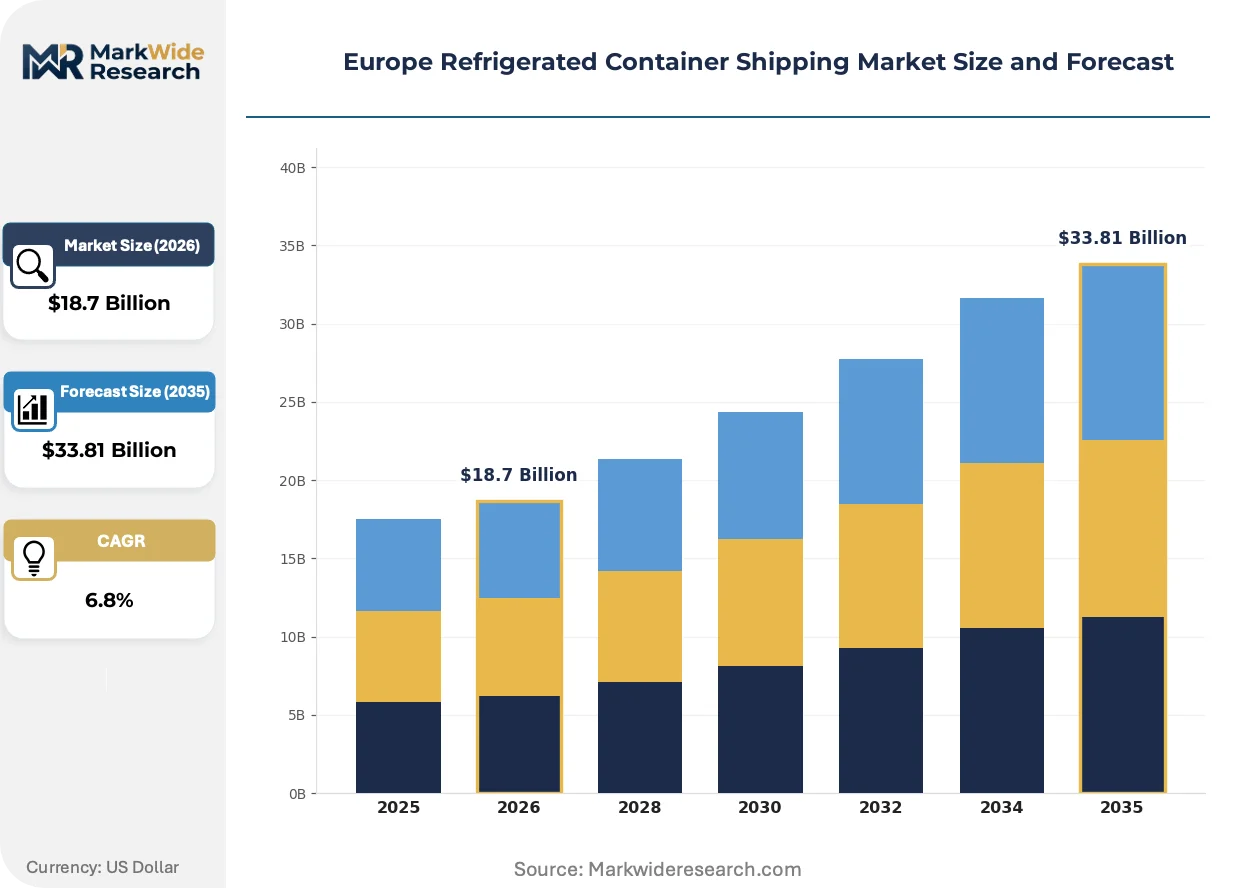
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Reefer Containers, Insulated Containers, Dry Containers, Ventilated Containers Temperature Control: Active Cooling, Passive Cooling, Insulated Padding, Dual-Temperature Systems End User: Food & Beverage, Pharmaceuticals, Chemicals, Vegetables Service Type: Full Service, Port-to-Port, Door-to-Door, Container Leasing |
| Companies Covered | Hapag-Lloyd, Ocean Network Express (ONE), Mediterranean Shipping Company (MSC), Almar Container Group, Seaco, A.P. Moller - Maersk, COSCO Shipping Lines, SeaCube Container Leasing, CMA CGM Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Refrigerated Container Shipping Market Trends and Innovations
Electrification and digital traceability are restructuring how European reefer operators manage power consumption, cargo condition verification, and intermodal handoff protocols across extended supply chains.
Cryogenic cooling systems using liquid nitrogen injection are decomposing the dominant position of compressor-driven mechanical refrigeration in pharmaceutical lanes. Biologics shippers operating Rotterdam-to-Milan rail corridors are piloting these units for their elimination of moving parts and vibration. The technology is decomposing maintenance cost structures and enabling extended inland transits without shore power dependency.
EU F-Gas Regulation phasedown schedules are compelling carriers to retire hydrofluorocarbon refrigerants by 2030. Fleet operators face binary choices between retrofitting existing boxes with hydrofluoroolefin blends or accelerating capital replacement cycles. Pharmaceutical-grade container configurations face the steepest compliance burden due to Good Distribution Practice validation requirements for temperature excursion documentation.
Consolidated procurement of reefer slots by large protein processors is compressing spot market availability and forcing smaller fresh produce exporters toward forward contract structures. German retail grocery chains are extending tender durations from annual to multi-year frameworks to secure dedicated capacity. The shift is most visible in Hamburg hinterland distribution, where controlled atmosphere container specifications are becoming standard procurement terms.
Europe Refrigerated Container Shipping Market Segmentation
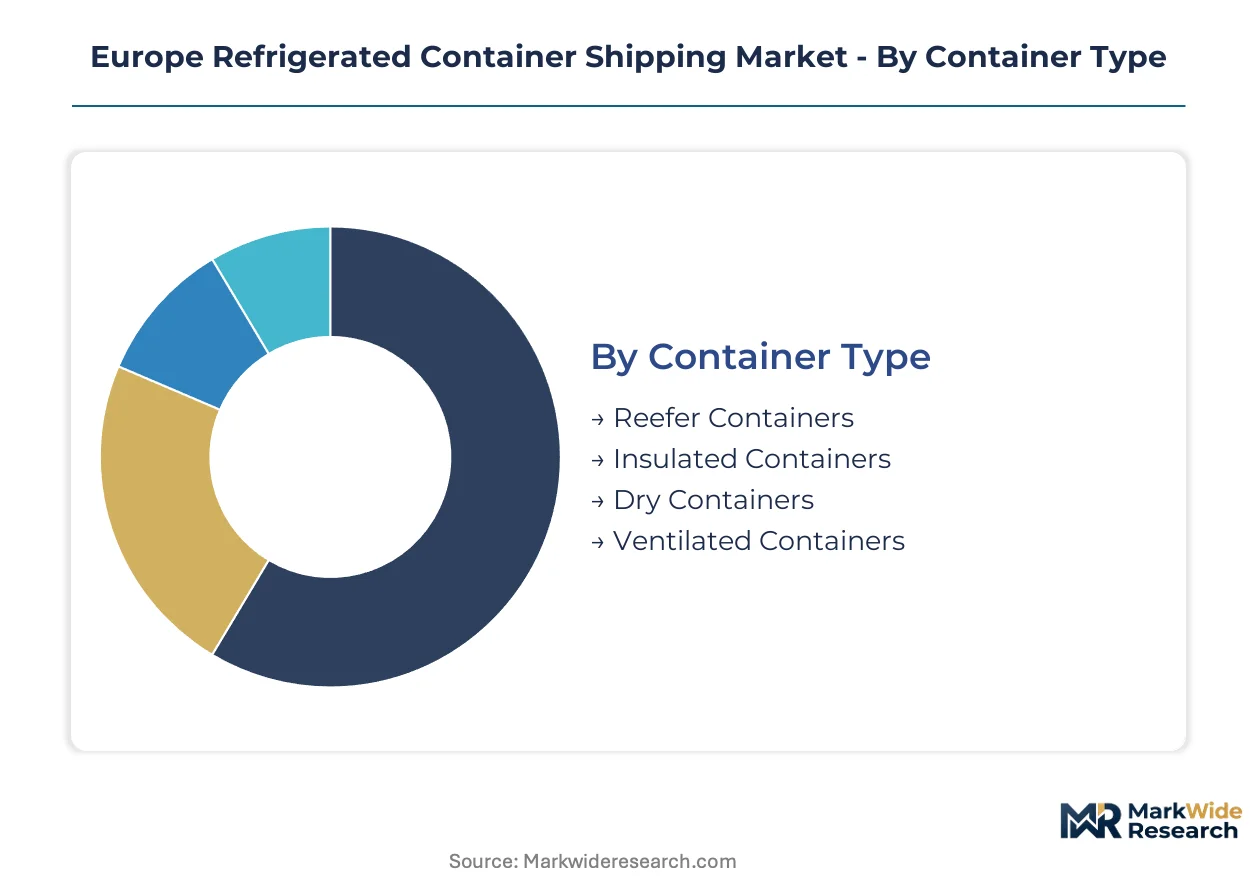
Segmentation in European refrigerated container shipping reveals how cargo characteristics dictate equipment specifications, regulatory compliance burdens, and service model selection across the cold chain value chain. Understanding these divisions exposes where substitution pressures from alternative transport modes or container technologies concentrate competitive risk.
Container Type:
Reefer containers face intensifying substitution pressure from cryogenic and battery-hybrid alternatives as EU F-Gas Regulation deadlines approach fleet renewal decisions.
- Reefer Containers:Engineered intermodal boxes with integrated compressor-driven refrigeration units maintaining set points between minus 30 and plus 30 degrees Celsius. German protein processors and Dutch flower exporters at Rotterdam and Hamburg absorb the dominant volume share as they require continuous active cooling across extended Atlantic and Baltic transit corridors.
- Insulated Containers:Passive thermal protection systems relying on pre-cooled cargo and insulating materials without mechanical refrigeration. Scandinavian fresh produce exporters moving seasonal berries through Gothenburg favor these units for short-sea North Sea routes where transit times stay under 48 hours and capital costs must compress.
- Dry Containers:Standard unmodified intermodal boxes handling non-temperature-sensitive cargo that occasionally substitutes for insulated units when seasonal demand spikes exhaust specialized fleet availability.
- Ventilated Containers:Passive airflow designs with adjustable vents for respiring agricultural products like bananas or avocados requiring humidity management rather than mechanical cooling.
Reefer containers retain volume leadership across European port throughput; dual-temperature configurations hold the steepest expansion curve as shippers consolidate mixed-cargo loads.
Temperature Control:
Cost tier stratification separates premium pharmaceutical-grade systems from commodity fresh produce cooling as compliance burdens diverge.
- Active Cooling:Compressor-driven mechanical refrigeration with continuous power supply through vessel plugs, diesel generators, or shore connections. Belgian biologics distributors at Antwerp mandate these systems for insulin and vaccine movements requiring uninterrupted temperature integrity and EMA-aligned Good Distribution Practice documentation.
- Passive Cooling:Thermal mass and insulating materials without mechanical components, suitable for frozen cargo with extended temperature hold times. Spanish citrus exporters through Valencia deploy these for cost-sensitive mandarin shipments to northern European distribution centers.
- Insulated Padding:Supplementary thermal blankets and liners added to standard containers for marginal temperature protection during transitional seasons.
- Dual-Temperature Systems:Partitioned cooling zones enabling simultaneous transport of frozen and chilled cargo within single units. German retail grocery chains specify these configurations for consolidated procurement of mixed protein and dairy loads through Hamburg hinterland distribution.
Active cooling commands premium positioning in pharmaceutical lanes; dual-temperature systems are gaining share fastest as consolidation demand intensifies.
End User:
Application-specific requirements drive divergence in container specifications, with pharmaceutical and food safety regulations imposing incompatible compliance frameworks.
- Food & Beverage:Protein processors, dairy distributors, and beverage exporters requiring HACCP-aligned temperature monitoring. French cheese exporters through Le Havre and Belgian chocolate manufacturers at Antwerp represent concentrated demand clusters with strict cold chain validation requirements.
- Pharmaceuticals:Biologics, vaccines, and cell therapies demanding continuous data logging, alarm redundancy, and EMA-validated temperature excursion protocols. Danish insulin manufacturers and German vaccine distributors route through Rotterdam and Hamburg under the steepest regulatory compliance burdens.
- Chemicals:Temperature-sensitive industrial compounds and specialty reagents requiring hazardous materials compatibility alongside thermal control.
- Vegetables:Fresh produce exporters with seasonal demand spikes and price-sensitive logistics budgets, concentrated in Spanish and Italian Mediterranean growing regions.
Food and beverage retains volume leadership; pharmaceuticals holds the steepest expansion curve as biologics cold chain requirements intensify.
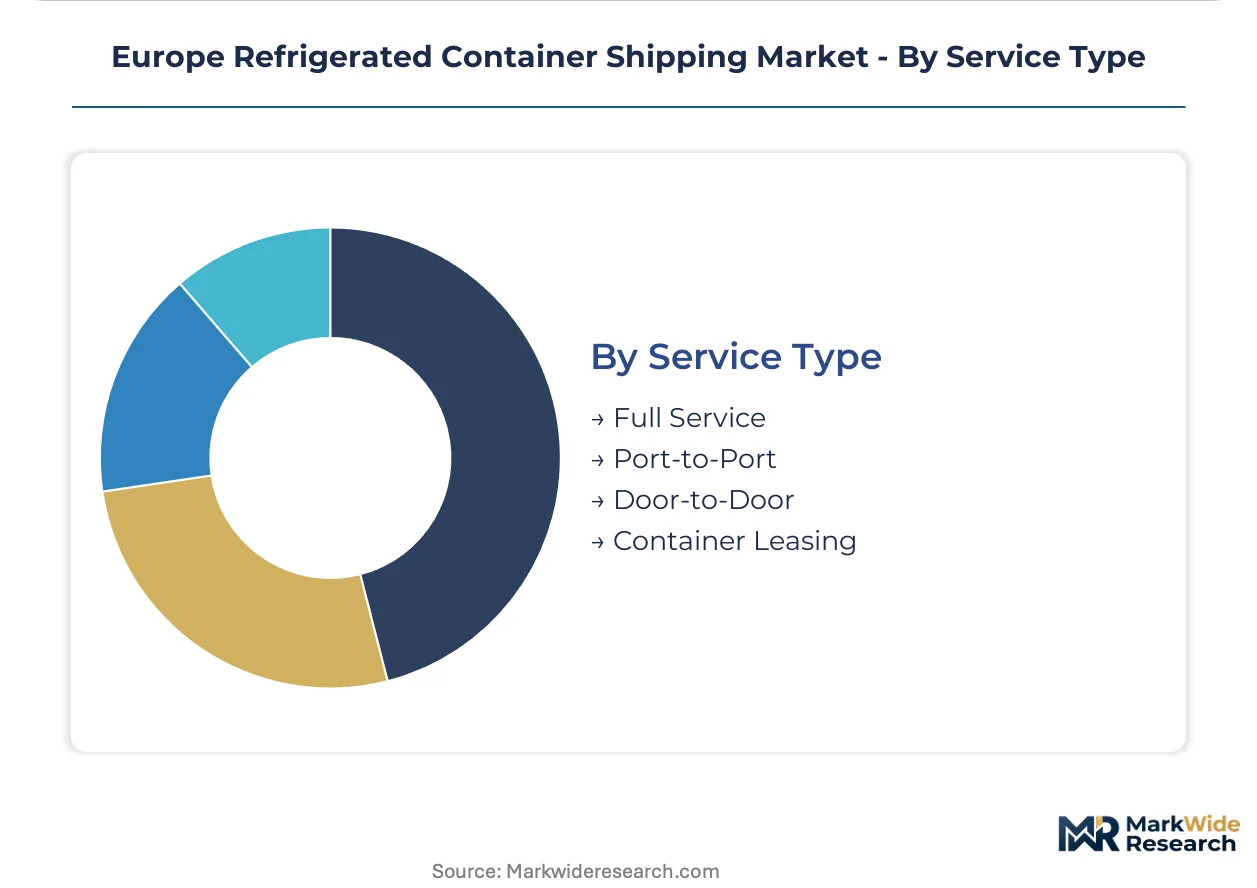
Service Type:
Customer type segmentation separates asset-heavy integrated carriers from flexible logistics providers as shippers balance control against capital efficiency.
- Full Service:End-to-end temperature-controlled logistics including pre-cooling, container provisioning, ocean freight, customs clearance, and last-mile delivery. Large German retail grocery chains contract these services for multi-year dedicated capacity commitments through Hamburg hub distribution.
- Port-to-Port:Maritime transport only with shipper responsibility for inland legs and intermodal handoffs. Smaller fresh produce exporters in Spain and Italy favor this model to retain control over domestic trucking relationships.
- Door-to-Door:Integrated origin-to-destination service with single accountability for temperature integrity, preferred by pharmaceutical distributors requiring audit trail continuity.
- Container Leasing:Asset-light access to refrigerated equipment without ownership burdens, enabling seasonal flexibility for agricultural exporters with volatile demand patterns.
Full service retains volume leadership; container leasing holds the steepest expansion curve as seasonal agricultural exporters prioritize capital flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large German retail grocery chains and Belgian biologics distributors concentrate procurement power across Northern European trade corridors. Pharmaceutical cold chain requirements from Danish insulin manufacturers and Dutch vaccine distributors are reshaping port infrastructure priorities. Container specifications diverge sharply between Mediterranean fresh produce exporters and North Sea protein processors.
Germany
The Port of Hamburg anchors continental reefer cargo distribution for protein processors and retail grocery chains. EU F-Gas Regulation compliance deadlines are accelerating fleet retrofits among Hamburg-based logistics providers. Bavarian dairy exporters and Baden-Württemberg pharmaceutical manufacturers are demanding dual-temperature container configurations for consolidated rail shipments.
Netherlands
Rotterdam's terminal operators are expanding shore power infrastructure to service battery-hybrid auxiliary systems for biologics distributors. REACH chemical safety registrations for hydrofluoroolefin refrigerants are clearing regulatory pathways at ECHA. Dutch flower exporters through Aalsmeer and pharmaceutical distributors at Schiphol logistics zones are driving specification for continuous data logging systems.
Belgium
Antwerp's integrated terminal network is absorbing expanded insulin and vaccine movements from Danish manufacturers. CE marking assessments under the Marine Equipment Directive are extending lead times for non-EU container manufacturers. Flemish chocolate manufacturers and Walloon biotech distributors are consolidating procurement through multi-year dedicated capacity contracts.
Spain
Valencia and Algeciras terminals are reducing diesel generator runtime through overnight grid-connected cold storage investments. Iberian track electrification is opening Spain-to-Germany intermodal routes for temperature-validated container movements. Andalusian citrus exporters and Catalan fresh produce distributors are piloting cryogenic cooling systems for extended inland transits.
France
Le Havre is capturing cheese export volumes from Normandy dairy processors requiring HACCP-aligned temperature monitoring. The EU Green Deal maritime decarbonization targets are pressuring fleet operators at Marseille-Fos to accelerate shore power adoption. Paris-region pharmaceutical distributors are specifying pharmaceutical-grade container fleets with EMA-validated temperature excursion protocols.
Europe Refrigerated Container Shipping Market Competitive Landscape
Player mix skews toward integrated ocean carriers with controlled terminal assets and specialized container lessors with seasonal flexibility offerings. Market structure concentrates around three strategic tiers: asset-heavy liner operators owning shore power infrastructure, mid-scale regional carriers with Mediterranean specialization, and equipment lessors serving volatile agricultural export demand. Competitive moves center on refrigerant retrofit partnerships with chemical suppliers and multi-year dedicated capacity contracts with protein processors.
Among integrated liner operators, Mediterranean Shipping Company, A.P. Moller - Maersk, and CMA CGM Group exemplify the asset-heavy archetype through controlled terminal networks and pharmaceutical-grade fleet specialization. These carriers occupy positions where shore power investments and remote monitoring platforms anchor customer retention. Container lessors including Seaco and SeaCube Container Leasing represent the capital-flexibility tier, serving seasonal exporters with asset-light access to refrigerated equipment. Hapag-Lloyd and Ocean Network Express sit within the mid-scale carrier segment, competing on Trans-Atlantic route density and Northern European port coverage. COSCO Shipping Lines anchors the Asia-Europe trade lane vector, while Almar Container Group exemplifies regional specialization in African and Mediterranean corridors.
| Leading Market Players |
|---|
| Hapag-Lloyd |
| Ocean Network Express (ONE) |
| Mediterranean Shipping Company (MSC) |
| Almar Container Group |
| Seaco |
| A.P. Moller - Maersk |
| COSCO Shipping Lines |
| SeaCube Container Leasing |
| CMA CGM Group |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation phasedown schedules gate both supplier qualification and price differentiation simultaneously, as CE marking under the Marine Equipment Directive extends lead times for non-EU manufacturers while pharmaceutical-grade container configurations command sustained premiums. German retail grocery chains and Belgian biologics distributors concentrate procurement power through multi-year dedicated capacity contracts that compress spot market availability for smaller Spanish fresh produce exporters.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate German protein processor agreements, insulating carriers from Corten steel volatility at Chinese fabrication yards. Three-tier pricing structure across pharmaceutical-grade, food-grade, and ventilated container tiers separates EMA-validated biologics units from commodity citrus shipments. Cost compression in standard reefer configurations is intensifying because REACH compliance upgrades for hydrofluoroolefin refrigerants concentrate production among three chemical suppliers. Spanish citrus exporters exhibit the highest price sensitivity due to seasonal demand spikes and thin margins, while Danish insulin manufacturers accept premium positioning for uninterrupted cold chain validation.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam elevates inbound logistics costs for Northern European trade corridors, while container availability constraints at Chinese and South Korean fabrication yards compress new-build delivery schedules. Manufacturing concentration in China, South Korea, and Germany feeds European fleet renewal demands, with Corten steel, aluminum alloys, and compressor units anchoring bill-of-material structures. Single-source vulnerability concentrates in hydrofluoroolefin refrigerant production as EU F-Gas Regulation deadlines approach. Distribution runs through integrated terminal networks at Antwerp and Valencia, with shore power infrastructure investments reshaping last-mile compatibility requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are opening as pharmaceutical cold chain requirements diverge from commodity fresh produce logistics, creating specialized niches for temperature-validated intermodal operators and regulatory advisory services.
For Market Incumbents: Fortify market position through backward integration into shore power infrastructure at Hamburg and Rotterdam terminals, while accelerating refrigerant retrofit partnerships with chemical suppliers ahead of 2030 compliance deadlines. CE marking friction for non-EU competitors creates a defensive moat for European-certified fleet operators. For New Entrants and Emerging Players: Lead with cryogenic cooling system deployments on Spain-to-Germany rail corridors, where Iberian track electrification completes temperature-validated intermodal routes underserved by incumbent compressor-driven fleets. Technical documentation preparation and Notified Body liaison services represent adjacent revenue streams requiring lower capital intensity than asset-heavy container ownership. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade container configurations as Good Distribution Practice validation requirements steepen compliance burdens. Target equipment lessors with seasonal flexibility offerings and established relationships with volatile agricultural exporters. The signal to watch is shore power infrastructure deployment timelines at Mediterranean hub terminals, which will determine compatibility requirements and fleet obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Retrofit Partnership | Secures supply chain positioning for EU F-Gas Regulation compliance at ECHA-registered chemical suppliers. |
| Shore Power Infrastructure Investment | Enables overnight grid-connected cold storage at Antwerp and Valencia terminals under EU Green Deal targets. |
| Rail-Pharma Corridor Development | Captures temperature-validated container movements on electrified Spain-to-Germany intermodal routes. |
| CE Marking Advisory Service Launch | Monetizes regulatory expertise through Notified Body liaison for non-EU container manufacturers. |
| Dual-Temperature Fleet Expansion | Addresses German retail grocery chain demand for consolidated protein and dairy load configurations. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations managers at integrated liner carriers, terminal infrastructure planners at Northern European hub ports, pharmaceutical logistics directors at Danish biologics distributors, and procurement leads at German retail grocery chains, and refined through secondary validation against EU F-Gas Regulation implementation timelines, ECHA REACH registration databases, port authority electrification disclosures, and customs trade flow records. Bottom-up container throughput modeling and top-down cold chain value chain analysis were triangulated to constrain variance.
Variance decomposition across container type, temperature control tier, end-use application, and service model dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand elasticity modeling and fleet replacement cycle analysis, with pharmaceutical cold chain expansion rates and shore power infrastructure deployment schedules serving as key forecast inputs.
Forecasts assume regulatory continuity in EU F-Gas Regulation phasedown schedules and Marine Equipment Directive conformity assessment procedures; material policy shifts or CE marking timeline extensions would require re-modeling. Recalibration cycles align with material shifts in refrigerant supply concentration, port electrification completion timelines, and cryogenic cooling system adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Australia Freight and Logistics Market